
 Europe Vaccines Market | 2026-2036
Europe Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vaccines Market Analysis
Software-defined cold-chain monitoring is consolidating as a recurring revenue layer atop physical vaccine distribution. GSK leverages its pan-European logistics network to bundle temperature-integrity subscriptions with bulk supply contracts. Sanofi Pasteur anchors its competitive stance through R&D intensity in mRNA platform adaptations for endemic diseases. Bavarian Nordic differentiates via specialized manufacturing for smallpox and mpox countermeasures.
Vaccines comprise biological preparations containing attenuated or inactivated pathogens, purified antigenic subunits, or lipid-nanoparticle-encapsulated mRNA sequences that stimulate adaptive immune responses without causing disease. European manufacturing adheres to stringent potency specifications, typically requiring antigen content within plus-or-minus twofold of labeled dose per batch release criteria. The mRNA segment is attracting the fastest capacity investment as platform flexibility shortens development timelines for variant-adapted formulations. Injectable delivery dominates volume, though intranasal routes are gaining structural attention for mucosal immunity advantages in respiratory pathogens. Pediatric applications command the largest revenue pool due to mandated national schedule compliance, while traveler vaccines present higher per-dose margins through private-channel distribution.
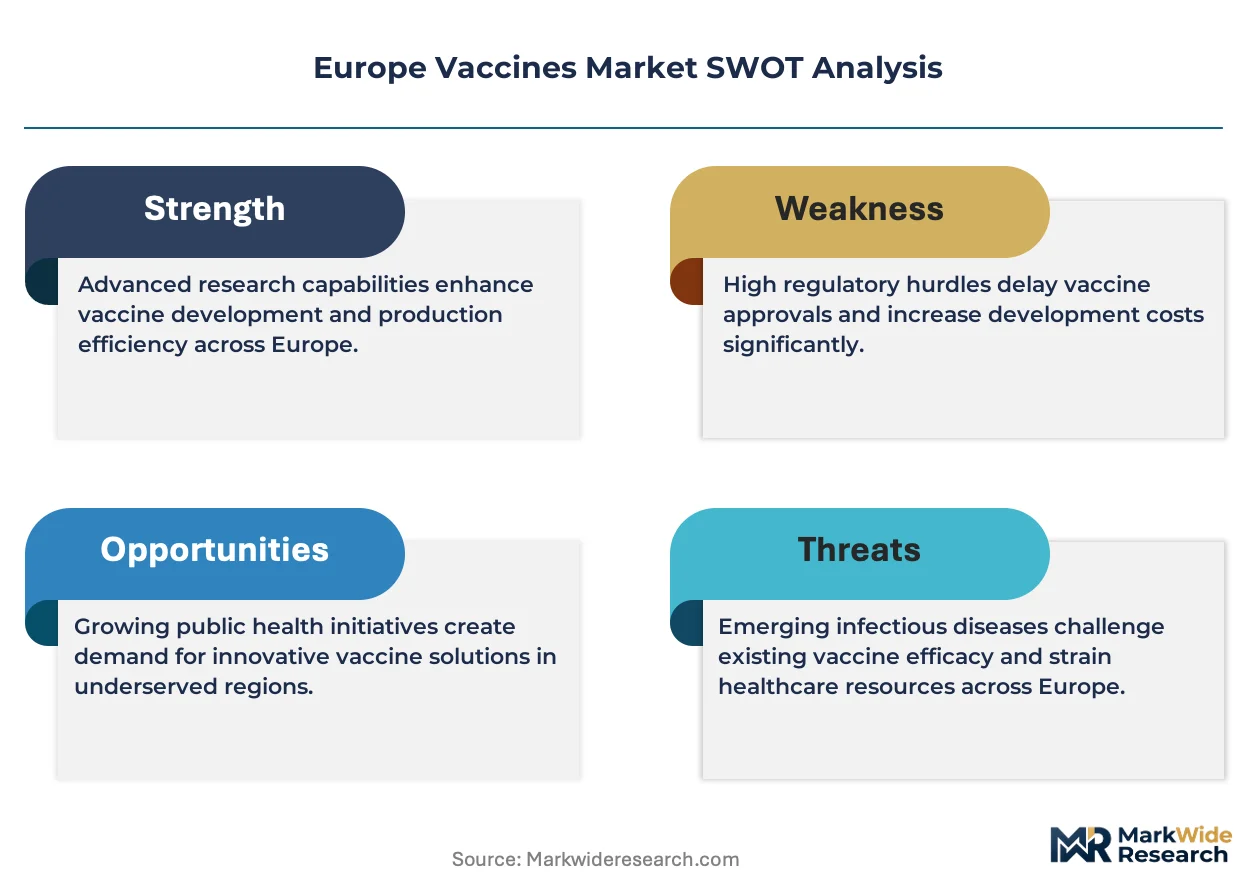
EMA centralized marketing authorization procedures govern pan-European access, while national regulators such as France's ANSM and Germany's Paul-Ehrlich-Institut execute batch release and pharmacovigilance oversight. MDR requirements for device-delivery combinations and REACH compliance for excipient chemicals add layered compliance costs that favor scaled manufacturers. The EU Green Deal's pharmaceutical sector emissions targets are pressuring suppliers to decarbonize fill-finish operations. Stakeholders must monitor how the EU AI Act's risk-classification rules affect automated quality-control systems in GMP environments.
Market Dynamics
EU Green Deal emissions targets and MDR compliance requirements are forcing vaccine manufacturers to reconfigure fill-finish operations while absorbing layered certification costs that favor scaled producers over mid-tier entrants.
Growth Catalysts
- MDR device-delivery frameworks:Combination product approvals for auto-injectors and needle-free systems are expanding addressable revenue per dose across EU member states.
- France, Germany, Italy procurement centralization:National immunization program tenders are consolidating volume commitments that secure multi-year manufacturing slots for qualified suppliers.
- mRNA platform flexibility:Rapid reformulation capabilities for variant-adapted vaccines are compressing development timelines against traditional egg-based production.
Market Restraints
- Excipient chemical compliance:REACH registration costs for novel lipid nanoparticle components are inflating raw material qualification budgets by six-figure sums per substance.
- Batch release concentration:Paul-Ehrlich-Institut and ANSM pharmacovigilance backlogs are extending time-to-market for new submissions beyond historical baselines.
- Cold-chain infrastructure gaps:Eastern EU member states lack ultra-low temperature storage density, limiting mRNA vaccine distribution reach.
Strategic Opportunities
- Poland and Romania pediatric expansion:Underpenetrated national immunization schedules present volume upside as EU structural funds modernize healthcare infrastructure.
- Intranasal delivery convergence:Mucosal immunity advantages for respiratory pathogens are attracting R&D investment alongside injectable platform extensions.
- Software-defined cold-chain subscriptions:Real-time temperature monitoring services are creating recurring revenue layers atop physical distribution contracts.
Industry Challenges
- Bioprocess engineering talent scarcity:EU vaccine manufacturing lacks sufficient GMP-qualified cell culture specialists and lipid nanoparticle formulation scientists.
- EU AI Act risk classification:Automated visual inspection systems for batch release face uncertain compliance timelines as regulators interpret high-risk AI thresholds for pharmaceutical quality control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vaccines Market |
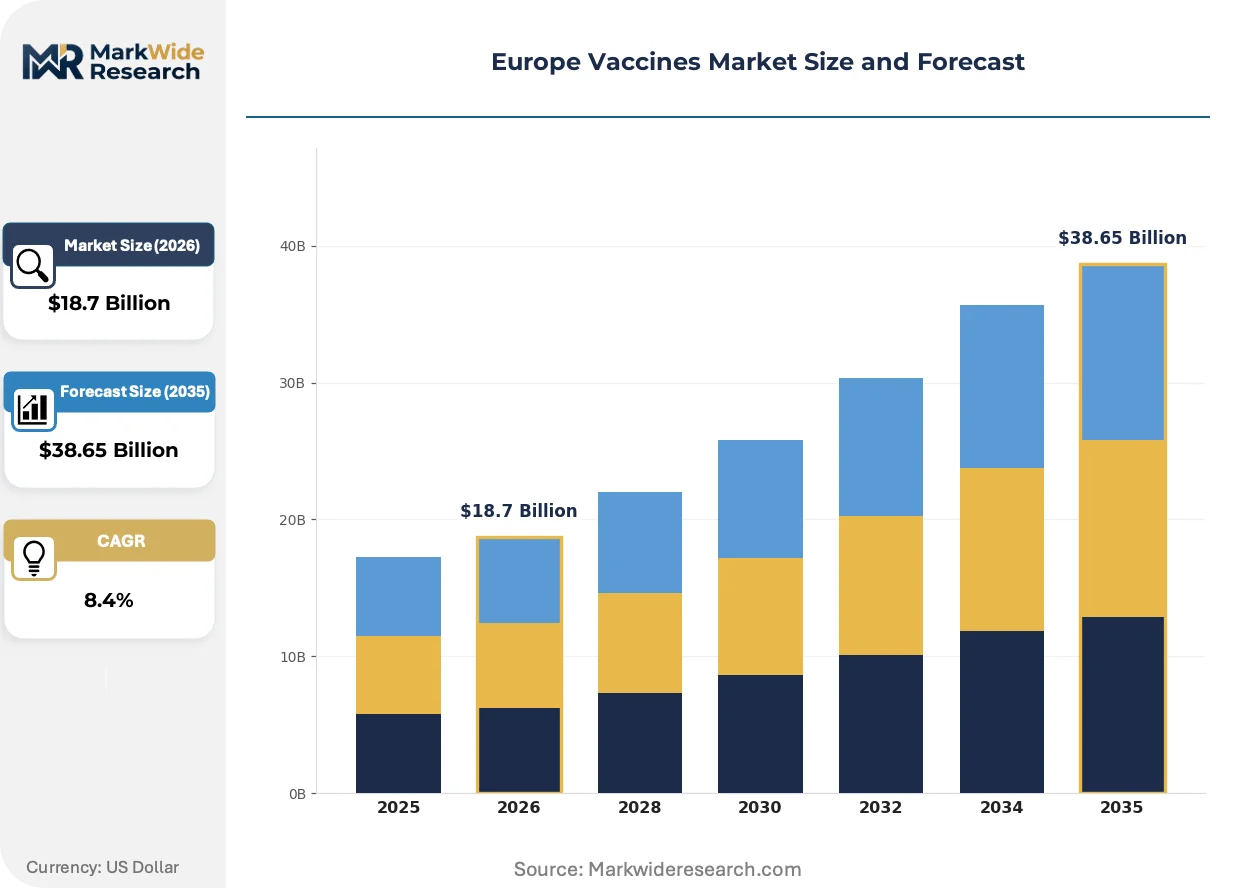
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, mRNA Delivery Mode: Injectable, Oral, Intranasal, Transdermal End User: Hospitals, Clinics, Pharmacies, Research Institutes Application: Pediatrics, Adults, Geriatrics, Travelers |
| Companies Covered | AstraZeneca, Bavarian Nordic, GSK, IDT Biologika, Valneva, Sanofi Pasteur, Novartis, Emergent BioSolutions, Roche, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vaccines Market Emerging Trajectories
Platform manufacturing flexibility and regulatory digitization are compressing traditional vaccine development paradigms while reshaping competitive advantage toward speed-to-variant rather than scale-alone.
Distributed fill-finish networks are decentralizing production geography across the continent. Mid-scale modular facilities in Portugal and the Netherlands are capturing regional supply contracts previously held by centralized Belgian and German sites. This architecture reduces transport-related temperature excursion risk while enabling faster national stockpile replenishment during outbreak response.
EMA's accelerated assessment pathways for public health threats are shortening marketing authorization timelines for variant-adapted mRNA formulations. The regulatory mechanism compresses traditional phased review without sacrificing batch release standards enforced by national competent authorities. Pediatric indication extensions and traveler vaccine categories are deploying these pathways most aggressively.
Hospital pharmacy procurement groups are consolidating vaccine purchasing across regional health systems in Spain and Italy. This buyer concentration is displacing fragmented municipal tender processes with multi-year framework agreements that bundle combination pediatric products across entire catchment populations. Southern European markets exhibit this pattern most visibly as austerity-era budget consolidation persists.
Europe Vaccines Market Segmentation
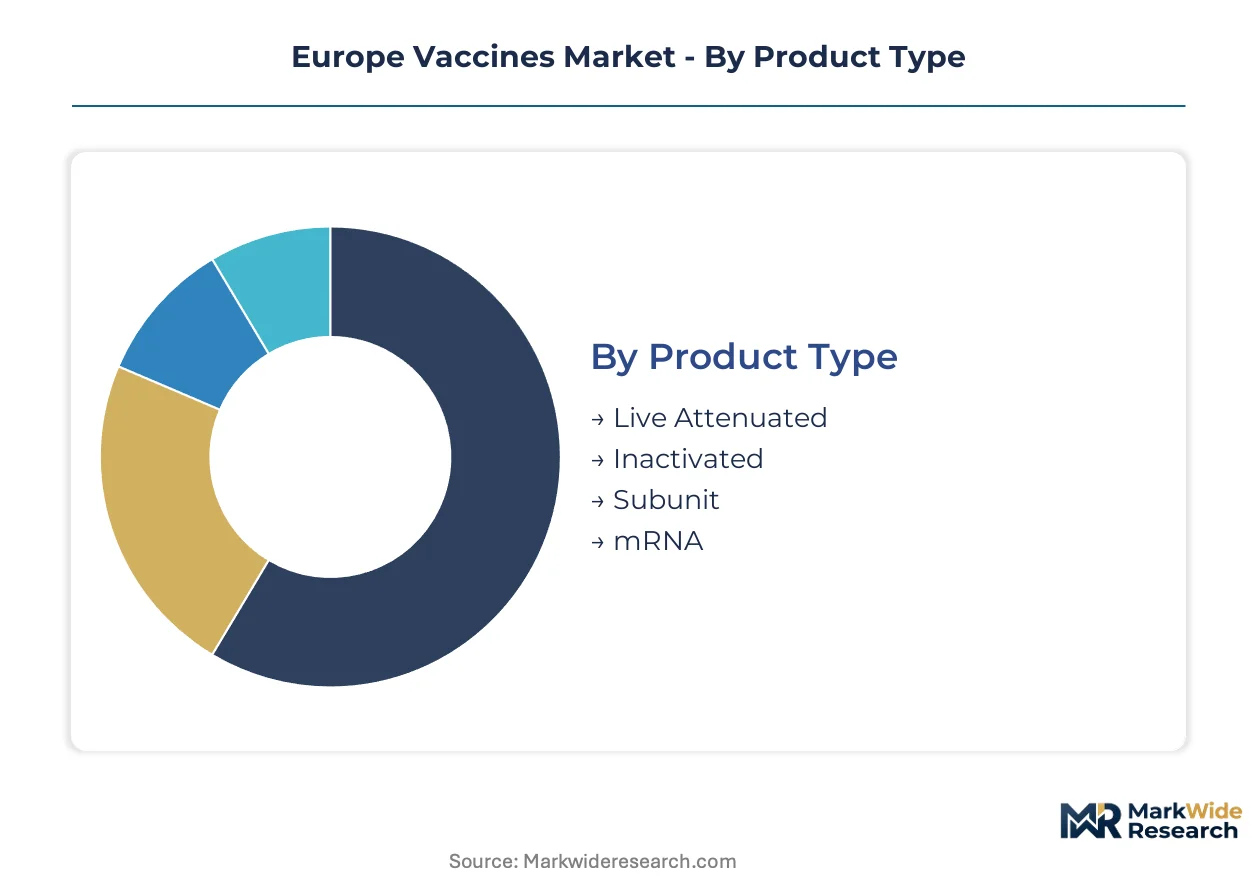
Vaccine segmentation in Europe reflects divergent commercial logics across technology platforms, delivery formats, and procurement channels. Pediatric mandates drive volume concentration while traveler applications sustain premium pricing tiers. Understanding these fault lines clarifies where manufacturers defend margin versus pursue scale.
Product Type:
Volume leadership sits with established platforms, while mRNA commands the steepest capacity investment curves as manufacturers bet on reformulation speed.
- mRNA:Lipid-nanoparticle-encapsulated nucleic acid sequences enable rapid variant-adapted formulation without cell culture infrastructure. German and Belgian manufacturing clusters attract the densest EMA batch release activity for these products, though REACH registration costs for novel ionizable lipids inflate raw material budgets.
- Subunit:Purified antigenic proteins or polysaccharides processed through recombinant DNA technology or chemical extraction. French and Italian national immunization schedules source combination pediatric products heavily from this category, where long-established supply contracts favor incumbents with Paul-Ehrlich-Institut release history.
- Live Attenuated:Weakened pathogen strains that replicate minimally in vivo to stimulate durable cellular immunity. MMR and varicella formulations dominate procurement tenders.
- Inactivated:Whole pathogens destroyed by heat or chemicals, retaining immunogenicity without replication risk. Seasonal influenza and polio coverage relies on this platform.
Today's leader: Subunit. Tomorrow's challenger: mRNA.
Delivery Mode:
Route selection determines cold-chain complexity, dosing compliance, and the regulatory pathway through MDR device-delivery combination frameworks.
- Injectable:Intramuscular and subcutaneous administration via syringe or auto-injector. This route captures overwhelming volume across EU member states, with centralized tenders in Germany and France specifying needle-free systems for school-based immunization programs.
- Intranasal:Mucosal deposition for respiratory pathogen immunity without systemic circulation. EMA accelerated assessment pathways are processing more submissions from this category as manufacturers target IgA-mediated protection.
- Oral:Enteric-coated formulations or live attenuated strains surviving gastric passage. Rotavirus and typhoid coverage deploys this route in pediatric schedules.
- Transdermal:Microneedle arrays or patches disrupting stratum corneum for antigen delivery. Pilot procurement in Dutch hospital pharmacy networks tests compliance advantages.
Injectable platforms anchor current procurement. Intranasal formats are climbing the fastest as respiratory-focused R&D reallocates.
End User:
Channel structure determines pricing transparency, with direct hospital procurement favoring volume discounts and pharmacy networks preserving premium margins.
- Hospitals:Regional health system pharmacy groups in Spain and Italy consolidate purchasing across catchment populations, displacing fragmented municipal tenders with multi-year framework agreements.
- Pharmacies:Private-channel distribution for traveler vaccines and adult boosters sustains higher per-dose margins through retail markup structures.
- Clinics:Outpatient settings handling routine immunization and specialty travel medicine consultations.
- Research Institutes:Clinical trial sites and public health laboratories managing investigational product distribution.
Hospital consolidation is accelerating. Pharmacy channels retain pricing power.
Application:
Age-based and behavioral risk categories split between mandated national schedule compliance and discretionary private purchase.
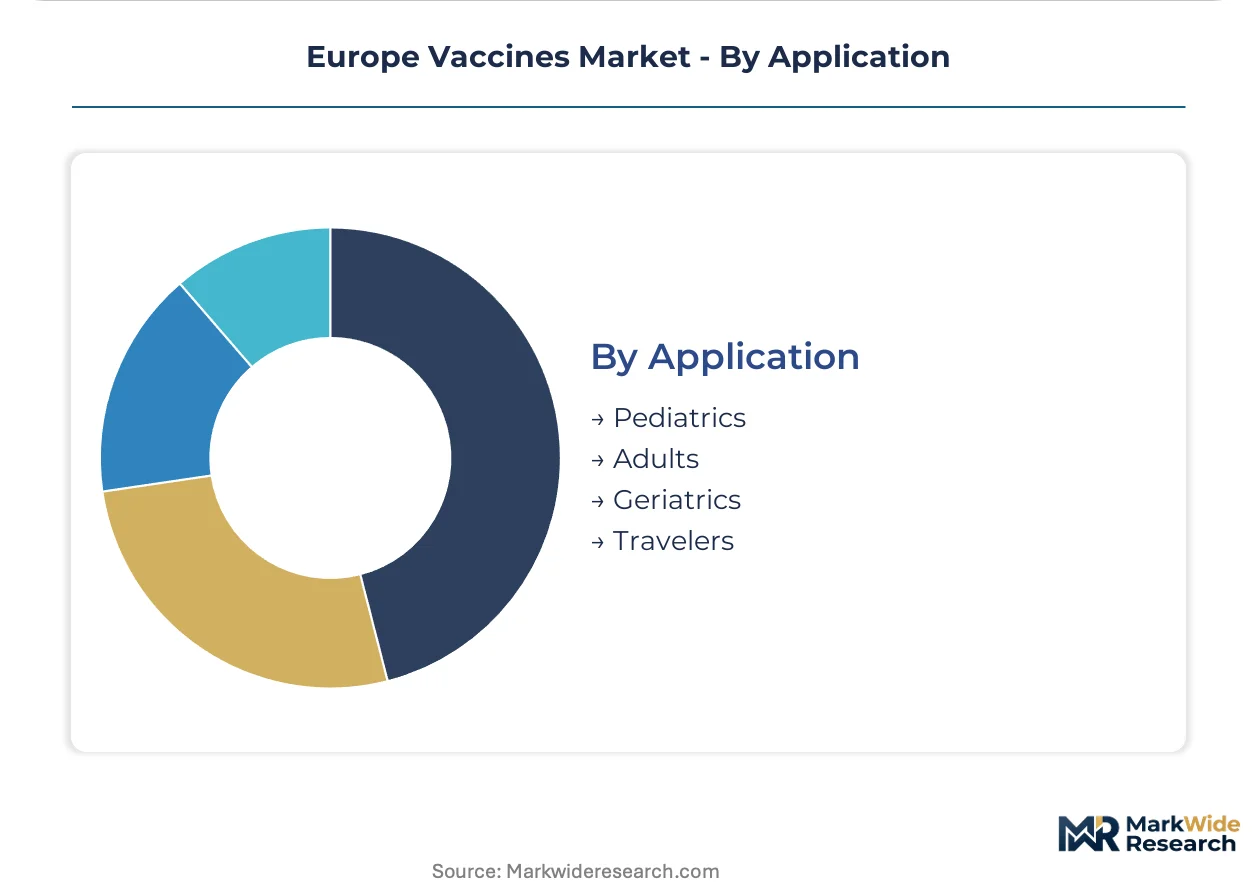
- Pediatrics:Mandated national immunization schedules across EU member states generate predictable volume through centralized procurement. Combination products covering diphtheria-tetanus-pertussis-polio-Hib dominate tenders.
- Travelers:Yellow fever, typhoid, and Japanese encephalitis vaccines distributed through private channels command substantial per-dose premiums versus schedule products.
- Adults:Booster programs and occupational health mandates sustain recurring demand outside pediatric frameworks.
- Geriatrics:Pneumococcal and shingles immunization targeting cellular senescence in immune response.
Pediatrics locks in manufacturing slots. Travelers unlock margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France diverge in procurement centralization intensity, with Berlin consolidating pediatric tenders through the Paul-Ehrlich-Institut while Paris maintains fragmented regional purchasing. This structural gap shapes where manufacturers anchor fill-finish capacity versus distribution partnerships.
Germany
Centralized procurement through the Paul-Ehrlich-Institut secures multi-year manufacturing slots for combination pediatric vaccines. The EU Green Deal emissions targets pressure fill-finish operations in Hesse and Bavaria to decarbonize. Marburg hosts dense mRNA batch release activity alongside Belgian corridor facilities.
France
ANSM pharmacovigilance oversight extends time-to-market for novel submissions beyond historical baselines. Regional health system consolidation in Île-de-France and Auvergne-Rhône-Alpes displaces municipal tenders with framework agreements. Lyon anchors subunit vaccine manufacturing clusters serving national immunization schedules.
Italy
Hospital pharmacy procurement groups consolidate purchasing across Lombardy and Emilia-Romagna catchment populations. MDR device-delivery combination frameworks expand addressable revenue for auto-injector bundling. Pavia and Siena host research institutes accelerating intranasal delivery development.
Poland
Underpenetrated national immunization schedules present volume upside as EU structural funds modernize healthcare infrastructure. REACH registration costs for novel excipients inflate raw material qualification budgets for entrants. Warsaw and Kraków clusters attract modular fill-finish investments from Western European suppliers.
Netherlands
Mid-scale modular facilities in Brabant capture regional supply contracts previously held by centralized German sites. EMA accelerated assessment pathways process variant-adapted mRNA submissions from Leiden corridor developers. Pilot procurement in Dutch hospital pharmacy networks tests transdermal microneedle compliance advantages.
Europe Vaccines Market Vendor Landscape
Top-tier vendors anchor pan-European supply contracts, while mid-tier specialists occupy niche platform segments. The vendor base stratifies across mRNA platform investors, subunit incumbents with Paul-Ehrlich-Institut release history, and smallpox countermeasure specialists. Three archetypes dominate: scaled manufacturers bundling cold-chain subscriptions, R&D-intensive platform adapters, and specialized biodefense contractors. Competitive moves concentrate on M&A for lipid nanoparticle formulation capabilities and strategic partnerships for Eastern EU distribution reach.
Within the scaled manufacturing tier, GSK and Sanofi Pasteur exemplify divergent strategic positioning. GSK leverages pan-European logistics networks to bundle temperature-integrity services with bulk supply agreements. Sanofi Pasteur occupies a position emphasizing R&D intensity in mRNA platform adaptations for endemic diseases. Bavarian Nordic represents the specialized contractor archetype, anchoring smallpox and mpox countermeasure manufacturing capabilities distinct from routine immunization suppliers.
| Leading Market Players |
|---|
| AstraZeneca |
| Bavarian Nordic |
| GSK |
| IDT Biologika |
| Valneva |
| Sanofi Pasteur |
| Novartis |
| Emergent BioSolutions |
| Roche |
| Others |
Supply Flow & Price Mechanics
REACH registration costs for novel lipid nanoparticle excipients cascade from ECHA compliance budgets through to per-dose pricing tiers, with German and Belgian manufacturers absorbing six-figure substance qualification overhead while Eastern European entrants face steeper pass-through to tender bids.
Pricing Analysis
Capacity additions in Belgium and Germany are reshaping price floors for mRNA formulations as modular fill-finish facilities in the Netherlands and Portugal capture regional contracts at compressed rates. Three-tier pricing structure across premium cold-chain-integrated, standard bulk-supply, and economy tender-minimum levels separates GSK's subscription-bundled offerings from commodity pediatric tenders. Cost compression in the economy tier is intensifying because Polish and Romanian procurement centralization exposes Western incumbents to volume-discount pressure. Hospital pharmacy groups in Southern Europe exhibit lowest price sensitivity due to bundled framework agreements, while municipal tenders in fragmented French regions remain most exposed to competitive bidding.
Supply Chain Analysis
Ultra-low temperature logistics costs for mRNA stability anchor supply chain decisions, with distribution running through Belgian corridor hubs serving German batch release and Dutch modular facilities. Manufacturing concentrates in Germany, Belgium, and the Netherlands, with emerging fill-finish capacity in Poland and Romania. Raw material sourcing draws from Swiss lipid suppliers, Austrian packaging component specialists, and Irish API intermediates. Single-source vulnerability around ionizable lipid formulations creates exposure to REACH registration delays. Downstream distribution rests on national immunization program tender structures with centralized procurement in Germany and fragmented regional purchasing in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe vaccines market functions as a geographic-arbitrage play where REACH compliance cost differentials between established Western European suppliers and Eastern European entrants create entry windows for modular manufacturing investments.
For Market Incumbents: Cement pan-European logistics dominance by acquiring software-defined cold-chain monitoring capabilities before subscription revenue layers commoditize. Expand fill-finish capacity in Poland and Romania to preempt Eastern European tender consolidation. Defend against mRNA platform specialists by accelerating Paul-Ehrlich-Institut release history into combination pediatric products. For New Entrants and Emerging Players: Enter via intranasal delivery development partnerships with Italian research institutes in Pavia and Siena, where mucosal immunity R&D lacks scaled manufacturing conversion. Target traveler vaccine pharmacy channels in France and Spain for premium margin capture absent tender price compression. Pursue go-to-market through Dutch hospital pharmacy pilot procurement for transdermal microneedle compliance advantages. For Investors and Strategic Acquirers: Consolidation pressure builds where lipid nanoparticle formulation talent scarcity intersects with MDR device-delivery combination certification bottlenecks. Long-term viability favors scaled manufacturers with Paul-Ehrlich-Institut release history and cold-chain subscription revenue. Acquisition target archetype: mid-tier subunit specialists with established national immunization schedule contracts and underutilized fill-finish capacity. Signal to watch: EMA accelerated assessment pathway queue length for variant-adapted mRNA submissions as indicator of platform competition intensity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Device-Delivery Certification | Auto-injector bundling expands addressable revenue per dose in German school-based programs. |
| Lipid Nanoparticle Formulation Acquisition | REACH-registered excipient portfolios reduce raw material qualification timelines for mRNA scale-up. |
| Eastern European Modular Capacity | Polish and Romanian fill-finish sites capture EU structural fund healthcare modernization contracts. |
| Software-Defined Cold-Chain Subscription | Real-time temperature monitoring services create recurring revenue atop physical distribution. |
| Intranasal Delivery Platform Extension | IgA-mediated respiratory immunity positions developers for EMA accelerated assessment pathways. |
Methodological Framework
Direct dialogue with vaccine manufacturing executives, EMA regulatory affairs leads, German Paul-Ehrlich-Institut batch release officers, French ANSM pharmacovigilance specialists, and hospital pharmacy procurement managers in Italy and Spain grounded qualitative assessment. Secondary validation drew from EMA centralized marketing authorization procedures, ClinicalTrials.gov investigator-initiated studies, EU Green Deal pharmaceutical sector emissions disclosures, and REACH registration databases for lipid nanoparticle excipients. Bottom-up tender analysis across national immunization programs triangulated with top-down capacity investment tracking at Belgian and German manufacturing clusters.
Segmented outputs across technology platform, delivery mode, end-user channel, and application category fed into analytical framework spanning the projection horizon. Modeled dimensions included mRNA versus subunit versus live attenuated platform splits, injectable versus intranasal versus transdermal route differentiation, and pediatric versus traveler versus geriatric application tiers. CAGRs were derived from volume-weighted tender commitments and capacity expansion announcements. Industry-specific inputs encompassed EMA accelerated assessment pathway utilization rates and Paul-Ehrlich-Institut batch release backlog durations.
Inputs from EMA marketing authorization databases and national competent authority release records were available through the study window; gaps in Eastern European ultra-low temperature storage infrastructure deployment timelines introduce uncertainty bands for mRNA distribution reach forecasts. Forecasts reflect assumptions around EU Green Deal emissions target enforcement timelines and MDR device-delivery framework implementation consistency. A model refresh is warranted upon material change in EMA batch release staffing levels or REACH substance registration cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Global HPMC Capsules Market