
 Global Antiemetics Market | 2026-2036
Global Antiemetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antiemetics Market Foresight
ISO 13485 certification for medical device quality management is reorganizing supplier eligibility across the antiemetics supply chain, particularly for combination drug-device delivery systems used in oncology settings. Pfizer Inc. leverages its manufacturing scale across multiple receptor antagonist classes to sustain hospital formulary positioning. Merck & Co., Inc. anchors its portfolio through neurokinin-1 receptor antagonist specialization in high-emetic-risk chemotherapy protocols. GlaxoSmithKline plc differentiates via established serotonin receptor antagonist franchises with deep channel penetration into retail pharmacy networks.
Antiemetics comprise pharmacological agents that modulate neurotransmitter signaling across dopamine, serotonin, histamine, acetylcholine, and substance P pathways to prevent or suppress vomiting reflex activation, with formulations ranging from oral tablets and orally disintegrating tablets to intravenous solutions and transdermal patches engineered for specific onset requirements and bioavailability profiles. The primary commercial purpose centers on prophylaxis and treatment of nausea and vomiting across chemotherapy, surgical recovery, motion-induced, and infectious etiologies. Serotonin receptor antagonists occupy the largest revenue pool given their first-line status in chemotherapy-induced nausea protocols across oncology centers. Neurokinin-1 receptor antagonists represent the fastest-expanding segment as combination regimens with 5-HT3 inhibitors become standard for highly emetogenic chemotherapy. Dopamine antagonists face margin compression in institutional settings where generic penetration has accelerated.
FDA risk evaluation and mitigation strategies for intravenous ondansetron constrain dispensing practices and mandate cardiovascular monitoring protocols that shape hospital procurement criteria. EMA pharmacovigilance requirements under the EU MDR framework impose additional post-market clinical follow-up obligations on manufacturers marketing across European oncology centers. Stakeholders must monitor evolving FDA and EMA guidance on antiemetic co-administration with immune checkpoint inhibitors, as emerging combination oncology regimens redefine prophylactic standards and create new product qualification requirements.
Market Dynamics
FDA risk evaluation and mitigation strategies for intravenous 5-HT3 receptor antagonists are compressing hospital procurement timelines and mandating cardiovascular monitoring infrastructure that reshapes formulary economics.
Growth Catalysts
- EMA pharmacovigilance under EU MDR:Post-market clinical follow-up obligations for oncology centers are accelerating demand for combination drug-device systems with embedded safety monitoring.
- High-emetic-risk chemotherapy expansion:Neurokinin-1 receptor antagonist protocols are becoming standard prophylaxis, pulling volume through hospital infusion centers.
- ISO 13485 certification requirements:Supplier eligibility constraints for combination delivery systems are concentrating procurement toward qualified manufacturers with device quality management credentials.
Market Restraints
- Generic serotonin antagonist saturation:Oral ondansetron commoditization has collapsed institutional margins and displaced originator products from standard-of-care protocols.
- Active pharmaceutical ingredient concentration:Key 5-HT3 antagonist API production clusters in India and China create single-source vulnerability for finished dose manufacturers.
- Cardiovascular safety monitoring costs:FDA-mandated QT interval surveillance for intravenous formulations adds fixed overhead that erodes profitability in high-volume chemotherapy units.
Strategic Opportunities
- Transdermal patch delivery systems:Sustained-release formulations bypass first-pass metabolism and capture surgical recovery segments where oral compliance fails.
- Japan's PMDA fast-track oncology pathway:Accelerated approval timelines for antiemetic combinations with immune checkpoint inhibitors open premium positioning for novel mechanisms.
- Pharmacy benefit manager integration:Direct contracting with United States PBMs for orally disintegrating tablet formularies bypasses hospital procurement bottlenecks.
Industry Challenges
- Device-drug combination validation timelines:ISO 13485 certification cycles for novel delivery systems extend 18-24 months, delaying market entry against pure pharmaceutical competitors.
- Cross-receptor pharmacology expertise scarcity:Clinical development teams fluent in both 5-HT3 and NK-1 pathway interactions command premium compensation that strains R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antiemetics Market |
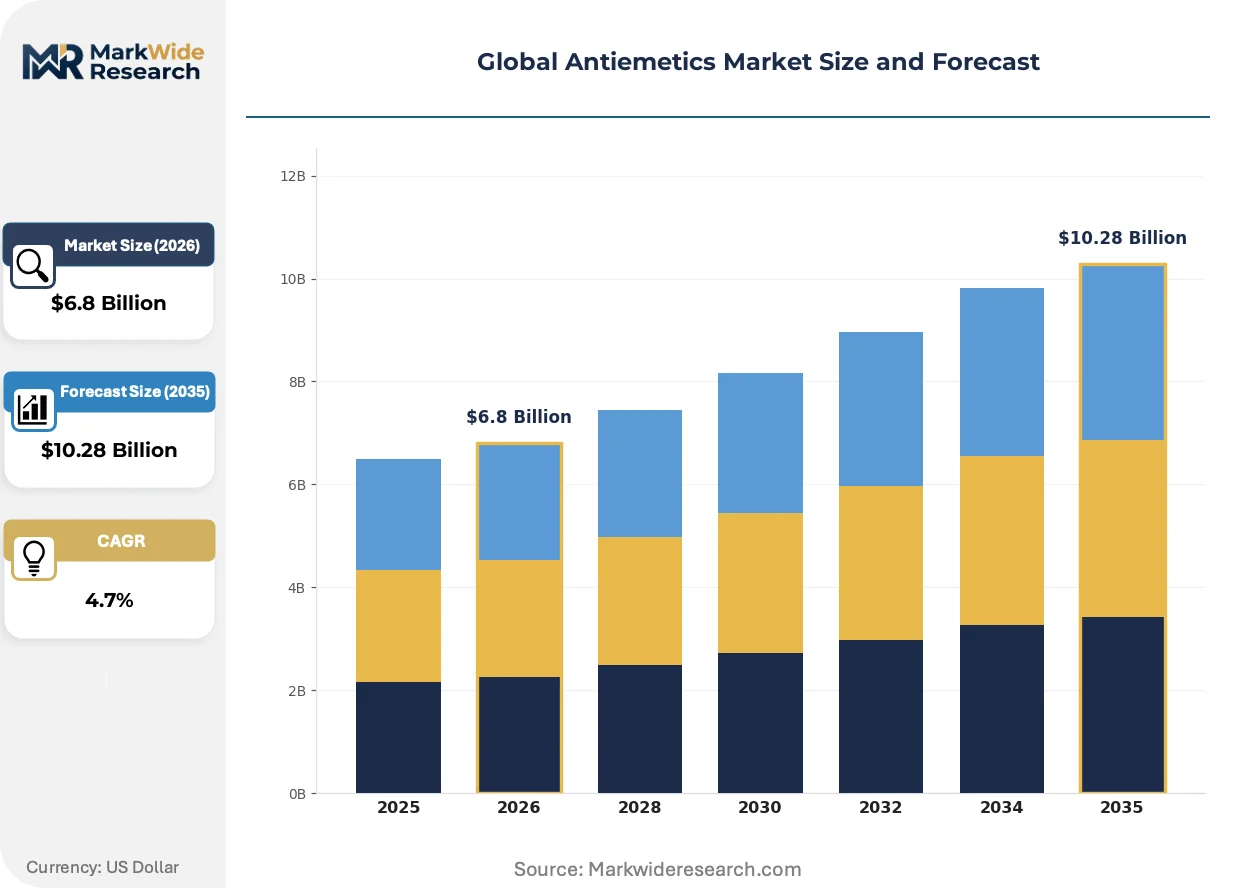
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serotonin Receptor Antagonists, Dopamine Antagonists, Neurokinin-1 Receptor Antagonists, Anticholinergics, Antihistamines Application: Chemotherapy-Induced Nausea, Postoperative Nausea, Motion Sickness, Pregnancy-Related Nausea, Gastroenteritis End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Oncology Centers, Home Healthcare Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Pfizer Inc., Johnson & Johnson Services, Inc., Merck & Co., Inc., GlaxoSmithKline plc., Cipla Inc., F. Hoffmann-La Roche Ltd., Novartis AG, Sanofi, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antiemetics Market Shifts & Advancements
Antiemetic delivery technology is fragmenting across receptor-specific formulations while regulatory surveillance intensifies for cardiovascular safety endpoints.
Orally disintegrating tablet technology is decomposing the hospital-centric infusion model for chemotherapy-induced nausea prophylaxis. Oncology outpatient clinics in the United States are adopting these formulations at accelerating rates to reduce chair time and staffing overhead. This shift is compressing intravenous solution volumes while expanding retail pharmacy capture of maintenance antiemetic regimens.
EU MDR pharmacovigilance requirements are mandating systematic post-market clinical follow-up for neurokinin-1 receptor antagonists used in combination protocols. European oncology centers must now submit periodic safety update reports that include cardiovascular event data. Manufacturers marketing across Germany, France, and Italy are restructuring field medical teams to support these surveillance obligations.
Hospital formulary committees are consolidating vendor relationships around suppliers offering integrated 5-HT3 and NK-1 antagonist portfolios. This concentration is displacing single-mechanism vendors from preferred tier status. The United States exhibits the most pronounced consolidation, with pharmacy benefit managers amplifying hospital purchasing leverage through aligned contracting.
Global Antiemetics Market Segmentation
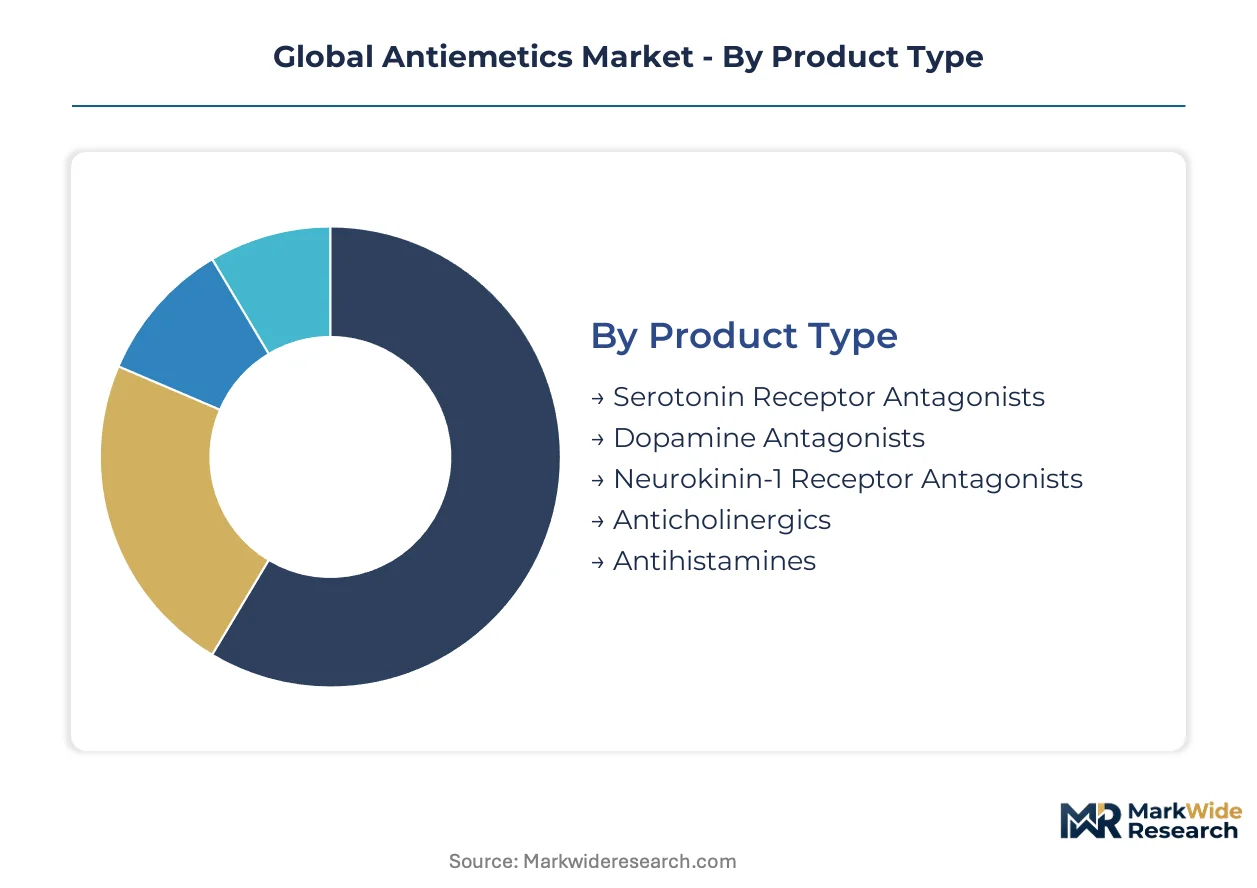
Antiemetic segmentation reveals divergent margin structures across receptor pharmacology, clinical setting economics, and channel control points. Manufacturers optimize portfolio mix by mapping formulation costs against reimbursement codes and procurement leverage.
Product Type:
Margin pools concentrate in receptor-specific formulations where patent protection or device combination status sustains pricing power against generic erosion.
- Serotonin Receptor Antagonists:5-HT3 pathway inhibitors including ondansetron and palonosetron dominate first-line chemotherapy protocols. United States oncology centers anchor demand as FDA-mandated cardiovascular monitoring for intravenous formulations creates barrier-to-entry for pure generics.
- Neurokinin-1 Receptor Antagonists:Substance P pathway blockers such as aprepitant and rolapitant command premium positioning in high-emetic-risk regimens. German and French hospital formularies drive European volume as EMA pharmacovigilance requirements under EU MDR favor established safety databases.
- Dopamine Antagonists:Prochlorperazine and metoclopramide face severe margin compression from Indian and Chinese API oversupply.
- Anticholinergics:Scopolamine transdermal systems capture surgical recovery segments in Japan where PMDA fast-track pathways reward novel delivery.
- Antihistamines:Meclizine and dimenhydrinate formulations serve motion sickness prophylaxis through retail pharmacy channels with minimal clinical differentiation.
The dominant share belongs to Serotonin Receptor Antagonists, while Neurokinin-1 Receptor Antagonists is closing the gap fastest.
Application:
Revenue concentration tracks emetogenic intensity of underlying clinical condition and corresponding prophylactic protocol standardization.
- Chemotherapy-Induced Nausea:CINV protocols represent the deepest reimbursement pool with combination 5-HT3 plus NK-1 antagonist regimens now standard across United States, Germany, and Japan oncology networks. Institutional purchasing consolidates around suppliers offering complete receptor coverage.
- Postoperative Nausea:PONV prophylaxis in ambulatory surgical settings favors rapid-onset intravenous formulations with short half-lives enabling same-day discharge. United Kingdom NHS procurement frameworks emphasize cost-per-prevented-emesis metrics.
- Motion Sickness:Transdermal scopolamine and oral antihistamines serve aviation and maritime markets with direct-to-consumer retail economics.
- Pregnancy-Related Nausea:Doxylamine-pyridoxine combinations face regulatory scrutiny from FDA reproductive toxicity classifications limiting promotion.
- Gastroenteritis:Ondansetron oral disintegrating tablets dominate emergency department protocols for pediatric dehydration management.
Chemotherapy-Induced Nausea commands institutional purchasing volumes, whereas Postoperative Nausea is expanding most quickly through ambulatory center conversion.
End User:
Customer type determines formulation requirements, compliance infrastructure, and contracting complexity across the value chain.
- Hospitals:Acute care institutions in the United States and Germany consolidate antiemetic procurement through pharmacy and therapeutics committees with ISO 13485 certification requirements for combination drug-device systems.
- Oncology Centers:Dedicated infusion facilities in France and Italy drive neurokinin-1 receptor antagonist adoption through protocol-driven combination regimens.
- Specialty Clinics:Gastroenterology and pain management practices in Japan favor orally disintegrating tablets for patient convenience.
- Ambulatory Surgical Centers:United States outpatient facilities prioritize rapid-turn intravenous formulations with minimal monitoring overhead.
- Home Healthcare:Transdermal patches and oral formulations serve post-discharge maintenance in United Kingdom community settings.
Hospitals retain the largest procurement scale, though Oncology Centers is gaining share fastest through protocol specialization.
Distribution Channel:
Channel selection shapes margin capture through formulary access, inventory risk allocation, and direct-to-patient reach.
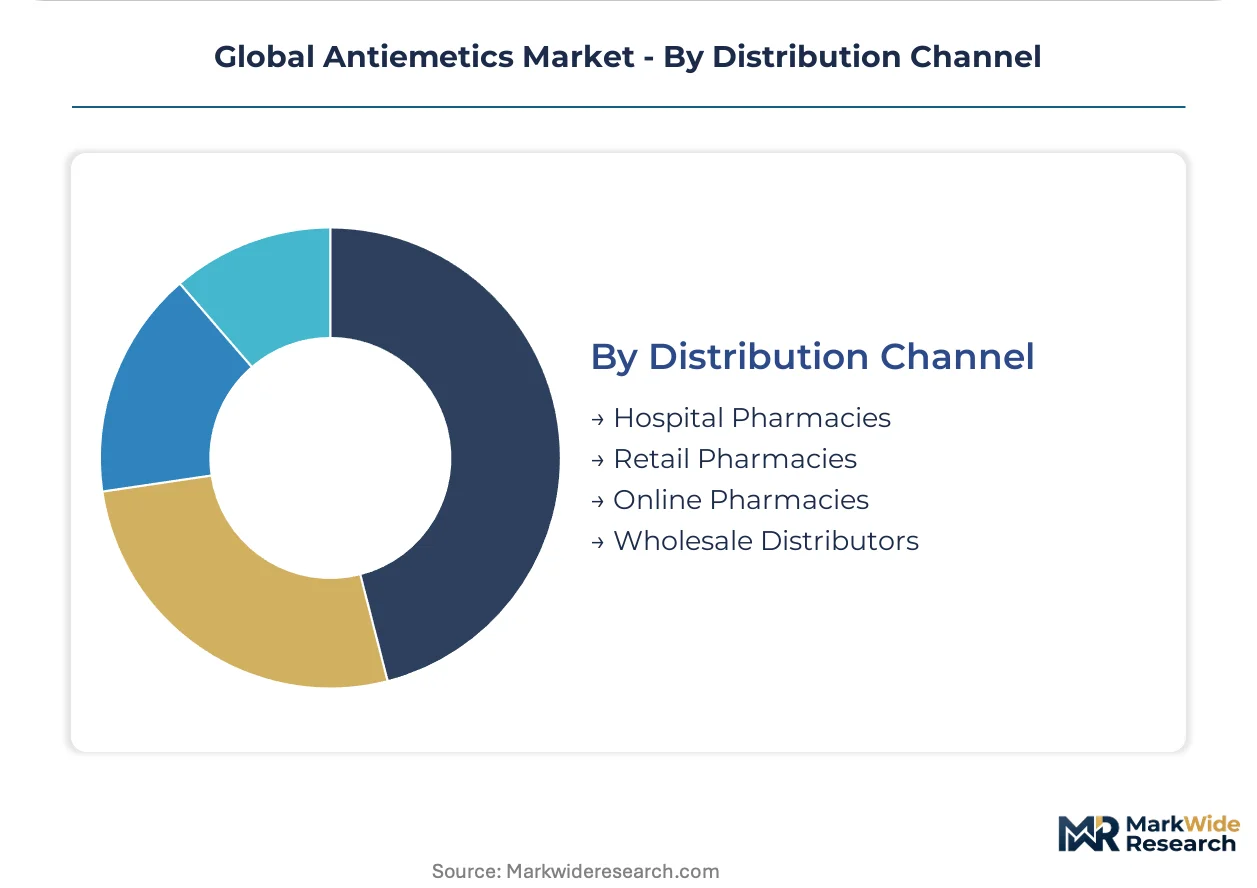
- Hospital Pharmacies:Captive dispensing within United States and German acute care facilities controls intravenous 5-HT3 antagonist distribution with mandated cardiovascular monitoring infrastructure.
- Retail Pharmacies:CVS Health and Walgreens Boots Alliance in the United States, plus Boots UK, dominate oral antiemetic fulfillment with pharmacy benefit manager contracting leverage.
- Online Pharmacies:Amazon Pharmacy and Zur Rose in Germany expand motion sickness and pregnancy-related nausea product access with direct-to-home logistics.
- Wholesale Distributors:McKesson and AmerisourceBergen in the United States, plus Phoenix Group in Germany, manage inventory and cold-chain logistics for hospital and clinic networks.
Hospital Pharmacies control the highest-value intravenous segment, while Online Pharmacies is climbing the fastest through patient convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive antiemetic formulations.
United States
Oncology centers in Houston and Boston drive intravenous 5-HT3 antagonist consumption through expanded prophylactic protocols. FDA risk evaluation and mitigation strategies mandate cardiovascular monitoring infrastructure that reshapes hospital procurement economics. The Research Triangle Park cluster in North Carolina anchors clinical trial activity for neurokinin-1 receptor antagonist combinations.
Germany
Hospital formularies in Munich and Berlin consolidate procurement around ISO 13485-certified suppliers for combination drug-device systems. EMA pharmacovigilance requirements under EU MDR impose systematic post-market clinical follow-up obligations on manufacturers. The Rhine-Main pharmaceutical corridor concentrates safety database management for European oncology networks.
Japan
PMDA fast-track oncology pathways accelerate approval timelines for antiemetic combinations with immune checkpoint inhibitors. METI industrial policy supports domestic manufacturing of orally disintegrating tablet formulations. The Kansai region's Osaka-Kobe pharmaceutical cluster specializes in transdermal delivery system production for surgical recovery segments.
India
API production clusters in Hyderabad and Ahmedabad supply key 5-HT3 antagonist intermediates to finished dose manufacturers worldwide. CDSCO manufacturing facility inspections enforce quality standards for export-oriented oncology formulations. The Gujarat pharmaceutical zone concentrates generic ondansetron production serving institutional markets across emerging economies.
United Kingdom
NHS procurement frameworks emphasize cost-per-prevented-emesis metrics for postoperative nausea prophylaxis in ambulatory surgical settings. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR pharmacovigilance standards for oncology center compliance. The Cambridge-London life sciences corridor hosts clinical development programs for novel receptor antagonist mechanisms.
Global Antiemetics Market Competitive Landscape
Listed leaders compete with private specialists across receptor antagonist portfolio breadth, with hospital formulary positioning determining procurement outcomes. The market structure concentrates around integrated pharmaceutical corporations with multi-class manufacturing capabilities and specialized oncology-focused developers. Three archetypes dominate: diversified giants with device quality management credentials, NK-1 pathway specialists commanding premium positioning, and generic manufacturers exploiting API cost advantages. Competitive moves center on M&A for delivery system capabilities and strategic partnerships with pharmacy benefit managers for oral formulation access.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. exemplify scale-driven hospital formulary anchoring across multiple receptor classes. GlaxoSmithKline plc occupies a position representing established serotonin antagonist franchises with deep retail pharmacy penetration. Among specialty developers, Cipla Inc. and Teva Pharmaceutical Industries Ltd. sit within the generic-access archetype, leveraging API integration for institutional margin capture.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc. |
| Cipla Inc. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Generic ondansetron substitution for intravenous palonosetron in United States oncology centers is simultaneously relocating API sourcing toward Indian manufacturing clusters and collapsing institutional margins through pharmacy benefit manager tiering.
Pricing Analysis
Certification level (ISO 13485, FDA-grade device quality) creates the primary spread between premium combination drug-device systems and commodity oral tablets. Three-tier pricing structure across premium NK-1 antagonist combinations, standard 5-HT3 formulations, and economy generic ondansetron reflects reimbursement code differentiation. Cost compression in the serotonin antagonist tier is intensifying because pharmacy benefit manager formulary exclusions have commoditized oral disintegrating tablets. Hospital procurement committees exhibit lowest price sensitivity for cardiovascular-monitored intravenous regimens, while ambulatory surgical centers demonstrate highest sensitivity to per-dose economics.
Supply Chain Analysis
Port congestion at Nhava Sheva and container availability constraints on the India-Europe trade lane are extending lead times for 5-HT3 antagonist API shipments to finished dose manufacturers. Active pharmaceutical ingredient production clusters in India, China, and the United States feed global formulation networks with ondansetron and palonosetron intermediates. Key dependencies include scopolamine base from Italian botanical processors, transdermal patch substrates from Japanese specialty film manufacturers, and sterile vial packaging from German glassworks. Single-source vulnerability in Indian API production creates supply chain risk given CDSCO inspection backlogs. Distribution runs through wholesale distributors McKesson and AmerisourceBergen in the United States, Phoenix Group in Germany, and regional hospital purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FDA risk evaluation and mitigation strategies create regulatory entrenchment that protects incumbents with established cardiovascular safety databases.
For Market Incumbents: Fortify hospital formulary positioning through backward integration into ISO 13485-certified device manufacturing capabilities that generic competitors cannot replicate. Expand field medical teams to support EMA pharmacovigilance reporting obligations, converting compliance burden into relationship lock-in with European oncology centers. The threat of NK-1 antagonist biosimilar entry from Indian manufacturers demands preemptive capacity expansion in United States infusion center partnerships.
For New Entrants and Emerging Players: Post-market clinical follow-up service gaps in EU MDR compliance represent the most penetrable white-space where incumbents under-serve mid-tier oncology centers. Target Japan's PMDA fast-track pathway for antiemetic-immune checkpoint inhibitor combinations, where accelerated timelines reward novel mechanism submissions. A go-to-market angle anchored in digitally integrated cardiovascular monitoring platforms can bypass established hospital procurement relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive API supply and device quality credentials. Long-term viability over the projection horizon rests on regulatory entrenchment depth and formulary tier positioning rather than pipeline novelty. Acquisition target archetype: mid-cap specialists with ISO 13485 certification and established European safety databases. The signal to watch is pharmacy benefit manager contracting leverage shifting toward orally disintegrating tablet formularies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PMDA fast-track submissions for NK-1 antagonist combinations accelerate Japanese market access timelines. |
| Regulatory Approval Pathway | FDA risk evaluation and mitigation strategy compliance creates barrier-to-entry for cardiovascular-monitored formulations. |
| Manufacturing Scale-Up | ISO 13485-certified device production capacity secures hospital formulary eligibility for combination systems. |
| Pipeline Diversification | Transdermal delivery development captures surgical recovery segments with bypassed first-pass metabolism. |
| Strategic Partnership | Direct PBM contracting for orally disintegrating tablets bypasses hospital procurement bottlenecks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oncology pharmacy directors, hospital formulary committee members, regulatory affairs specialists at receptor antagonist manufacturers, and procurement managers at United States group purchasing organizations. Secondary validation drew from FDA REMS documentation, EMA periodic safety update report databases, ClinicalTrials.gov protocol registries, and hospital formulary tiering publications. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue segmentation across receptor classes and administration routes.
Across the analysis window, projections integrated treatment protocol evolution in oncology centers, reimbursement code stability for prophylactic antiemetic regimens, and regulatory surveillance intensity for cardiovascular endpoints. Segmentation dimensions modeled include receptor pharmacology, dosage form, emetogenic risk classification, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to procedure volume forecasts and protocol penetration assumptions. Industry-specific inputs encompassed chemotherapy regimen expansion rates and immune checkpoint inhibitor combination trial pipelines.
Forecasts assume regulatory continuity in FDA REMS requirements and EU MDR pharmacovigilance obligations; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Gabapentin Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Photophobia Drug Market