
 Anti-Obesity Therapeutics Market | 2026-2036
Anti-Obesity Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Obesity Therapeutics Market Outlook
Endocrinology fellowship training capacity is rotating toward metabolic disease management as health systems scramble to staff obesity care programs. Novo Nordisk A/S dominates the injectable GLP-1 segment with manufacturing scale that anchors its supply position. Eli Lilly and Company differentiates through dual GIP/GLP-1 receptor agonist technology that extends its clinical value proposition. Boehringer Ingelheim International GmbH competes through cardiovascular outcome integration that positions its pipeline for differentiated labeling.
Anti-obesity therapeutics comprise pharmacological agents, medical devices, and behavioral interventions designed to achieve and sustain clinically significant weight reduction, typically defined as five to fifteen percent body mass loss from baseline. Prescription drugs, particularly injectable peptide therapies, command the dominant margin pool as reimbursement frameworks expand coverage for pharmacotherapy. Device-based solutions occupy a niche recovery trajectory as surgical intervention volumes face substitution pressure from effective pharmaceutical alternatives. Homecare settings represent the fastest-growing delivery channel as self-administration protocols and telehealth monitoring reduce clinic dependency.
FDA obesity drug approval standards and EMA pharmacovigilance requirements for cardiovascular safety shape clinical trial design and commercialization timelines. The EU MDR framework imposes device reclassification burdens on implantable obesity technologies, while HIPAA compliance structures constrain digital therapeutic data architectures in the United States. Stakeholders must monitor reimbursement policy divergence between public and private payers as formulary placement decisions determine patient access trajectories and manufacturer revenue realization.
Market Dynamics
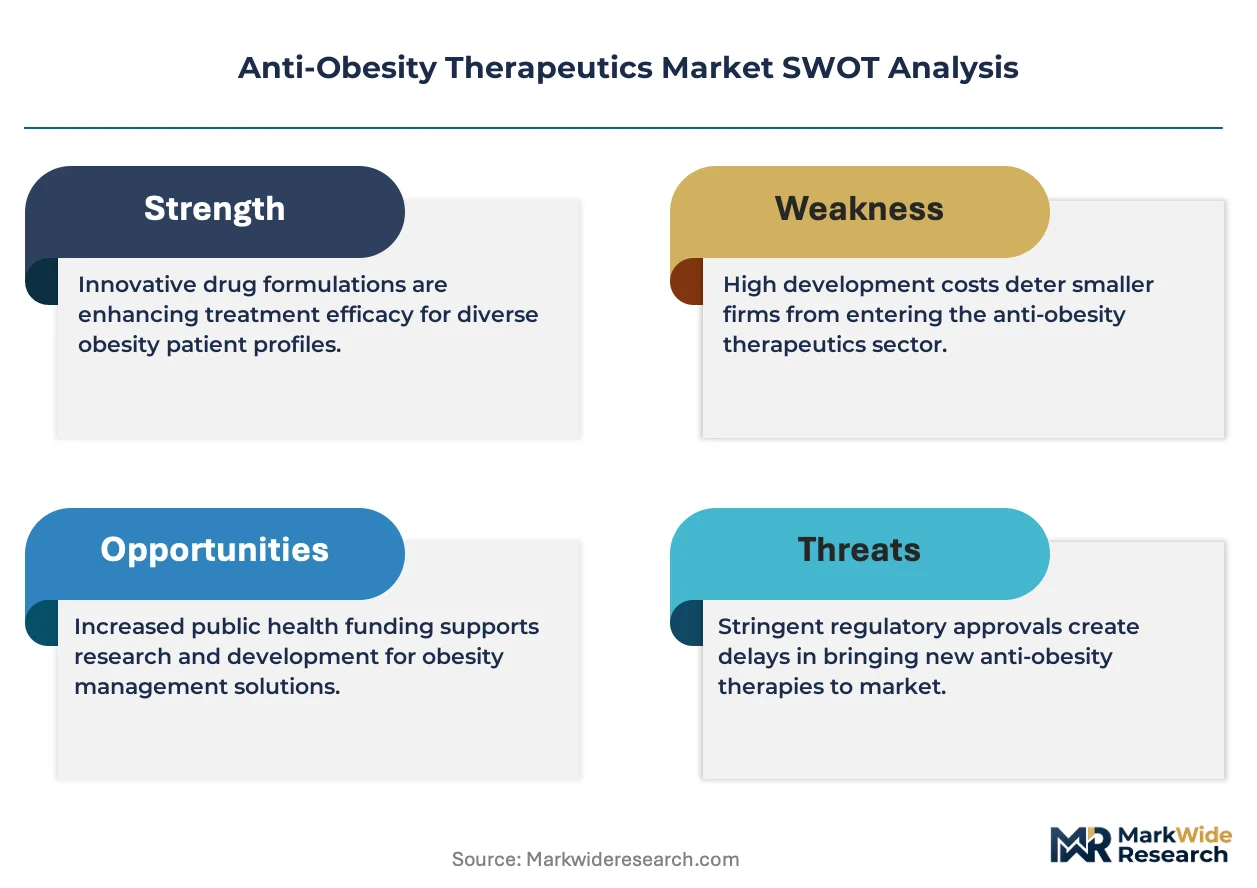
Injectable peptide therapies are compressing surgical intervention volumes while forcing hospital systems to reconfigure metabolic service lines around pharmacological protocols rather than bariatric procedures.
Growth Catalysts
- Employer-sponsored coverage expansion:Large self-insured employers in the United States are adding GLP-1 receptor agonists to formularies, creating direct demand pull from covered populations.
- FDA accelerated approval pathways:The Breakthrough Therapy and Fast Track designations for obesity drug candidates are compressing Phase III-to-approval timelines.
- Telehealth protocol maturation:Remote patient monitoring platforms enable home-based injection training and adherence tracking without clinic dependency.
Market Restraints
- Active pharmaceutical ingredient concentration:Peptide synthesis capacity concentrates among specialized CDMOs in Switzerland and Denmark, creating supply bottlenecks during demand surges.
- Medicare reimbursement exclusion:The statutory prohibition on Medicare Part D coverage for weight-loss drugs limits access for Americans aged sixty-five and older.
- Cardiovascular outcome trial requirements:FDA mandates for pre-approval CVOT data extend development timelines and inflate clinical trial costs.
Strategic Opportunities
- Oral small-molecule formulations:Non-injectable GLP-1 receptor agonists would unlock patient segments with needle aversion and simplify pharmacy distribution.
- Combination therapy protocols:Pairing incretin-based agents with SGLT2 inhibitors or mineralocorticoid antagonists creates differentiated metabolic profiles.
- India's metabolic disease burden:The country's rising obesity prevalence and expanding private insurance penetration create underpenetrated demand.
Industry Challenges
- Endocrinology workforce scarcity:Fellowship programs produce insufficient metabolic disease specialists to staff expanding obesity clinic networks.
- Cold chain integrity at scale:Multi-dose pen injectors require uninterrupted refrigerated distribution, complicating last-mile delivery to retail pharmacies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Obesity Therapeutics Market |
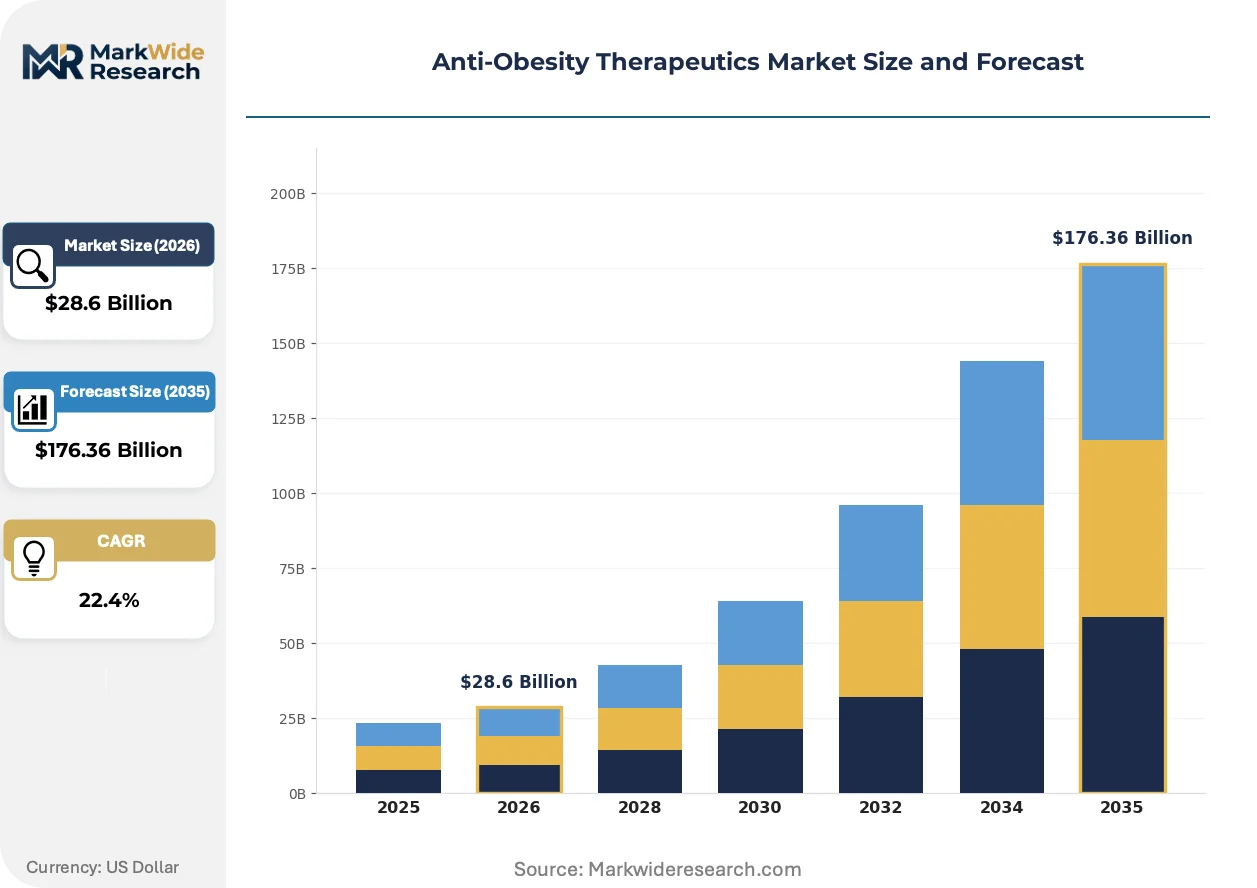
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $176.36 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-The-Counter Products, Dietary Supplements, Device-Based Solutions Therapy Area: Behavioral Therapy, Pharmacotherapy, Surgical Intervention, Nutritional Counseling End User: Healthcare Providers, Clinics, Hospitals, Homecare Settings Delivery Mode: Oral, Injectable, Transdermal, Inhalation |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, GlaxoSmithKline plc, F. Hoffmann-La Roche Ltd, Currax Pharmaceuticals LLC, VIVUS LLC, Boehringer Ingelheim International GmbH, Rhythm Pharmaceuticals, Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Obesity Therapeutics Market Strategic Shifts
Pharmaceutical innovation is splitting the market between high-efficacy injectable peptides and emerging oral alternatives, while regulatory frameworks and care delivery models scramble to adapt.
Dual GIP/GLP-1 receptor agonist technology is bifurcating the competitive landscape between single-mechanism legacy agents and next-generation combination therapies. Academic medical centers and integrated delivery networks are prioritizing these agents for treatment-resistant patients. The technology is bifurcating clinical trial endpoints, forcing sponsors to demonstrate superiority against existing standards rather than placebo.
EMA pharmacovigilance requirements for cardiovascular safety monitoring are reshaping post-market surveillance obligations. Sponsors must implement registry-based outcome tracking across multiple EU member states. The regulation most affects injectable peptide manufacturers, which are building pan-European patient monitoring infrastructure.
Direct-to-consumer pharmacy channels are displacing traditional clinic-based initiation protocols for established therapies. Telehealth platforms now handle prescription authorization and dose escalation without in-person visits. This shift concentrates in the United States, where state-level telehealth parity laws enable remote prescribing.
Anti-Obesity Therapeutics Market Segmentation
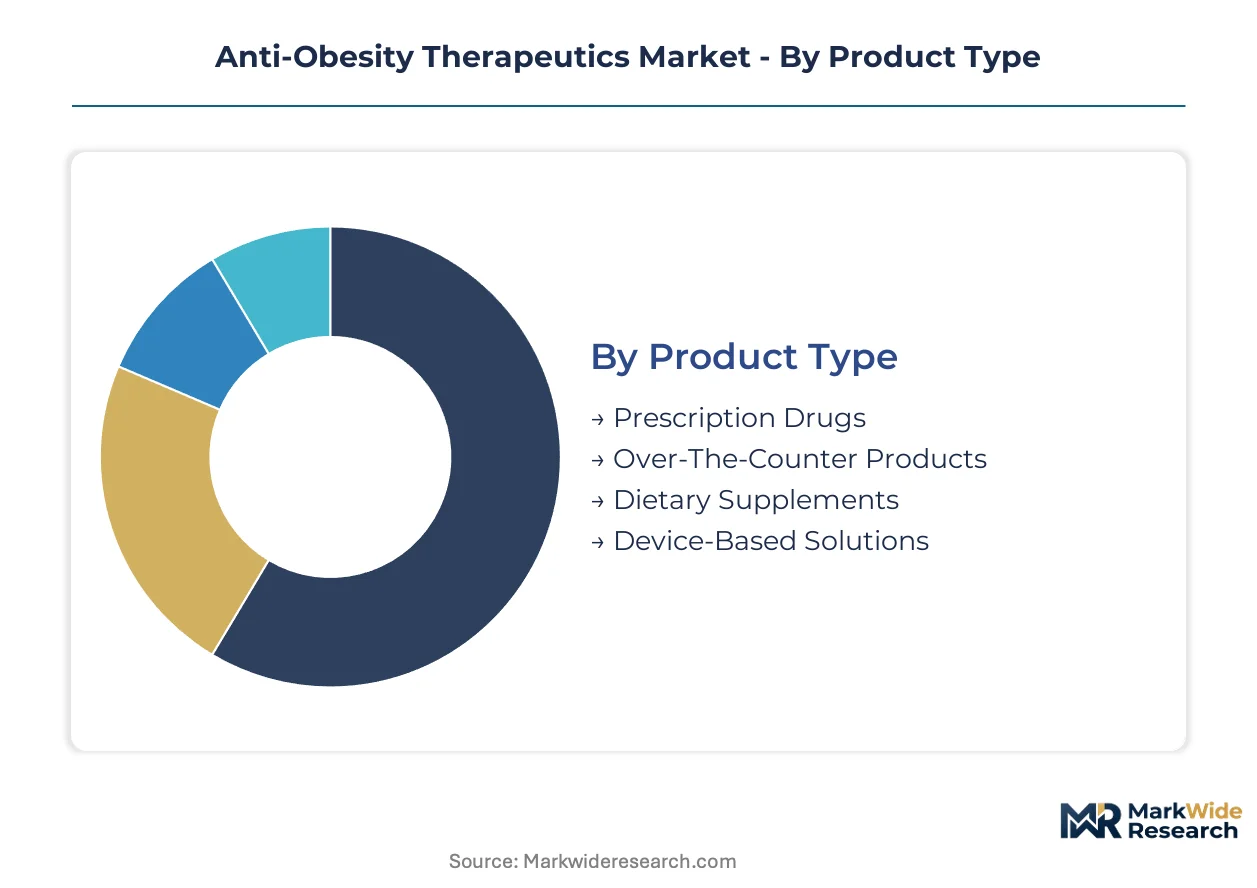
Anti-obesity therapeutics segment along four dimensions that determine reimbursement pathways, prescribing authority, and patient access protocols. Channel economics vary sharply between institutional settings and direct-to-consumer routes, with each segment commanding distinct margin profiles and regulatory scrutiny levels.
Product Type:
Distribution channels bifurcate sharply between pharmacy-dispensed pharmaceuticals and retail-direct wellness products, with prescription workflows dominating revenue concentration while consumer channels drive volume reach.
- Prescription Drugs:Injectable peptide therapies and oral small-molecule agents requiring physician authorization and pharmacy fulfillment. Hospital systems and specialty pharmacies in the United States capture the dominant share of GLP-1 receptor agonist dispensing as employer formularies expand coverage.
- Over-The-Counter Products:Orlistat and phentermine-topiramate combinations available without prescription through retail pharmacy chains. These products concentrate in pharmacy retail channels across Germany and the United Kingdom where pharmacist counseling requirements create a semi-regulated access layer.
- Dietary Supplements:Herbal and nutritional formulations with limited clinical evidence claims distributed through e-commerce platforms and mass retail.
- Device-Based Solutions:Gastric balloons and electrical stimulation systems deployed through ambulatory surgical centers and specialized clinics.
By volume, Dietary Supplements leads. By growth pace, Prescription Drugs is climbing the fastest.
Therapy Area:
Cost tier stratification separates high-intensity clinical interventions from lower-touch behavioral protocols, with reimbursement depth determining patient flow across the pyramid.
- Behavioral Therapy:Structured counseling programs delivered by registered dietitians and clinical psychologists. Digital therapeutic platforms in Sweden and the Netherlands are scaling automated cognitive behavioral interventions for weight management as national health systems integrate software-based treatments into standard care pathways.
- Pharmacotherapy:Drug-based protocols using incretin mimetics, lipase inhibitors, and combination therapies. Academic medical centers in Switzerland and Denmark prioritize these interventions for patients with metabolic comorbidities as EMA cardiovascular safety databases mature.
- Surgical Intervention:Bariatric procedures including gastric bypass and sleeve gastrectomy performed in hospital operating suites.
- Nutritional Counseling:Dietary planning and macronutrient optimization delivered through telehealth and clinic-based consultations.
Pharmacotherapy commands the highest per-patient economics. Nutritional Counseling shows the steepest expansion trajectory as telehealth platforms reduce delivery friction.
End User:
Customer type determines procurement authority and reimbursement complexity, with institutional buyers negotiating formulary placement while individual patients drive out-of-pocket segments.
- Healthcare Providers:Individual physicians and group practices prescribing and managing obesity treatment protocols. Endocrinology specialists in the United States are consolidating into metabolic health service lines as health systems respond to GLP-1 demand surges.
- Clinics:Dedicated weight management and metabolic health facilities. Private clinic networks in India are expanding bariatric service capacity as urban obesity prevalence climbs and medical tourism flows strengthen.
- Hospitals:Integrated delivery networks and academic medical centers with comprehensive metabolic programs.
- Homecare Settings:Patient-managed injection and monitoring protocols supported by remote care infrastructure.
Hospitals anchor institutional procurement volume. Homecare Settings is gaining share fastest as self-administration protocols and telehealth monitoring reduce clinic dependency.
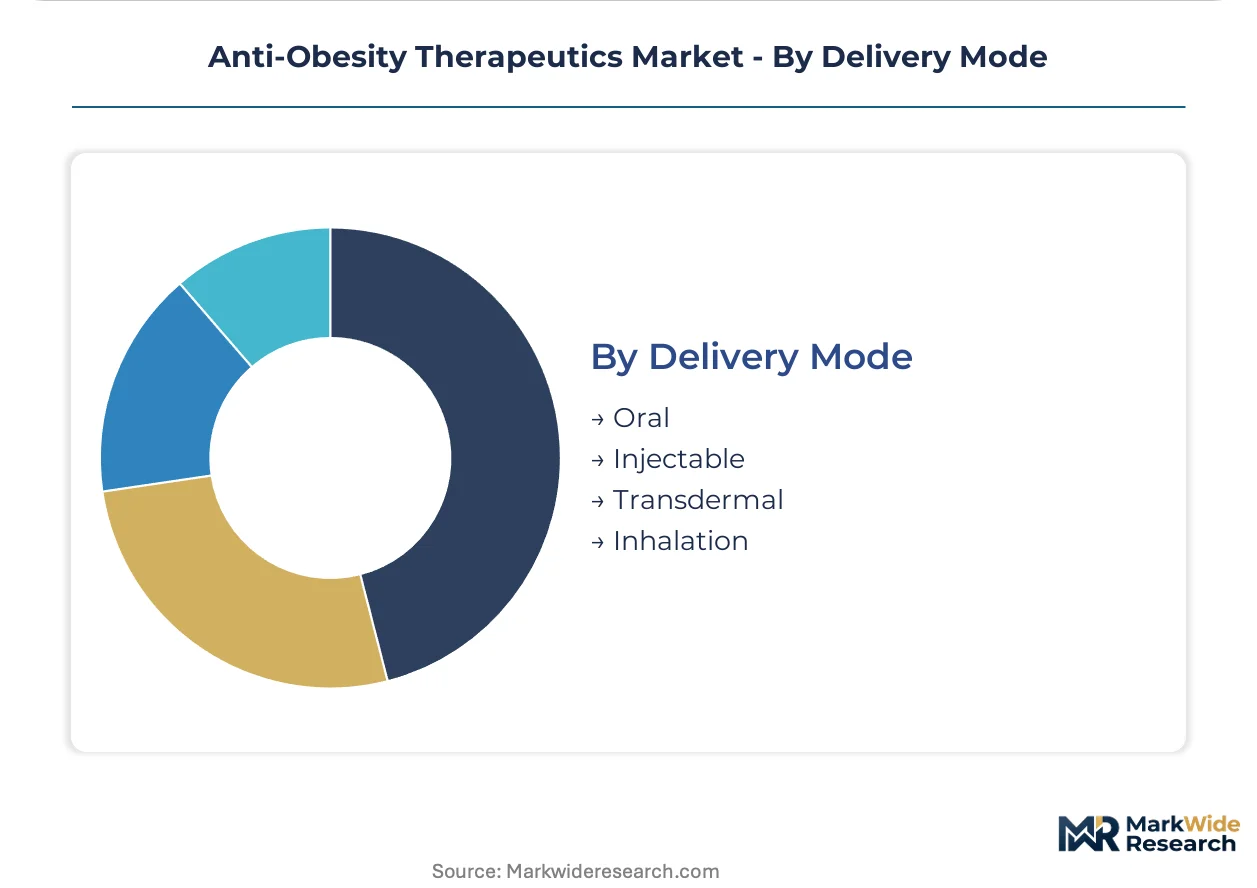
Delivery Mode:
Supply concentration shapes competitive positioning, with injectable formats demanding cold chain infrastructure while oral alternatives unlock geographic expansion.
- Injectable:Subcutaneous peptide formulations requiring refrigerated storage and pen-based delivery systems. Manufacturing capacity concentrates in Swiss and Danish CDMO facilities as peptide synthesis complexity limits supplier base expansion.
- Oral:Tablet and capsule formulations enabling pharmacy distribution without cold chain constraints. Formulation development in the United States and Japan is accelerating small-molecule GLP-1 programs to address needle aversion and simplify last-mile logistics.
- Transdermal:Patch-based delivery systems for continuous hormone or drug administration.
- Inhalation:Aerosolized and dry powder formulations for pulmonary absorption pathways.
Injectable formats dominate current revenue realization. Oral delivery is expanding most quickly as development pipelines prioritize patient convenience and distribution scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States far outstrips European markets, where EMA cost-effectiveness thresholds compress reimbursement rates. This asymmetry concentrates manufacturer investment toward American formulary placement while leaving EU markets as volume-fillers with thinner margins.
United States
Employer-sponsored coverage expansion and Medicare reimbursement debates pull demand from large self-insured corporations. FDA Breakthrough Therapy designations compress Phase III-to-approval timelines for obesity drug candidates. The Greater Boston corridor anchors metabolic health service line expansion as academic medical centers reconfigure around GLP-1 protocols.
Germany
Statutory health insurance cost-benefit assessments constrain pharmacotherapy access for BMI thresholds below 35. The EU MDR framework imposes device reclassification burdens on implantable obesity technologies. The Rhine-Ruhr metropolitan region concentrates bariatric clinic networks adapting to surgical volume compression from effective pharmaceutical alternatives.
Switzerland
Specialized CDMO peptide synthesis capacity anchors global supply chains for injectable GLP-1 receptor agonists. Swissmedic pharmacovigilance requirements align with EMA cardiovascular safety monitoring standards. The Basel biotech cluster houses manufacturing infrastructure that limits supplier base expansion during demand surges.
India
Rising urban obesity prevalence and expanding private insurance penetration create underpenetrated demand for metabolic disease management. The CDSCO accelerated approval pathway for drugs addressing unmet medical needs shortens regulatory timelines. Mumbai and Delhi-NCR private clinic networks scale bariatric service capacity as medical tourism flows strengthen.
Japan
PMDA consultation programs for innovative pharmaceuticals streamline development of oral small-molecule GLP-1 alternatives. METI healthcare technology assessment frameworks influence reimbursement pricing for obesity interventions. The Kanto region around Tokyo concentrates endocrinology fellowship programs rotating toward metabolic disease specialization.
Anti-Obesity Therapeutics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with peptide synthesis specialists commanding premium positioning while generic manufacturers compete on price. The market structure consolidates around injectable GLP-1 capacity holders with manufacturing scale advantages. Three archetypes dominate: large-cap pharmaceutical conglomerates with cardiovascular outcome integration capabilities, mid-cap metabolic disease specialists with focused pipelines, and emerging biotechs pursuing oral small-molecule formulations. Capacity expansion and strategic partnerships represent the dominant competitive moves as cold chain infrastructure and CDMO relationships become bottlenecks.
Among Danish and American pharmaceutical conglomerates, Novo Nordisk A/S and Eli Lilly and Company anchor the injectable peptide segment through manufacturing scale that limits competitive entry. Boehringer Ingelheim International GmbH occupies a differentiated position through cardiovascular outcome trial integration that shapes regulatory labeling. These three exemplify how manufacturing concentration and clinical trial infrastructure create defensive moats in a market where supply constraints persist.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| F. Hoffmann-La Roche Ltd |
| Currax Pharmaceuticals LLC |
| VIVUS LLC |
| Boehringer Ingelheim International GmbH |
| Rhythm Pharmaceuticals, Inc. |
| Amgen Inc. |
| Others |
Value Chain & Pricing Dynamics
Peptide synthesis scale economies in Swiss and Danish CDMO facilities concentrate manufacturing capacity among a handful of specialized suppliers, creating asymmetric pricing power that anchors price floors for injectable GLP-1 receptor agonists while compressing margins for second-tier oral formulation competitors.
Pricing Analysis
Configured-to-order pricing for patient-specific dosing protocols commands a substantial premium over standard pharmacy-dispensed formats in the United States. Three-tier pricing structure across premium, standard, and economy levels separates branded injectable peptides from authorized generics and compounded alternatives. Pricing pressure stems from Medicare Part D statutory exclusion limiting volume access for Americans aged sixty-five and older. Employer-sponsored plans show the lowest price sensitivity due to productivity-linked coverage justifications, while uninsured cash-pay patients face the highest sensitivity and drive demand for compounded semaglutide alternatives.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for active pharmaceutical ingredient shipments originating from Chinese fermentation facilities. Manufacturing concentration in Switzerland, Denmark, and the United States draws from specialized peptide synthesis infrastructure and cold chain distribution networks. Supply chain risk centers on single-source vulnerability for multi-dose pen injector components sourced from precision molders in Germany and Japan. Distribution runs through hospital systems and specialty pharmacy channels in the United States, with retail pharmacy chains capturing European volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as telehealth protocol maturation and employer formulary expansion create distinct patient access niches beyond traditional clinic-based initiation models.
For Market Incumbents: Secure captive peptide synthesis capacity through long-term CDMO offtake agreements or backward integration into fermentation infrastructure to defend against Novo Nordisk and Eli Lilly manufacturing scale advantages. Lock in exclusive hospital system partnerships before integrated delivery networks consolidate metabolic service line procurement authority. Prioritize cardiovascular outcome trial data integration for differentiated FDA labeling that sustains premium positioning against emerging oral small-molecule entrants.
For New Entrants and Emerging Players: Anchor in India's underpenetrated private insurance market where urban obesity prevalence climbs and CDSCO accelerated approval pathways compress regulatory timelines. Target oral small-molecule formulation development for needle-averse patient segments that incumbent injectable portfolios cannot serve. Pursue direct-to-consumer pharmacy channel partnerships that bypass traditional clinic-based initiation protocols and capture cash-pay volume outside employer-sponsored coverage networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among metabolic disease specialists with integrated telehealth platforms and pharmacy distribution relationships rather than device manufacturers facing surgical volume compression. Long-term viability favors acquisition targets with FDA Breakthrough Therapy designations already secured and cardiovascular outcome trial infrastructure in place. Watch for Medicare Part D reimbursement policy shifts as the primary inflection signal that would re-rate volume-access assumptions for the sixty-five-plus demographic.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | CVOT data integration shapes FDA labeling differentiation for cardiovascular safety claims. |
| Manufacturing Scale-Up | Peptide synthesis capacity expansion in Swiss CDMO facilities limits supply bottlenecks during demand surges. |
| Regulatory Approval Pathway | Breakthrough Therapy designation compresses Phase III-to-approval timelines for obesity candidates. |
| Strategic Partnership | Hospital system alliances secure formulary placement before IDN procurement consolidation accelerates. |
| Pipeline Diversification | Oral small-molecule programs address needle aversion and unlock pharmacy distribution scalability. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov protocols, and hospital formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists across North America and Europe. Primary fieldwork with CDMO operations managers and cold chain logistics providers validated capacity constraints and distribution economics. Secondary sources included SEC 10-K pharmaceutical disclosures, CMS Medicare coverage determinations, and EU MDR device classification notices. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates.
Variance decomposition across therapeutic modality, delivery format, patient population risk profile, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, therapy intensity tier, end-user procurement authority, and administration route. CAGRs were derived from patient volume forecasts applied to evolving reimbursement rates and pricing tier trajectories. Forecast inputs incorporated employer coverage expansion assumptions, Medicare policy scenario weights, and peptide manufacturing capacity utilization curves.
Underlying assumptions cover sustained employer formulary inclusion, stable FDA cardiovascular safety standards, and uninterrupted cold chain infrastructure, with deviation risk concentrated in Medicare legislative reform and active pharmaceutical ingredient supply disruptions. Forecasts reflect these documented conditions and scenario-weighted probabilities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Medication Adherence Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Antimycotics Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Aspirin API Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Olanzapine API Market
Pharmacology
Hypertension Drug Market
Pharmacology
Ketoprofen API Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Anti-Hypertensive Drugs Market