
 P2X7 Receptor Antagonists Market | 2026-2036
P2X7 Receptor Antagonists Market Size, Share, and Industry Trends Forecast 2026-2036
P2X7 Receptor Antagonists Market Analysis
Outcome-based licensing for companion diagnostics is decoupling reimbursement from pure molecule sales in the P2X7 antagonist space. Johnson & Johnson leverages its neurology franchise to anchor clinical development across multiple P2X7 indications. Roche sustains leadership through integrated biomarker platforms that stratify responder populations. Evotec specializes in fragment-based discovery, occupying a critical niche in early-stage candidate generation.
P2X7 receptor antagonists are small-molecule or biologic compounds that block ATP-gated ion channel signaling, typically exhibiting nanomolar affinity at the orthosteric binding site and allosteric modulation sites. These agents suppress NLRP3 inflammasome activation and IL-1β release, serving primary commercial purpose in neuroinflammatory and autoimmune conditions. Small molecules dominate current pipelines due to established oral bioavailability and blood-brain barrier penetrance, while monoclonal antibodies capture emerging interest for peripheral inflammatory disorders where CNS penetration is unnecessary. Neurology represents the deepest therapy area by trial volume, though immunology segments show faster enrollment acceleration as rheumatoid arthritis and inflammatory bowel disease indications mature.
FDA breakthrough therapy designation and EMA PRIME eligibility reshape competitive timelines by compressing Phase II-to-approval pathways for P2X7 programs targeting rare neurodegenerative diseases. The NIH and the European Innovative Medicines Initiative co-fund academic-industry consortia that de-risk early clinical translation, indirectly steering private R&D allocation. China's NMPA revised clinical trial waivers for innovative CNS drugs, altering market access calculus for multinational sponsors. Stakeholders must monitor biomarker-qualified responder definitions, as payer acceptance hinges on demonstrated enrichment strategies rather than broad population efficacy claims.
Market Dynamics
FDA breakthrough therapy designations and EMA PRIME eligibility compress Phase II-to-approval timelines for P2X7 programs targeting neurodegenerative diseases, fundamentally restructuring competitive positioning around speed-to-market rather than molecule differentiation alone.
Growth Catalysts
- NIH-funded consortia:United States-based research partnerships prioritize P2X7-targeted drug development for Alzheimer's and Parkinson's disease, channeling federal resources toward validated targets and de-risking early clinical translation for private sponsors.
- Injectable formulation demand:Neurology clinics in Germany, Japan, and the United States drive adoption of hospital-administered P2X7 antagonists, creating concentrated prescriber bases that accelerate trial enrollment and post-launch uptake.
- Biomarker platform integration:Responder stratification through integrated diagnostics is reshaping trial design, enabling smaller enriched populations and faster regulatory pathways for neuroinflammatory indications.
Market Restraints
- Blood-brain barrier penetration costs:Small-molecule optimization for CNS penetrance requires extensive medicinal chemistry cycles, elevating preclinical expenditure and extending discovery timelines relative to peripheral-targeted biologics.
- Specialized CRO concentration:Neurodegenerative trial expertise concentrates among a limited set of contract research organizations with validated biomarker networks, creating capacity bottlenecks and inflating service pricing for Phase II programs.
- IL-1β assay standardization gaps:Inconsistent biomarker measurement protocols across academic and commercial laboratories complicate cross-trial comparison and regulatory submission packages.
Strategic Opportunities
- Peripheral immunology expansion:Rheumatoid arthritis and inflammatory bowel disease indications show faster enrollment acceleration than neurology, offering near-term revenue diversification without CNS penetration requirements.
- China NMPA pathway optimization:Revised clinical trial waivers for innovative CNS drugs alter market access calculus, enabling multinational sponsors to leverage local patient pools and accelerated review timelines.
- Fragment-based discovery convergence:Integration of cryo-EM structural biology with high-throughput screening is unifying target validation and lead optimization, compressing early-stage timelines for novel allosteric modulators.
Industry Challenges
- NLRP3 inflammasome pharmacology expertise scarcity:The specialized knowledge required for P2X7-NLRP3 pathway drug development concentrates among a limited pool of academic and industry scientists, constraining team scaling for multiple parallel programs.
- Companion diagnostic co-development complexity:Synchronized validation of biomarker assays with therapeutic candidates demands coordinated regulatory submissions to FDA's Center for Devices and Radiological Health, extending preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | P2X7 Receptor Antagonists Market |
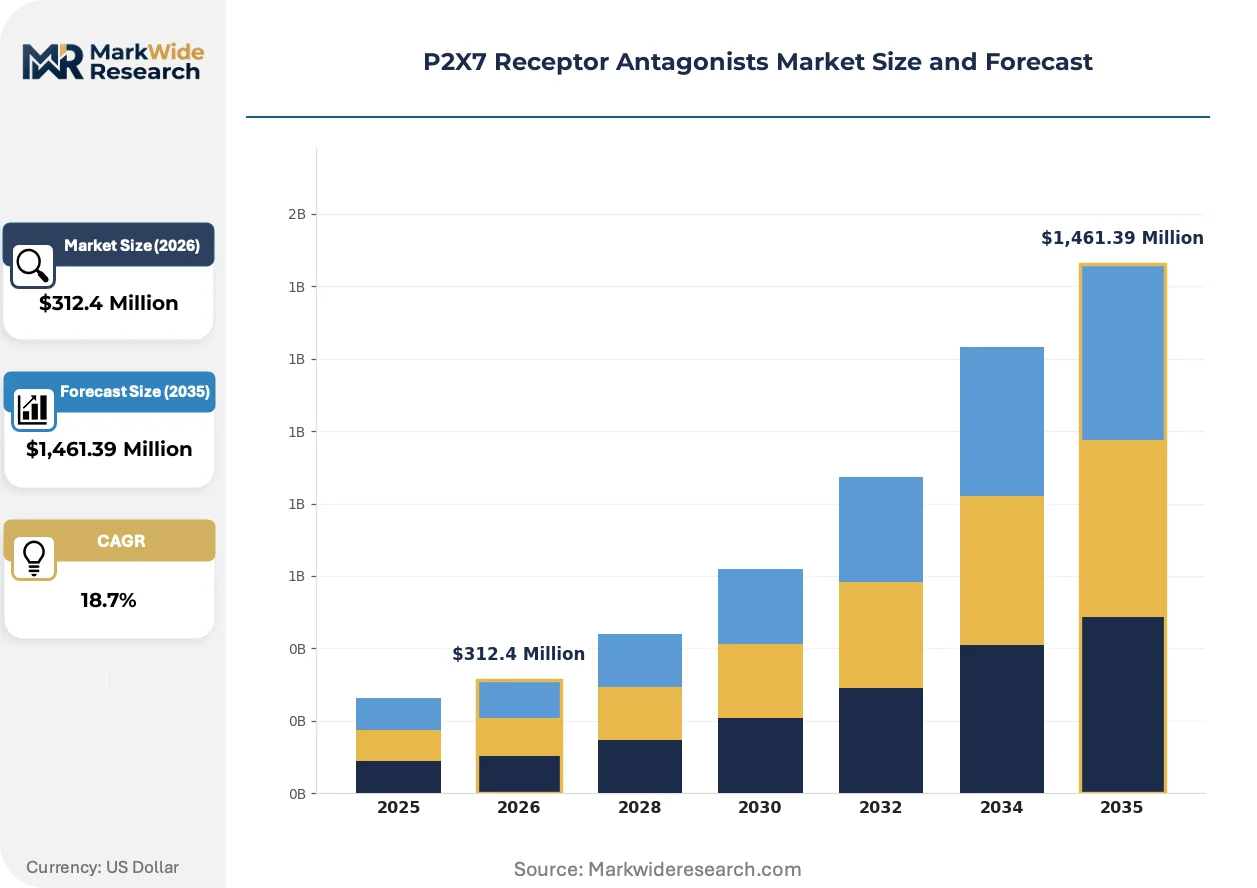
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Peptides, Others Therapy Area: Neurology, Immunology, Oncology, Inflammatory Disorders End User: Hospitals, Research Institutions, Clinics, Pharmaceutical Companies Delivery Mode: Oral, Injectable, Intravenous, Transdermal |
| Companies Covered | Johnson & Johnson, Evotec, Roche, Novartis, UCB, Biosceptre, GlaxoSmithKline, Boehringer Ingelheim, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
P2X7 Receptor Antagonists Market Emerging Trajectories
Discovery and development methodologies for P2X7 antagonists are converging toward integrated platform approaches that compress traditional stage-gate timelines. Three developments are reshaping how candidates advance from target validation to registrational trials.
Cryo-electron microscopy structural determination is unifying fragment screening and lead optimization workflows for allosteric P2X7 modulators. Biotech discovery teams in Boston and Basel now adopt continuous structure-enabled design cycles rather than discrete hit-to-lead handoffs. This methodology is compressing preclinical development timelines by enabling rational polypharmacology management early in optimization.
EMA's PRIME eligibility criteria for neurodegenerative disease programs are accelerating scientific advice engagement and accelerated assessment pathways for P2X7-targeted assets. Sponsors with qualifying data packages now access parallel regulatory dialogue that previously required sequential national consultations. European biotechnology firms are restructuring development organizations around these compressed timelines, prioritizing regulatory strategy hires with prior PRIME qualification experience.
Academic medical centers in the United States are consolidating neuroinflammatory trial networks around standardized CSF biomarker protocols. Site selection criteria now emphasize pre-qualified lumbar puncture capacity and central lab relationships over traditional geographic coverage models. This concentration is visible in NIH-funded Alzheimer's Disease Research Centers, where streamlined biomarker infrastructure enables multi-arm adaptive trial designs that previously required separate standalone studies.
P2X7 Receptor Antagonists Market Segmentation
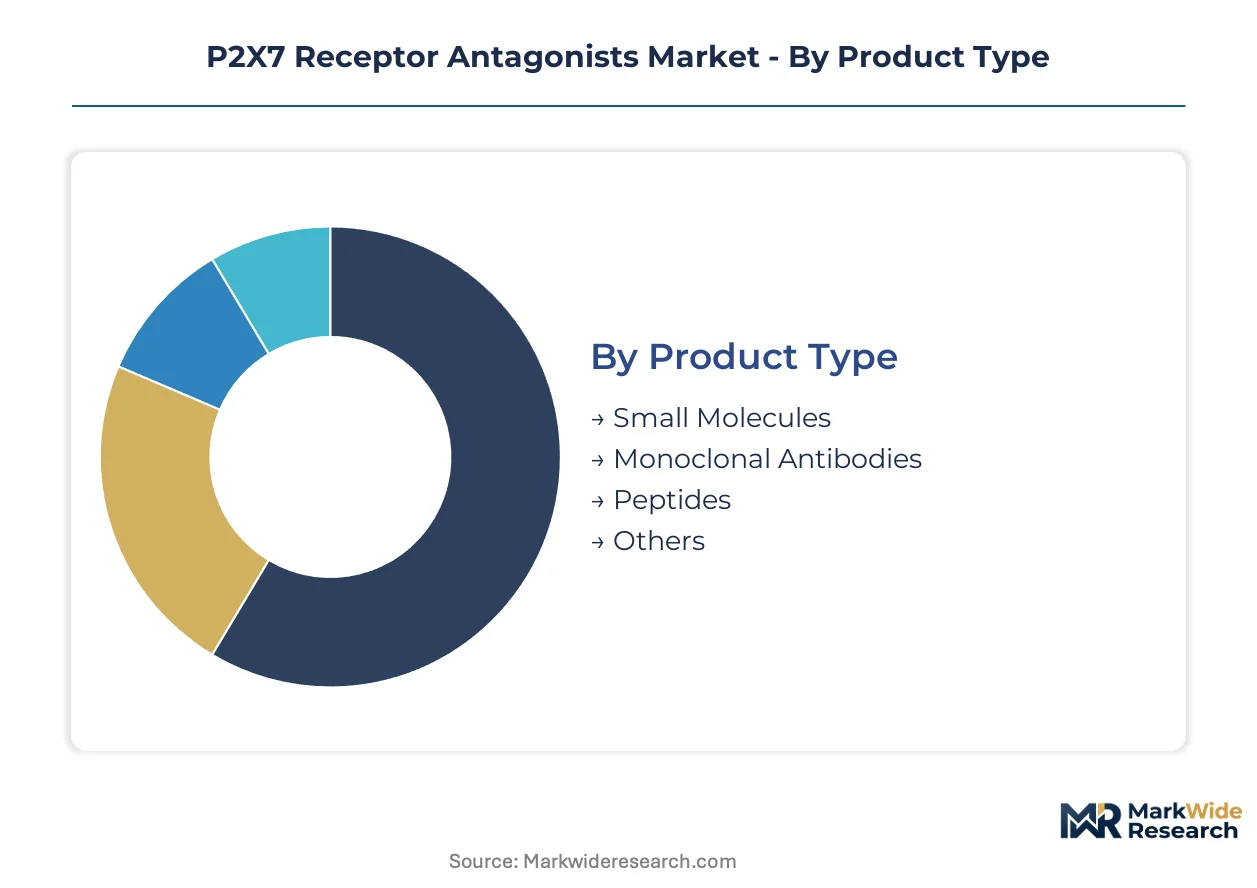
P2X7 receptor antagonist development fragments across molecular architectures and clinical settings, with each segment demanding distinct regulatory, manufacturing, and commercial capabilities. Supply concentration in small-molecule chemistry versus biologics capacity shapes where sponsors allocate capital and which contract partners they engage.
Product Type:
Small-molecule chemistry capacity concentrates among a limited network of CROs with validated blood-brain barrier optimization expertise, while biologics manufacturing gravitates toward distinct geographic clusters with specialized cell-line development capabilities.
- Small Molecules:These compounds achieve nanomolar affinity at orthosteric and allosteric P2X7 binding sites with established oral bioavailability. Neurology programs in the United States and Germany prioritize small-molecule leads for Alzheimer's and Parkinson's indications where CNS penetrance is mandatory. Blood-brain barrier optimization cycles extend discovery timelines and elevate preclinical expenditure relative to peripheral-targeted alternatives.
- Monoclonal Antibodies:Biologic antagonists target peripheral inflammatory disorders where CNS penetration is unnecessary, leveraging standard parenteral delivery. Rheumatoid arthritis and inflammatory bowel disease trials show faster enrollment acceleration than neurology, creating near-term revenue diversification opportunities without CNS penetration requirements.
- Peptides:Mid-sized biologics occupy a narrow niche between small molecules and full antibodies, with limited commercial pipelines in P2X7 targeting.
- Others:Emerging modalities include nucleic acid-based approaches and engineered protein scaffolds still in preclinical validation.
Today's leader: Small Molecules. Tomorrow's challenger: Monoclonal Antibodies.
Therapy Area:
Clinical trial volume and regulatory pathway complexity vary dramatically across therapeutic applications, with neurology commanding the deepest development investment despite slower enrollment curves.
- Neurology:Alzheimer's and Parkinson's disease programs dominate P2X7 trial volume, driven by NIH-funded consortia prioritizing neuroinflammatory targets. FDA breakthrough therapy and EMA PRIME designations compress Phase II-to-approval timelines for qualifying assets. The specialized CRO concentration for neurodegenerative trials creates capacity bottlenecks and inflates service pricing.
- Immunology:Rheumatoid arthritis and inflammatory bowel disease indications are climbing the fastest, with enrollment acceleration outpacing neurology. Peripheral targeting eliminates blood-brain barrier optimization costs, shortening preclinical timelines and reducing medicinal chemistry expenditure.
- Oncology:Tumor microenvironment modulation through P2X7 blockade remains exploratory, with limited validated biomarker strategies.
- Inflammatory Disorders:Broader autoimmune applications beyond rheumatology are emerging, though clinical validation lags immunology's core indications.
Neurology retains development depth; immunology is gaining share fastest.
End User:
Site selection criteria and procurement authority concentrate demand among institutional actors with specialized infrastructure and centralized purchasing.
- Hospitals:Injectable formulation demand concentrates in neurology clinics across Germany, Japan, and the United States. Hospital-administered P2X7 antagonists require validated biomarker networks and lumbar puncture capacity, favoring academic medical centers with NIH-funded Alzheimer's Disease Research Centers.
- Research Institutions:Academic-industry consortia co-funded by the NIH and European Innovative Medicines Initiative de-risk early clinical translation. Standardized CSF biomarker protocols and central lab relationships enable multi-arm adaptive trial designs.
- Clinics:Outpatient settings favor oral formulations with simpler logistics, though neurology specialization requirements limit addressable prescriber bases.
- Pharmaceutical Companies:Internal R&D and in-licensing decisions concentrate among firms with established neurology franchises and integrated biomarker platforms.
Hospitals anchor near-term revenue; research institutions shape pipeline composition.
Delivery Mode:
Formulation technology and administration setting determine competitive differentiation, with oral bioavailability and CNS penetrance representing distinct optimization challenges.
- Oral:Small-molecule P2X7 antagonists with validated blood-brain barrier penetrance enable outpatient administration for chronic neurodegenerative conditions. Medicinal chemistry cycles for CNS optimization elevate discovery costs relative to peripheral indications.
- Injectable:Hospital-administered formulations dominate current neurology adoption, with concentrated prescriber bases in Germany, Japan, and the United States accelerating both trial enrollment and post-launch uptake.
- Intravenous:Continuous infusion capabilities are limited to specialized centers, constraining addressable patient populations for acute neuroinflammatory indications.
- Transdermal:Skin penetration of P2X7-targeted compounds remains technically challenging, with no validated commercial pathways.
Injectable formulations dominate current adoption; oral candidates are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's neurology clinics outpace Japan in P2X7 antagonist trial enrollment density, while the United States concentrates the largest share of NIH-funded neuroinflammatory research consortia. Regulatory pathway compression through FDA breakthrough therapy and EMA PRIME designations is redrawing competitive timelines across all three markets.
United States
NIH-funded Alzheimer's Disease Research Centers in Boston and San Francisco anchor the deepest P2X7 clinical trial infrastructure globally. FDA breakthrough therapy designation compresses Phase II-to-approval timelines for neurodegenerative indications. The Greater Boston biotech cluster houses the highest concentration of fragment-based discovery platforms targeting allosteric P2X7 modulators.
Germany
Neurology clinics in Munich and Heidelberg drive concentrated demand for injectable P2X7 antagonist formulations in hospital settings. EMA PRIME eligibility accelerates scientific advice engagement for sponsors with qualifying neurodegenerative data packages. The Rhine-Main biopharma corridor integrates biomarker-qualified responder stratification into adaptive trial designs.
Japan
PMDA consultations for innovative CNS drugs are compressing review timelines for P2X7 programs targeting Parkinson's disease. METI-funded academic-industry partnerships de-risk early clinical translation for domestic biotech sponsors. The Kansai region's Osaka-Kobe medical cluster concentrates specialized CRO capacity for neuroinflammatory biomarker networks.
China
NMPA revised clinical trial waivers for innovative CNS drugs are altering market access calculus for multinational P2X7 sponsors. The Yangtze River Delta's Shanghai-Suzhou biotech corridor is consolidating cryo-EM structural biology capacity for target validation. Local patient pools enable accelerated enrollment for peripheral immunology indications.
Switzerland
Swissmedic's parallel scientific advice pathways align with EMA PRIME timelines for neurodegenerative P2X7 assets. Basel's pharmaceutical cluster anchors integrated biomarker platform development for responder population stratification. The country's contract manufacturing network specializes in small-molecule blood-brain barrier optimization chemistry.
P2X7 Receptor Antagonists Market Vendor Landscape
Top-tier vendors anchor integrated neurology franchises and biomarker platforms, while mid-tier discovery specialists occupy fragment-based and early-stage candidate generation niches. The competitive structure stratifies across three archetypes: large-cap pharmaceutical incumbents with regulatory acceleration experience, biotech discovery platforms with structural biology integration, and specialized CRO networks with validated neuroinflammatory biomarker infrastructure. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic licensing to access NMPA-accelerated pathways in China.
Within the large-cap pharmaceutical tier, Johnson & Johnson and Roche exemplify archetypes built on neurology franchise depth and integrated diagnostic platforms respectively. Evotec occupies a position as the representative discovery specialist, anchoring fragment-based lead optimization for allosteric modulator programs. These three entities collectively illustrate how competitive positioning in P2X7 antagonists depends on regulatory acceleration capabilities and biomarker integration rather than molecule differentiation alone.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Evotec |
| Roche |
| Novartis |
| UCB |
| Biosceptre |
| GlaxoSmithKline |
| Boehringer Ingelheim |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
Cryo-electron microscopy structural determination is compressing discovery timelines while simultaneously concentrating specialized chemistry capacity among CROs with validated blood-brain barrier optimization expertise, reshaping both cost economics and supplier bargaining power across the P2X7 antagonist value chain.
Pricing Analysis
Capacity additions in Switzerland and Germany are reshaping price floors for small-molecule blood-brain barrier optimization services. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FDA breakthrough therapy-qualified programs commanding premium tiers. Cost compression in standard-tier medicinal chemistry is intensifying because CRO network expansion outpaces demand growth. Academic medical centers with NIH-funded consortia exhibit lowest price sensitivity due to federal subsidy coverage, while emerging biotechs without consortium access face highest procurement pressure.
Supply Chain Analysis
Dual-sourcing requirements for critical IL-1β assay reagents are mandating multi-supplier qualification across academic and commercial laboratories. Manufacturing concentrates in Switzerland, Germany, and the United States for small-molecule active pharmaceutical ingredients, while biologics cell-line development clusters in South Korea and Japan. Raw material dependencies include fluorinated intermediates, specialized chromatography resins, and cryo-EM grid substrates. Single-source vulnerability runs through Swiss-based blood-brain barrier chemistry CROs with decades of accumulated optimization expertise. Distribution feeds from contract manufacturing organizations through centralized warehousing to hospital pharmacy consortia and academic medical center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The P2X7 receptor antagonists market operates as a stable compounder, with NIH-funded neuroinflammatory research consortia providing sustained federal resource allocation that de-risks development timelines across multiple therapeutic programs.
For Market Incumbents: Hedge against fragment-based discovery platform disruption by acquiring structural biology integration capabilities in Boston or Basel clusters. Prioritize backward integration into companion diagnostic assay development to capture outcome-based licensing revenue streams. Defensive patent landscaping around allosteric modulator binding sites preserves exclusivity runway as competitor pipelines mature. For New Entrants and Emerging Players: Begin with peripheral immunology indications in rheumatoid arthritis and inflammatory bowel disease, where enrollment acceleration outpaces neurology and blood-brain barrier optimization costs are eliminated. China's NMPA-accelerated pathways offer the most penetrable regulatory geography for multinational market access. A go-to-market angle anchored in biomarker-qualified responder stratification enables premium positioning without broad population efficacy requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biotechs with validated P2X7 lead compounds lacking regulatory acceleration designations. Long-term viability centers on platform durability across neurodegenerative and autoimmune expansion indications. Acquisition target archetype: firms with EMA PRIME-qualified assets and integrated biomarker discovery capabilities. The signal to watch is FDA breakthrough therapy designation announcements for neurodegenerative programs, which compress Phase II-to-approval timelines and revalue development-stage assets.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Acceleration Pathway | FDA breakthrough therapy designation compresses Phase II-to-approval timelines for Alzheimer's programs. |
| Biomarker Platform Integration | Responder stratification through CSF protocols enables smaller enriched trial populations at NIH-funded centers. |
| Geographic Licensing Agreement | NMPA pathway partnerships in China leverage local patient pools for peripheral immunology indications. |
| Companion Diagnostic Co-development | Synchronized assay validation with therapeutic candidates secures outcome-based reimbursement contracts. |
| Fragment-based Discovery Expansion | Cryo-EM structural biology integration compresses lead optimization cycles for allosteric modulators. |
Methodological Framework
Bottom-up hospital and research institution demand modeling reconciled against top-down CRO capacity and NIH funding allocation tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up and top-down triangulation identifies capacity-demand mismatches in blood-brain barrier optimization chemistry.
Input-output matrices map therapy area demand drivers through molecular architecture segments to derive volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, delivery mode, and regional regulatory cluster. CAGRs were derived from enrollment velocity differentials between neurology and immunology indications, adjusted for FDA and EMA acceleration pathway qualification rates. Industry-specific forecast inputs incorporate biomarker protocol standardization timelines and CRO capacity utilization rates.
Several conditions sit outside the modeled scope, including pipeline failures at Phase IIb, regulatory rejection of companion diagnostic submissions, and geopolitical restrictions on cryo-EM equipment exports. Forecasts reflect assumptions around continued NIH consortium funding stability and EMA PRIME eligibility criteria consistency. Deviation in FDA breakthrough therapy designation grant rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Antidiuretic Drugs Market