
 Prescription Lens Market | 2026-2036
Prescription Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Lens Market Intelligence
EU MDR is recalibrating the cost-of-entry calculus for lens manufacturers seeking European market access. EssilorLuxottica leverages its captive retail network to sustain margin capture across the value chain. Hoya Corporation anchors its position through deep specialization in high-index materials and myopia-control designs. Carl Zeiss AG differentiates via precision free-form technology leadership in customized progressive surfaces.
Prescription lenses are ophthalmic devices ground to individualized dioptric specifications, typically fabricated from organic polymers such as polycarbonate or Trivex with Abbe values between 30 and 45, designed to correct refractive errors including myopia, hyperopia, astigmatism, and presbyopia. Progressive lenses now command the dominant value share as aging populations in developed economies drive multifocal replacement cycles. High-index materials represent the fastest-expanding material category, with 1.67 and 1.74 index substrates displacing standard CR-39 in mid-to-premium dispensing channels where thickness reduction justifies price premiums.
FDA ophthalmic device regulations, EU MDR conformity requirements, and ISO 8980 series standards collectively govern optical performance tolerances, biocompatibility testing, and labeling claims across major markets. These frameworks elevate compliance burdens for smaller laboratories while creating structural advantages for manufacturers with established quality-management systems and notified-body relationships. Stakeholders must monitor evolving digital-health integrations, as connected lenses and embedded sensors trigger reclassification debates that could reshape competitive boundaries and partnership requirements.
Market Dynamics
Free-form digital surfacing is compressing production cycles and eroding the cost advantage of conventional polishing equipment, forcing mid-tier laboratories to absorb capital write-downs or exit fabrication entirely.
Growth Catalysts
- Myopia management protocols:Pediatric ophthalmology programs in China now mandate specialized single-vision and progressive designs for school-age patients, accelerating replacement frequency among the 6-18 demographic.
- EU MDR harmonization:The Medical Device Regulation streamlines conformity assessment across 27 member states, reducing redundant testing burdens for lens manufacturers with established quality-management systems.
- High-index material substitution:1.67 and 1.74 index polymers are displacing CR-39 in premium dispensing channels where thickness reduction commands measurable price premiums.
Market Restraints
- Monomer cost volatility:Thiourethane and allyl diglycol carbonate feedstock prices fluctuate with petrochemical indices, squeezing margin predictability for independent laboratories.
- Coating supply concentration:Anti-reflective and photochromic layer deposition equipment relies on German and Japanese vacuum-chamber manufacturers, creating single-source vulnerability.
- Abbe value trade-offs:High-index materials exhibit dispersion coefficients below 32, producing chromatic aberration that limits adoption in precision optical applications.
Strategic Opportunities
- Rural China penetration:County-level vision-care chains remain underserved by free-form surfacing capacity, presenting first-mover advantage for equipment-leasing models.
- Connected lens sensors:Integration of intraocular pressure monitoring and glucose-sensing hydrogels positions prescription lenses as FDA Class II diagnostic platforms.
- Direct-to-consumer refraction:Telehealth-enabled prescription renewal bypasses traditional optometry channels, capturing replacement cycles from price-sensitive wearers.
Industry Challenges
- Free-form technician scarcity:Digital surface modeling and 5-axis CNC programming skills concentrate among German and Japanese equipment specialists, inflating recruitment costs for expanding laboratories.
- ISO 8980-1 certification timelines:Optical power tolerance testing and biocompatibility documentation extend product launch windows by 8-14 months for novel substrate formulations.
- Legacy edger integration:Blockless surfacing workflows require retrofitting or replacing rimless and semi-rimless mounting equipment, straining capital allocation for mid-scale dispensers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Lens Market |
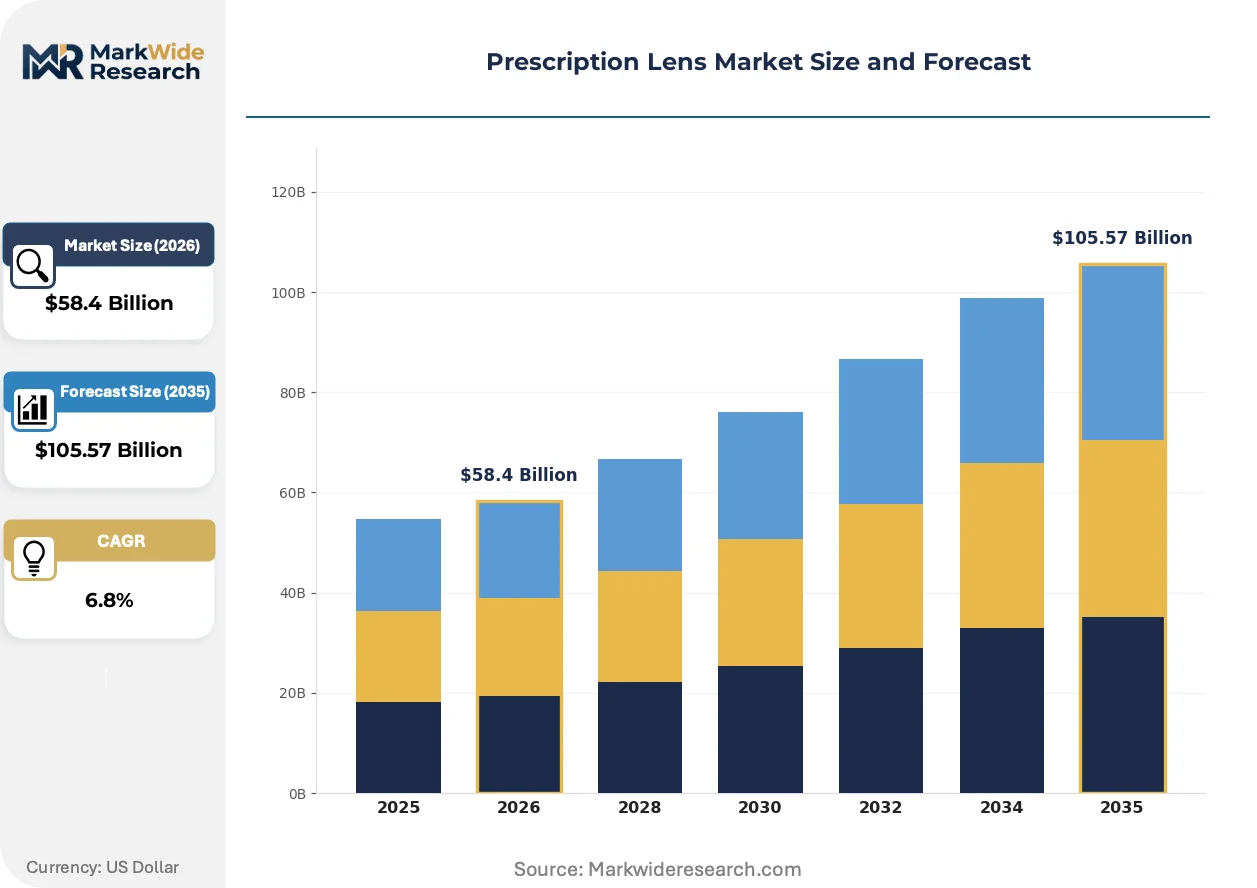
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lens Type: Single Vision, Bifocal, Trifocal, Progressive Material: Polycarbonate, High Index, Glass, Trivex Coating: Anti-Reflective, Scratch-Resistant, Blue Light Blocking, Photochromic Usage: Everyday Wear, Sports, Safety, Fashion |
| Companies Covered | Johnson & Johnson Vision, Seiko Optical Products, EssilorLuxottica, Bausch & Lomb Inc, Shamir Optical Industry Ltd., Hoya Corporation, Rodenstock GmbH, Alcon, Inc., Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Lens Market Strategic Shifts & Innovations
Digital manufacturing workflows are redefining competitive advantage across the value chain, compressing lead times while elevating customization depth beyond what conventional tooling permits.
Free-form digital surfacing is overtaking conventional polishing methods in progressive lens fabrication. Independent laboratories and retail-integrated manufacturing centers adopt 5-axis CNC generators equipped with sub-micron accuracy feedback loops. This technology is overtaking legacy equipment by enabling point-by-point surface optimization that reduces peripheral aberration without manual polishing stages.
EU MDR recalibration is elevating conformity assessment stringency for customized ophthalmic devices. Manufacturers must maintain notified-body relationships and updated technical documentation across all substrate categories. High-index and photochromic lens portfolios face heightened scrutiny in Germany and France, where competent authorities prioritize post-market surveillance of refractive stability claims.
Urban vision-care chains in China are compressing replacement cycles through subscription-based lens replacement programs. School-screening mandates generate predictable demand streams that bypass traditional optometry gatekeepers. This behavioral shift concentrates procurement power among three national retail networks, forcing independent laboratories to accept volume-based pricing schedules or exit the pediatric segment entirely.
Prescription Lens Market Segmentation
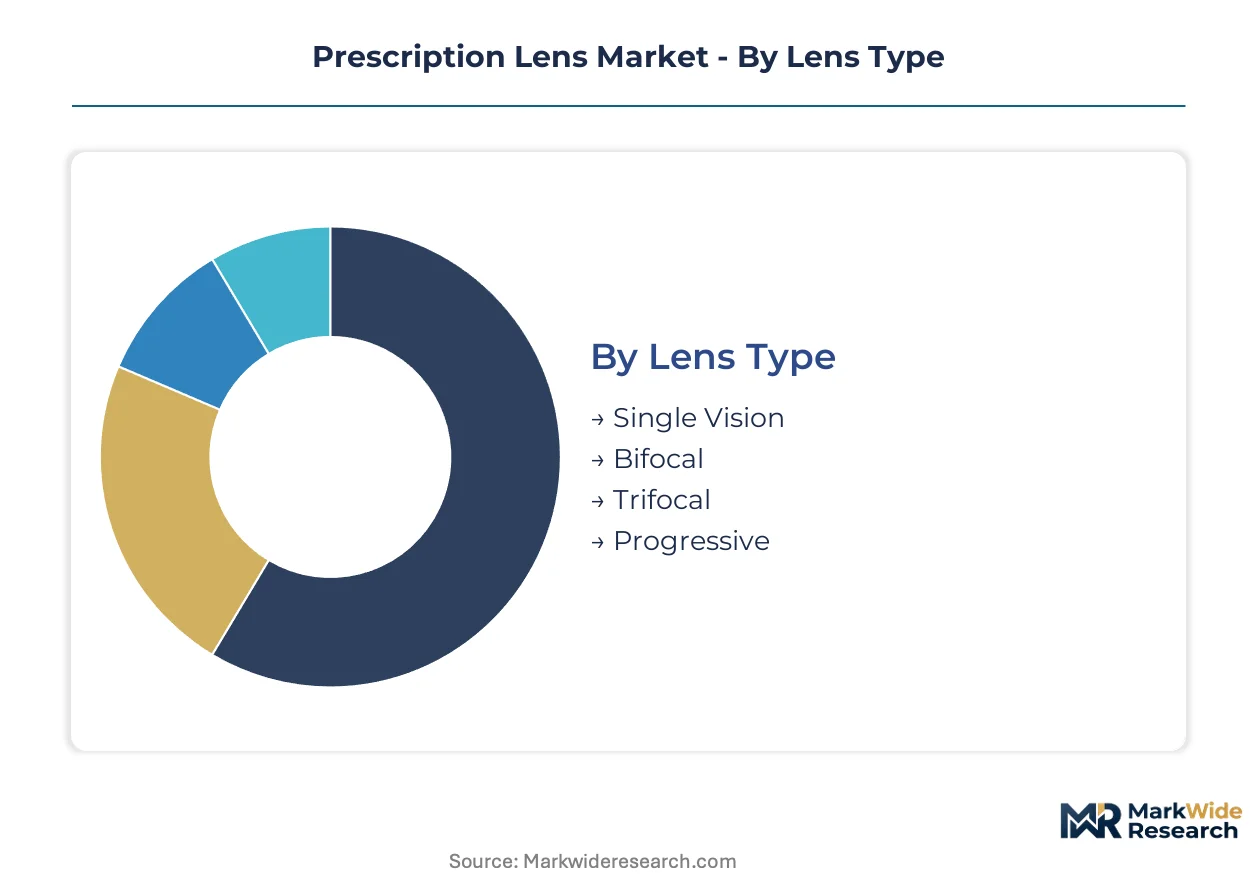
Prescription lens segmentation reveals how regulatory pathways, material science advances, and end-use specialization fragment manufacturing requirements. Each dimension carries distinct certification burdens, capital intensity thresholds, and margin profiles that shape competitive positioning across the value chain.
Lens Type:
FDA Class I designation covers most single-vision and bifocal lenses, while progressive and certain specialized designs trigger EU MDR heightened scrutiny requiring notified-body intervention.
- Single Vision:Uniform dioptric power across the entire optical surface, typically prescribed for myopia or hyperopia correction. Demand concentrates in China's pediatric screening programs where government mandates accelerate replacement cycles among school-age populations.
- Progressive:Gradual power variation from distance to near zones without visible segmentation lines, fabricated through free-form digital surfacing. Aging demographics in Germany and Japan drive multifocal replacement cycles as presbyopia incidence rises among workers delaying retirement.
- Bifocal:Two distinct optical zones separated by a visible segment line, with near-vision portion ground to specific add power. Occupational safety regulators in France and Italy mandate this design for specific manufacturing environments.
- Trifocal:Three power zones accommodating intermediate vision alongside distance and near correction. Niche adoption persists among precision machinists and pilots requiring dedicated intermediate focal lengths.
Single Vision sits at the top of the volume ranking, with Progressive climbing the fastest.
Material:
Cost tiers stratify sharply around index values, with 1.50 standard substrates occupying economy channels while 1.67 and 1.74 formulations command premium positioning.
- Polycarbonate:Thermoplastic polymer with inherent impact resistance and 1.59 refractive index, widely specified for pediatric and safety applications. US sports eyewear manufacturers specify this substrate for ASTM F803 compliance in racket and ball sports.
- High Index:Thiourethane-based polymers at 1.67 and 1.74 indices enabling significant thickness reduction in strong prescriptions. Japanese optical chains and German premium dispensers drive substitution away from CR-39 as frame fashion prioritizes minimal edge profile.
- Glass:Mineral substrates with superior optical clarity and scratch resistance but substantial weight penalty. Precision optical laboratories in Switzerland and laboratory settings retain demand for applications demanding maximum Abbe value performance.
- Trivex:PPG-developed urethane-based material combining impact resistance with low density and 1.53 index. Tactical and military procurement specifications in the US favor this substrate for ballistic eyewear requirements.
Polycarbonate dominates unit volume through safety mandates, while High Index gains share fastest in premium dispensing channels.
Coating:
Application-specific performance requirements determine deposition technology selection, with vacuum-chamber equipment concentration in Germany and Japan creating supply vulnerability.
- Anti-Reflective:Multi-layer interference coatings reducing surface reflections below 1% through magnesium fluoride and metal oxide stacks. Night driving and computer workstation users in South Korea and the Netherlands drive specification rates above 80% in premium channels.
- Scratch-Resistant:Hardcoat layers of silicon dioxide or organic-inorganic hybrids protecting softer substrates. Mandatory for polycarbonate and high-index materials where base polymer hardness falls below pencil hardness 4H.
- Blue Light Blocking:Selective absorption or reflection in 400-450nm range targeting digital device emission spectra. Corporate wellness programs in US technology sector and Japanese office workers accelerate adoption despite ongoing clinical efficacy debates.
- Photochromic:Silver halide or naphthopyran molecules enabling reversible darkening under UV exposure. Transitions Optical's chemistry dominates dispensing through exclusive retail partnerships, though Hoya and Zeiss maintain competing formulations.
Anti-Reflective leads volume through near-universal premium channel specification, with Blue Light Blocking expanding most quickly among digital-native demographics.
Usage:
Customer type and risk exposure determine testing protocols, with safety and sports applications triggering ANSI Z87.1 and EN 166 certification requirements absent from everyday wear.
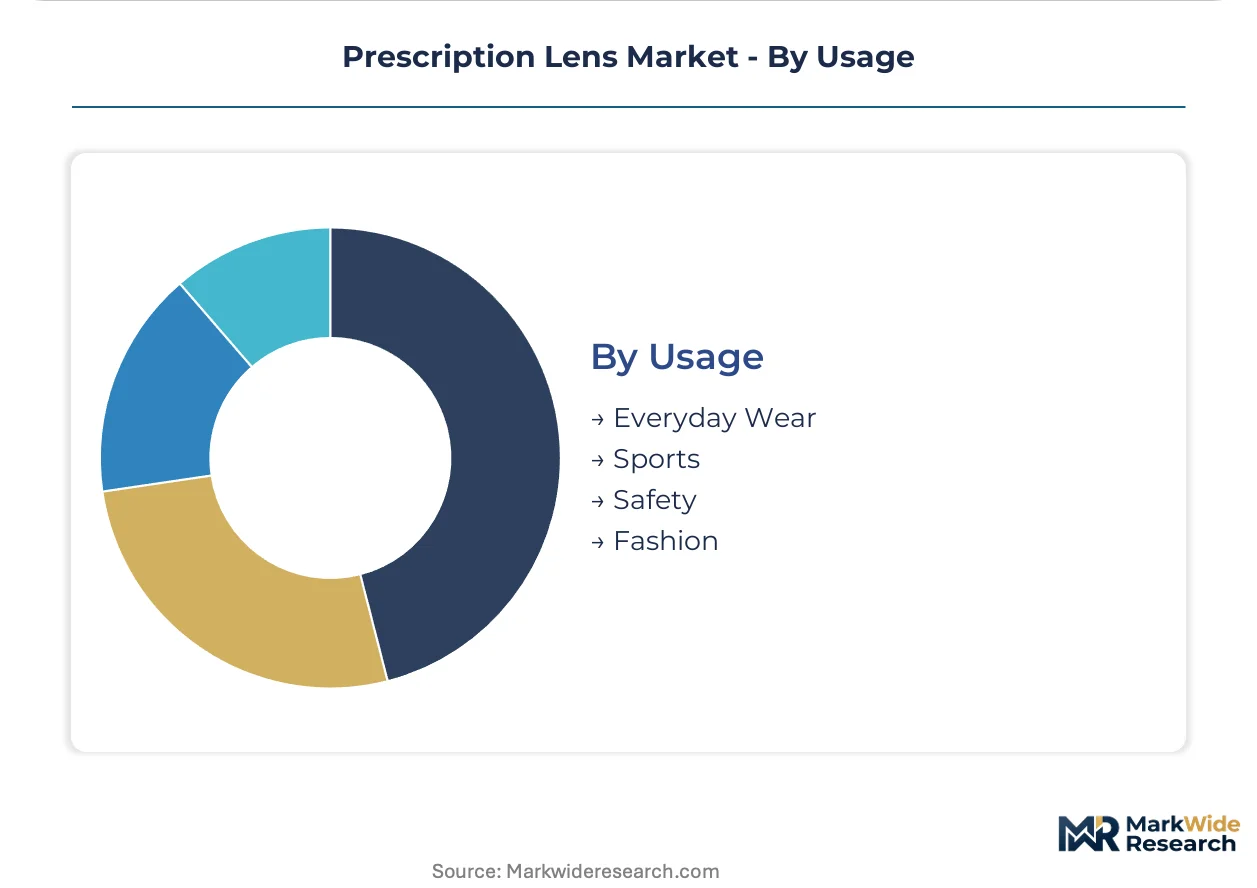
- Everyday Wear:General-purpose correction for occupational and social activities, representing the baseline application for all substrate and design categories. Replacement frequency varies by geography, with China's urban chains compressing cycles through subscription models.
- Sports:Impact-optimized designs with wraparound frame compatibility and enhanced peripheral optics. US collegiate athletic programs and European cycling federations specify polycarbonate or Trivex with polarized options.
- Safety:Occupational lenses meeting ANSI Z87.1, EN 166, or CSA Z94.3 standards for impact and chemical splash resistance. Manufacturing and construction employers in Germany and Texas mandate prescription safety eyewear through workers' compensation protocols.
- Fashion:Plano or minimally-corrected lenses prioritizing aesthetic frame presentation over optical performance. Luxury optical retail in Milan and Seoul drives demand for clear lens options in non-prescription sunglasses frames.
Everyday Wear captures the highest unit volume, with Safety climbing fastest through regulatory expansion into service sector occupations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical manufacturing talent clusters in Germany, Japan, and China anchor the industry's geographic footprint, with precision engineering skills concentrating around Stuttgart, Osaka, and Shanghai.
China
Urban vision-care chains in Shanghai and Beijing compress replacement cycles through subscription-based pediatric programs. Government school-screening mandates under the National Health Commission generate predictable demand streams for myopia-management designs. Danyang in Jiangsu Province hosts the densest concentration of lens surfacing laboratories, where free-form equipment adoption outpaces inland provinces.
Germany
Precision optics engineers in Baden-Württemberg and Bavaria sustain leadership in free-form surface modeling software. EU MDR notified-body relationships concentrate in Berlin and Munich, elevating compliance burdens for foreign entrants. The Stuttgart metropolitan area anchors Zeiss and Rodenstock manufacturing footprints, with Oberkochen serving as a precision glass and polymer research cluster.
United States
FDA Class I and Class II ophthalmic device approvals drive regulatory strategy for laboratories serving the Medicare-reimbursed presbyopia segment. Dallas and Phoenix host major free-form surfacing facilities supplying independent optometry chains. Military and tactical procurement specifications favor Trivex and polycarbonate substrates from PPG and independent fabricators in the Southeast.
Japan
High-index thiourethane formulation expertise concentrates in Tokyo and Osaka, where Hoya Corporation and Seiko Optical anchor material science R&D. METI industrial standards for optical tolerances exceed ISO baselines, creating export quality premiums. The Higashiosaka cluster specializes in anti-reflective coating deposition equipment, supplying vacuum chambers to German and Chinese laboratories.
France
EssilorLuxottica's captive retail integration radiates from Charenton-le-Pont, controlling procurement flows across European dispensing channels. ANSM post-market surveillance prioritizes refractive stability claims for photochromic and progressive portfolios. The Lyon optical cluster maintains specialty glass lens fabrication for precision industrial applications abandoned by mass-market polymer producers.
Prescription Lens Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The vendor base stratifies around three structural archetypes: integrated retail-laboratory hybrids controlling end-to-end value chains, independent surfacing specialists serving regional optometry networks, and material-science laboratories supplying substrate formulations to downstream fabricators. Competitive moves center on free-form equipment leasing partnerships in underserved county-level markets and M&A activity targeting coating deposition technology.
Among integrated retail-laboratory hybrids, EssilorLuxottica and Hoya Corporation exemplify the captive-channel archetype, leveraging vertical control over dispensing networks to sustain margin capture. Carl Zeiss AG occupies a position within the precision-technology tier, anchoring free-form surface optimization capabilities. These three entities represent divergent strategic postures: retail integration versus material specialization versus precision engineering leadership.
| Leading Market Players |
|---|
| Johnson & Johnson Vision |
| Seiko Optical Products |
| EssilorLuxottica |
| Bausch & Lomb Inc |
| Shamir Optical Industry Ltd. |
| Hoya Corporation |
| Rodenstock GmbH |
| Alcon, Inc. |
| Carl Zeiss AG |
| Others |
Cost & Logistics Intelligence
Free-form digital surfacing compresses production cycles while concentrating fabrication capacity among laboratories equipped with 5-axis CNC generators, simultaneously lowering per-unit processing costs and elevating capital barriers that filter mid-tier competitors from premium dispensing channels. This technological transition rewards scale operators with procurement leverage over monomer suppliers and coating deposition equipment manufacturers while forcing smaller laboratories into volume-based pricing schedules or segment exit.
Pricing Analysis
Bundled lens-and-coating packages dominate premium dispensing channels while unbundled substrate-only transactions persist in economy segments. Three-tier pricing structure across premium, standard, and economy levels separates free-form progressive designs from conventional single-vision and basic CR-39 offerings. Price differentiation hinges on certification grade—ISO 8980-1 compliance commands measurable premiums—and customization depth. Cost compression in standard-index substrates is intensifying because Chinese urban chains negotiate volume-based procurement contracts. Pediatric screening programs in China exhibit lowest price sensitivity due to government reimbursement, while independent rural dispensers face acute margin pressure.
Supply Chain Analysis
Direct-to-retail laboratory networks handle hyperscale demand from China's three national vision-care chains, while independent fabricators serve regional optometry through distributor intermediaries. Geographic supply concentration centers on China, Germany, and Japan, where Danyang hosts surfacing clusters, Stuttgart anchors free-form software development, and Osaka specializes in thiourethane monomer formulation. Raw material dependencies include allyl diglycol carbonate feedstocks, thiourethane resins, and vacuum-chamber coating equipment. Single-source vulnerability concentrates in German and Japanese anti-reflective deposition machinery. Distribution runs through EssilorLuxottica's captive retail integration and Hoya's direct laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in high-index material substitution and myopia-management program participation, where free-form fabrication capabilities and pediatric dispensing relationships command sustainable premiums.
For Market Incumbents: Extend free-form equipment leasing partnerships into China's underserved county-level markets before regional competitors consolidate surfacing capacity. Deepen backward integration into thiourethane monomer formulation to offset petrochemical price volatility squeezing margin predictability. Prioritize notified-body relationship maintenance under EU MDR recalibration to defend European market access against smaller laboratories facing compliance burden escalation. For New Entrants and Emerging Players: Enter via telehealth-enabled prescription renewal platforms targeting price-sensitive wearers bypassing traditional optometry gatekeepers. Target rural China penetration through equipment-leasing models addressing free-form surfacing scarcity at county-level vision-care chains. Pursue direct-to-consumer refraction partnerships with digital health platforms as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among independent surfacing specialists lacking captive retail integration but possessing ISO 8980-1 certification and established coating deposition workflows. Long-term viability over the projection horizon favors laboratories with backward integration into high-index monomer supply or forward integration into pediatric dispensing networks. Monitor EU MDR reclassification debates around connected lens sensors as the critical inflection indicator for diagnostic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Free-Form Equipment Leasing | Enables laboratory expansion in China's county-level markets without capital-intensive ownership. |
| Myopia Management Program Enrollment | Captures recurring replacement cycles from government-mandated pediatric screening in China. |
| Notified-Body Relationship Investment | Secures EU MDR conformity assessment pathways for progressive and photochromic portfolios. |
| High-Index Monomer Backward Integration | Reduces exposure to thiourethane feedstock volatility from petrochemical indices. |
| Connected Lens Sensor Development | Positions prescription lenses for FDA Class II diagnostic platform reclassification. |
Research Approach
Bottom-up optometry channel modeling reconciled against top-down lens fabrication capacity tracking forms the analytical core of this study. Primary interviews with surfacing laboratory managers, ophthalmic equipment specialists, pediatric optometrists, and vision-care retail procurement directors combined with secondary validation from FDA 510(k) filings, EU MDR notified-body documentation, ISO 8980-1 certification records, and Chinese National Health Commission screening program disclosures. This approach triangulates demand-side replacement frequency data against supply-side free-form equipment installation rates.
Input-output matrices map substrate category volumes through coating application rates and dispensing channel margins across the modeling period. Segmentation dimensions include lens type, material index tier, coating functionality, and end-use application. CAGRs derive from regression analysis of historical replacement cycles projected against demographic aging trajectories and myopia prevalence trends. Industry-specific forecast inputs incorporate free-form equipment adoption curves and EU MDR compliance timeline assumptions.
The model holds under stable regulatory classification for prescription lenses as Class I/II devices; deviation in FDA or EU MDR reclassification toward diagnostic platforms would shift competitive boundaries and partnership requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Treatment Pumps Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Implantable Collamer Lens Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Software As a Medical Device Market
Medical Devices
Toe Fixation System Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Global Medical Drones Market
Medical Devices
Global Medical Suction Devices Market