
 Iron Deficiency Injectables Market | 2026-2036
Iron Deficiency Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Deficiency Injectables Market Intelligence
India is tilting toward expanded injectable iron capacity as domestic manufacturers respond to government procurement mandates for anemia treatment programs. Pharmacosmos A/S leverages its carbohydrate-complex expertise to sustain premium positioning in European nephrology channels. Fresenius Kabi AG anchors hospital supply contracts through integrated dialysis-therapy bundling across multiple continents.
Iron deficiency injectables comprise parenteral iron formulations—typically colloidal iron-carbohydrate complexes with particle sizes between 5 and 30 nanometers—administered intravenously or subcutaneously to replenish ferritin stores when oral supplementation fails or is contraindicated. Ferric carboxymaltose dominates hospital formularies due to rapid high-dose infusion capability and lower anaphylaxis risk versus iron dextran legacy products. Oncology therapy areas generate concentrated demand as chemotherapy-induced anemia drives routine IV iron co-administration in infusion centers.
The FDA maintains strict boxed warnings on dextran-containing products, while the EMA's PRAC periodically reviews hypersensitivity signals across the parenteral iron class, directly shaping prescriber confidence and product substitution patterns. India's CDSCO has accelerated biosimilar-equivalence pathways for complex iron formulations under its revised biologics guidance. Stakeholders must monitor evolving pharmacovigilance databases to anticipate regulatory label changes that could reorder competitive standing among carbohydrate-complex platforms.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while simultaneously demanding larger-volume, longer-term supply contracts for parenteral iron formulations. This structural force is virtualizing competitive positioning around carbohydrate-complex manufacturing scale and pharmacovigilance data depth rather than brand heritage alone.
Growth Catalysts
- FDA Boxed Warning Differentiation:The FDA's maintained boxed warnings on iron dextran formulations create prescriber preference for ferric carboxymaltose and iron sucrose alternatives in US infusion centers.
- Oncology Infusion Center Expansion:Chemotherapy-induced anemia protocols at major cancer treatment networks now mandate IV iron co-administration, embedding parenteral iron into standard-of-care pathways.
- German Nephrology Protocol Leadership:Dialysis clinics across Bavaria and North Rhine-Westphalia have adopted ferric carboxymaltose as first-line therapy, creating template adoption patterns for neighboring EU markets.
Market Restraints
- Carbohydrate Complex Supply Concentration:Maltodextrin and oxidized maltose raw material supply chains concentrate in Chinese chemical manufacturing clusters, exposing formulators to input cost volatility and geopolitical friction.
- EMA PRAC Signal Review Cycles:The European Medicines Agency's periodic safety signal reviews for hypersensitivity reactions across all parenteral iron classes create regulatory friction that delays label expansions and new indication approvals.
- Subcutaneous Iron Replacement Substitution:Novel erythropoiesis-stimulating agents and HIF-PH inhibitors in late-stage development threaten to displace IV iron in select chronic kidney disease patient segments.
Strategic Opportunities
- India's Anemia Treatment Mandate:The country's national anemia reduction program under the Ministry of Health creates procurement volume tailwinds for domestic injectable iron manufacturers with CDSCO manufacturing licenses.
- Subcutaneous Ferric Derisomaltose Formulation:Next-generation iron carbohydrate complexes enabling subcutaneous administration open home-infusion and self-administration channels previously closed to hospital-centric IV products.
- Integrated Dialysis-Therapy Bundling:Nephrology service providers are consolidating pharmaceutical procurement under single-source contracts, rewarding suppliers with captive manufacturing and direct distribution capabilities.
Industry Challenges
- Pharmacovigilance Data Science Talent Scarcity:Post-market surveillance requirements for hypersensitivity signal detection demand specialized biostatisticians and real-world evidence analysts that contract manufacturers struggle to recruit.
- Complex Generic Bioequivalence Pathways:India's CDSCO revised guidance for iron-carbohydrate complex biosimilar equivalence requires extensive immunogenicity studies that extend development timelines and capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Deficiency Injectables Market |
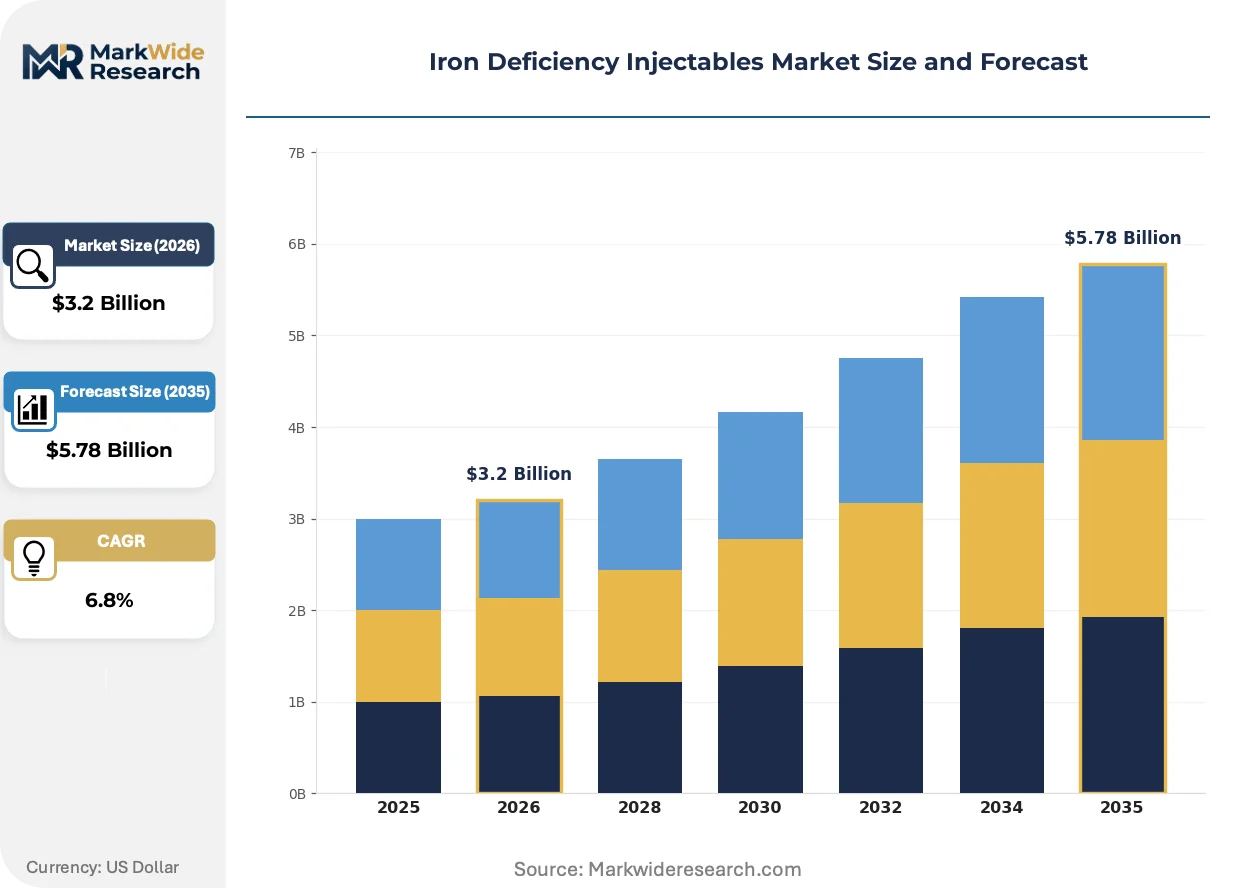
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Sucrose, Ferric Carboxymaltose, Iron Dextran, Sodium Ferric Gluconate Therapy Area: Oncology, Gastroenterology, Nephrology, Obstetrics Formulation: Injection, Intravenous, Subcutaneous, Infusion End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Daiichi Sankyo Company Limited, AbbVie Inc., American Regent Inc., Pharmacosmos A/S, Fresenius Kabi AG, CSL Vifor, Pfizer Inc., Bayer AG, Rockwell Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Deficiency Injectables Market Strategic Shifts & Innovations
Carbohydrate engineering and administration modality innovation are compressing the traditional hospital-centric delivery model for parenteral iron. These shifts are virtualizing where and how iron deficiency therapy reaches patients.
Particle engineering advances in ferric carboxymaltose manufacturing are reducing mean particle size distributions toward the 5-nanometer threshold. Nephrology and oncology infusion centers in Germany and the United States are adopting these refined formulations for rapid high-dose protocols. This technology is virtualizing site-of-care requirements by enabling shorter chair times and same-day discharge.
The EMA's PRAC has intensified post-authorization safety study requirements for all new parenteral iron marketing authorizations following hypersensitivity signal accumulation. Formulators must now commit to multi-year patient registries as a condition of approval. European nephrology clinics are responding by consolidating purchases around established products with mature safety databases rather than novel entrants.
Hospital procurement departments are unbundling pharmaceutical sourcing from medical device and dialysis service contracts that previously bundled parenteral iron. Independent infusion centers and physician office laboratories are capturing volume previously locked within hospital outpatient departments. This pattern is most visible in the United States, where site-neutral payment policies accelerate channel fragmentation.
Iron Deficiency Injectables Market Segmentation
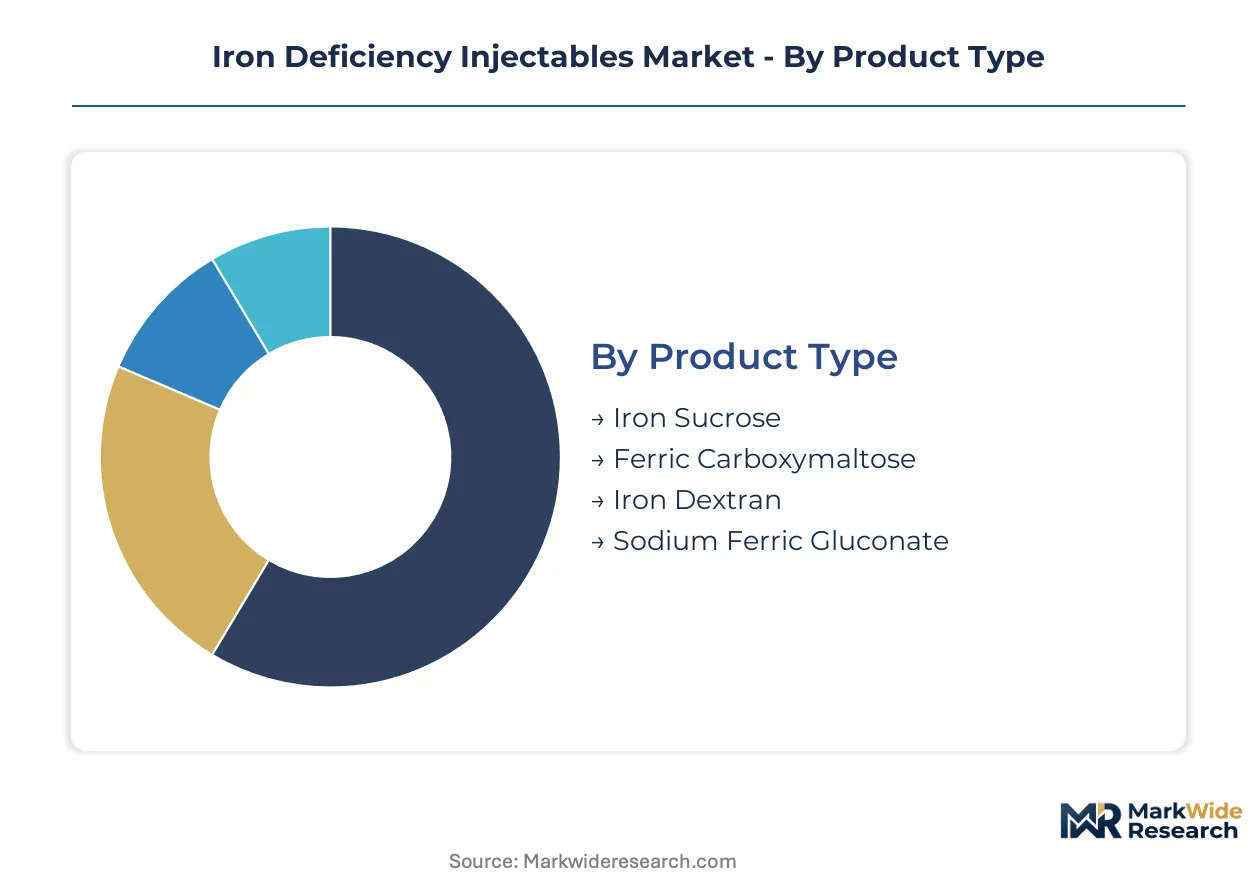
Parenteral iron formulations fragment across carbohydrate-complex chemistry, therapy specialization, and site-of-care delivery. Procurement officers and clinical pharmacists navigate these dimensions simultaneously when building formularies.
Product Type:
After-sales pharmacovigilance intensity varies sharply across iron-carbohydrate platforms, with newer complexes demanding more intensive hypersensitivity monitoring than legacy formulations.
- Ferric Carboxymaltose:A dextran-free iron carbohydrate complex with a molecular weight of approximately 150 kDa enables rapid high-dose infusion protocols. German nephrology clinics in Bavaria have adopted this formulation as first-line therapy for dialysis patients, displacing iron dextran due to superior safety profiles and shorter chair times.
- Iron Sucrose:A colloidal iron oxide sucrose complex administered via slower infusion protocols requiring multiple doses for equivalent iron repletion. US oncology infusion centers favor this established platform for chemotherapy-induced anemia where cumulative safety data supports routine co-administration with cytotoxic agents.
- Iron Dextran:High molecular weight dextran-complexed iron carries FDA boxed warnings for anaphylaxis risk.
- Sodium Ferric Gluconate:A lower molecular weight complex suited for patients with documented hypersensitivity to dextran-containing products.
By volume, iron sucrose leads hospital procurement globally. By growth pace, ferric carboxymaltose is expanding most quickly as nephrology protocols shift toward rapid-infusion platforms.
Therapy Area:
Clinical protocol standardization across therapy areas creates divergent volume concentration and margin profiles for parenteral iron suppliers.
- Nephrology:Dialysis-dependent chronic kidney disease generates the largest addressable patient population for IV iron replacement. Fresenius Kabi AG and independent dialysis operators in Germany, Italy, and Spain have consolidated procurement under bundled therapy contracts that lock in multi-year supply commitments.
- Oncology:Chemotherapy-induced anemia protocols at major cancer networks now mandate IV iron co-administration. Memorial Sloan Kettering and MD Anderson have embedded ferric carboxymaltose into standard-of-care pathways, creating institutional preference that propagates to affiliated community oncology practices.
- Gastroenterology:Inflammatory bowel disease and celiac disease patients with malabsorption drive demand in infusion centers.
- Obstetrics:Postpartum hemorrhage and antenatal anemia protocols generate concentrated demand in maternity hospital systems.
Nephrology captures the highest absolute volume. Oncology delivers the steepest expansion trajectory as infusion center networks proliferate.
Formulation:
Administration modality determines site-of-care economics and patient throughput capacity for iron replacement programs.
- Intravenous:Direct venous administration of iron-carbohydrate complexes dominates hospital outpatient departments and infusion centers. The 15-60 minute infusion protocols enable same-day discharge and high patient turnover in German and US nephrology clinics.
- Infusion:Extended-duration parenteral iron delivery accommodates higher single-dose iron repletion in supervised clinical settings.
- Subcutaneous:Novel ferric derisomaltose formulations under development target home-infusion and self-administration channels.
- Injection:Bolus intramuscular delivery persists in resource-constrained settings with limited infusion infrastructure.
Intravenous administration commands current volume leadership. Subcutaneous platforms are gaining share fastest as manufacturers invest in home-care delivery infrastructure.
End User:
Procurement consolidation patterns and reimbursement mechanics create distinct competitive dynamics across delivery settings.
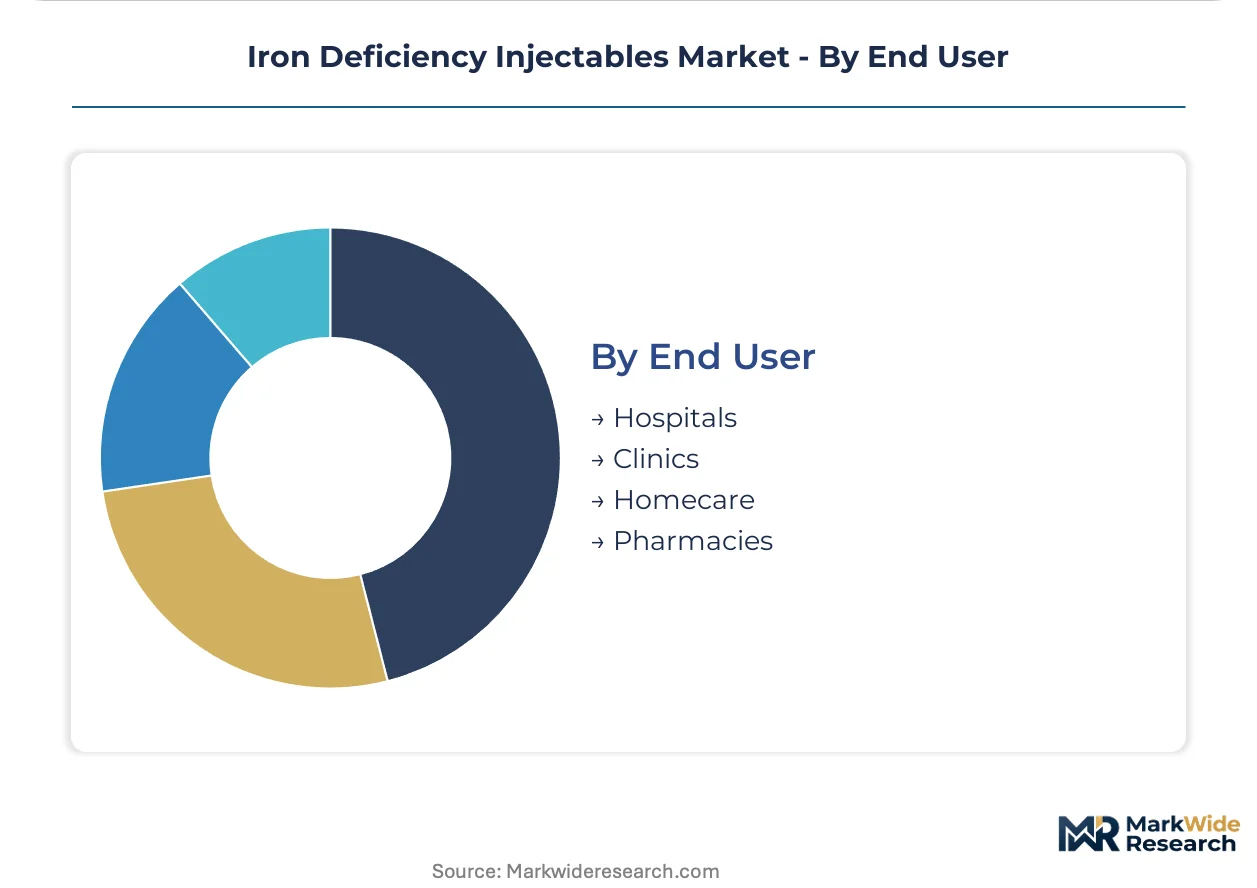
- Hospitals:Integrated health systems leverage GPO-negotiated contracts for parenteral iron across inpatient and outpatient settings. Hospital procurement departments in the United States are unbundling pharmaceutical sourcing from device and service contracts, creating independent RFP processes for iron-carbohydrate complexes.
- Clinics:Independent nephrology and oncology practices capture volume migrating from hospital outpatient departments under site-neutral payment policies. US Medicare reimbursement parity accelerates this channel fragmentation.
- Homecare:Subcutaneous formulation advances enable delivery outside traditional clinical settings.
- Pharmacies:Specialty pharmacy dispensing of parenteral iron remains limited by cold chain and administration supervision requirements.
Hospitals retain volume dominance. Clinics are climbing the fastest as site-neutral payment policies accelerate channel shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's pharmaceutical cold-chain infrastructure anchors Central European distribution for parenteral iron formulations, while Singapore's Changi Airport freight hub enables Asia-Pacific transshipment of temperature-sensitive carbohydrate complexes.
United States
Oncology infusion centers at Memorial Sloan Kettering and MD Anderson drive concentrated demand for ferric carboxymaltose protocols. The FDA maintains boxed warnings on iron dextran formulations, creating prescriber preference for alternative carbohydrate complexes. Boston's Longwood Medical Area anchors nephrology research clusters advancing rapid-infusion safety data.
Germany
Dialysis clinics across Bavaria and North Rhine-Westphalia have adopted ferric carboxymaltose as first-line therapy for dialysis-dependent patients. The EMA's PRAC periodically reviews hypersensitivity signals across parenteral iron classes, shaping prescriber confidence. Frankfurt's pharmaceutical logistics corridor consolidates European distribution for carbohydrate-complex formulations.
India
Government procurement mandates under the national anemia reduction program generate volume tailwinds for domestic manufacturers. The CDSCO has accelerated biosimilar-equivalence pathways for complex iron formulations under revised biologics guidance. Hyderabad's vaccine and injectables manufacturing cluster expands capacity for parenteral iron production.
Japan
Aging demographics and rising chronic kidney disease prevalence expand nephrology service demand in Kanto and Kansai regions. The PMDA maintains stringent post-market surveillance requirements for hypersensitivity signal detection. Osaka's pharmaceutical formulation corridor specializes in particle-engineered carbohydrate complexes for rapid infusion.
Australia
Hospital outpatient departments in New South Wales and Victoria unbundle pharmaceutical sourcing from device contracts, creating independent procurement channels for parenteral iron. The TGA aligns safety monitoring with EMA signal review cycles. Melbourne's biomedical research precinct advances real-world evidence collection for iron replacement therapy.
Iron Deficiency Injectables Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying carbohydrate-complex raw materials and finished formulations. The market structures around three tiers: multinational pharmaceutical conglomerates with nephrology and oncology portfolios, mid-cap injectable specialists with carbohydrate-engineering capabilities, and regional contract manufacturers serving government procurement programs. Consolidation pressures favor players with integrated dialysis-therapy bundling and direct hospital supply contracts. Competitive positioning hardens around pharmacovigilance data depth and manufacturing scale rather than brand heritage alone.
Among European-based specialists, Pharmacosmos A/S and Fresenius Kabi AG exemplify contrasting archetypes within the parenteral iron segment. Pharmacosmos occupies a position as a carbohydrate-complex engineering specialist with concentrated European nephrology channel presence. Fresenius Kabi represents the integrated dialysis-therapy platform, leveraging captive distribution through affiliated clinical service networks. Daiichi Sankyo Company Limited anchors the Asia-Pacific originator tier, with Japanese manufacturing heritage supporting regulatory positioning across multiple geographies. These three entities collectively illustrate how competitive advantage fragments across technical specialization, vertical service integration, and geographic regulatory footprint.
| Leading Market Players |
|---|
| Daiichi Sankyo Company Limited |
| AbbVie Inc. |
| American Regent Inc. |
| Pharmacosmos A/S |
| Fresenius Kabi AG |
| CSL Vifor |
| Pfizer Inc. |
| Bayer AG |
| Rockwell Medical Inc. |
| Others |
Cost & Logistics Intelligence
Hyderabad's vaccine and injectables manufacturing cluster anchors global capacity for parenteral iron formulations, with its expansion dynamics directly compressing margins for European and North American suppliers unable to match its government-backed scale economics.
Pricing Analysis
Volume-discount tiering structures separate hospital GPO-negotiated contracts from independent clinic procurement and government tender awards. Pricing stratifies across premium, standard, and economy tiers based on pharmacovigilance database maturity and manufacturing scale. Cost compression in the economy tier is intensifying because Indian domestic manufacturers exploit CDSCO fast-track pathways to undercut established carbohydrate-complex platforms. Government procurement officers exhibit highest price sensitivity; nephrology bundled-therapy providers show lowest.
Supply Chain Analysis
Extended payment terms from German hospital systems and supply-chain finance facilities anchored by Frankfurt's pharmaceutical logistics corridor sustain working capital for carbohydrate-complex formulators. Maltodextrin and oxidized maltose raw material supply chains concentrate in Chinese chemical manufacturing clusters, India, and select European specialty chemical producers. Single-source vulnerability in Chinese maltodextrin feedstocks exposes formulators to input cost volatility. Distribution runs through hospital GPOs, independent infusion center networks, and government procurement depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HIF-PH inhibitors and novel erythropoiesis-stimulating agents threaten to displace IV iron in chronic kidney disease segments, forcing incumbents to defend substitution risk through pharmacovigilance data depth and administration modality innovation.
For Market Incumbents: Build pharmacovigilance data moats by committing to multi-year patient registries as EMA PRAC conditions demand. Capture backward integration into maltodextrin carbohydrate engineering to neutralize Chinese supply concentration risk. Anchor hospital supply contracts through integrated dialysis-therapy bundling before channel fragmentation accelerates.
For New Entrants and Emerging Players: Pursue subcutaneous ferric derisomaltose formulation development to unlock home-infusion channels closed to hospital-centric IV incumbents. Target India's national anemia reduction program procurement mandates as the most penetrable volume opportunity. Lead with CDSCO manufacturing license acquisition as the essential go-to-market credential.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated dialysis-therapy platforms with captive distribution through affiliated clinical service networks. Long-term viability favors carbohydrate-complex engineering specialists with established European nephrology channel presence over commodity contract manufacturers. Monitor EMA PRAC hypersensitivity signal review outcomes as the critical inflection indicator for competitive standing reordering.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacovigilance Database Expansion | Multi-year patient registries satisfy EMA PRAC approval conditions and lock in prescriber confidence. |
| Carbohydrate Engineering Scale-Up | Particle size refinement toward 5-nanometer thresholds enables rapid high-dose infusion protocols in German clinics. |
| Subcutaneous Formulation Development | Home-infusion capability opens channels previously restricted to hospital outpatient departments. |
| Integrated Dialysis-Therapy Bundling | Single-source contracts with Fresenius Kabi AG and independent operators lock in multi-year supply commitments. |
| CDSCO Manufacturing License Acquisition | Indian regulatory credential unlocks government procurement mandates under national anemia reduction programs. |
Research Approach
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases preceded structured interviews with nephrology clinic directors, hospital procurement managers, regulatory affairs leads, and carbohydrate-complex manufacturing specialists. Primary intelligence combined with secondary validation through GPO contract databases and CMS Medicare utilization data. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation anchored value estimates.
Assumption sets held regulatory approval timelines and reimbursement parity conditions fixed while varying HIF-PH inhibitor substitution penetration and Indian domestic manufacturing capacity buildout rates across the projection horizon. Segmentation modeling spanned carbohydrate-complex chemistry, therapy area specialization, administration modality, and site-of-care delivery setting. CAGRs derived from patient population epidemiology, protocol penetration curves, and pricing trajectory synthesis. Forecast inputs incorporated dialysis center expansion pipelines and oncology infusion center network proliferation.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, currency volatility affecting API import costs, or trade friction in Chinese chemical feedstocks would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and substitution technology timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Cryptococcosis Therapeutics Market