
 Global in-Flight Voice Recognition Market | 2026-2036
Global in-Flight Voice Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Global in-Flight Voice Recognition Market Analysis
Software-defined feature licensing is restructuring how avionics suppliers monetize in-flight voice recognition, shifting hardware-centric contracts toward recurring revenue models. Honeywell International Inc leverages its integrated flight deck ecosystem to bundle voice command modules with existing avionics suites. Collins Aerospace sustains technology leadership through deep R&D investment in noise-canceling microphone arrays optimized for cabin acoustics. Thales Group anchors its position in European airline retrofit programs by specializing in multilingual natural language processing engines.
In-flight voice recognition encompasses airborne speech interfaces that convert crew or passenger vocal commands into machine-executable instructions, typically operating at signal-to-noise ratios exceeding 20 dB in pressurized cabin environments with 70-85 dB ambient sound levels. The primary commercial purpose is hands-free control of avionics, entertainment, and environmental systems to reduce pilot workload and improve passenger experience. Software solutions command the strongest margin pools as airlines prioritize cloud-updatable language models over static embedded firmware. Machine learning segments are expanding fastest as carriers demand adaptive accent recognition for international route networks. Control systems remain the most mature category, with hardware commoditization pressuring suppliers toward service-based differentiation.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements shape product development timelines by mandating redundant speech recognition pathways for safety-critical applications. The EU AI Act introduces algorithmic transparency obligations for automated decision-making systems deployed on European-registered aircraft, compelling vendors to document training data provenance. Stakeholders must monitor evolving cybersecurity mandates from ICAO and national regulators as voice biometrics become integral to crew authentication protocols.
Market Dynamics
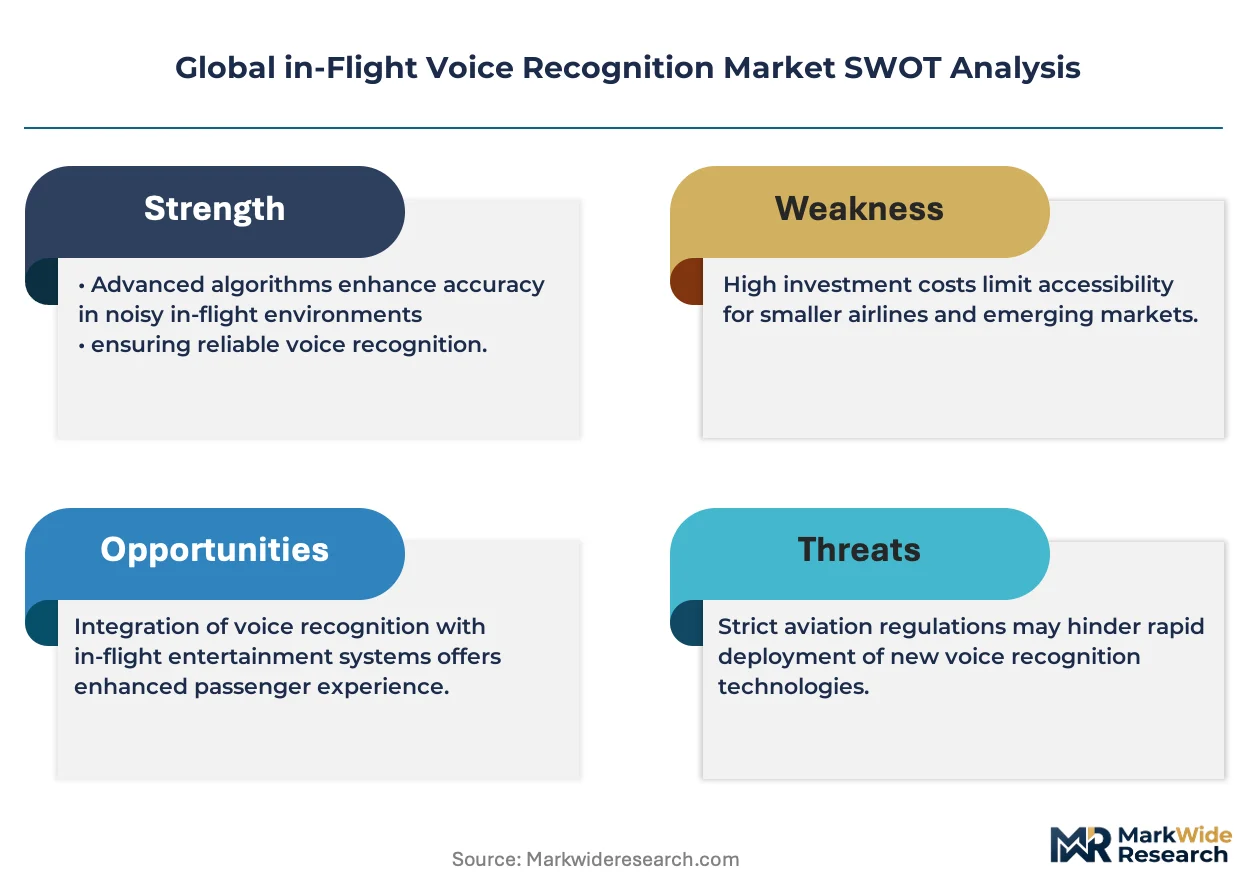
FAA Part 25 certification requirements for redundant speech recognition pathways are compressing product development timelines while simultaneously elevating barriers to entry for safety-critical avionics applications.
Growth Catalysts
- FAA Speech Recognition Mandates:Tightening accuracy standards for cockpit voice systems are forcing carriers to upgrade legacy installations, creating replacement demand across narrow-body and wide-body fleets.
- Machine Learning Accent Adaptation:Adaptive language models trained on international route networks are reducing command misinterpretation rates, expanding carrier willingness to deploy voice control on transcontinental services.
- United States Fleet Retrofit Concentration:Major US carriers are accelerating narrow-body modernization programs, concentrating near-term demand in North American installation and certification channels.
Market Restraints
- Avionics-Grade Microphone Cost Volatility:Precision noise-canceling arrays using rare-earth magnet components face input cost pressure from concentrated Chinese rare earth processing.
- EASA Certification Timeline Friction:The EU AI Act's algorithmic transparency obligations are extending documentation requirements for European-registered aircraft, delaying deployment schedules.
- Touchscreen Interface Substitution:Mature capacitive flight deck displays continue capturing budget-conscious retrofit segments where voice recognition premiums face procurement scrutiny.
Strategic Opportunities
- India Domestic Fleet Expansion:Low penetration of voice-enabled crew communication systems in Indian carriers' rapidly growing narrow-body orders represents uncaptured white space for multilingual NLP engines.
- Cybersecurity-Integrated Voice Biometrics:ICAO's evolving crew authentication protocols are converging voice recognition with identity verification, opening adjacent service revenue streams.
- Cloud-Updatable Firmware Licensing:Airlines are migrating from static embedded systems to subscription-based language model updates, restructuring supplier monetization toward recurring revenue architectures.
Industry Challenges
- Acoustic Engineer Talent Scarcity:Specialized expertise in cabin noise suppression algorithm design remains concentrated among defense-aerospace crossover professionals, constraining vendor scaling.
- Legacy Avionics Bus Integration Complexity:ARINC 429 and MIL-STD-1553 protocol translation requirements are extending system integration timelines for retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in-Flight Voice Recognition Market |
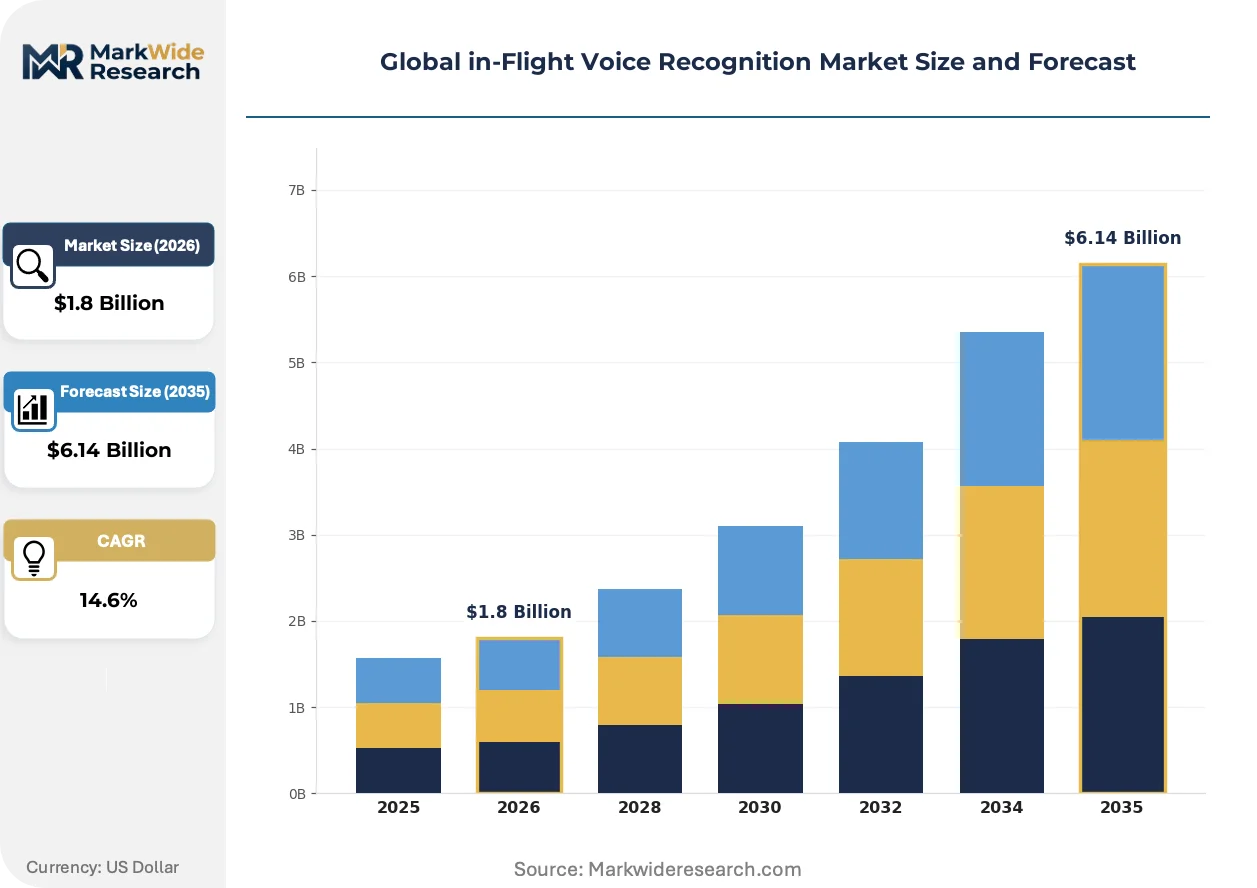
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Microphones, Control Systems, Software Solutions Technology: Natural Language Processing, Machine Learning, Speech Analytics, Voice Command End User: Aerospace Manufacturers, Airlines, Cabin Crew, Passengers Application: Customer Service, Crew Communication, Safety Protocols, Entertainment Systems |
| Companies Covered | Honeywell International Inc, Collins Aerospace, Thales Group, Panasonic Avionics, Nuance Communications, Airbus S.A.S., Raytheon Technologies Corporation, Safran Cabin, VoiceFlight Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in-Flight Voice Recognition Market Emerging Trajectories
Speech interface architectures are fragmenting into composable software layers that separate acoustic processing from command interpretation, enabling faster certification cycles and vendor specialization.
Edge-deployed neural inference engines are modularizing previously monolithic voice recognition stacks into discrete acoustic front-end, language understanding, and command execution modules. Regional carriers with mixed fleet ages are adopting this architecture most aggressively, compressing hardware refresh cycles from seven years toward three-year software-defined upgrade intervals. The separation of microphone array hardware from cloud-updatable language models is modularizing supplier relationships and eroding traditional avionics suite bundling power.
The EU AI Act's automated decision-making transparency requirements are mandating documented training data provenance for European-registered aircraft. Vendors must now maintain auditable supply chains for accent and noise-condition datasets used in safety-critical speech models. Narrow-body retrofit programs serving EU routes face the steepest compliance burden, with some carriers delaying deployment until certification pathways clarify.
Airline technical procurement teams are unbundling voice recognition from full flight deck upgrade contracts, issuing standalone RFPs for crew communication modules. MRO channels and specialized avionics integrators are displacing OEM-direct relationships in the retrofit segment, particularly among low-cost carriers with insourced engineering capabilities. This pattern is most pronounced in the United States, where FAA-certified repair stations have captured increasing share of narrow-body modification programs.
Global in-Flight Voice Recognition Market Segmentation
Voice recognition deployment in aviation requires segment-specific certification pathways. FAA Part 25 airworthiness standards impose redundant validation requirements on safety-critical applications, while passenger-facing systems navigate lighter compliance burdens.
Product Type:
FAA and EASA certification intensity varies sharply across hardware versus software segments, with safety-critical installations demanding dual-pathway redundancy documentation.
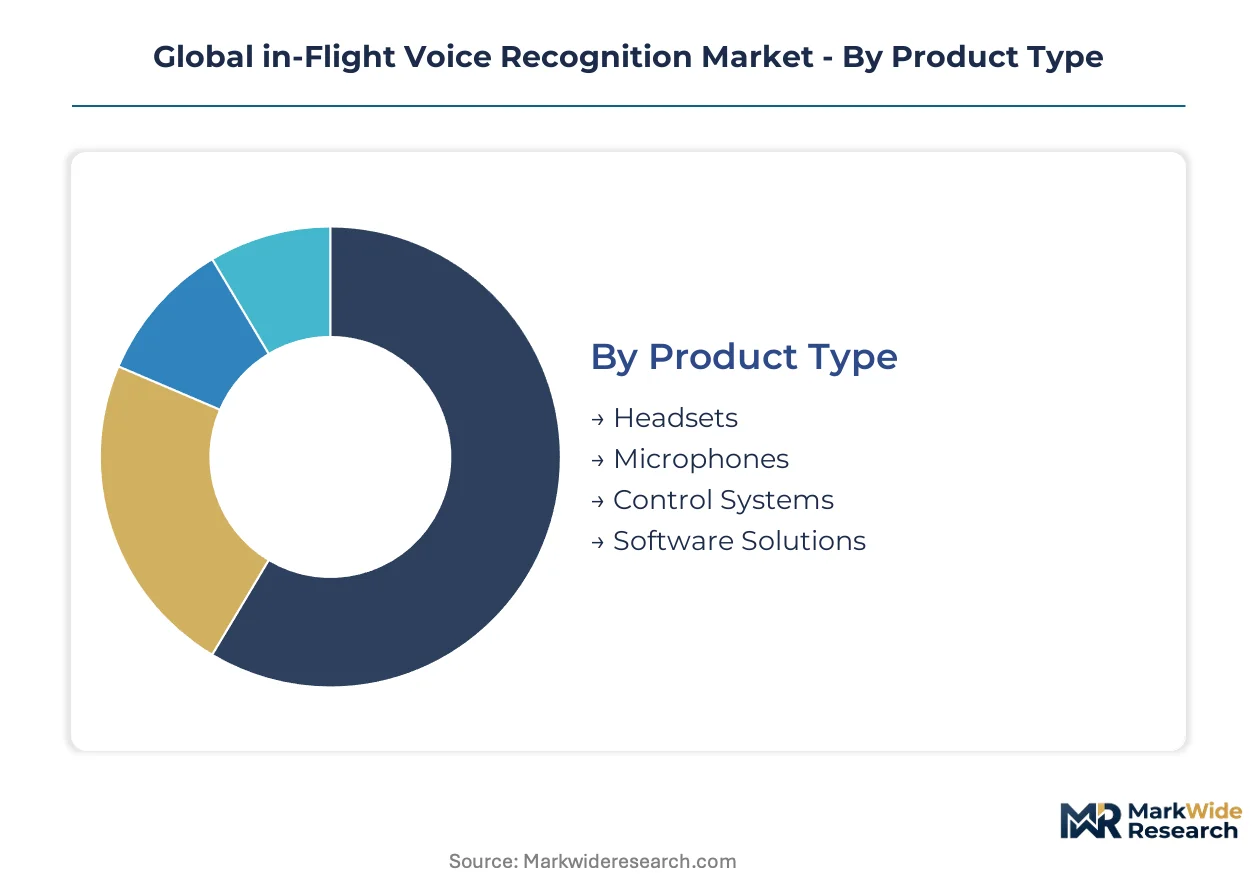
- Software Solutions:Cloud-updatable language models enable continuous accent adaptation without hardware recertification. Airlines prioritize these for international route networks where command misinterpretation risks escalate. Recurring licensing revenue is restructuring supplier relationships away from one-time avionics suite sales.
- Control Systems:Mature ARINC 429 and MIL-STD-1553 protocol interfaces dominate flight deck integration. Hardware commoditization pressures margins, pushing vendors toward service-based differentiation and firmware subscription models.
- Microphones:Precision noise-canceling arrays using rare-earth magnet components face input cost volatility from concentrated Chinese processing.
- Headsets:Crew-worn devices integrate acoustic processing with push-to-talk backup mechanisms for redundancy compliance.
Control Systems sits at the top of the volume ranking, with Software Solutions climbing the fastest.
Technology:
Development cost tiers separate established signal processing from emerging neural architectures, with machine learning segments commanding premium R&D investment.
- Machine Learning:Adaptive accent recognition models trained on international route data reduce command error rates in multicultural crew environments. Carriers deploy these most aggressively on transcontinental services where static language models fail.
- Natural Language Processing:Multilingual engines enable single-system deployment across diverse route networks, reducing fleet configuration complexity for global carriers.
- Voice Command:Template-based instruction recognition remains the cost-efficient default for narrow-body retrofit programs with constrained budgets.
- Speech Analytics:Post-flight crew communication analysis supports training and incident investigation workflows.
Voice Command maintains the largest installed base, while Machine Learning gains share fastest.
End User:
Procurement authority concentration shapes vendor access, with airline technical teams increasingly unbundling voice modules from full flight deck contracts.
- Airlines:Fleet-wide standardization drives volume procurement of integrated voice control platforms, with major US carriers accelerating narrow-body modernization programs.
- Aerospace Manufacturers:OEM line-fit installations require multi-year validation cycles but capture long-term supplier relationships through avionics suite bundling.
- Cabin Crew:Hands-free environmental and communication controls reduce workload during high-task phases of flight.
- Passengers:In-seat entertainment voice interfaces navigate lighter certification requirements but face budget scrutiny from low-cost carriers.
Airlines represent the dominant revenue concentration, with Cabin Crew applications expanding most quickly.
Application:
Safety-critical use cases impose the steepest validation burdens, while passenger experience applications move through faster deployment cycles.
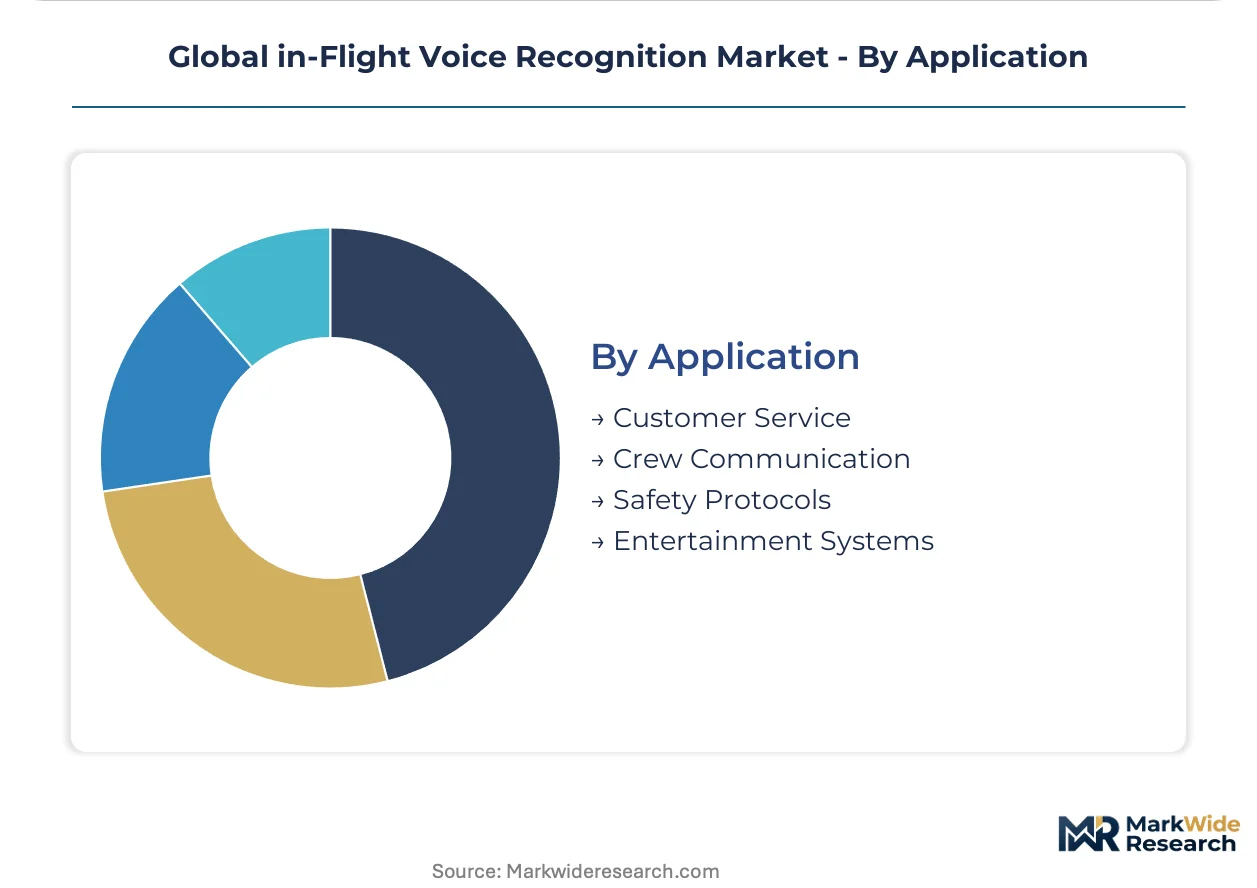
- Crew Communication:Cockpit voice systems require redundant speech recognition pathways under FAA Part 25, extending development timelines but creating replacement demand as accuracy standards tighten.
- Safety Protocols:Emergency command interfaces demand fail-operational architectures with documented training data provenance for EU AI Act compliance on European-registered aircraft.
- Customer Service:Passenger-facing inquiry handling operates under lighter regulatory scrutiny, enabling faster iteration of natural language capabilities.
- Entertainment Systems:In-flight media voice control competes with mature touchscreen alternatives, facing procurement pressure in budget-conscious retrofit segments.
Crew Communication leads by deployment volume, with Safety Protocols showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates narrow-body retrofit demand while Germany anchors European certification pathways for multilingual systems. China and India represent divergent growth trajectories, with the former scaling OEM line-fit installations and the latter expanding domestic fleet procurement. Japan maintains specialized acoustic engineering clusters serving defense-aerospace crossover applications.
United States
Major carriers accelerate narrow-body modernization programs, retrofitting integrated voice control platforms across aging fleets. FAA Part 25 certification requirements for redundant speech recognition pathways compress supplier qualification timelines. Dallas-Fort Worth and Seattle-Tacoma aerospace clusters host concentrated MRO channel capacity for avionics modification programs.
Germany
Lufthansa Group's fleet standardization drives volume procurement of crew communication modules with EU AI Act compliance documentation. EASA CS-25 certification requirements extend validation cycles for algorithmic transparency in safety-critical applications. Hamburg and Munich aerospace engineering centers specialize in noise-canceling microphone array development for pressurized cabin environments.
China
COMAC C919 domestic production creates line-fit demand for indigenous voice recognition systems in narrow-body platforms. MIIT avionics standardization initiatives align with national civil aviation authority certification pathways. Shanghai and Xi'an manufacturing clusters integrate speech interfaces into regional jet flight decks for export markets.
India
IndiGo and Air India narrow-body order backlogs generate white space for multilingual NLP engine deployment on international route networks. DGCA operational approval processes for adaptive accent recognition systems lag FAA and EASA precedent. Bangalore and Hyderabad technology corridors attract voice bi R&D investment from global avionics suppliers seeking cost-engineering advantages.
Japan
ANA and JAL fleet renewal programs prioritize crew workload reduction through hands-free environmental controls in high-task flight phases. METI aerospace technology roadmaps emphasize human-machine interface standardization for next-generation flight decks. Nagoya and Tokyo defense-aerospace crossover talent pools concentrate acoustic engineer expertise in cabin noise suppression algorithm design.
Global in-Flight Voice Recognition Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system integrators capturing OEM line-fit relationships while component suppliers penetrate retrofit channels through MRO partnerships. The vendor base organizes into three archetypes: diversified aerospace conglomerates bundling voice modules within avionics suites, specialized speech technology firms licensing adaptive language models, and acoustic hardware manufacturers supplying precision microphone arrays. Consolidation pressure intensifies as airlines unbundle procurement decisions from traditional flight deck upgrade contracts. Strategic moves center on cloud-updatable firmware licensing transitions and cybersecurity-integrated voice biometric service expansion.
Within the diversified aerospace tier, Honeywell International Inc and Collins Aerospace exemplify integrated platform strategies that embed voice command functionality within broader flight deck ecosystems. Thales Group occupies a distinct position anchoring European airline retrofit programs through multilingual natural language processing specialization. These three corporations represent contrasting geographic anchoring—American conglomerate structures against French defense-aerospace lineage—while converging on recurring revenue architectures that displace one-time hardware sales.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Collins Aerospace |
| Thales Group |
| Panasonic Avionics |
| Nuance Communications |
| Airbus S.A.S. |
| Raytheon Technologies Corporation |
| Safran Cabin |
| VoiceFlight Systems LLC |
| Others |
Supply Flow & Price Mechanics
FAA Part 25 certification tiering separates premium avionics-grade voice systems from commodity passenger entertainment modules, with that bifurcation concentrating supplier margins in dual-redundancy hardware while compressing returns on uncertified software licenses. Pricing power accumulates with vendors controlling rare-earth magnet microphone array production, whereas cost pressure transmits downstream through airlines unbundling procurement from traditional flight deck upgrade contracts.
Pricing Analysis
Capacity additions in China's precision magnet processing facilities are reshaping price floors for noise-canceling microphone arrays, even as FAA-certified dual-pathway systems sustain premium positioning through documentation burden. Three-tier pricing structure across certified flight deck, retrofit crew communication, and passenger entertainment levels reflects certification grade and after-sales service bundling. Cost compression in entertainment-tier modules intensifies because touchscreen substitution erodes voice control premiums. Low-cost carriers exhibit highest price sensitivity, while flag carriers accept certification-driven premiums for safety-critical installations.
Supply Chain Analysis
Rare-earth magnet supply rests on Chinese processing concentration for neodymium and dysprosium components essential to precision microphone arrays. Acoustic engineering talent draws from Japanese defense-aerospace crossover clusters and German cabin noise suppression specialists. Single-source vulnerability concentrates in rare-earth separation and refining capacity. Distribution runs through FAA-certified repair stations in the United States and EASA-approved MRO channels in Germany, with specialized avionics integrators displacing OEM-direct relationships in retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where airlines prioritize cloud-updatable language models and redundant certification documentation over static embedded firmware, concentrating procurement authority with vendors sustaining dual-pathway validation capabilities.
For Market Incumbents: Anticipate touchscreen interface substitution threats in budget-conscious retrofit segments by accelerating firmware subscription transitions that embed continuous accent adaptation. Defensive consolidation moves center on acquiring specialized acoustic engineering talent from Japanese defense-aerospace crossover pools and securing rare-earth magnet supply through upstream partnerships with Chinese processors. Channel control through FAA-certified repair station networks represents the priority lever against MRO channel displacement. For New Entrants and Emerging Players: Launch via standalone crew communication module RFPs targeting Indian domestic fleet expansion where multilingual NLP engine penetration remains low and DGCA approval processes lag FAA precedent. White-space targets concentrate on adaptive accent recognition for IndiGo and Air India narrow-body order backlogs, with cloud-updatable firmware licensing as the go-to-market angle. Cybersecurity-integrated voice biometrics adjacent to ICAO crew authentication protocols offers secondary entry path. For Investors and Strategic Acquirers: Consolidation pressure builds where airlines unbundle voice recognition from full flight deck contracts, fragmenting vendor relationships and eroding traditional avionics suite bundling power. Long-term viability favors specialized speech technology firms with documented training data provenance for EU AI Act compliance, positioned for acquisition by diversified aerospace conglomerates seeking recurring revenue architectures. The signal to watch is EASA certification timeline clarification for algorithmic transparency obligations, which would accelerate deployment schedules and revalue compliance-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Updatable Firmware Licensing Transition | Restructures supplier monetization from hardware sales toward recurring SaaS revenue streams. |
| Multilingual NLP Engine Specialization | Captures Indian and Southeast Asian fleet expansion where accent adaptation reduces command errors. |
| Cybersecurity-Integrated Voice Biometrics | Aligns with ICAO crew authentication protocols opening adjacent identity verification service revenue. |
| Rare-Earth Magnet Supply Partnership | Secures input cost stability against Chinese processing concentration volatility. |
| FAA-Certified Repair Station Network Expansion | Defends channel position against MRO displacement in United States narrow-body retrofit programs. |
Methodological Framework
Direct dialogue with avionics engineering directors, airline technical procurement managers, FAA certification specialists, and MRO channel operators grounded qualitative findings in operational reality. Secondary validation drew from FAA Part 25 airworthiness filings, EASA CS-25 certification documentation, EU AI Act regulatory texts, and ICAO cybersecurity guidance materials. Bottom-up installation and retrofit demand estimates triangulated against top-down fleet projection models from aircraft manufacturer delivery schedules.
Segment-level outputs across software solutions, control systems, microphone hardware, and headset devices combined with technology tier splits in machine learning, natural language processing, and voice command architectures. End-user segmentation incorporated airline fleet procurement patterns, aerospace manufacturer line-fit programs, and cabin crew application expansion trajectories. CAGRs derived from installed base turnover rates, certification timeline compression effects, and cloud-update adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EASA algorithmic transparency documentation delays or rare-earth export restriction scenarios. Forecasts reflect assumptions regarding FAA speech recognition mandate implementation timing and airline unbundling acceleration. A small set of named triggers—EU AI Act certification pathway clarification, ICAO voice biometric protocol finalization, and Chinese rare-earth processing policy shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Space Oscillator Market
Aerospace & Defense
Aerospace Plastics Market
Aerospace & Defense
Programmable Ammunition Market
Aerospace & Defense
AI in Defense Market
Aerospace & Defense
Less Lethal Ammunition Market
Aerospace & Defense
Asia Pacific Commercial Aircraft Aerostructures Market
Aerospace & Defense
North America Satellite Bus Market
Aerospace & Defense
Aerospace and Defense Telemetry Market
Aerospace & Defense
Commercial Aircraft Lavatory System Market
Aerospace & Defense
UK Space Propulsion System Market
Aerospace & Defense
Global Flight Inspection Market
Aerospace & Defense
Airborne ISR Market
Aerospace & Defense
Military Avionic Systems Market
Aerospace & Defense
Global Non Lethal Biochemical Weapon Market
Aerospace & Defense
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aerospace & Defense
Ablative Coatings Market