
 UAV Simulator Market | 2026-2036
UAV Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Simulator Market Intelligence
Software-defined feature licensing is consolidating recurring revenue streams alongside perpetual hardware sales in the UAV simulator sector. CAE Inc. leverages its installed base of flight training devices to cross-sell UAV modules across allied defense programs. L3Harris Technologies Inc. anchors military simulation portfolios with hardware-in-the-loop architectures for tactical drone rehearsal. Thales Group competes on European defense procurement frameworks with deployable simulator containers for expeditionary operations.
A UAV simulator is a synthetic training environment replicating unmanned aircraft dynamics, sensor payloads, and command-and-control interfaces through computational physics models and visual databases, used to qualify operators without risking airframes or violating airspace restrictions. Rotary-wing UAV simulators dominate procurement volumes due to the mechanical complexity of multirotor flight regimes and the higher skill threshold for precision hovering and landing. Hardware-in-the-loop configurations command premium positioning because they integrate actual avionics firmware into training scenarios, validating software patches before field deployment.
FAA Part 107 certification requirements and EASA drone operator competency standards together mandate documented simulator hours for commercial remote pilot licensing, directly expanding addressable demand. The U.S. Department of Defense operates under MIL-STD-810 and DO-178C software assurance guidelines that shape simulator fidelity specifications for mission rehearsal systems. Stakeholders must monitor evolving cross-border data sovereignty rules affecting cloud-based simulation architectures, as defense customers increasingly require on-premise deployment with sovereign data controls.
Market Dynamics
Military procurement cycles and FAA Part 107 certification mandates are compressing training timelines, forcing simulator vendors to deliver higher-fidelity systems at accelerated deployment schedules.
Growth Catalysts
- FAA Part 107 mandates:Documented simulator hours are now required for commercial remote pilot licensing in the United States, directly expanding institutional procurement from flight schools and commercial operators.
- Multirotor complexity:Rotary-wing UAV simulators address the mechanical intricacy of precision hovering and landing regimes, creating persistent demand for high-fidelity training environments.
- Hardware-in-the-loop validation:Integration of actual avionics firmware into training scenarios enables software patch verification before field deployment, anchoring defense procurement specifications.
Market Restraints
- Semiconductor supply concentration:GPU and FPGA shortages from Taiwan-based foundries create lead time volatility for visual rendering and real-time computing subsystems.
- DO-178C compliance costs:Software assurance documentation for military applications demands extensive verification cycles, inflating development overhead for simulator firmware.
- Cloud sovereignty restrictions:Defense customers in NATO member states increasingly require on-premise deployment with sovereign data controls, limiting scalable SaaS architectures.
Strategic Opportunities
- Urban air mobility training:Emerging eVTOL operator certification programs in Germany and France are creating demand for multi-aircraft swarm simulation environments.
- Expeditionary deployable systems:Containerized simulator architectures address expeditionary military requirements across European defense procurement frameworks.
- Cross-domain sensor fusion:Convergence of electro-optical, infrared, and synthetic aperture radar payloads in single training scenarios enables premium module licensing.
Industry Challenges
- Embedded software engineering scarcity:Real-time physics modeling and avionics protocol expertise concentrates among defense contractor workforces, constraining vendor hiring pipelines.
- MIL-STD-810 environmental qualification:Temperature, shock, and electromagnetic interference testing for field-deployable simulators extends certification timelines.
- Legacy system protocol fragmentation:Proprietary command-and-control interfaces across drone OEMs force simulator vendors to maintain extensive adapter libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Simulator Market |
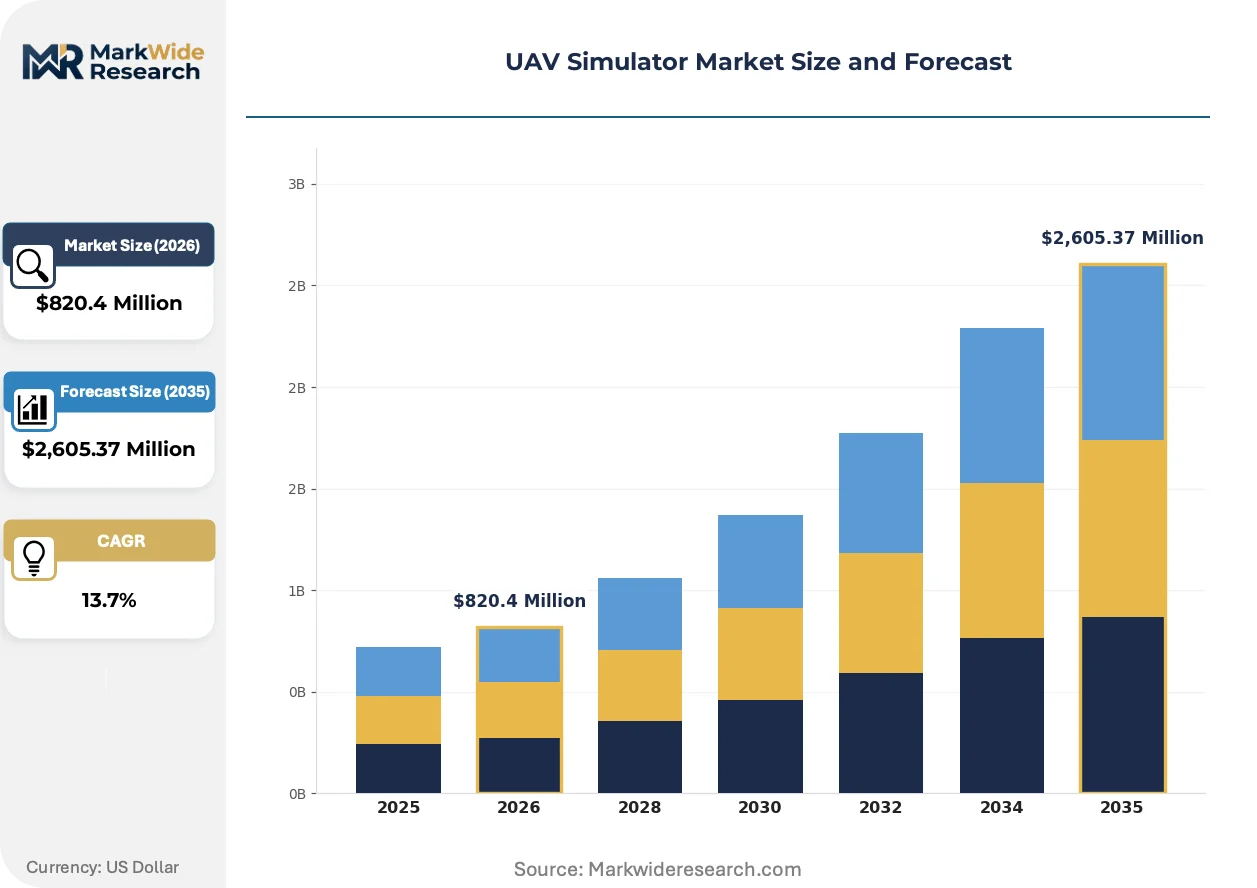
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $2,605.37 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing UAV Simulator, Rotary-Wing UAV Simulator, Hybrid UAV Simulator, Tactical UAV Simulator Technology: Augmented Reality, Virtual Reality, Cloud-Based Simulation, Desktop Simulation, Hardware-in-the-Loop Application: Military Training, Commercial Pilot Training, Disaster Management, Agricultural Monitoring, Infrastructure Inspection End User: Defense Forces, Flight Schools, Emergency Services, Agricultural Firms, Utility Providers |
| Companies Covered | L3Harris Technologies Inc., General Atomics Aeronautical Systems Inc., CAE Inc., Thales Group, Leonardo S.p.A, Lockheed Martin Corporation, Boeing Co., Textron Inc., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Simulator Market Strategic Shifts & Innovations
Physics engine fidelity and regulatory data architectures are converging to reshape how unmanned aircraft operators qualify for commercial and military missions without airframe risk.
Artificial intelligence is automating scenario generation and adaptive difficulty scaling in next-generation UAV simulators. Defense training commands in Australia and the United Kingdom are piloting these systems for tactical rehearsal. The technology is compressing instructor overhead while expanding scenario complexity beyond manually scripted mission sets.
EASA drone operator competency standards are mandating documented synthetic training hours for beyond-visual-line-of-sight operations. This regulatory architecture is forcing simulator vendors to integrate logging and attestation features directly into training platforms. Commercial drone service providers in France and Germany are responding by consolidating procurement around certified training device networks.
Defense acquisition offices are unbundling hardware procurement from software licensing, creating recurring revenue streams for scenario content and firmware updates. Simulator vendors are responding with subscription-based mission libraries targeting allied military interoperability requirements. This pattern is most visible in NATO joint training exercises where standardized scenarios reduce integration friction across national forces.
UAV Simulator Market Segmentation
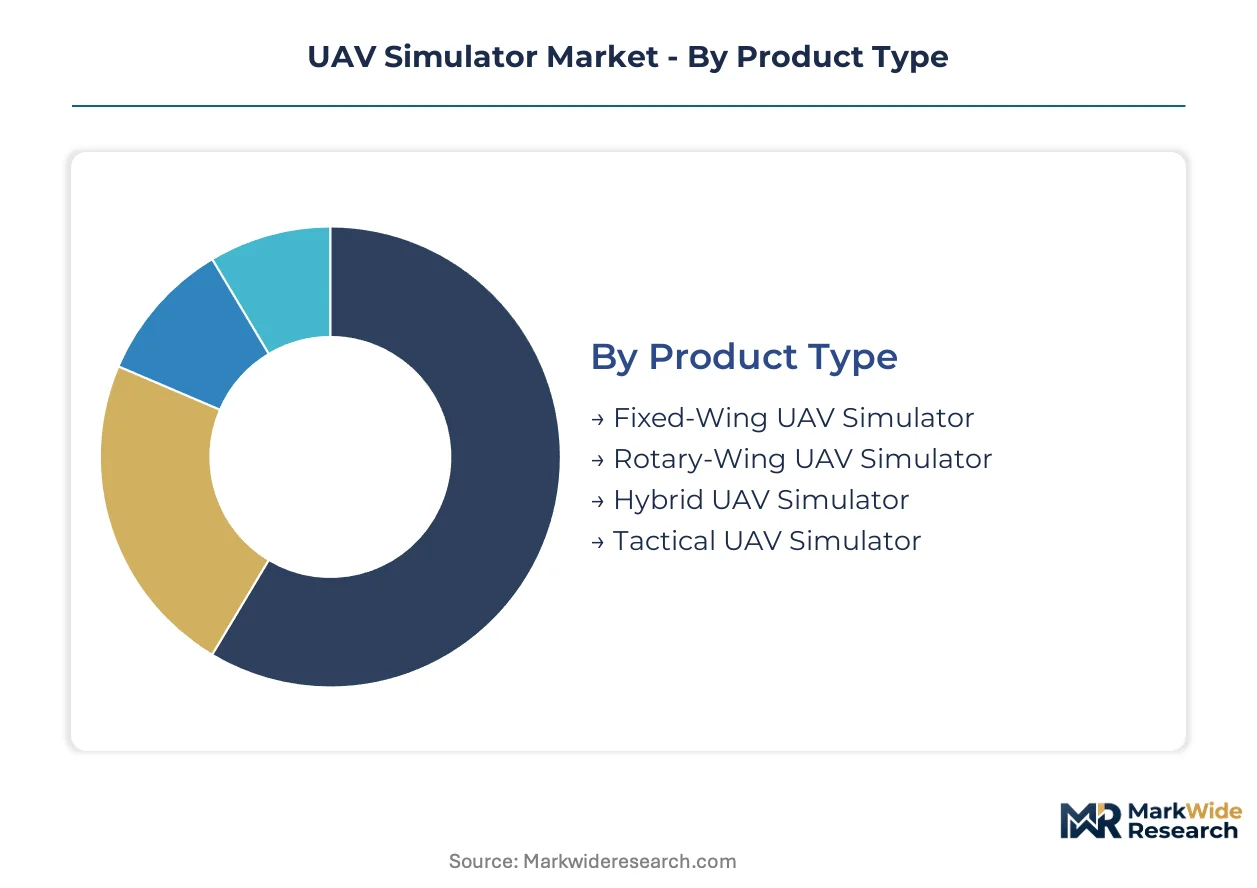
UAV simulator procurement patterns diverge sharply between defense programs requiring hardware-in-the-loop fidelity and commercial operators prioritizing cost-effective desktop solutions. Understanding these segment boundaries clarifies where vendors must anchor R&D investments versus where scalable software licensing dominates revenue architecture.
Product Type:
Standalone simulator systems address discrete training missions while embedded configurations integrate into broader synthetic battlefield networks, creating divergent specification requirements across procurement channels.
- Fixed-Wing UAV Simulator:Replicates long-endurance flight dynamics for surveillance and cargo platforms with extended range profiles. Defense procurement in the United States anchors demand through MQ-9 Reaper training programs, though commercial logistics operators are expanding procurement for beyond-visual-line-of-sight certification.
- Rotary-Wing UAV Simulator:Multirotor physics engines model the complex aerodynamic instabilities of precision hovering and vertical landing regimes. Flight schools across Germany and France concentrate procurement here due to EASA competency mandates for commercial drone licensing.
- Hybrid UAV Simulator:Combines fixed-wing efficiency with rotary-wing maneuverability for transitional flight training. Agricultural monitoring firms in Australia represent emerging demand as hybrid platforms gain share in crop-spraying applications.
- Tactical UAV Simulator:Compact deployable units designed for expeditionary military operations with rapid setup protocols. NATO joint training exercises in Poland and Romania drive standardization requirements.
Volume placements concentrate in Rotary-Wing UAV Simulator; the faster expansion belongs to Tactical UAV Simulator.
Technology:
Cost tier stratification separates premium immersive systems from accessible entry-level platforms, with middleware architectures capturing institutional procurement at scale.
- Augmented Reality:Overlays synthetic aircraft and telemetry onto physical environments for mixed-reality pilot training. Emergency services in the United Kingdom are piloting these systems for search-and-rescue scenario rehearsal.
- Virtual Reality:Fully immersive head-mounted displays with six-degrees-of-freedom tracking for spatial disorientation training. Flight schools in Canada cite equipment cost barriers despite superior fidelity outcomes.
- Cloud-Based Simulation:Distributed computing architectures enabling multi-user collaborative training without local hardware investment. Utility providers in Spain leverage these platforms for distributed workforce certification.
- Desktop Simulation:Screen-based interfaces with joystick peripherals for foundational skills acquisition. Agricultural firms in Brazil dominate procurement due to price accessibility and minimal infrastructure requirements.
- Hardware-in-the-Loop:Integration of actual avionics firmware into synthetic environments for software validation before field deployment. Defense forces in the United States mandate this architecture for mission-critical system qualification.
Desktop Simulation captures the widest installed base; Hardware-in-the-Loop commands the steepest expansion trajectory.
Application:
Customer maturity varies from regulated certification programs to exploratory operational testing, shaping simulator fidelity requirements and procurement cycle lengths.
- Military Training:Mission rehearsal systems replicate contested electromagnetic environments and kinetic threat scenarios. Defense procurement in Australia and Japan follows allied interoperability frameworks for joint exercise compatibility.
- Commercial Pilot Training:FAA Part 107 and EASA competency documentation drives standardized curriculum deployment. Flight schools across the United States anchor procurement volume through regulatory mandate compliance.
- Disaster Management:Scenario libraries model flood assessment, wildfire perimeter mapping, and structural damage evaluation. Emergency services in Italy and Greece are expanding procurement following recent Mediterranean climate events.
- Agricultural Monitoring:Crop health mapping and precision spraying simulation for seasonal operator certification. Agricultural firms in Argentina and Chile represent emerging demand centers.
- Infrastructure Inspection:Power line, pipeline, and cellular tower simulation for utility sector workforce development. Utility providers in Norway and Sweden concentrate procurement for offshore wind and hydroelectric asset monitoring.
Military Training dominates absolute spending; Disaster Management is climbing the fastest as climate adaptation budgets expand.
End User:
Procurement authority fragmentation separates centralized defense acquisition from distributed commercial purchasing, influencing vendor sales channel architecture.
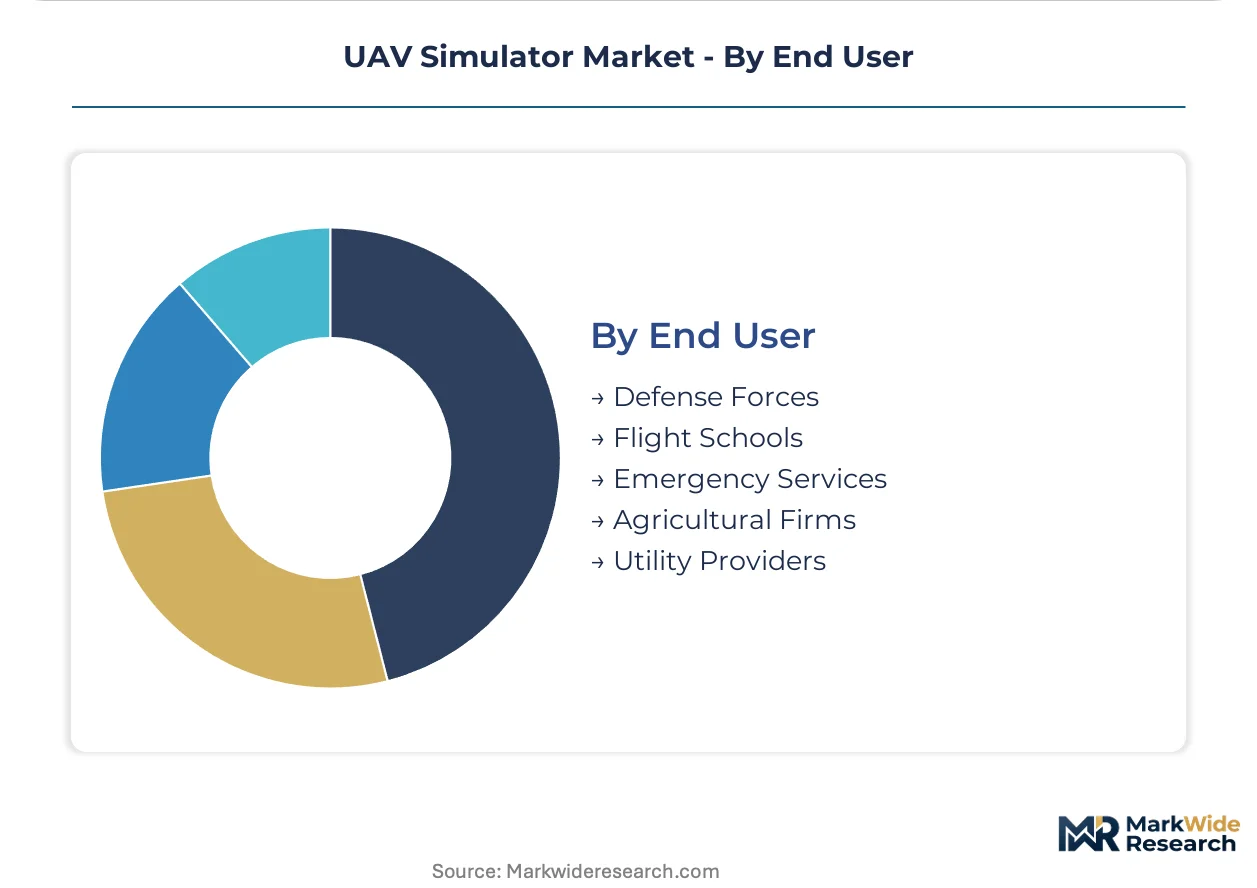
- Defense Forces:Centralized procurement through national acquisition offices with MIL-STD compliance requirements. Defense forces in the United States, United Kingdom, and France anchor global demand through allied modernization programs.
- Flight Schools:Federated purchasing networks responding to regulatory certification mandates. Flight schools across Germany and the Netherlands are consolidating around vendor-certified training device networks.
- Emergency Services:Municipal and regional procurement for search-and-rescue and disaster response capabilities. Emergency services in Italy and Spain are expanding simulator deployment for Mediterranean wildfire response.
- Agricultural Firms:Seasonal hiring patterns drive demand for rapid operator certification without airframe risk. Agricultural firms in Brazil and Australia represent volume procurement centers.
- Utility Providers:Infrastructure reliability requirements mandate documented training for beyond-visual-line-of-sight operations. Utility providers in Scandinavia and Canada lead procurement for remote asset inspection.
Defense Forces anchor procurement value; Flight Schools are gaining share fastest through regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simulator production concentrates among defense contractors in the United States and France, while procurement demand disperses across NATO member states and Asia-Pacific allies responding to regulatory certification mandates.
United States
FAA Part 107 mandates drive flight school procurement for commercial remote pilot licensing, while DoD programs anchor military simulator acquisition. MIL-STD-810 environmental qualification requirements shape vendor specifications for mission rehearsal systems. Greater Washington DC and Orlando defense corridors concentrate CAE Inc. and L3Harris Technologies Inc. training device manufacturing.
Germany
EASA drone operator competency standards mandate documented synthetic training hours for BVLOS operations, expanding institutional procurement. The country's national aviation regulator enforces certification parity with manned aircraft standards. Munich and Hamburg aerospace clusters host Thales Group and Rheinmetall simulation engineering centers serving Bundeswehr modernization.
United Kingdom
Royal Air Force synthetic training programs prioritize interoperability with allied forces for joint exercise compatibility. Ministry of Defence procurement follows DO-178C software assurance guidelines for mission-critical system qualification. Bristol and Farnborough defense technology corridors concentrate hardware-in-the-loop integration facilities.
France
DGA procurement frameworks standardize deployable simulator containers for expeditionary operations across African and Eastern European theaters. EASA regulatory alignment with military certification creates dual-use commercial opportunities. Bordeaux and Paris-Saclay aerospace valleys anchor Thales Group and Safran simulation R&D for rotary-wing UAV training.
Australia
Royal Australian Air Force pilot training modernization prioritizes tactical UAV rehearsal systems for Indo-Pacific contingency scenarios. Defence Department acquisition follows allied interoperability frameworks standardized through AUKUS agreements. Adelaide and Brisbane defense manufacturing corridors concentrate simulation integration for MQ-9B SkyGuardian qualification programs.
UAV Simulator Market Key Industry Players
Top-tier vendors anchor defense procurement, while mid-tier specialists serve commercial flight schools and agricultural operators. The vendor base stratifies across hardware-in-the-loop system integrators, software-defined scenario providers, and deployable container fabricators. Three archetypes dominate: legacy aerospace conglomerates with installed training device bases, defense contractors with MIL-STD compliance expertise, and emerging software houses licensing cloud-based mission libraries. Competitive moves concentrate on cross-selling UAV modules into existing flight training footprints and unbundling hardware procurement from recurring software subscriptions.
Within the legacy aerospace tier, CAE Inc., L3Harris Technologies Inc., and Thales Group occupy positions spanning North American and European defense procurement channels. CAE Inc. leverages its Canadian corporate structure and extensive installed base of civil aviation training devices to cross-sell military UAV modules. L3Harris Technologies Inc. exemplifies the US defense contractor archetype with hardware-in-the-loop architectures. Thales Group represents European sovereign capability in deployable expeditionary systems.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| General Atomics Aeronautical Systems Inc. |
| CAE Inc. |
| Thales Group |
| Leonardo S.p.A |
| Lockheed Martin Corporation |
| Boeing Co. |
| Textron Inc. |
| Northrop Grumman Corporation |
| Others |
Cost & Logistics Intelligence
Defense contractor consolidation through private-equity roll-ups has concentrated manufacturing ownership among five aerospace conglomerates, tightening supply discipline while enabling subscription-based software pricing that decouples revenue from hardware shipment cycles.
Pricing Analysis
Cost-down pressure on hardware-in-the-loop systems accelerates because Taiwan-based GPU foundry constraints force vendors to absorb component inflation rather than pass through to defense procurement offices locked in multi-year contract ceilings. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810 qualified expeditionary containers from desktop commercial trainers, with certification grade and after-sales service bundling as the primary differentiation drivers. Flight schools exhibit acute price sensitivity due to thin margins on per-student licensing revenue, whereas defense acquisition offices prioritize mission fidelity over unit cost.
Supply Chain Analysis
Freight cost volatility for visual rendering subsystems shipped from East Asian manufacturing nodes has prompted vendors to regionalize final assembly in the United States, Germany, and Australia. GPU and FPGA supply draws from Taiwan, South Korea, and United States fabrication facilities, while motion platform actuators and projection engines source from Japanese and German precision manufacturers. Single-source vulnerability in Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through direct defense procurement channels and certified training device networks for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 107 and EASA drone operator competency mandates impose documentation burdens that compliant incumbents have already absorbed, erecting regulatory moats against undercapitalized entrants lacking verification infrastructure.
For Market Incumbents: Anticipate cloud sovereignty restrictions fragmenting addressable markets by forcing redundant on-premise deployment architectures across NATO member states. Counter semiconductor supply concentration through backward integration into FPGA firmware development or captive supply agreements with South Korean foundry alternatives. Certification investment in DO-178C compliance documentation represents the priority defensive lever against emerging software houses lacking military software assurance expertise.
For New Entrants and Emerging Players: Agricultural firms in Brazil and Australia represent the most penetrable buyer archetype due to seasonal hiring patterns and minimal infrastructure requirements favoring desktop simulation solutions. White-space targets include containerized tactical systems for expeditionary military operators and cross-domain sensor fusion modules for multi-payload training scenarios. Go-to-market execution should anchor on utility provider partnerships for beyond-visual-line-of-sight certification programs in Scandinavia.
For Investors and Strategic Acquirers: Defense acquisition offices unbundling hardware procurement from software licensing is the leading indicator that recurring revenue multiples will expand for scenario content providers over pure hardware fabricators. Long-term viability favors vendors with installed training device bases enabling cross-selling into allied defense interoperability frameworks. Acquisition targets should screen for MIL-STD compliance expertise and sovereign data control architectures. Monitor NATO joint training exercise standardization protocols as the inflection signal for scalable mission library demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-in-the-Loop Integration | Validates actual avionics firmware before field deployment, anchoring defense procurement specifications. |
| Software-Defined Scenario Licensing | Creates recurring revenue streams decoupled from hardware shipment cycles across allied training programs. |
| Expeditionary Container Deployment | Addresses NATO rapid-setup requirements for Eastern European and African theater operations. |
| Cloud Sovereignty Architecture | Enables on-premise simulation with data controls required by European defense customers. |
| Cross-Domain Sensor Fusion | Converges electro-optical, infrared, and radar payloads for premium module licensing opportunities. |
Research Approach
Multi-period observation of defense procurement cycles, regulatory mandate adoption timelines, and simulator deployment schedules anchored the trend analysis, supplemented by interviews with flight school operators, defense acquisition officers, simulation engineering directors, and commercial drone service providers. Secondary validation drew from FAA certification databases, EASA regulatory filings, NATO joint training exercise documentation, and defense contractor SEC disclosures. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrix modeling connected training device shipments, software licensing attach rates, and regulatory mandate compliance deadlines across the projection horizon. Segmentation dimensions included product type, technology tier, application vertical, and end-user procurement authority. CAGRs derived from regression analysis of historical defense spending patterns and commercial licensing growth trajectories. Industry-specific forecast inputs incorporated semiconductor lead time indices and EASA competency standard implementation schedules.
Revisions become necessary when Taiwan-based foundry capacity constraints intensify, FAA or EASA regulatory timelines accelerate, or allied defense procurement frameworks shift toward sovereign data control mandates. Forecasts reflect documented assumptions about procurement cycle continuity and regulatory mandate enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Enterprise Drone Management Solutions Market
UAV
Rc Helicopter Market
UAV
UAV GNSS Antenna Market
UAV
Stratospheric Flying Drone Market
UAV
Racing Drone Market
UAV
Counter-UAS Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Passenger Drones Market
UAV
Drone Lens Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Latin America Small UAV Market
UAV
Global Drone Analytics Market
UAV
Drone Telematics Market
UAV
Tactical UAV Market
UAV
Global Aerial Survey Services Market