
 Global Renewable Drones Market | 2026-2036
Global Renewable Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Renewable Drones Market Outlook
Drone-as-a-service leasing is rewriting competitive economics for fleet operators without heavy balance sheets. DJI leverages its manufacturing scale to dominate hardware supply across Asia-Pacific wind farm deployments. Terra Drone Corporation anchors its position through specialized infrastructure inspection protocols for offshore renewable assets. DroneDeploy, Inc competes on software integration, bundling thermal analytics with subscription-based fleet management tools.
Renewable drones are unmanned aerial systems engineered with photovoltaic-integrated airframes and extended-endurance power management, typically achieving flight durations exceeding four hours for continuous asset monitoring. These platforms perform thermographic fault detection, vegetation encroachment mapping, and structural degradation assessment across solar arrays and wind turbine installations. Multirotor drones currently lead deployment volumes due to vertical takeoff agility in complex terrain, while fixed-wing drones capture margin pools through long-range linear inspection of transmission corridors. Solar-powered drones represent the fastest-growing product category as photovoltaic cell efficiency improvements enable persistent loitering missions without battery swap logistics.
The EU Green Deal and REACH compliance frameworks mandate lower-carbon inspection methodologies across member state renewable portfolios, directly stimulating drone substitution for manned helicopter surveys. FAA Part 107 waivers in the United States and EASA open-category certifications in Europe establish operational altitude and beyond-visual-line-of-sight parameters that shape product design roadmaps. China's MIIT issues GB standards for industrial UAV airworthiness that constrain market entry for non-compliant hardware vendors. Stakeholders must monitor evolving energy-harvesting efficiency benchmarks and fragmented national airspace integration timelines as determinants of scalable deployment economics.
Market Dynamics
Photovoltaic cell efficiency gains are compressing battery swap logistics across solar-powered drone fleets, forcing operators to restructure maintenance economics around persistent loitering architectures rather than cyclic ground interventions.
Growth Catalysts
- EU Green Deal procurement mandates:Clean-tech inspection standards across member state renewable portfolios accelerate drone substitution for manned helicopter surveys in offshore wind maintenance.
- China's MIIT GB airworthiness protocols:State-backed renewable infrastructure programs integrate standardized UAV inspection protocols across industrial corridors, creating compliant demand pipelines.
- Agricultural monitoring expansion:Crop health surveillance operations across Brazil and Australia scale drone fleets for vegetation encroachment mapping and irrigation system assessment.
Market Restraints
- Lithium-polymer battery cost volatility:Extended-endurance power management systems face input price pressure from raw material supply concentration in concentrated cathode processing regions.
- Fragmented national airspace integration:FAA Part 107 waiver limitations and EASA open-category altitude parameters create operational friction for beyond-visual-line-of-sight missions.
- Manned aviation substitution economics:Helicopter inspection providers in mature European markets retain cost advantages for one-off emergency response deployments.
Strategic Opportunities
- Drone-as-a-service leasing models:Fleet operators without heavy balance sheets access renewable asset inspection capabilities through subscription-based thermal analytics bundling.
- Transmission corridor linear inspection:Fixed-wing platforms capture margin pools in long-range infrastructure monitoring across China's state grid expansion zones.
- ISO 21384-3 unmanned aircraft systems standards:Emerging global certification frameworks enable cross-border operational approvals for persistent solar-powered surveillance missions.
Industry Challenges
- Beyond-visual-line-of-sight pilot certification:Regulatory competency requirements outpace training infrastructure availability in fragmented national aviation authority jurisdictions.
- Thermographic sensor integration complexity:Fault detection algorithm calibration demands specialized skill sets spanning photovoltaic physics and aerial data processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Renewable Drones Market |
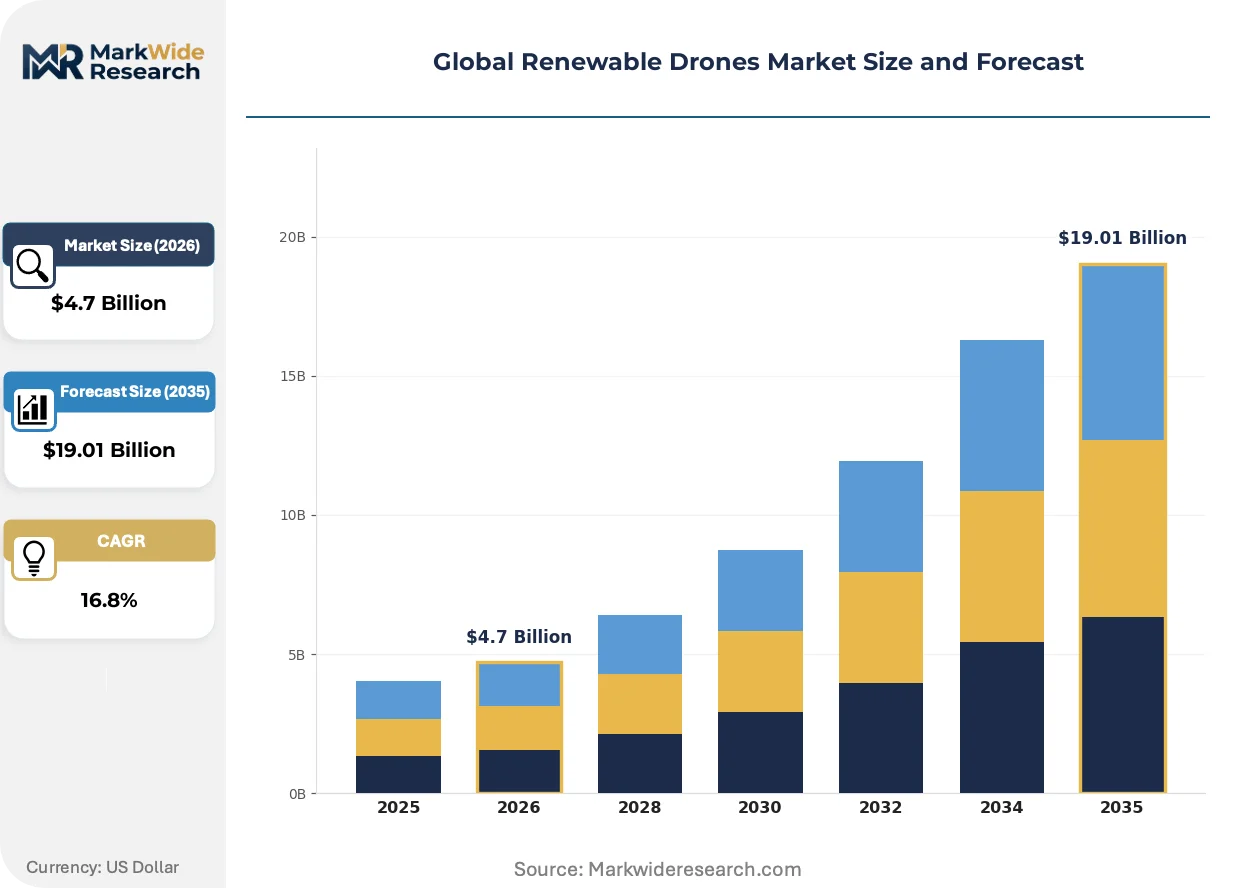
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multirotor Drones, Hybrid Drones, Solar-Powered Drones Application: Agricultural Monitoring, Infrastructure Inspection, Environmental Surveying, Disaster Management End User: Agriculture Sector, Defense Sector, Construction Industry, Logistics Providers Technology: Autonomous Navigation, Energy Harvesting, Machine Learning, Remote Sensing |
| Companies Covered | Drone Volt Group, DJI, Terra Drone Corporation, DroneDeploy, Inc, ABJ Drones, Parrot, Aerodyne Measure, Raptor Maps, Flyability, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Renewable Drones Market Strategic Shifts
Operational altitude waivers and photovoltaic airframe engineering are converging to enable multi-hour persistent missions, compressing the economics of continuous renewable asset monitoring against cyclic manned alternatives.
Photovoltaic-integrated airframes with gallium arsenide cell architectures are digitizing power management protocols across solar-powered drone categories. Wind farm operators in Denmark and Spain adopt these platforms for thermographic blade inspection at expanded operational radii. The technology is digitizing maintenance scheduling from calendar-based rotations toward condition-triggered interventions.
EASA open-category certifications and FAA Part 107 waiver expansions are establishing harmonized beyond-visual-line-of-sight parameters across North Atlantic regulatory zones. Industrial UAV manufacturers align product roadmaps with these altitude and range specifications to secure cross-jurisdictional operational approvals. Offshore wind inspection providers in the North Sea corridor accelerate fleet certification timelines to capture emerging mission scopes.
Subscription-based fleet management tools are displacing perpetual license software procurement across agricultural and utility inspection segments. DroneDeploy-style thermal analytics bundling shifts buyer economics from capital expenditure toward operational expenditure frameworks. This purchasing rotation concentrates most visibly across Australia's cotton belt irrigation monitoring contracts and Brazil's sugarcane estate surveillance operations.
Global Renewable Drones Market Segmentation
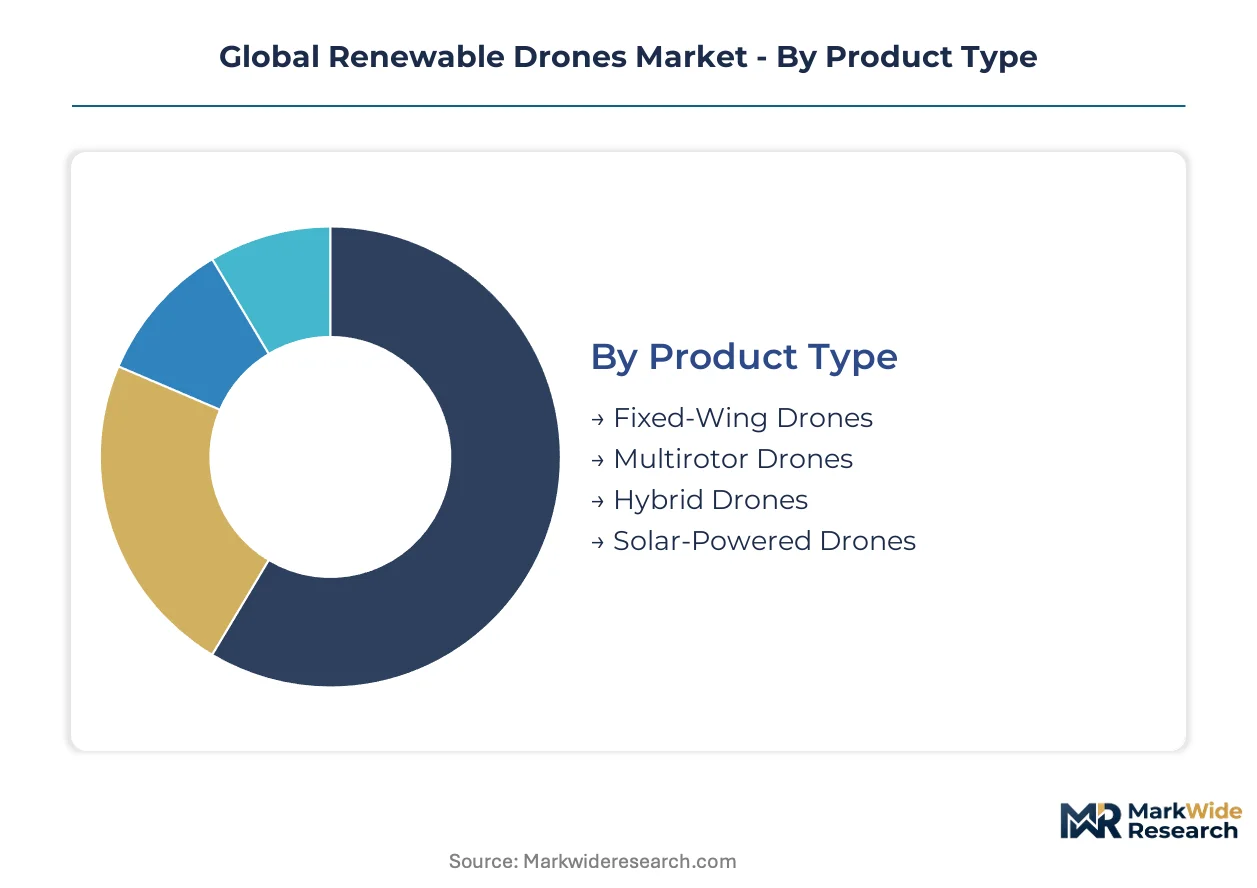
Segmentation in renewable drones reveals how power management architectures and mission profiles dictate procurement decisions across asset-intensive industries. Understanding these divides exposes where photovoltaic integration, autonomous capabilities, and regulatory compliance create divergent margin pools.
Product Type:
Mature multirotor platforms dominate current deployment volumes, while emerging solar-powered architectures are compressing maintenance economics through persistent loitering capabilities.
- Multirotor Drones:Vertical takeoff agility enables complex terrain navigation across wind farm nacelle inspections and solar array thermography. Demand concentrates in China's industrial corridor where state-backed renewable infrastructure programs integrate UAV inspection protocols for turbine blade assessment.
- Solar-Powered Drones:Photovoltaic-integrated airframes with gallium arsenide cell architectures achieve flight durations exceeding four hours without battery swap logistics. EU Green Deal procurement mandates across member state renewable portfolios accelerate substitution for manned helicopter surveys in offshore wind maintenance.
- Fixed-Wing Drones:Long-range linear inspection capabilities capture margin pools in transmission corridor monitoring across China's state grid expansion zones.
- Hybrid Drones:Dual-power architectures combine vertical takeoff agility with extended cruise endurance for mixed-terrain renewable asset surveys.
Multirotor drones retain volume leadership; solar-powered platforms hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive infrastructure inspection from operational expenditure-driven agricultural monitoring contracts.
- Infrastructure Inspection:Thermographic fault detection and structural degradation assessment across solar arrays and wind turbine installations demand specialized sensor payloads. Offshore wind operators in Denmark and Spain adopt persistent solar-powered platforms for blade inspection at expanded operational radii.
- Agricultural Monitoring:Crop health surveillance and vegetation encroachment mapping scale through subscription-based fleet management tools. Australia's cotton belt irrigation monitoring contracts and Brazil's sugarcane estate surveillance operations concentrate demand for thermal analytics bundling.
- Environmental Surveying:Ecosystem monitoring and carbon stock assessment missions leverage remote sensing payloads across protected renewable development zones.
- Disaster Management:Rapid deployment architectures for post-extreme-weather damage assessment prioritize battery swap logistics over persistent loitering.
Infrastructure inspection commands premium pricing; agricultural monitoring scales fastest through drone-as-a-service leasing penetration.
End User:
Customer type fragmentation separates balance-sheet-heavy utility operators from asset-light service providers restructuring procurement around operational expenditure frameworks.
- Agriculture Sector:Fleet operators without heavy balance sheets access inspection capabilities through thermal analytics subscriptions. Brazil and Australia expand drone fleets for crop health surveillance and irrigation system assessment.
- Defense Sector:Secure communication protocols and hardened airworthiness standards constrain vendor qualification to compliant hardware manufacturers.
- Construction Industry:Pre-commissioning surveys and progressive monitoring of renewable installation sites drive multirotor deployment for vertical agility.
- Logistics Providers:Last-mile delivery experimentation with solar-powered platforms remains nascent against core renewable asset inspection demand.
Agriculture sector procurement scales through subscription models; defense sector requirements enforce steepest certification barriers.
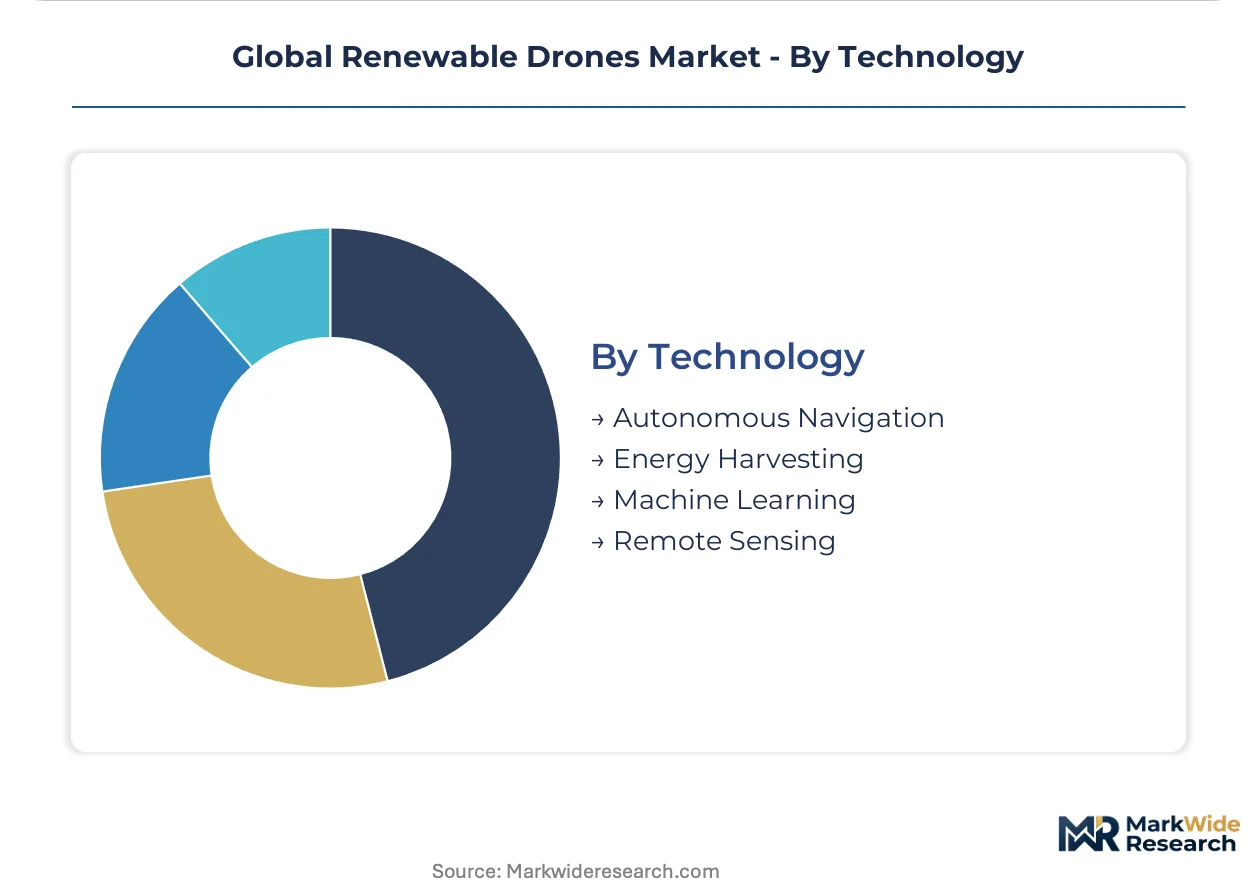
Technology:
Supply concentration in sensor integration and power management semiconductors shapes competitive positioning across technology tiers.
- Energy Harvesting:Photovoltaic cell efficiency gains digitize power management protocols and compress battery swap logistics. Gallium arsenide architectures enable persistent missions that restructure maintenance scheduling from calendar-based rotations toward condition-triggered interventions.
- Remote Sensing:Thermographic sensor integration demands specialized skill sets spanning photovoltaic physics and aerial data processing for fault detection algorithm calibration.
- Autonomous Navigation:Beyond-visual-line-of-sight mission parameters require alignment with FAA Part 107 waivers and EASA open-category certifications.
- Machine Learning:Predictive maintenance algorithms process inspection imagery to flag degradation patterns before structural failure.
Energy harvesting retains technology leadership; machine learning applications climb fastest as fault prediction accuracy improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in renewable drones tilt toward manufacturing surplus in East Asia against service-led demand absorption in Western markets. Import dependency for photovoltaic-integrated airframes concentrates in European and North American procurement pipelines. Export competitiveness hinges on GB standards compliance and FAA/EASA operational certifications.
China
State-backed renewable infrastructure programs across the industrial corridor integrate UAV inspection protocols for wind turbine blade assessment. MIIT issues GB standards for industrial UAV airworthiness that constrain market entry for non-compliant hardware vendors. Yangtze River Delta manufacturing clusters supply photovoltaic-integrated airframes to domestic wind farm operators and export markets.
United States
FAA Part 107 waivers establish operational altitude and beyond-visual-line-of-sight parameters that shape product design roadmaps for solar-powered platforms. The Inflation Reduction Act accelerates clean-tech procurement across utility-scale renewable portfolios. Texas wind belt operators deploy thermographic inspection fleets across turbine installations in the Panhandle and Gulf Coast corridors.
Germany
EU Green Deal procurement mandates accelerate drone substitution for manned helicopter surveys in North Sea offshore wind maintenance. REACH compliance frameworks mandate lower-carbon inspection methodologies across member state renewable portfolios. Hamburg and Bremerhaven port clusters anchor offshore service vessel integration with persistent solar-powered surveillance missions.
Brazil
Agricultural monitoring operations scale drone fleets for crop health surveillance and vegetation encroachment mapping across sugarcane estates. ANVISA regulates aerial application equipment standards that intersect with renewable platform airworthiness requirements. São Paulo state concentrates service provider networks for thermal analytics bundling in irrigation system assessment contracts.
Australia
Cotton belt irrigation monitoring contracts concentrate demand for subscription-based fleet management tools and thermal analytics bundling. TGA-equivalent aviation safety standards govern beyond-visual-line-of-sight operational approvals for persistent loitering missions. Queensland and New South Wales renewable zones deploy fixed-wing platforms for transmission corridor linear inspection across state grid expansion areas.
Global Renewable Drones Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in sensor payloads and photovoltaic cell architectures. Market structure tilts toward consolidated hardware supply with fragmented service layer competition. Three archetypes dominate: manufacturing-scale platform vendors, specialized inspection service providers, and software-centric fleet management bundlers. Competitive moves concentrate on strategic partnerships for regulatory certification and geographic expansion through drone-as-a-service leasing models.
Within the manufacturing-scale tier, DJI anchors hardware supply across Asia-Pacific wind farm deployments. Terra Drone Corporation occupies a position among specialized infrastructure inspection protocol developers for offshore renewable assets. DroneDeploy, Inc exemplifies the software-centric archetype through subscription-based thermal analytics integration. These three represent divergent margin capture strategies across the platform, service, and software layers.
| Leading Market Players |
|---|
| Drone Volt Group |
| DJI |
| Terra Drone Corporation |
| DroneDeploy, Inc |
| ABJ Drones |
| Parrot |
| Aerodyne Measure |
| Raptor Maps |
| Flyability |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters anchor photovoltaic-integrated airframe production, and their capacity utilization rates directly transmit into downstream pricing power for solar-powered drone platforms. Battery swap logistics versus persistent loitering architectures create divergent cost structures that reshape procurement economics across fleet operators.
Pricing Analysis
Industrial OEM buyers anchor a subscription-based pricing structure across renewable asset inspection segments. Price differentiation rests on FAA Part 107 certification tier and after-sales thermal analytics bundling. Cost compression in multirotor hardware is intensifying because DJI manufacturing scale floods Asia-Pacific wind farm deployment channels. Agricultural service providers in Brazil and Australia exhibit highest price sensitivity, while offshore wind operators in the North Sea corridor accept premium positioning for persistent solar-powered surveillance missions.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn and DJI's in-house Shenzhen facilities for airframe assembly, while gallium arsenide cell fabrication draws from Taiwan and South Korea foundries. Raw material dependencies span lithium-polymer cathode precursors, thermographic sensor arrays, and composite fiber structures. Single-source vulnerability in concentrated cathode processing regions threatens extended-endurance power management system availability. Distribution runs through direct OEM sales to utility-scale wind farm operators and drone-as-a-service leasing networks for agricultural monitoring contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beyond-visual-line-of-sight pilot certification scarcity constrains fleet scaling across fragmented national aviation authority jurisdictions, creating competitive moats for compliant operators. Thermographic sensor integration complexity demands specialized skill sets that outpace training infrastructure development.
For Market Incumbents: Pre-empt regulatory capture by accelerating FAA Part 107 waiver expansion and EASA open-category certification timelines before emerging solar-powered platform vendors achieve operational parity. Anchor backward integration into gallium arsenide cell architectures to secure persistent loitering mission economics against battery swap logistics providers. Defensive patent positioning around thermographic fault detection algorithms protects margin pools in infrastructure inspection segments. For New Entrants and Emerging Players: Establish a beachhead in Australia's cotton belt irrigation monitoring contracts where subscription-based thermal analytics bundling displaces perpetual license software procurement. Agricultural monitoring operations across Brazil's sugarcane estates offer penetrable white-space for drone-as-a-service leasing models without heavy balance sheet requirements. ISO 21384-3 unmanned aircraft systems certification investment unlocks cross-border operational approvals for persistent solar-powered surveillance missions. For Investors and Strategic Acquirers: Carve-out targets emerge from defense sector hardware manufacturers with dormant commercial UAV divisions and stranded GB standards compliance capabilities. Long-term viability hinges on photovoltaic cell efficiency trajectories enabling four-plus-hour flight durations without ground intervention. Watch EASA-FAA harmonization progress on beyond-visual-line-of-sight parameters as inflection indicator for scalable deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Airframe Integration | Gallium arsenide cell architectures compress battery swap logistics across solar-powered drone fleets. |
| Beyond-Visual-Line-of-Sight Certification | FAA Part 107 waiver expansion and EASA open-category alignment unlock cross-jurisdictional operational approvals. |
| Drone-as-a-Service Leasing Models | Subscription-based thermal analytics bundling shifts buyer economics from capital expenditure toward operational expenditure frameworks. |
| Transmission Corridor Linear Inspection | Fixed-wing platforms capture margin pools in China's state grid expansion zones through long-range infrastructure monitoring. |
| ISO 21384-3 Standards Compliance | Global certification frameworks enable cross-border operational approvals for persistent solar-powered surveillance missions. |
Study Parameters
Cross-validation between primary interviews with fleet operations directors, utility procurement managers, and thermal analytics engineers and secondary validation through FAA waiver databases, EASA certification registries, and MIIT GB standards filings anchors the qualitative findings. Bottom-up triangulation aggregates segment-level deployment volumes across multirotor, solar-powered, fixed-wing, and hybrid architectures. Top-down calibration benchmarks aggregate market sizing against Inflation Reduction Act clean-tech procurement disclosures and EU Green Deal implementation tracking.
Calibration against historical deployment trajectories in China's industrial corridor and Denmark's offshore wind zones validates growth assumptions across the projection horizon. Segmentation modeling incorporates product type, application, end user, and technology dimensions with specific treatment of photovoltaic integration efficiency curves and beyond-visual-line-of-sight regulatory progression. CAGRs derive from installed base expansion rates and replacement cycle compression in persistent loitering architectures.
Sensitivities concentrate around lithium-polymer battery cost volatility, fragmented national airspace integration timelines, and photovoltaic cell efficiency benchmark revisions. Forecasts reflect documented assumptions on regulatory harmonization progress and energy-harvesting technology maturation. Quarterly review of FAA Part 107 waiver issuance rates and EASA open-category certification volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Wireless Charging Station Market
UAV
Europe Tactical UAV Market
UAV
Global Target Drone Market
UAV
Global Inspection Drones Market
UAV
Asia Pacific Small UAV Market
UAV
Drone Camera Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Auto-Follow Drone Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Miniature Drone Market
UAV
Global Aerial Imaging Market
UAV
Global Drone Data Services Market
UAV
Global Drone Services Market
UAV
North America Drone Software Market
UAV
UAV Simulator Software Market
UAV
North America Tactical UAV Market