
 UAV Drones Market | 2026-2036
UAV Drones Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Drones Market Intelligence
China's expanding manufacturing base for commercial drones is tilting the competitive landscape toward high-volume, cost-effective production. SZ DJI Technology Co., Ltd dominates the consumer and prosumer segments with its integrated hardware and software ecosystem. In contrast, Northrop Grumman Corporation specializes in high-altitude, long-endurance systems for military surveillance. Israel Aerospace Industries Ltd. competes with a focus on tactical drones and loitering munitions for defense clients.
Unmanned Aerial Vehicle (UAV) drones are aircraft without a human pilot onboard, operated through ground-based controllers or pre-programmed autonomous flight plans. These systems integrate components like GPS for navigation, gyrostabilizers for flight control, and payloads such as cameras or sensors. Rotary-wing models lead in commercial applications like surveying due to their hovering capability, while fixed-wing platforms are preferred by defense agencies for long-range reconnaissance. The integration of LIDAR sensors represents a high-margin technology segment, driven by precision mapping requirements from commercial operators.
Regulatory frameworks from the FAA in the United States and the EASA in Europe are establishing rules for beyond-visual-line-of-sight operations, which are critical for market expansion. Concurrently, China's MIIT influences manufacturing standards and spectrum allocation for UAV communication links, shaping hardware development. Stakeholder success will depend on navigating these evolving international air traffic management rules and securing certifications for autonomous systems.
Market Dynamics
The UAV drone market's central dynamic is the divergence between high-volume, cost-driven commercial manufacturing and specialized, performance-driven defense systems. This creates distinct value chains for consumer-grade quadcopters versus military-grade long-endurance platforms, even as dual-use technologies blur application boundaries.
Growth Catalysts
- Regulatory Frameworks:The establishment of rules for beyond-visual-line-of-sight (BVLOS) operations by regulators like the FAA and EASA is unlocking long-range applications such as pipeline inspection and package delivery.
- AI-Powered Analytics:The integration of artificial intelligence for real-time data processing enables advanced applications like precision agriculture, where drones can autonomously identify crop stress or pest infestation.
- National Industrial Policies:Government support, such as policies from China's MIIT to promote smart logistics and urban air mobility, is accelerating infrastructure development and creating concentrated demand for commercial drone fleets.
Market Restraints
- Spectrum Scarcity:Competition for and regulation of radio frequency spectrum for command-and-control links and data downlinks create operational constraints, limiting the density of drone operations in urban areas.
- Payload and Endurance Limits:The energy density of current battery technology restricts flight times and the weight of sensor payloads, particularly for smaller rotary-wing models, limiting their utility for extended surveillance missions.
- Sensor Cost Barriers:The high acquisition cost of advanced payloads, such as survey-grade LIDAR or hyperspectral sensors, remains a significant barrier for smaller enterprises in sectors like civil engineering and environmental monitoring.
Strategic Opportunities
- Drone-in-a-Box Systems:Fully automated, remotely deployable drone stations offer significant potential for autonomous site security, asset monitoring, and emergency response without requiring an on-site pilot.
- 5G and Edge Computing Convergence:The combination of high-bandwidth, low-latency 5G networks with onboard edge computing can enable new services like real-time 4K video streaming and complex autonomous navigation in dense environments.
- Agricultural Penetration in Southeast Asia:Vast agricultural lands and a need for improved crop yields present a major opportunity for deploying drones for spraying, seeding, and monitoring, especially in countries with large farming sectors.
Industry Challenges
- Certified Pilot Shortage:A persistent gap exists between the supply of commercially licensed and experienced UAV pilots and the demand from enterprises scaling up their drone programs for complex operations.
- Data Integration Complexity:Integrating vast quantities of drone-captured data, including imagery and sensor readings, into existing enterprise GIS and asset management workflows remains a significant technical and software hurdle.
- Air Traffic Management Standardization:The lack of a globally harmonized Unmanned Traffic Management (UTM) system complicates the development of interoperable technologies and hinders safe, large-scale autonomous drone operations across different jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Drones Market |
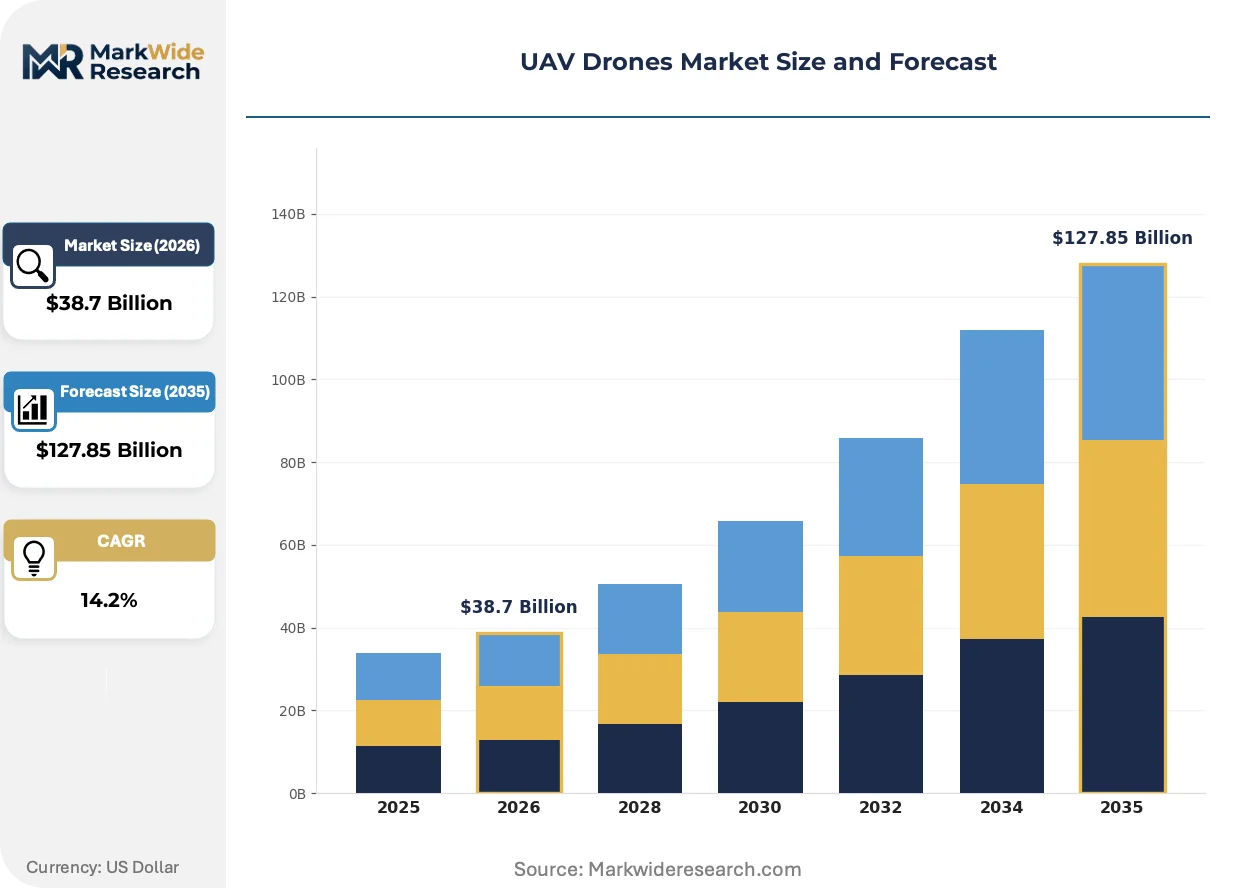
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano Drones, Tactical Drones Technology: GPS Navigation, Obstacle Avoidance, Thermal Imaging, AI-Powered Analytics, LIDAR Sensors Application: Agricultural Monitoring, Infrastructure Inspection, Search and Rescue, Environmental Conservation, Surveying End User: Defense Agencies, Commercial Operators, Film Production, Disaster Management Teams, Scientific Research Organizations |
| Companies Covered | SZ DJI Technology Co., Ltd, Northrop Grumman Corporation, General Atomics Aeronautical Systems, Lockheed Martin Corporation, AeroVironment Inc., RTX Corporation, Israel Aerospace Industries Ltd., Teledyne FLIR LLC, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Drones Market Strategic Shifts & Innovations
Autonomy in flight and data analysis is the core theme transforming the UAV drone market. This shift moves the technology's value from simple aerial imaging to integrated, intelligent decision-support systems that operate with minimal human intervention.
Onboard AI processors provide drones with real-time decision-making capabilities independent of ground control links. Commercial operators in agriculture and infrastructure inspection are rapidly adopting this for tasks like automated fault detection. This technology is digitizing aerial data workflows, transforming drones from simple collection tools into platforms for immediate, on-site analysis.
The European Union Aviation Safety Agency (EASA) is implementing its U-space regulatory framework to manage drone traffic. This initiative establishes a digital infrastructure for ensuring safe coexistence between unmanned and manned aircraft, particularly in urban and suburban skies. The commercial delivery and urban air mobility segments are most affected, as their business models depend on gaining certification to operate within this managed airspace.
A notable shift in acquisition patterns is the move from outright hardware purchasing to adopting Drones-as-a-Service (DaaS) models. This trend disrupts traditional equipment sales channels, as enterprise clients in construction and mining now pay for data outcomes on a subscription basis. This model is most prominent in North America and Europe, where companies prioritize operational expenditure over capital investment.
UAV Drones Market Segmentation
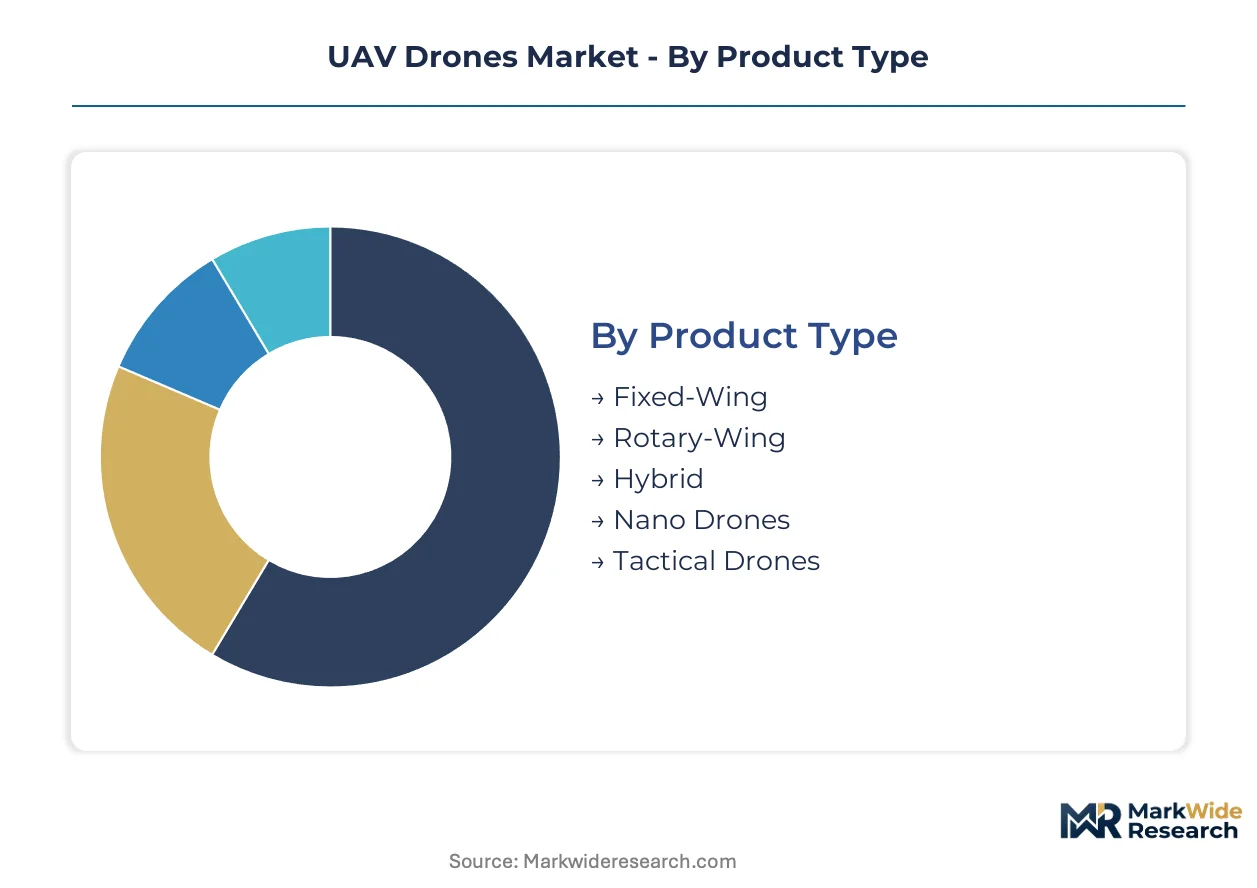
The UAV Drones Market segmentation reveals how diverse technological advancements and application-specific demands shape product development and market penetration. Understanding these distinct segments is crucial for stakeholders to identify areas of concentrated demand and emerging growth opportunities across global markets.
Product Type:
The intensity of after-sales service requirements often dictates the commercial viability across drone product types, influencing operator investment decisions.
- Rotary-Wing:These drones feature multiple rotors, enabling vertical takeoff and landing, hovering capabilities, and precise maneuverability in confined spaces. Demand concentrates in commercial applications like surveying and infrastructure inspection due to their operational flexibility.
- Fixed-Wing:Characterized by wings that generate lift, these platforms offer longer flight durations and higher speeds, making them suitable for covering large areas. Defense agencies prefer fixed-wing drones for long-range reconnaissance missions due to their endurance.
- Hybrid:Combining features of both fixed-wing and rotary-wing designs, hybrid drones offer vertical takeoff and landing with the endurance of winged flight.
- Nano Drones:These are extremely small and lightweight drones, primarily used for indoor inspection, surveillance, or tactical reconnaissance in tight spaces.
- Tactical Drones:Designed for military and security operations, these drones provide intelligence, surveillance, and reconnaissance capabilities in combat zones.
By volume, Rotary-Wing models lead the market. By growth pace, Hybrid designs are ahead.
Technology:
Cost tiers for integrated drone technologies directly influence accessibility and deployment scales for commercial operators.
- AI-Powered Analytics:This technology integrates artificial intelligence algorithms directly into drone systems or ground stations for real-time data processing and automated decision-making. Demand concentrates in precision agriculture and infrastructure inspection, where autonomous fault detection is critical.
- LIDAR Sensors:Light Detection and Ranging (LIDAR) sensors use pulsed laser light to measure distances, generating highly accurate 3D maps and elevation models. Commercial operators in civil engineering drive demand for LIDAR due to its precision mapping requirements.
- GPS Navigation:Global Positioning System (GPS) modules provide precise location data, enabling autonomous flight paths and accurate mapping capabilities for drones.
- Obstacle Avoidance:This technology uses sensors like ultrasonic, infrared, or vision systems to detect and bypass obstacles, enhancing flight safety and operational autonomy.
- Thermal Imaging:Thermal cameras detect infrared radiation, allowing drones to identify heat signatures for applications like search and rescue, security, and agricultural health monitoring.
The integration of AI-Powered Analytics significantly enhances operational efficiency across diverse applications.
Application:
The specific application requirements drive innovation in sensor payloads and flight autonomy for UAV drones.
- Agricultural Monitoring:Drones equipped with multispectral or hyperspectral cameras assess crop health, monitor irrigation, and detect pest infestations, optimizing farm management. Demand concentrates in regions with large agricultural lands, such as Southeast Asia, where improved crop yields are a priority.
- Infrastructure Inspection:Drones survey critical infrastructure like pipelines, power lines, bridges, and wind turbines, identifying defects or maintenance needs. Regulatory frameworks from the FAA and EASA for BVLOS operations are unlocking long-range inspection capabilities.
- Search and Rescue:Drones assist emergency services by providing aerial views of disaster zones, locating missing persons, and delivering supplies in inaccessible areas.
- Environmental Conservation:Drones monitor wildlife populations, track deforestation, assess pollution levels, and aid in ecological research and land management.
- Surveying:Drones capture high-resolution aerial imagery and generate precise topographic maps, used in construction, urban planning, and geological studies.
Infrastructure Inspection and Agricultural Monitoring applications collectively represent the steepest expansion trajectory for commercial drone services.
End User:
Distinct end-user profiles shape procurement strategies, from specialized defense contracts to high-volume commercial fleet acquisitions.
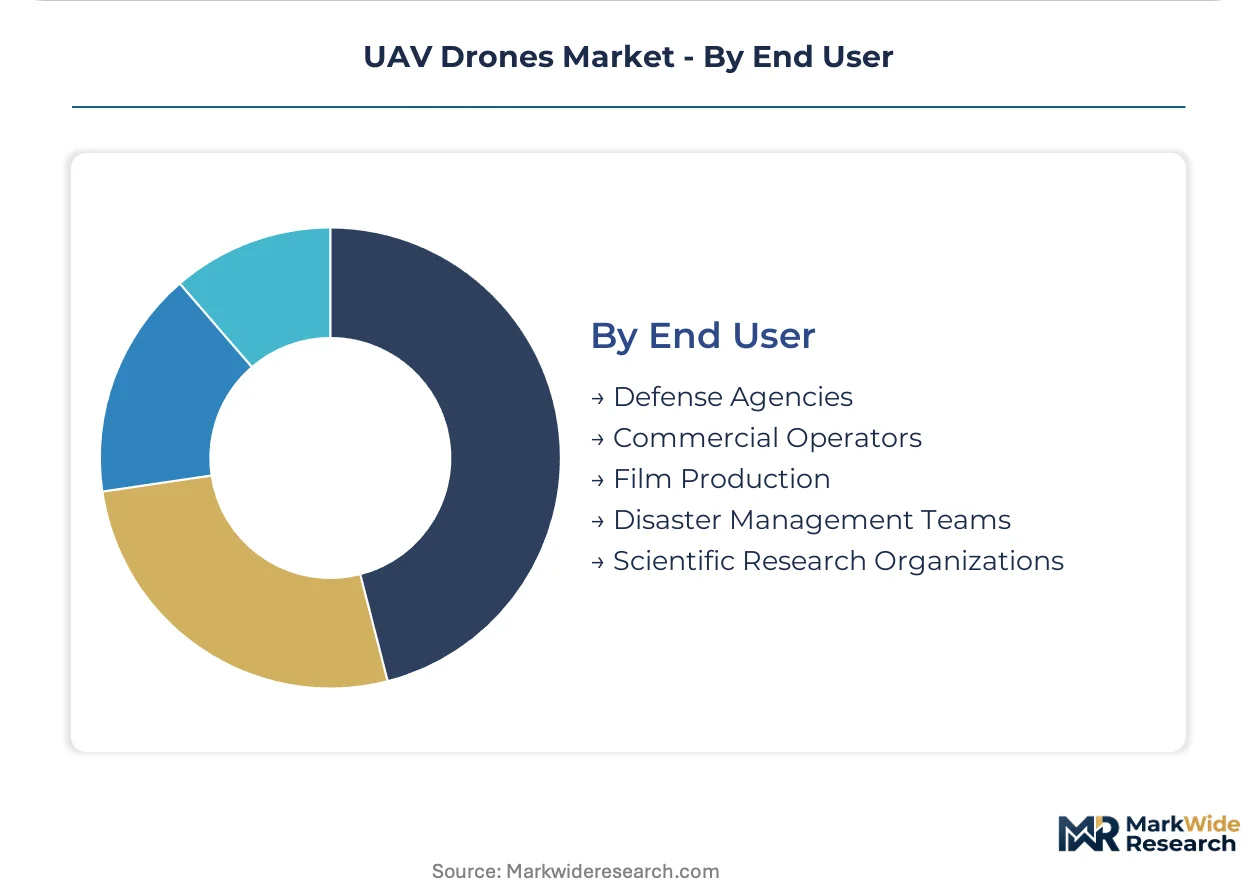
- Commercial Operators:This segment includes businesses and enterprises utilizing drones for various commercial services, such as logistics, construction, media, and agriculture. Commercial operators prioritize cost-effectiveness and scalability in their drone fleets.
- Defense Agencies:Government military and intelligence organizations procure drones for surveillance, reconnaissance, target acquisition, and combat operations. Defense agencies prioritize specialized performance and robust security features for their systems.
- Film Production:Film studios and media companies use drones for capturing cinematic aerial footage, offering dynamic perspectives previously achievable only with helicopters.
- Disaster Management Teams:These teams deploy drones for rapid damage assessment, situational awareness, and coordinating relief efforts during natural disasters or emergencies.
- Scientific Research Organizations:Universities and research institutions employ drones for data collection in fields like meteorology, glaciology, and atmospheric science.
Commercial Operators exhibit the broadest market influence, while Defense Agencies command the highest per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global UAV Drones market exhibits a notable supply-side concentration, particularly in manufacturing capabilities. This concentration influences global pricing and product availability across diverse applications. Key regions drive both technological advancement and demand for autonomous aerial systems.
China
China's demand for commercial drones is fueled by national policies promoting smart logistics and urban air mobility. The Ministry of Industry and Information Technology (MIIT) influences manufacturing standards and spectrum allocation, shaping hardware development. Shenzhen serves as a global manufacturing base, producing high-volume, cost-effective commercial drone systems.
United States
The United States sees significant demand for infrastructure inspection and defense applications of UAVs. The Federal Aviation Administration (FAA) is establishing rules for beyond-visual-line-of-sight operations, critical for market expansion. Silicon Valley and other tech hubs concentrate on AI-powered analytics and advanced sensor integration for drone platforms.
Germany
Germany's commercial operators drive demand for industrial inspection and precision agriculture drones. The European Union Aviation Safety Agency (EASA) implements its U-space regulatory framework to manage drone traffic. Bavaria, with its strong automotive and aerospace industries, fosters innovation in drone component manufacturing and system integration.
United Kingdom
The United Kingdom experiences demand for public safety, commercial delivery, and environmental monitoring applications. EASA regulatory alignment impacts certification for autonomous systems and urban air mobility. Cranfield, a prominent aerospace research hub, contributes to advanced drone technology development and testing.
Israel
Israel's market concentrates on military surveillance, reconnaissance, and loitering munitions for defense clients. The Defense Ministry's procurement strategies prioritize specialized performance and robust security features for tactical drones. Tel Aviv's defense technology clusters develop cutting-edge UAV systems and associated command-and-control technologies.
UAV Drones Market Key Industry Players
Platform integrators command the system tier, offering complete hardware and software ecosystems, while component specialists sit upstream, supplying critical sensors and propulsion systems. The market structure exhibits a tiered consolidation, with a few dominant players in both consumer and military segments. Strategic archetypes include high-volume commercial manufacturers and specialized defense contractors. Portfolio diversification into dual-use technologies and strategic partnerships are dominant competitive moves.
Specialists in integrated ecosystems include Shenzhen-based SZ DJI Technology Co., Ltd., which exemplifies market leadership in consumer and prosumer segments. Northrop Grumman Corporation, a US-based entity, represents the high-altitude, long-endurance military systems archetype. Israel Aerospace Industries Ltd., an Israeli company, occupies a position focused on tactical drones and loitering munitions for defense clients. These entities anchor distinct competitive vectors within the global UAV Drones market.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd |
| Northrop Grumman Corporation |
| General Atomics Aeronautical Systems |
| Lockheed Martin Corporation |
| AeroVironment Inc. |
| RTX Corporation |
| Israel Aerospace Industries Ltd. |
| Teledyne FLIR LLC |
| Elbit Systems Ltd. |
| Others |
Cost & Logistics Intelligence
China's significant undercapacity in advanced sensor manufacturing for UAV drones drives supplier behavior, influencing global pricing postures for high-precision mapping and surveillance systems. This utilization imbalance creates distinct market dynamics between high-volume commercial components and specialized defense-grade technologies.
Pricing Analysis
The European Union Aviation Safety Agency (EASA) U-space framework dictates the pricing tier structure for certified autonomous systems, particularly for urban air mobility. Pricing models often combine subscription-based Drones-as-a-Service (DaaS) for commercial operators with project-based fees for specialized defense contracts. Price differentiation stems from the level of autonomy and the integration of advanced payloads like survey-grade LIDAR sensors. Pricing softness affects the consumer and prosumer segments due to intense competition from Shenzhen-based manufacturers. Commercial operators exhibit moderate price sensitivity, balancing operational expenditure against data accuracy requirements.
Supply Chain Analysis
Contract manufacturing concentration in China, alongside specialized component production in the United States and Israel, underpins the UAV drone supply chain. Key raw material dependencies include high-energy density battery cells and precision optical components for cameras and LIDAR sensors. A structural risk involves single-source vulnerability for advanced AI processors and specialized gyrostabilizers. Distribution runs through direct sales channels for defense agencies and a hybrid model of direct sales and DaaS providers for commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAV Drones market presents a defensive-moat story, primarily due to regulatory entrenchment and the high switching costs associated with integrating complex autonomous systems into enterprise workflows.
For Market Incumbents:Pre-empt emerging regulatory shifts by investing in certification pathways for beyond-visual-line-of-sight (BVLOS) operations across multiple geographies. Consolidate market share in core segments like infrastructure inspection through strategic acquisitions of specialized software analytics firms, mitigating the threat from new entrants focused solely on data processing. Deepen vertical integration into critical component manufacturing, such as advanced sensor arrays, to control supply and enhance performance differentiation.
For New Entrants and Emerging Players:Regional agricultural monitoring in Southeast Asia represents the most penetrable entry point for new drone service providers. Target niche applications requiring specialized data analytics, such as autonomous pest detection or yield optimization, where established players have yet to fully penetrate. A go-to-market angle focused on Drones-as-a-Service (DaaS) models with outcome-based pricing can lower initial capital expenditure barriers for local farming enterprises.
For Investors and Strategic Acquirers:Capital is best deployed toward mid-cap platform integrators specializing in dual-use technologies with proven commercial and defense applications. These entities offer balanced growth potential and reduced reliance on a single market segment. Long-term viability over a five-to-ten-year window favors companies with strong intellectual property in AI-powered analytics and robust regulatory compliance frameworks. The signal to watch is the acceleration of standardized Unmanned Traffic Management (UTM) systems, which will unlock large-scale autonomous operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI Analytics Firms | Integrates advanced data processing capabilities, enhancing decision-support systems for commercial operators. |
| Investment in BVLOS Certification | Unlocks long-range applications like pipeline inspection, expanding market reach under FAA and EASA rules. |
| Development of Hybrid Drone Platforms | Combines rotary-wing flexibility with fixed-wing endurance, addressing diverse application requirements for defense. |
| Expansion of Drones-as-a-Service Models | Lowers entry barriers for commercial operators, shifting from capital expenditure to operational expenditure. |
| Strategic Partnerships for 5G Integration | Enables real-time data streaming and complex autonomous navigation in dense urban environments. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with industry stakeholders and rigorous secondary validation. Interviews included commercial drone fleet managers, defense procurement specialists, AI software developers, and regulatory affairs experts from the FAA and EASA. Secondary data sources encompassed company financial filings, industry association reports, government regulatory documents, and specialized technology publications, triangulated through bottom-up and top-down analyses.
The calibration approach informed the analytical framework, modeling market segments across the analysis window through product type, technology, application, end-user, and key geographic regulatory zones. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical market trends, technological adoption curves, and projected regulatory impact. Industry-specific forecast inputs included anticipated battery energy density improvements and the timelines for U-space framework implementation.
Stress conditions across geopolitical stability, spectrum availability, and AI regulatory frameworks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continued technological advancements and a progressive regulatory environment. Cross-checking against national aviation authority reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Smart Commercial Drones Market
UAV
North America Drones Market
UAV
Toy Drones Market
UAV
Global Aerial Imaging Market
UAV
Multirotor Drones Market
UAV
Global Drone Software Market
UAV
UAV Payload Market
UAV
Global Drone Light Shows Market
UAV
Global Multirotor UAV Market
UAV
Tactical UAV Market
UAV
UAV Simulator Market
UAV
Global Renewable Drones Market
UAV
UAV GNSS Antenna Market
UAV
Portable Drone Market
UAV
UAV Navigation Systems Market
UAV
Global Stratospheric UAV Payload Technology Market