
 Drone Defense System Market | 2026-2036
Drone Defense System Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Defense System Market Intelligence
Counter-small-UAS capability standards above Group 1 threat thresholds is redrawing procurement priorities across defense ministries. Dedrone Inc leverages persistent RF analytics to anchor urban airspace monitoring contracts in European capitals. Rheinmetall AG sustains its position through in-house production of directed-energy subsystems for mobile platform integration. RTX Corporation differentiates via software-defined signal intelligence architectures that merge electronic warfare with civilian air traffic management protocols.
Drone defense systems encompass layered detection-to-defeat architectures combining radar, electro-optical, and RF sensing modalities with kinetic or non-kinetic neutralization mechanisms, typically operating across X-band through Ku-band frequencies with sub-degree tracking accuracy to intercept targets below 400 feet AGL and sub-55-pound mass thresholds. Their primary purpose is protecting fixed-site critical infrastructure, mobile military formations, and mass-gathering venues from unauthorized unmanned aerial vehicle incursions. Anti-drone systems and jammers currently dominate deployed inventory, though laser weapons represent the fastest-growing product category as solid-state fiber laser costs decline and thermal management improves. Military end users command the largest budget share, while homeland security applications exhibit the steepest growth trajectory as domestic agencies replicate battlefield detection networks for border and event protection.
The FAA's remote ID rule and evolving counter-UAS statutory authorities shape domestic product certification pathways, while EASA's drone regulation framework and EU Green Deal dual-use technology provisions influence European procurement specifications. Military buyers now require interoperability with NATO STANAG 4671 and national encrypted datalinks, compressing vendor qualification timelines. Stakeholders must monitor how emerging directed-energy export control classifications and software vulnerability disclosure mandates alter competitive access to allied defense markets.
Market Dynamics
Layered counter-UAS architectures are compressing procurement cycles as NATO defense ministries mandate interoperability between radar, RF, and directed-energy subsystems under unified command protocols.
Growth Catalysts
- EU Drone Strategy 2.0:The European Commission's framework mandates urban airspace monitoring networks across member states, creating standardized procurement specifications for detection-to-defeat systems.
- Solid-state fiber lasers:Declining thermal management costs and improved beam quality are accelerating deployment of mobile directed-energy platforms for Group 1 drone neutralization.
- Critical infrastructure operators:Federal facilities in the United States face escalating aerial intrusion threats, driving demand for persistent perimeter monitoring integrated with existing security operations centers.
Market Restraints
- Rare-earth magnet supply:Chinese export controls on neodymium and dysprosium concentrate input costs for precision gimbal motors and radar positioning systems.
- Directed-energy export classifications:Emerging Wassenaar Arrangement controls on high-power laser subsystems restrict vendor access to allied defense procurement channels.
- Spectral congestion:Civilian 5G C-band expansion overlaps with Ku-band radar allocations, degrading detection margins in dense electromagnetic environments.
Strategic Opportunities
- Software-defined architectures:Signal intelligence platforms that merge electronic warfare protocols with civilian air traffic management systems open dual-use contracting pathways.
- Border protection agencies:Homeland security applications replicate battlefield detection networks for coastal and frontier monitoring, outpacing military budget growth rates.
- EU Green Deal dual-use provisions:Technology transfer incentives for energy-efficient solid-state lasers reduce qualification barriers for European system integrators.
Industry Challenges
- RF engineer scarcity:Specialized talent for microwave circuit design and phased-array calibration commands premium compensation, extending development timelines for Ku-band subsystems.
- NATO STANAG 4671 integration:Encrypted datalink interoperability mandates compress vendor qualification windows, requiring accelerated firmware certification cycles.
- Legacy radar retrofit:Mechanical scanning systems in existing air defense networks lack software interfaces for drone-specific track filters, forcing parallel infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Defense System Market |
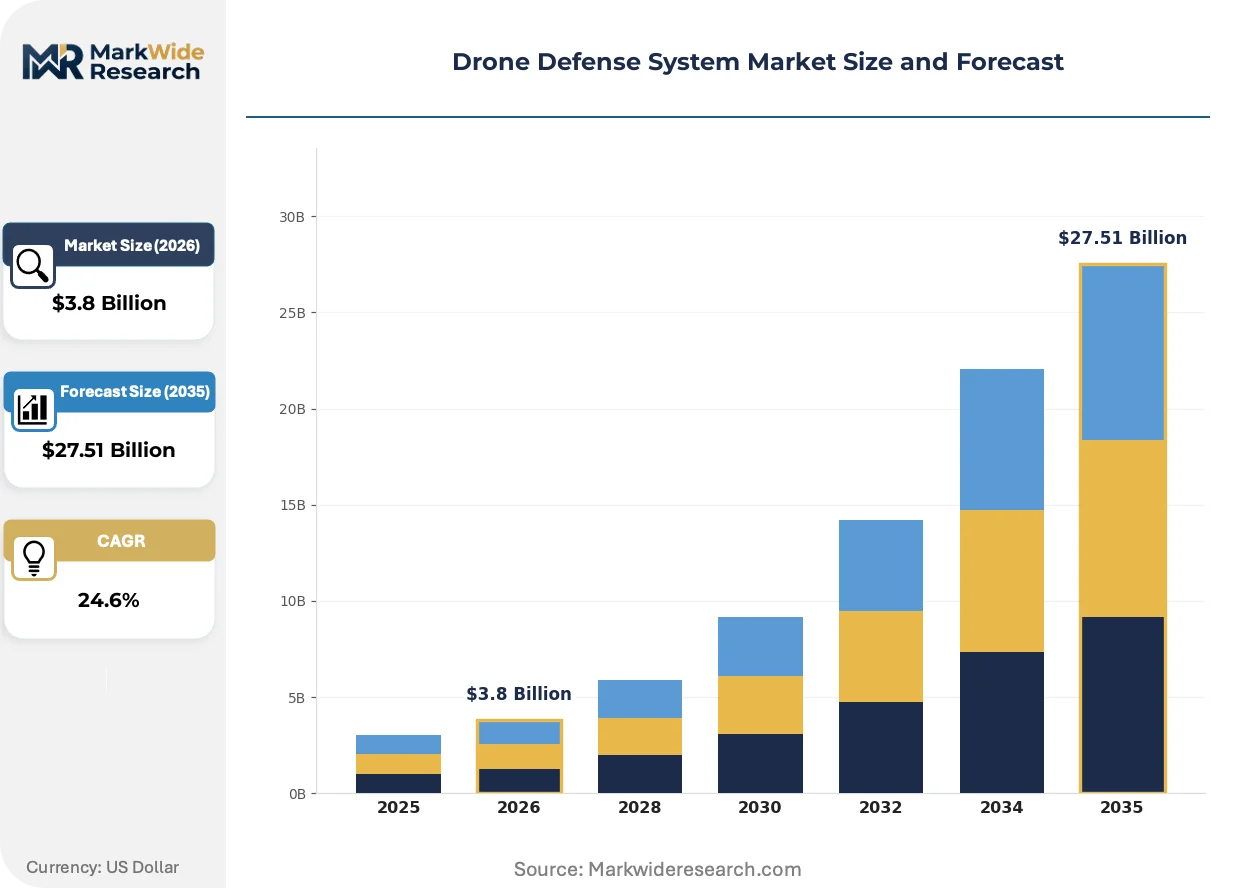
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Drone Systems, Jammers, Laser Weapons, Interceptors End User: Military, Homeland Security, Private Security, Critical Infrastructure Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Technology: Radar Systems, Electro-Optical Systems, Signal Intelligence, Countermeasure Software |
| Companies Covered | Dedrone Inc, DroneShield, Blighter Surveillance Systems Ltd, Aaronia AG, Leonardo S.P.A., Rheinmetall AG, Northrop Grumman, RTX Corporation, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Defense System Market Strategic Shifts & Innovations
Convergence between electronic warfare and civilian airspace governance is redefining system architectures, with software-defined platforms displacing hardware-specific legacy designs across procurement portfolios.
High-power microwave subsystems are displacing kinetic interceptors as the preferred defeat mechanism for swarming Group 1 threats. Naval surface warfare centers and expeditionary ground units are accelerating adoption of vehicle-mounted HPM arrays. This displacement compresses ammunition logistics chains while reducing collateral damage risks in urban proximity operations.
EASA's drone regulation framework and evolving remote identification mandates are tightening airworthiness certification requirements for counter-UAS platforms operating in civilian airspace. European system integrators must now demonstrate electromagnetic compatibility with commercial aviation transponder protocols. Urban air mobility corridors in Germany and France are emerging as the most regulated test environments for integrated detect-and-avoid architectures.
Defense procurement offices are unbundling detection and defeat subsystems, awarding separate contracts for sensor networks and neutralization modules rather than integrated turnkey platforms. Systems integrators accustomed to prime contractor roles now compete as subsystem vendors. This pattern is most visible in United States federal contracting, where Customs and Border Protection and domestic security agencies replicate military layered architectures through fragmented acquisition vehicles.
Drone Defense System Market Segmentation
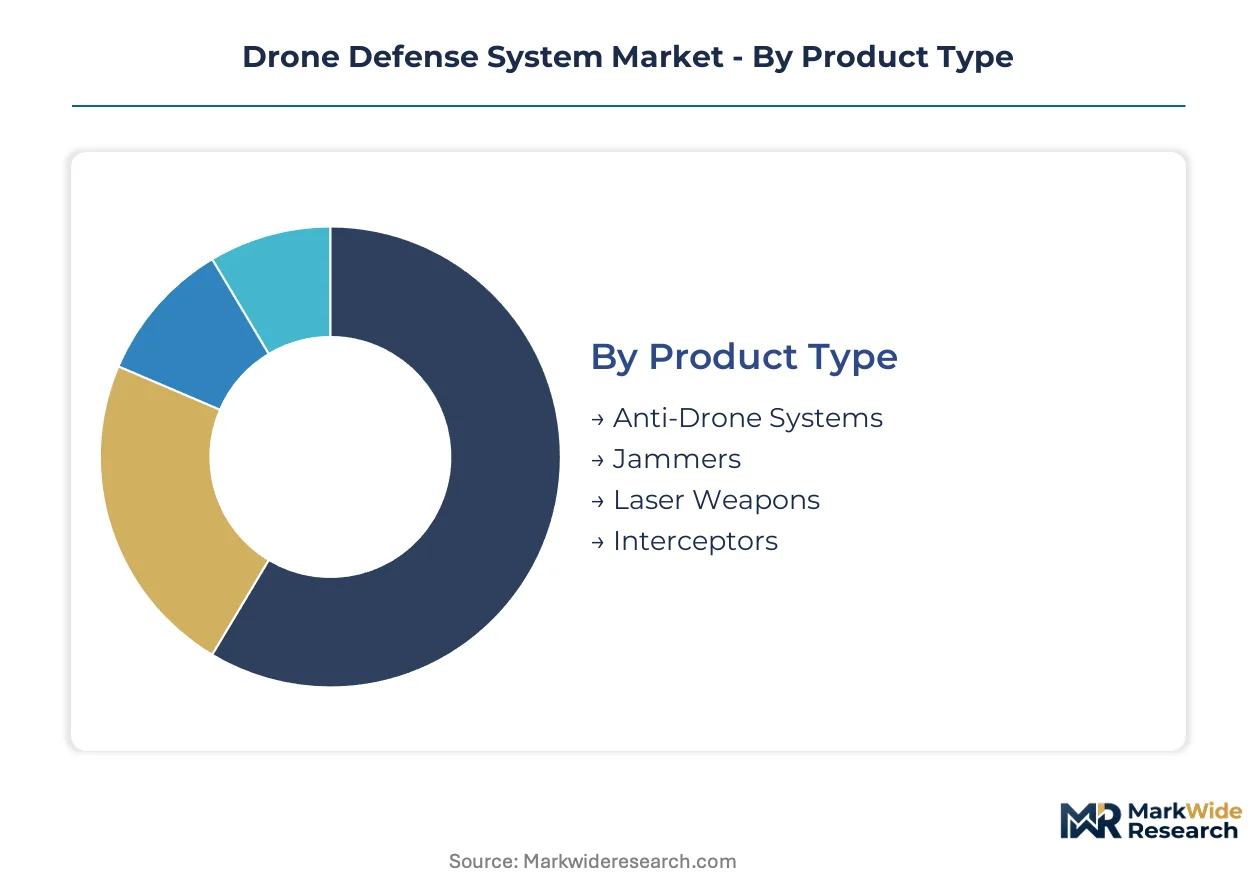
Segmentation in the drone defense system market reveals how procurement channels diverge between military integrators and civilian security operators. Each dimension—product, end user, deployment mode, and sensing technology—carries distinct qualification barriers and contracting pathways that reshape vendor go-to-market strategies.
Product Type:
Military procurement channels favor integrated platforms with classified datalink compatibility, while homeland security and private sector buyers increasingly unbundle detection and defeat subsystems through separate acquisition vehicles.
- Anti-Drone Systems:Integrated detection-to-defeat platforms combining radar, RF sensing, and neutralization modules into unified command architectures. Military end users in NATO member states concentrate procurement here, driven by STANAG 4671 interoperability mandates that compress vendor qualification timelines.
- Jammers:RF-based electronic countermeasure devices operating across X-band through Ku-band frequencies to disrupt drone command links and navigation systems. Homeland security agencies in the United States replicate battlefield detection networks for border protection, outpacing military budget growth in this segment.
- Laser Weapons:Solid-state fiber laser platforms for directed-energy neutralization of Group 1 threats.
- Interceptors:Kinetic defeat mechanisms including net-capture systems and kamikaze drones.
By volume, jammers lead deployed inventory across all end-use sectors. By growth pace, laser weapons are climbing the fastest as thermal management costs decline and mobile platform integration matures.
End User:
Cost tier stratification separates military-grade encrypted systems from commercial perimeter monitoring solutions, with price differentials exceeding an order of magnitude between equivalent detection capabilities.
- Military:Layered counter-UAS architectures requiring interoperability with NATO encrypted datalinks and national command systems. Procurement concentrates in the United States, Germany, and France, where defense ministries mandate unified command protocols across radar, RF, and directed-energy subsystems.
- Homeland Security:Persistent perimeter monitoring for federal facilities and border protection. Customs and Border Protection in the United States accelerates adoption through fragmented acquisition vehicles that unbundle sensor networks from neutralization modules.
- Private Security:Event protection and corporate facility monitoring with simplified RF detection.
- Critical Infrastructure:Power generation, telecommunications, and transportation hub protection integrated with existing security operations centers.
By budget share, military commands the largest allocation. By expansion trajectory, homeland security applications are gaining share fastest as domestic agencies scale battlefield-proven architectures.
Deployment:
Application context determines architecture—fixed-site critical infrastructure demands persistent perimeter coverage, while expeditionary military formations prioritize rapid redeployment and minimal logistics footprint.
- On-Premise:Permanent installations at fixed-site critical infrastructure with dedicated power and network backbones. Federal facilities in the United States drive concentration here, facing escalating aerial intrusion threats that demand integration with existing security operations centers.
- Mobile:Vehicle-mounted and man-portable systems for expeditionary ground units and naval surface warfare centers. High-power microwave arrays are displacing kinetic interceptors here, compressing ammunition logistics chains while reducing collateral damage risks.
- Cloud-Based:Centralized data fusion with distributed edge sensors for urban airspace monitoring networks.
- Hybrid:Local processing with cloud backup for resilience in contested electromagnetic environments.
By installed base, on-premise systems dominate. By deployment velocity, mobile platforms are expanding most quickly as solid-state directed-energy subsystems shrink thermal management requirements.
Technology:
Supply concentration in phased-array radar and solid-state laser subsystems creates qualification bottlenecks, while software-defined signal intelligence platforms open dual-use contracting pathways through civilian air traffic management integration.
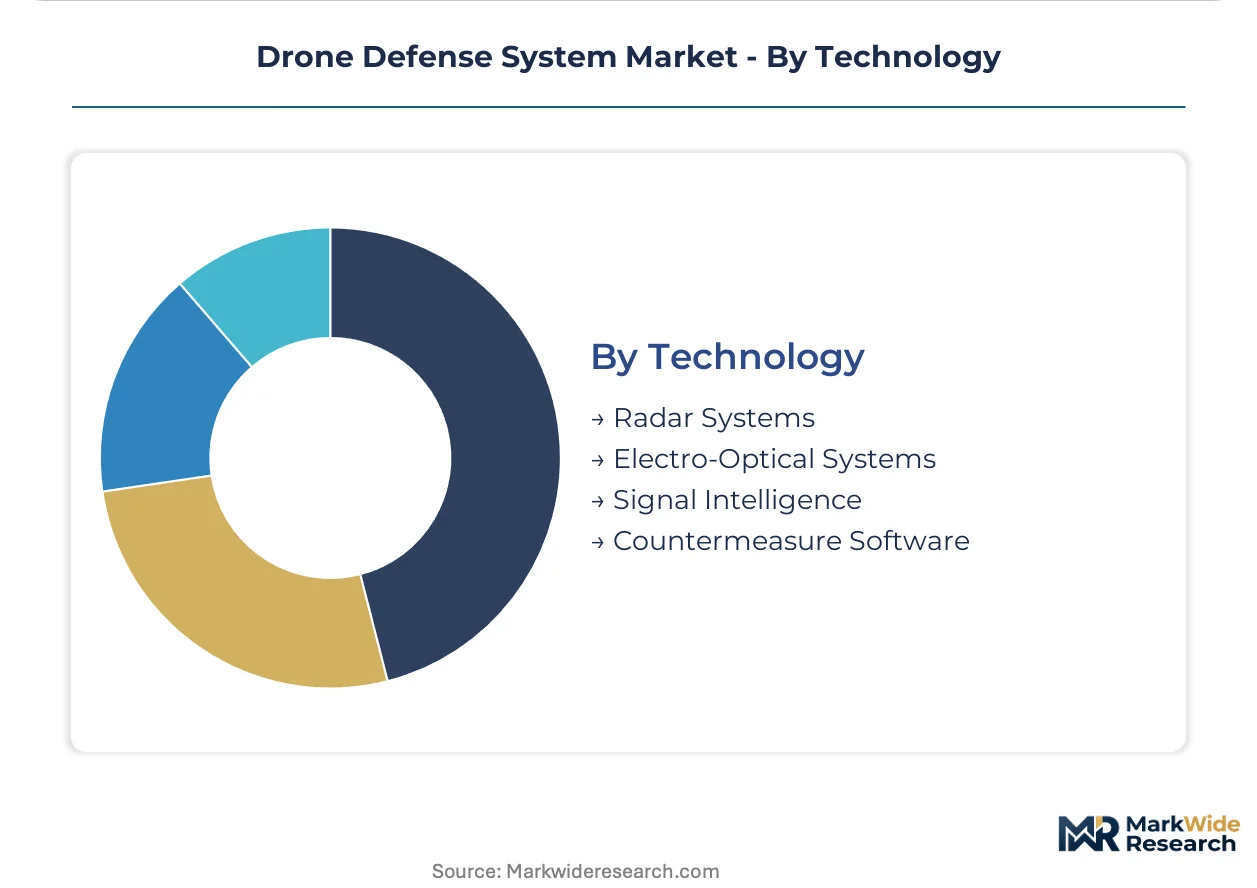
- Radar Systems:X-band through Ku-band phased-array and mechanical scanning platforms with sub-degree tracking accuracy. The EU Drone Strategy 2.0 mandates urban airspace monitoring networks across member states, creating standardized procurement specifications that favor interoperable radar architectures.
- Signal Intelligence:Software-defined RF analytics merging electronic warfare protocols with civilian air traffic management systems. EASA's drone regulation framework tightens airworthiness certification requirements here, forcing electromagnetic compatibility demonstrations with commercial aviation transponder protocols.
- Electro-Optical Systems:Thermal and daylight camera arrays for visual confirmation and fine tracking.
- Countermeasure Software:AI-enabled threat classification and autonomous engagement authorization systems.
By procurement volume, radar systems lead technology acquisition. By technology transition velocity, signal intelligence platforms are advancing fastest as defense ministries unbundle software from hardware-specific legacy designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision gimbal motor and solid-state laser subsystem manufacturing clusters in Germany, the United States, and Israel supply NATO-aligned procurement channels. Defense ministries in these countries compress vendor qualification timelines through STANAG 4671 interoperability mandates.
United States
Federal critical infrastructure operators and Customs and Border Protection accelerate adoption of layered counter-UAS architectures. The FAA's remote ID rule and evolving counter-UAS statutory authorities shape domestic product certification pathways. Washington D.C. and Southwest border states concentrate deployment of persistent perimeter monitoring systems integrated with security operations centers.
Germany
The Bundeswehr mandates unified command protocols across radar, RF, and directed-energy subsystems for mobile platform integration. EU Green Deal dual-use technology provisions reduce qualification barriers for energy-efficient solid-state lasers. Bavaria and North Rhine-Westphalia host Rheinmetall AG's in-house directed-energy production facilities serving NATO procurement.
France
The Direction Générale de l'Armement unbundles detection and defeat subsystems through fragmented acquisition vehicles. EASA's drone regulation framework tightens airworthiness certification requirements for electromagnetic compatibility with commercial aviation. Île-de-France and Provence-Alpes-Côte d'Azur urban air mobility corridors emerge as regulated test environments for detect-and-avoid architectures.
Israel
Defense procurement agencies prioritize interoperability with national encrypted datalinks and battlefield-proven detection networks. The country's national defense regulator accelerates firmware certification cycles for software-defined signal intelligence platforms. Tel Aviv and Haifa metropolitan clusters concentrate RF analytics and microwave circuit design talent for Ku-band subsystem development.
United Kingdom
Home Office border protection agencies replicate military layered architectures for coastal monitoring, outpacing military budget growth in jammer procurement. Blighter Surveillance Systems Ltd anchors domestic radar subsystem production. London and Southeast England concentrate urban airspace monitoring contracts leveraging persistent RF analytics.
Drone Defense System Market Key Industry Players
Concentration sits with defense primes possessing in-house directed-energy production and software-defined signal intelligence capabilities. Tiered structure separates classified-datalink military integrators from commercial perimeter monitoring specialists. Three archetypes dominate: radar-RF subsystem vendors, solid-state laser platform builders, and software-defined electronic warfare fusion providers. Competitive moves center on NATO STANAG 4671 interoperability certification and unbundled subsystem contracting for homeland security channels.
Within the defense prime tier, RTX Corporation and Lockheed Martin exemplify software-defined architecture providers merging electronic warfare with civilian air traffic management protocols. Rheinmetall AG occupies a position among European-directed energy specialists with captive solid-state fiber laser production. Dedrone Inc represents the RF analytics archetype securing urban airspace monitoring contracts through persistent signal intelligence platforms.
| Leading Market Players |
|---|
| Dedrone Inc |
| DroneShield |
| Blighter Surveillance Systems Ltd |
| Aaronia AG |
| Leonardo S.P.A. |
| Rheinmetall AG |
| Northrop Grumman |
| RTX Corporation |
| Lockheed Martin |
| Others |
Cost & Logistics Intelligence
Twenty-four-week lead times for Ku-band phased-array components concentrate pricing power with German and Israeli subsystem vendors who maintain captive radar foundry capacity. Military buyers absorbing NATO STANAG 4671 certification costs face tiered procurement structures that separate encrypted datalink platforms from commercial perimeter monitoring alternatives.
Pricing Analysis
The FAA's remote ID rule and evolving counter-UAS statutory authorities dictate the pricing tier structure across detection-to-defeat platforms. Three-tier pricing structure across military-encrypted, dual-use certified, and commercial-grade levels separates procurement channels, with volume scale and STANAG 4671 interoperability commanding premium positioning. Cost compression in commercial jammer segments is intensifying because unbundled subsystem contracting allows homeland security agencies to fragment acquisition vehicles. Private security operators exhibit the highest price sensitivity, while defense primes with in-house directed-energy production capture margin insulation.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for rare-earth magnet shipments originating from Chinese processing facilities. Precision gimbal motor manufacturing draws from German, United States, and Israeli production clusters, with neodymium and dysprosium sourcing tethered to concentrated Asian refining capacity. Single-source vulnerability in solid-state fiber laser diode supply creates qualification bottlenecks for mobile directed-energy platforms. Distribution runs through NATO-aligned defense procurement channels with fragmented acquisition vehicles for homeland security applications.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around NATO STANAG 4671 interoperability creates defensive moats for vendors with accelerated firmware certification cycles. Switching costs escalate as military buyers mandate unified command protocols across layered counter-UAS architectures.
For Market Incumbents: Consolidate software-defined signal intelligence capabilities through in-house RF analytics development, defending against emerging subsystem vendors unbundling detection from defeat modules. Capacity addition in Bavaria and North Rhine-Westphalia reinforces Rheinmetall AG's captive solid-state laser production position. Certification investment in FAA and EASA airworthiness pathways preserves channel control against commercial perimeter monitoring specialists. For New Entrants and Emerging Players: Lead with software-defined architectures that merge electronic warfare protocols with civilian air traffic management systems, penetrating the most accessible homeland security segment where Customs and Border Protection replicates battlefield detection networks. Cloud-based data fusion with distributed edge sensors offers a direct go-to-market angle for urban airspace monitoring contracts in European capitals lacking persistent RF analytics infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates spinning off non-core counter-UAS divisions lacking NATO encrypted datalink compatibility. Long-term viability centers on vendors controlling both Ku-band phased-array production and directed-energy thermal management IP. Monitor EASA electromagnetic compatibility mandates as the inflection indicator for European system integrator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG 4671 Interoperability Certification | Accelerates vendor qualification timelines across NATO defense procurement channels. |
| Software-Defined Signal Intelligence Platform | Opens dual-use contracting pathways through FAA air traffic management integration. |
| Captive Solid-State Laser Production | Reduces thermal management cost exposure for mobile directed-energy platforms. |
| Urban Airspace Monitoring Network Deployment | Captures EU Drone Strategy 2.0 standardized procurement specifications across member states. |
| High-Power Microwave Array Integration | Displaces kinetic interceptors for swarming Group 1 threat neutralization in expeditionary formations. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, RF systems engineers, homeland security agency program managers, and critical infrastructure security directors. Secondary validation drew from FAA remote ID rulemaking dockets, NATO STANAG documentation, EASA drone regulation frameworks, EU Green Deal dual-use technology provisions, and defense ministry budget appropriations. Bottom-up triangulation across subsystem vendor shipments and top-down reconciliation against NATO member state procurement forecasts anchored market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation between anti-drone systems, jammers, laser weapons, and interceptors alongside end-user stratification across military, homeland security, and private security channels. Deployment mode differentiation between on-premise, mobile, cloud-based, and hybrid architectures informed capacity planning assumptions. CAGRs were derived from layered adoption curves for directed-energy platforms and unbundled subsystem contracting velocity in federal channels.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense budget trajectories and stable rare-earth magnet supply channels would require recalibration. Forecasts reflect assumptions regarding EASA electromagnetic compatibility mandate timelines and Wassenaar Arrangement directed-energy export classification stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drones Market
UAV
Drone Roof Inspection Market
UAV
Asia Pacific Commercial Drone Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Stratospheric Flying Drone Market
UAV
Ultra-Long Endurance Drone Market
UAV
GCC Drone Pilot Training Market
UAV
US Commercial Drone Market
UAV
Commercial UAV Market
UAV
Europe Tactical UAV Market
UAV
Toy Drones Market
UAV
Global Inspection Drones Market
UAV
Fuel Cell UAV Market
UAV
Drone Motors Market
UAV
Global Aerial Imaging Market
UAV
Europe Drone Light Shows Market