
 UAV Simulator Software Market | 2026-2036
UAV Simulator Software Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Simulator Software Market Insights
Project finance tied to defense training modernization is tilting competitive access toward vendors with established government contracting channels. CAE Inc. leverages its military aviation heritage to anchor long-term service agreements with allied air forces. L3Harris Technologies sustains R&D intensity across live-virtual-constructive training architectures. Zen Technologies competes on cost-optimized hardware-in-the-loop systems for emerging militaries.
UAV simulator software denotes programmable environments that replicate flight dynamics, sensor payloads, and mission scenarios through physics-based modeling and real-time graphics rendering, primarily serving pilot proficiency development and mission rehearsal without airborne asset risk. The solution type dimension shows flight simulation occupying the largest revenue share while software testing gains traction from autonomous system verification needs. Cloud-based deployment is accelerating as defense agencies accept fedRAMP-authorized platforms for distributed training.
The FAA, EASA, and ISO shape market requirements through airworthiness certification standards, remote pilot competency frameworks, and software quality management protocols respectively. Regulatory divergence between FAA Part 107 and EASA open-category rules forces vendors to maintain parallel compliance tracks. Stakeholders must monitor how military export control revisions affect simulator technology transfer timelines.
Market Dynamics
Military training budget reallocation toward synthetic environments is compressing demand for physical flight hours while elevating software fidelity requirements for mission rehearsal systems.
Growth Catalysts
- FAA Part 107 Evolution:Commercial drone competency mandates in the United States are forcing training providers to integrate airspace compliance modules into simulator platforms.
- NATO Synthetic Training:Allied defense procurement agencies are expanding simulator-based programs to reduce operational UAV flight hours and preserve airframe lifecycles.
- Hardware-in-the-Loop Convergence:Physics-based sensor payload replication is enabling emerging militaries to deploy cost-optimized training infrastructure without live asset risk.
Market Restraints
- Export Control Friction:Military technology transfer timelines face compression from evolving International Traffic in Arms Regulations affecting simulator component shipments.
- Regulatory Divergence:Parallel compliance tracks for FAA Part 107 and EASA open-category rules force vendors to maintain redundant certification pathways.
- High-Fidelity Rendering Costs:Real-time graphics processing unit clusters required for sensor-accurate environments constrain price accessibility for civilian aviation academies.
Strategic Opportunities
- FedRAMP-Authorized Cloud:United States defense agencies are accepting distributed training platforms, opening subscription revenue models for software vendors.
- Autonomous System Verification:Software testing applications for beyond-visual-line-of-sight mission validation represent underpenetrated demand from commercial logistics operators.
- Emerging Military Procurement:Cost-optimized hardware-in-the-loop systems address budget-constrained allied forces in Eastern Europe and Southeast Asia.
Industry Challenges
- Physics Engine Talent Scarcity:Flight dynamics modeling expertise concentrates among aerospace engineering programs with limited annual graduate pipelines.
- Airworthiness Certification Timelines:ISO 9001 and DO-178C software quality protocols extend development cycles for new simulator releases.
- Legacy System Integration:Existing training infrastructure from prior-generation UAV platforms resists seamless interoperability with modern software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Simulator Software Market |
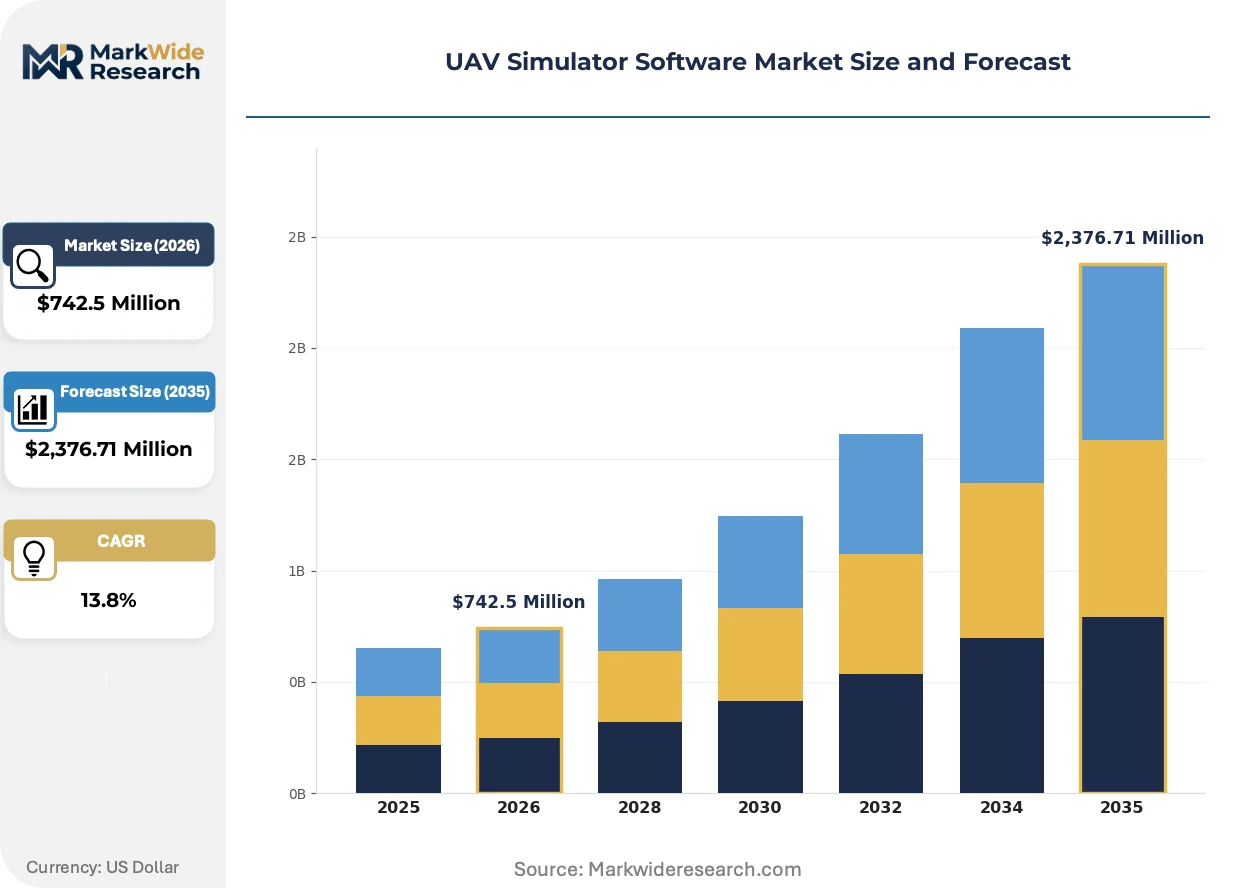
| Market Size in 2026 | $742.5 Million |
| Market Size in 2035 | $2,376.71 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based Solution Type: Flight Simulation, Mission Planning, Operator Training, Software Testing, Maintenance Planning Use Case: Military Operations, Disaster Management, Agricultural Monitoring, Infrastructure Inspection, Research & Development End User Industry: Defense Contractors, Environmental Agencies, Precision Farming Firms, Energy Sector Companies, Academic Institutions |
| Companies Covered | CAE Inc., L3Harris Technologies, Northrop Grumman Corporation, Presagis Canada, Zen Technologies, General Atomics Aeronautical Systems, Quantum3D, Leonardo S.p.A., BlueHalo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Simulator Software Market Trends and Innovations
Artificial intelligence is embedding adaptive scenario generation into training workflows, while regulatory pressure and procurement model evolution reshape how simulators reach end-users.
Digital twin architectures are virtualizing entire UAV operational environments including weather patterns, electromagnetic interference, and terrain mapping. Defense contractors in the United States and allied NATO states are deploying these systems for mission rehearsal at accelerating procurement velocity. This capability is virtualizing the traditional boundaries between pre-flight planning and live operational execution.
EASA's evolving open-category framework for remote pilot competency is forcing simulator vendors to recalibrate certification modules for European commercial operators. The regulation mandates specific flight hour equivalents in synthetic environments before licensing. Training providers in Germany, France, and the Netherlands are responding by integrating EASA-compliant competency tracking into their platform architectures.
Subscription-based access models are displacing perpetual license sales across civilian aviation academies and commercial drone training centers. United States-based flight schools now favor monthly software access over capital-intensive hardware purchases. This pattern concentrates most visibly in California, Texas, and Florida where Part 107 certification volume drives training infrastructure investment cycles.
UAV Simulator Software Market Segmentation
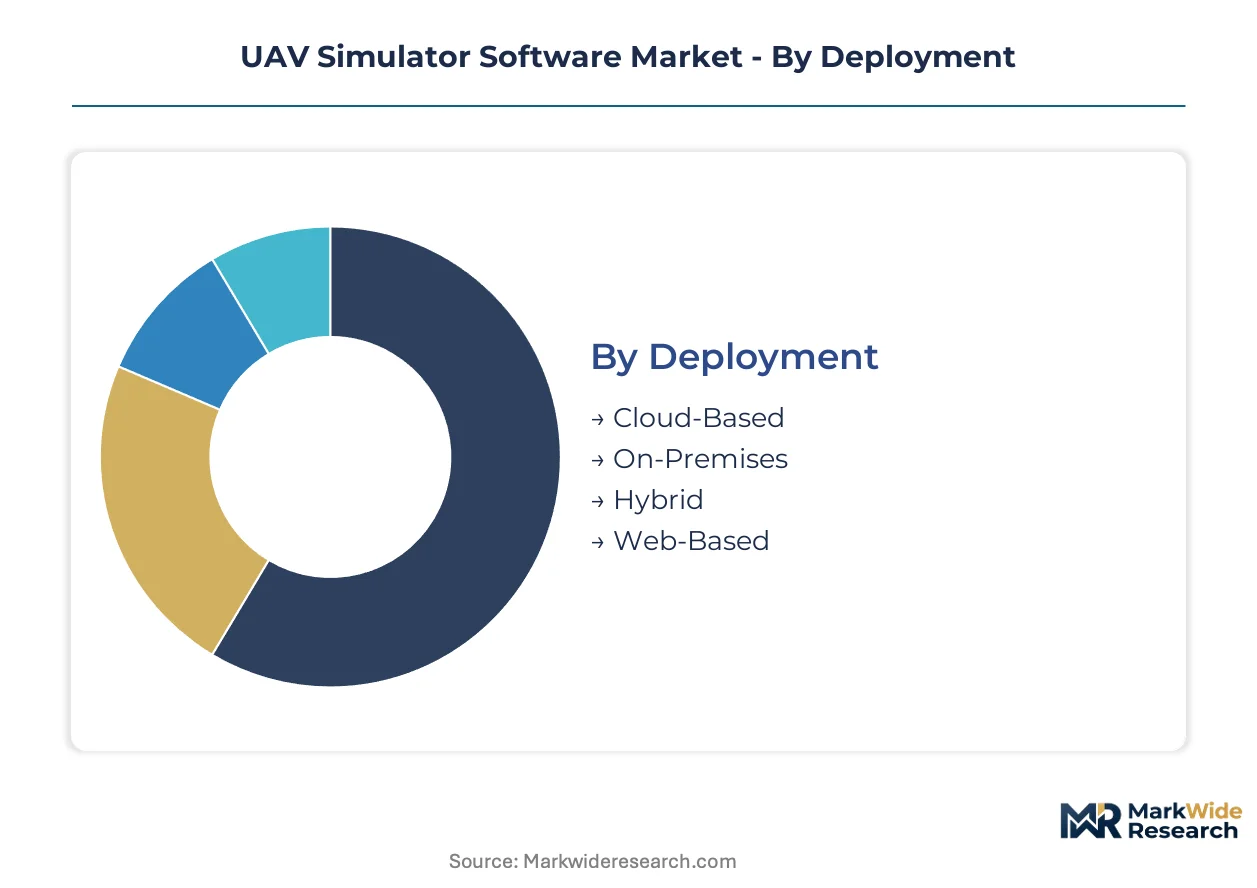
Segmentation in the UAV simulator software market reveals distinct procurement patterns across deployment architectures and end-use applications. Defense contractors prioritize air-gapped on-premises systems for classified mission rehearsal, while commercial operators gravitate toward scalable cloud platforms for distributed Part 107 training. Understanding these divides enables vendors to align licensing models with customer infrastructure constraints and compliance requirements.
Deployment:
After-sales service intensity varies sharply across deployment modes, with on-premises installations demanding sustained field engineering support while cloud subscriptions shift burden to vendor-side platform maintenance.
- Cloud-Based:FedRAMP-authorized platforms enable distributed training across multiple defense installations without hardware proliferation. United States military procurement agencies are accelerating adoption as cyber-hardened cloud architectures mature, reducing capital expenditure cycles for synthetic training infrastructure.
- On-Premises:Air-gapped server clusters isolate classified flight dynamics data and mission scenarios from external networks. NATO member states mandate these configurations for sensitive UAV mission rehearsal, particularly in Germany and Poland where national security protocols restrict data egress.
- Hybrid:Combines local rendering engines with cloud-based scenario libraries, balancing latency-sensitive pilot training with content scalability. Precision farming firms in California and Texas deploy hybrid stacks to maintain field-ready simulators while accessing updated agricultural terrain databases.
- Web-Based:Browser-accessible lightweight simulators target civilian aviation academies with limited IT infrastructure. These configurations sacrifice sensor-fidelity for accessibility, serving commercial drone certification programs in Florida flight schools.
By volume, cloud-based deployments lead. By growth pace, hybrid architectures are expanding most quickly as organizations reconcile security mandates with operational flexibility.
Solution Type:
Cost tier stratification separates capital-intensive hardware-in-the-loop flight systems from software-only modules accessible to budget-constrained training providers.
- Flight Simulation:Physics-based cockpit environments replicate control surface response, engine performance, and atmospheric conditions with sensor-grade accuracy. Defense contractors in the United States anchor procurement here, driven by FAA and military airworthiness certification requirements for pilot proficiency development.
- Mission Planning:Pre-flight scenario construction tools integrate terrain mapping, weather forecasting, and threat modeling for operational rehearsal. Allied NATO forces in Eastern Europe are expanding procurement as synthetic training displaces live flight hours for tactical UAV operations.
- Operator Training:Curriculum-managed competency tracking aligns synthetic flight hours with regulatory licensing frameworks. EASA's evolving open-category mandates are accelerating European commercial adoption, particularly in Germany and the Netherlands.
- Software Testing:Autonomous system verification environments validate beyond-visual-line-of-sight algorithms without airborne asset risk. Commercial logistics operators represent underpenetrated demand as BVLOS regulatory frameworks mature.
- Maintenance Planning:Virtual troubleshooting scenarios reduce physical airframe exposure during technician certification. Energy sector companies deploy these modules for offshore infrastructure inspection UAV fleets.
By installed base, flight simulation dominates. By expansion trajectory, software testing is climbing the fastest as autonomous system development accelerates.
Use Case:
Application-specific fidelity requirements range from military-grade electromagnetic interference modeling to civilian agricultural terrain mapping, dictating sensor payload complexity and rendering intensity.
- Military Operations:Classified mission rehearsal environments replicate electronic warfare conditions, jamming scenarios, and contested airspace dynamics. United States defense procurement channels concentrate demand here, with allied NATO programs following at reduced classification tiers.
- Disaster Management:Search-and-rescue scenario libraries simulate collapsed structure navigation, thermal signature detection, and coordination with ground response teams. Environmental agencies in California and Florida fund these capabilities for wildfire and hurricane response preparation.
- Agricultural Monitoring:Crop health assessment and precision spraying simulation require multispectral sensor replication and variable-rate application modeling. Midwestern United States farming cooperatives are emerging as training infrastructure investors.
- Infrastructure Inspection:Power line, pipeline, and cellular tower proximity scenarios emphasize obstacle avoidance and close-quarters maneuvering. Energy sector companies in Texas and Louisiana prioritize these modules for offshore and refinery UAV operations.
- Research & Development:Open-architecture platforms enable academic modification of flight dynamics models and sensor integration protocols. United States university engineering programs maintain procurement relationships for algorithm validation.
By current procurement volume, military operations leads. By adoption momentum, disaster management is gaining share fastest as climate resilience funding expands.
End User Industry:
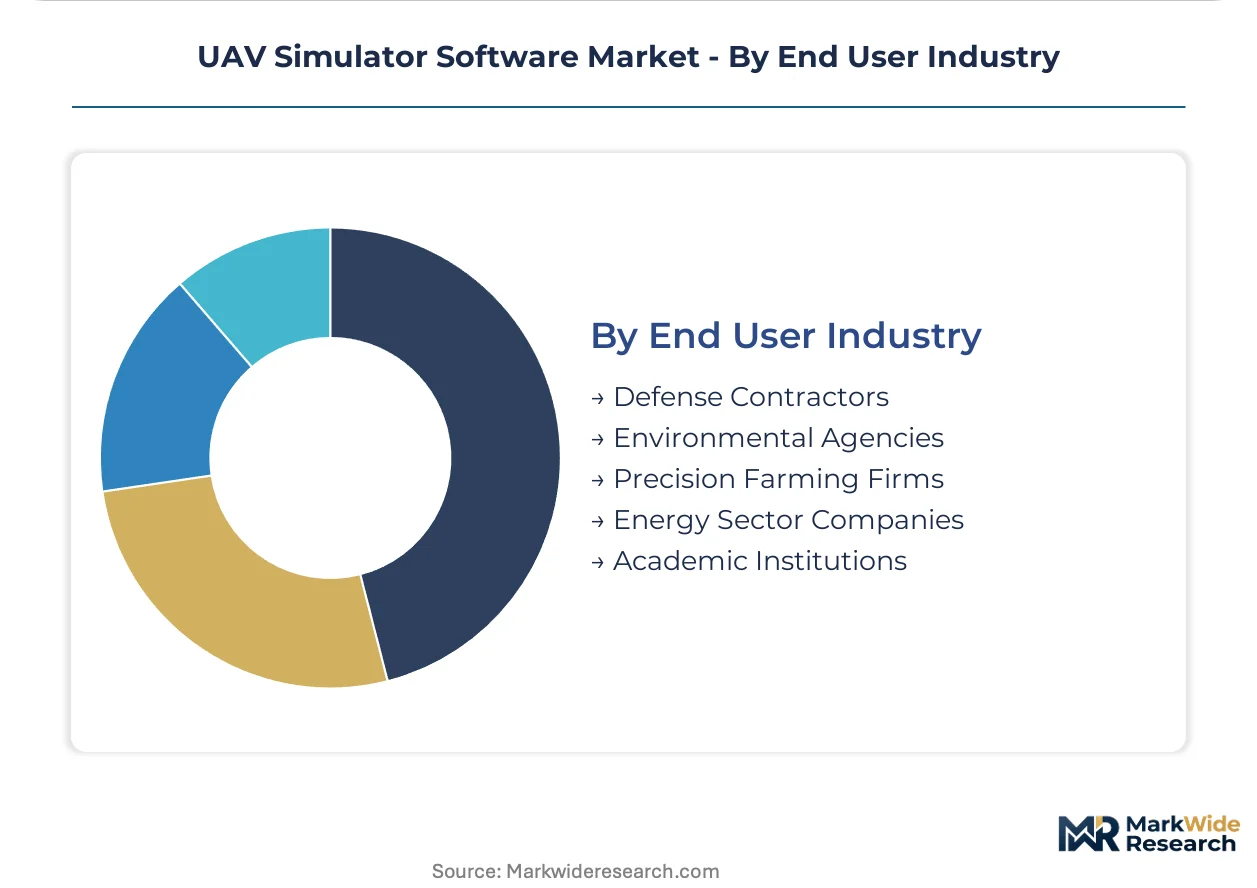
Customer type determines procurement authority structures, with defense contractors navigating military acquisition regulations while precision farming firms operate through decentralized equipment purchasing.
- Defense Contractors:Prime systems integrators aggregate simulator procurement across multiple military service branches, leveraging established government contracting channels. United States-based vendors anchor long-term service agreements through these relationships.
- Environmental Agencies:Federal and state-level departments fund disaster response training infrastructure through emergency preparedness appropriations. California's Cal FIRE and Florida's Division of Emergency Management represent concentrated state-level demand.
- Precision Farming Firms:Agricultural cooperatives and equipment dealerships deploy simulator modules for commercial drone operator certification. Midwestern United States grain belt operations are expanding training infrastructure investment cycles.
- Energy Sector Companies:Oil, gas, and utility operators require specialized offshore and high-voltage proximity scenarios. Gulf Coast energy infrastructure operators in Texas and Louisiana concentrate procurement for inspection UAV fleet qualification.
- Academic Institutions:Engineering programs and civilian aviation academies procure open-architecture platforms for research and pilot training. Texas and California flight schools drive civilian Part 107 certification volume.
By contract value concentration, defense contractors lead. By procurement velocity, precision farming firms are expanding most rapidly as agricultural UAV adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in simulator technology tilt toward net-importing defense ministries in Eastern Europe and Southeast Asia, while the United States and select NATO allies retain export advantages through established military contracting channels.
United States
The Pentagon's synthetic training modernization drives procurement volume, with defense contractors anchoring long-term service agreements across multiple service branches. FAA Part 107 evolution compels commercial training providers to integrate airspace compliance modules into simulator platforms. California and Texas flight schools concentrate civilian certification demand, particularly for commercial drone operator licensing.
Germany
Bundeswehr procurement agencies mandate air-gapped on-premises systems for classified UAV mission rehearsal, reflecting stringent national security protocols. EASA open-category competency frameworks force recalibration of certification modules for European commercial operators. Defense industrial clusters in Bavaria and Baden-Württemberg host prime systems integrators serving allied NATO programs.
Poland
Eastern flank NATO commitments accelerate simulator-based tactical training procurement to preserve airframe lifecycles amid heightened operational tempo. National security protocols restrict data egress, favoring domestic installation of air-gapped server clusters. Warsaw-based defense contractors aggregate regional demand across Baltic and Black Sea allied forces.
India
Budget-constrained military procurement favors cost-optimized hardware-in-the-loop systems from domestic and imported sources. The country's defense acquisition regulations prioritize local production partnerships under offset requirements. Bengaluru and Hyderabad engineering clusters incubate indigenous simulator development for tactical UAV platforms.
Australia
AUKUS defense technology sharing agreements facilitate simulator technology transfer from United States and United Kingdom sources. Civilian aviation academies in Queensland and Victoria expand commercial drone training infrastructure for agricultural and environmental monitoring applications. The country's Civil Aviation Safety Authority aligns competency frameworks with evolving beyond-visual-line-of-sight regulatory pathways.
UAV Simulator Software Market Competitive Landscape
On the supply side, the industry is consolidating around defense contractors with established government contracting channels and diversified technology conglomerates with live-virtual-constructive training architectures. Two strategic archetypes dominate: heritage military aviation specialists leveraging long-term service agreements, and cost-optimized hardware-in-the-loop vendors targeting emerging military procurement. Competitive positioning hinges on FedRAMP cloud authorization attainment and parallel FAA-EASA certification track maintenance.
Within the heritage defense contractor tier, CAE Inc. and L3Harris Technologies occupy positions shaped by decades of military aviation training relationships. CAE Inc. exemplifies the long-term service agreement archetype through its Canadian-incorporated, globally deployed defense contracting footprint. L3Harris Technologies represents the diversified technology conglomerate model with integrated live-virtual-constructive capabilities spanning multiple domains. Zen Technologies anchors the cost-optimized hardware-in-the-loop segment, with its India-based structure reflecting emerging military procurement targeting.
| Leading Market Players |
|---|
| CAE Inc. |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| Presagis Canada |
| Zen Technologies |
| General Atomics Aeronautical Systems |
| Quantum3D |
| Leonardo S.p.A. |
| BlueHalo |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in GPU cluster manufacturing across Taiwan and South Korea is squeezing rendering hardware availability, compelling simulator vendors to front-load component procurement and compress margin structures for civilian training providers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Defense contractors absorb premium tiers for FedRAMP-authorized cloud platforms and hardware-in-the-loop fidelity, while civilian aviation academies cluster in economy tiers for browser-accessible modules. Price differentiation rests on ISO 9001 certification grade and after-sales field engineering intensity. Cost compression in economy tiers is intensifying because precision farming firms in the Midwestern United States negotiate volume-based SaaS subscriptions. Commercial drone training centers exhibit highest price sensitivity; allied defense procurement agencies least.
Supply Chain Analysis
International Traffic in Arms Regulations and evolving military export controls are fragmenting cross-border component flows for sensor payload replication hardware. Manufacturing concentrates in the United States, Germany, and India for classified flight dynamics modules. Supply chains draw from Taiwan for GPU clusters, South Korea for memory components, and domestic U.S. foundries for air-gapped server architectures. Single-source vulnerability in advanced graphics processing units poses structural risk. Distribution runs through prime defense contractors aggregating multi-branch military procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward defense procurement agencies consolidating synthetic training budgets across NATO service branches, compressing vendor margins through multi-year service agreement consolidation.
For Market Incumbents: Insulate long-term government contracting relationships through FedRAMP authorization maintenance and parallel FAA-EASA certification track investments. Threat substitution emerges from cost-optimized hardware-in-the-loop vendors in India targeting emerging military procurement. Capacity addition in Bavaria and Baden-Württemberg engineering clusters reinforces European anchor positioning. For New Entrants and Emerging Players: Establish a beachhead in software testing modules for beyond-visual-line-of-sight autonomous system verification, the most penetrable segment as commercial logistics operators mature BVLOS operations. White-space targets include hybrid deployment architectures for precision farming firms in California and Texas. Go-to-market angles should emphasize subscription-based access displacing perpetual license sales in civilian aviation academies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with FedRAMP authorization serving distributed defense training infrastructure. Long-term viability favors vendors with live-virtual-constructive architecture integration spanning multiple domains. Acquisition targets should display established government contracting channels and ISO 9001 software quality certification. The signal to watch is EASA open-category framework finalization accelerating European commercial procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Attainment | Unlocks subscription revenue from U.S. defense agencies accepting distributed training platforms. |
| Parallel FAA-EASA Certification Investment | Mitigates regulatory divergence friction forcing redundant compliance pathway maintenance. |
| Hardware-in-the-Loop Cost Optimization | Captures budget-constrained allied forces procurement in Eastern Europe and Southeast Asia. |
| Cloud-Native Platform Development | Aligns with civilian aviation academy preference for monthly software access over capital purchases. |
| Autonomous System Verification Module Launch | Addresses underpenetrated demand from commercial logistics operators advancing BVLOS operations. |
Research Methodology
Cross-validation between primary interviews with defense procurement officers, simulator platform engineers, and civilian flight school operators and secondary validation anchors the qualitative findings. Secondary sources include FAA Part 107 regulatory filings, EASA open-category framework documentation, NATO synthetic training procurement disclosures, and defense contractor SEC 10-K segment reporting. Bottom-up triangulation aggregates deployment-mode and solution-type volumes; top-down calibration cross-checks against aggregate military training budget reallocation trends.
Calibration against historical procurement velocity across the analysis window validates growth trajectory assumptions. Segmentation dimensions modeled include deployment architecture, solution type, use case application, and end-user industry procurement authority. CAGRs derive from weighted average of segment expansion rates. Industry-specific inputs include Pentagon synthetic training modernization budget flows and EASA competency mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations cycles or semiconductor manufacturing capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory framework evolution and military export control stability. Cross-checking against NATO allied procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Fixed Wing Military Drones Market
UAV
Ultra Micro Drone Market
UAV
Drone Leasing Market
UAV
Drone Powered Business Solutions Market
UAV
Nano Drones Market
UAV
Global Drone Autopilots Market
UAV
UAV GNSS Antenna Market
UAV
Global Drone Inspection and Monitoring Market
UAV
Asia-Pacific Drones Market
UAV
Global Multirotor UAV Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Toy Drones Market
UAV
Drone Motors Market
UAV
Stratospheric Flying Drone Market
UAV
Tactical UAV Market
UAV
Drone Telematics Market