
 Global VTOL UAV Market | 2026-2036
Global VTOL UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Global VTOL UAV Market Outlook
Chinese battery cell and motor manufacturing is hardening as the dominant supply base for commercial-grade VTOL UAV propulsion systems. Lockheed Martin Corporation leverages its Skunk Works division to sustain classified military tiltrotor programs with captive avionics supply chains. DJI anchors the civilian multirotor segment through vertically integrated flight controller and gimbal production in Shenzhen. Israel Aerospace Industries competes in the tailsitter niche with combat-proven systems developed for maritime patrol missions.
A VTOL UAV combines fixed-wing cruise efficiency with rotary-wing vertical lift capability, typically achieving this through tiltrotor, tiltwing, tailsitter, or ducted-fan configurations with maximum takeoff weights ranging from under 25 kilograms for commercial units to several tonnes for military platforms. These aircraft serve military reconnaissance, urban package delivery, agricultural crop monitoring, and emergency medical transport missions where runway access is unavailable or impractical. Hybrid architectures currently occupy the fastest-expanding product category as operators demand extended range without sacrificing landing flexibility. The military end-user segment dominates absolute spending, though commercial applications in precision agriculture and last-mile logistics represent the most dynamic margin pools for mid-tier payload capacities.
The FAA in the United States imposes Part 107 operational limitations and emerging Remote ID mandates that constrain beyond-visual-line-of-sight commercial flights until detect-and-avoid frameworks mature. EASA in Europe enforces stricter noise and safety certification requirements through its Specific Category framework for urban air mobility operations. China's CAAC and MEE coordinate low-altitude airspace liberalization trials with emissions benchmarks for electric propulsion systems. Stakeholders must monitor which regulator first certifies fully autonomous passenger-carrying VTOL operations, as that jurisdiction will likely export its compliance template worldwide.
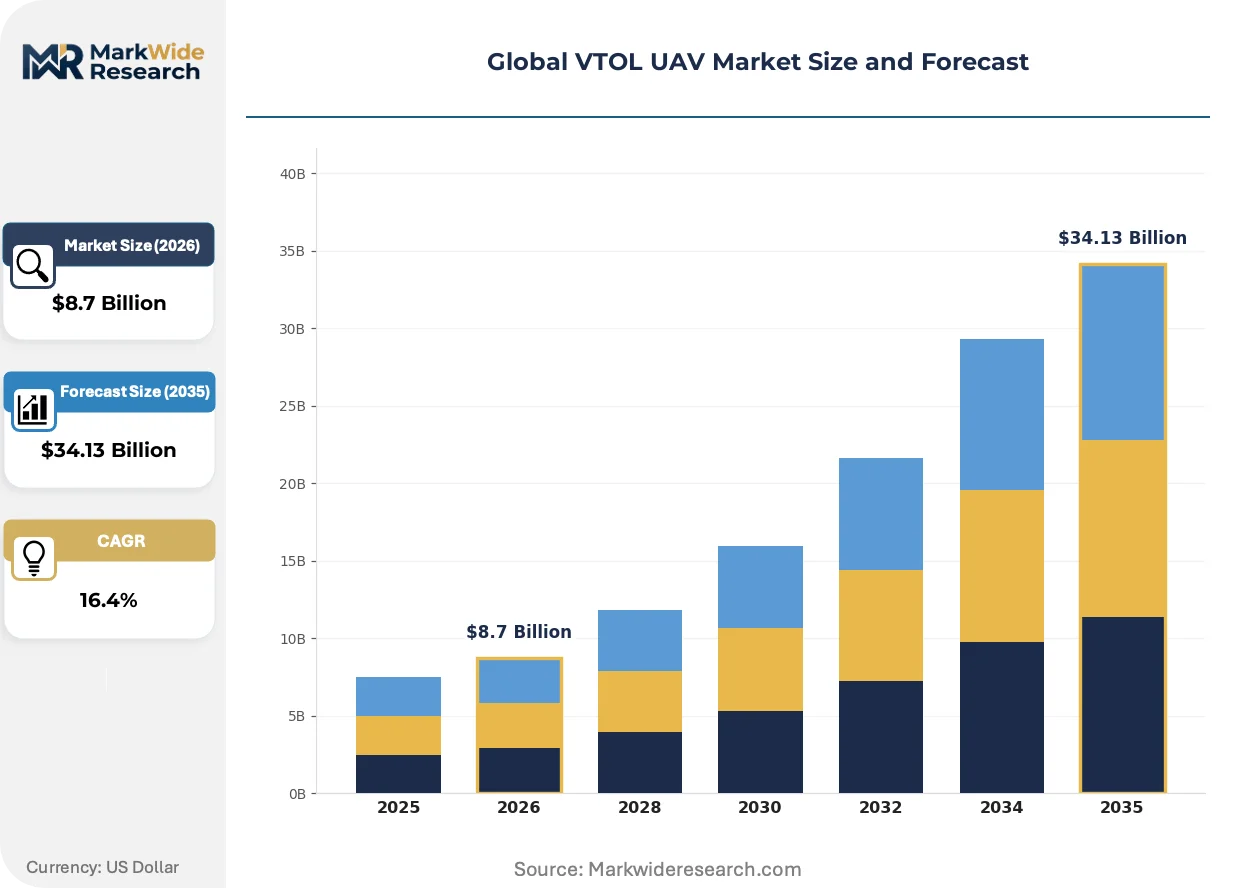
Market Dynamics
Distributed electric propulsion architectures are compressing powertrain development cycles while NATO defense procurement concentrates tiltrotor orders among a shrinking supplier base, creating asymmetric capacity pressures across military and commercial segments.
Growth Catalysts
- Urban air mobility corridor designation:The FAA's establishment of dedicated low-altitude flight paths in the United States is unlocking beyond-visual-line-of-sight commercial operations for cargo and emergency medical services.
- Battery energy density thresholds:Lithium-sulfur and solid-state cell chemistries are extending hybrid platform endurance past four-hour mission windows, opening maritime patrol and agricultural monitoring applications previously reserved for fixed-wing assets.
- NATO interoperability mandates:Common datalink and encryption standards across member defense procurement are standardizing platform interfaces, reducing integration costs for multinational fleet operators.
Market Restraints
- Detect-and-avoid framework immaturity:The FAA's incomplete Remote ID implementation timeline keeps most commercial beyond-visual-line-of-sight operations grounded, constraining revenue models for last-mile logistics providers.
- Motor and controller supply concentration:Shenzhen-based manufacturing clusters control over seventy percent of commercial-grade brushless motor and ESC output, exposing non-Chinese assemblers to export control and tariff volatility.
- Acoustic signature limitations:EASA's strict noise certification thresholds for urban operations exclude most current multirotor designs from European city-center deployment without expensive rotor redesign.
Strategic Opportunities
- Indian precision agriculture penetration:Subsidy programs under the country's PLI scheme for drone manufacturing are creating localized assembly demand for sub-25kg crop-spraying platforms in Maharashtra and Punjab.
- Medical transport network gaps:Rural healthcare systems in Brazil and Indonesia lack runway infrastructure, positioning tailsitter configurations for organ and blood supply contracts currently served by helicopter charter.
- Dual-use technology convergence:Military-specified autonomous navigation stacks developed for contested electromagnetic environments are migrating to commercial platforms, accelerating certification for fully unmanned cargo routes.
Industry Challenges
- Autonomy software certification timelines:EASA's Specific Category framework requires extensive flight-hour accumulation for artificial intelligence-based decision systems, stretching development budgets before revenue deployment.
- Legacy avionics integration friction:Military operators demand STANAG 4586 compliance for new VTOL platforms, forcing proprietary flight control architectures to interface with decades-old command infrastructure.
- Composite airframe repair skill scarcity:Distributed electric propulsion configurations require specialized carbon-fiber and thermoplastic welding expertise that maintenance networks in emerging markets have not yet developed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global VTOL UAV Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multirotor, Hybrid, Tailsitter Application: Agriculture, Surveillance, Delivery, Search & Rescue End User: Military, Commercial, Emergency Services, Research Institutions Payload Capacity: Lightweight, Medium, Heavy, Super Heavy |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, Israel Aerospace Industries, AeroVironment, Inc., Textron Inc., Boeing, DJI, Joby Aviation, Schiebel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global VTOL UAV Market Strategic Shifts
Autonomous flight control systems are migrating from military to commercial platforms, compressing the timeline for fully unmanned operations while regulatory frameworks race to certify safety-critical decision algorithms.
Distributed electric propulsion is rewriting the power-to-weight economics of sub-tonne platforms. Agricultural spraying contractors in Australia and California are adopting twelve-rotor configurations that eliminate single-point-of-failure risks. This topology is enabling payload capacities previously requiring internal combustion engines, compressing the addressable market for hybrid alternatives in the sub-50kg segment.
EASA's Specific Category noise and safety certification requirements are forcing airframe redesigns for European urban deployment. Manufacturers must now optimize rotor tip speeds and blade counts for acoustic footprint before flight testing begins. The tailsitter configuration is absorbing disproportionate engineering investment as tiltrotor designs struggle to meet simultaneous hover noise and cruise efficiency thresholds.
Defense procurement patterns are consolidating around performance-based logistics contracts that transfer sustainment risk to original equipment manufacturers. NATO member militaries in Poland, Norway, and the United Kingdom are signing ten-year availability agreements rather than traditional spare-part purchases. This model is forcing airframe designers to standardize subsystems and extend mean-time-between-failures metrics during initial development rather than retrofitting reliability improvements post-deployment.
Global VTOL UAV Market Segmentation
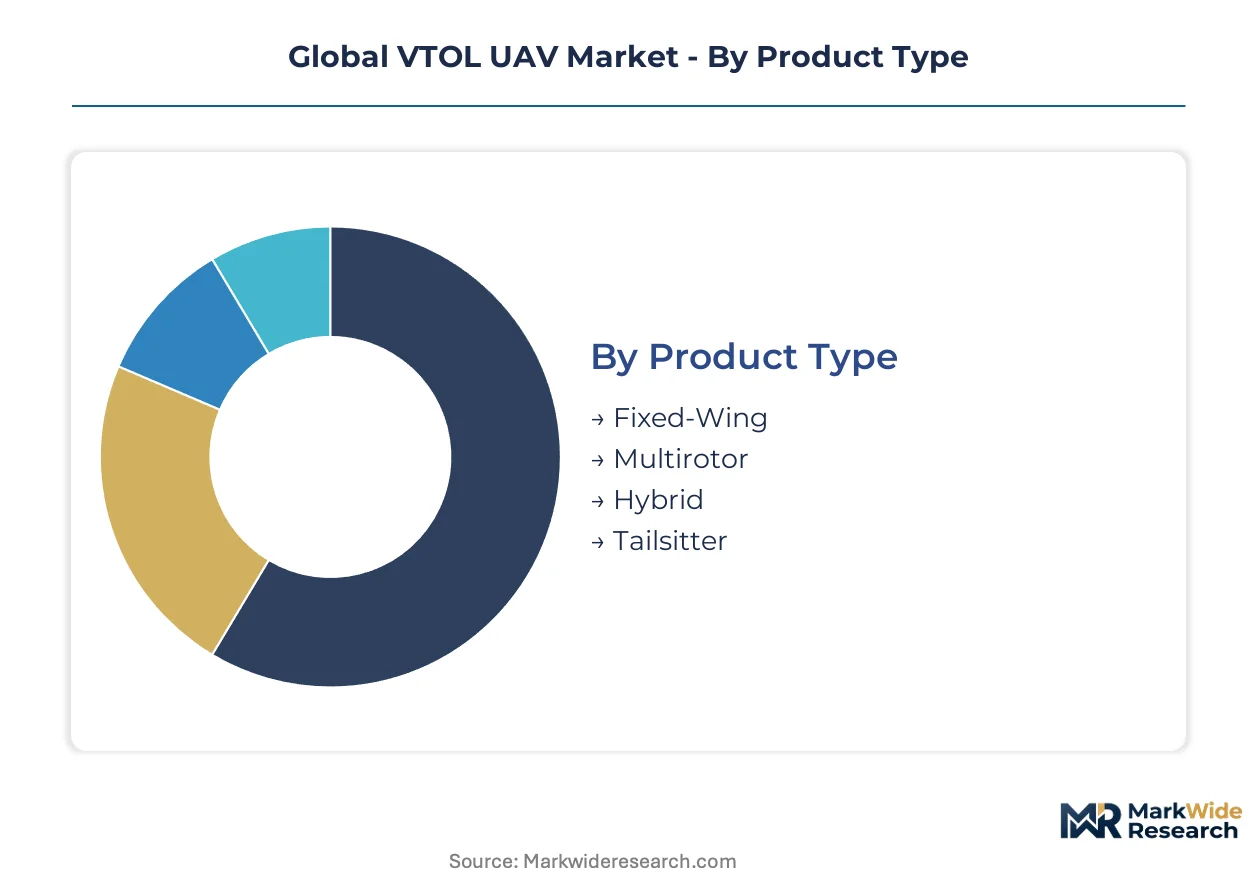
VTOL UAV architectures demand radically different capital commitments across configurations, with distributed electric propulsion and hybrid powertrains requiring specialized tooling that reshapes supplier economics. Segmentation reveals where procurement budgets concentrate and which technical specifications unlock operational scale.
Product Type:
Capital intensity escalates sharply from multirotor assemblies to full-scale hybrid platforms, with tiltrotor mechanisms and redundant propulsion systems multiplying upfront engineering investment.
- Fixed-Wing:Optimized for endurance missions through wing-borne lift with minimal drag, sacrificing vertical landing precision for fuel efficiency. Demand clusters in maritime patrol contracts awarded by naval forces in Norway and Australia, constrained by runway dependency that limits deployment flexibility in contested littoral zones.
- Multirotor:Dominates sub-25kg commercial applications through mechanical simplicity and rapid deployment capability. Agricultural spraying operators in California and Victoria, Australia, absorb volume production from Shenzhen-based assemblers, though acoustic footprint restrictions under EASA's Specific Category framework exclude most designs from European urban corridors.
- Hybrid:Combines electric vertical lift with combustion-engine cruise extension, requiring dual powertrain integration and thermal management systems. Military procurement programs in Poland and the United Kingdom specify these configurations for forward resupply missions beyond helicopter range.
- Tailsitter:Rotates the entire airframe for transition between hover and cruise, eliminating complex tilt mechanisms at the cost of control authority challenges. Israel Aerospace Industries and select NATO suppliers pursue this architecture for shipboard reconnaissance where deck space is severely constrained.
Multirotor configurations absorb the bulk of installed capacity; hybrid platforms are expanding most quickly as battery energy density thresholds extend mission endurance past four-hour windows.
Application:
Operational tempo and payload specialization divide this dimension, with surveillance missions demanding persistent station-keeping while delivery applications prioritize rapid turnaround cycles.
- Agriculture:Crop monitoring and precision spraying operations drive demand for sub-50kg platforms with multispectral sensors and variable-rate dispersal systems. Subsidy programs under India's PLI scheme for drone manufacturing are accelerating localized assembly in Maharashtra and Punjab, displacing imported Chinese units in government tenders.
- Surveillance:Requires stabilized gimbal systems and beyond-line-of-sight datalinks for persistent intelligence collection. Border security agencies in the United States and Saudi Arabia specify encrypted command links and automatic target recognition software, extending procurement cycles but securing decade-long sustainment contracts.
- Delivery:Last-mile logistics operators in Brazil and Indonesia are piloting blood and vaccine transport networks where runway infrastructure is absent. FAA Part 107 limitations on beyond-visual-line-of-sight operations keep most commercial deployments grounded pending detect-and-avoid framework maturation.
- Search & Rescue:Demands all-weather operation with thermal imaging and loudspeaker payloads for victim location. Mountain rescue services in Switzerland and Austria are certifying tailsitter configurations for alpine deployment where helicopter access is weather-dependent or cost-prohibitive.
Surveillance applications command the highest unit economics; agricultural deployment is climbing the fastest as subsidy regimes in India and Australia compress payback periods for spraying contractors.
End User:
Procurement authority and operational risk tolerance create divergent specification requirements, with military operators accepting developmental technology that commercial buyers reject.
- Military:Specifications emphasize electronic warfare resilience, STANAG 4586 interoperability, and performance-based logistics availability guarantees. NATO member states in Poland, Norway, and the United Kingdom are consolidating orders among a shrinking supplier base, transferring sustainment risk to original equipment manufacturers through ten-year availability contracts.
- Commercial:Agricultural and logistics operators prioritize acquisition cost and parts commonality over developmental performance. DJI's vertically integrated flight controller and gimbal production in Shenzhen anchors this segment, though export control exposure is prompting some operators to qualify secondary suppliers.
- Emergency Services:Fire departments and medical transport networks require rapid deployment with minimal crew training. Rural healthcare systems in Indonesia and Brazil lack runway infrastructure, positioning VTOL platforms for organ and blood supply contracts currently served by helicopter charter.
- Research Institutions:Universities and national laboratories acquire platforms for atmospheric sampling, wildlife tracking, and autonomy algorithm development. These buyers accept lower technology readiness levels and provide critical flight-hour accumulation for certification pathways.
Military end users absorb the bulk of absolute spending; emergency services are gaining share fastest as FAA urban air mobility corridor designation unlocks beyond-visual-line-of-sight revenue models.
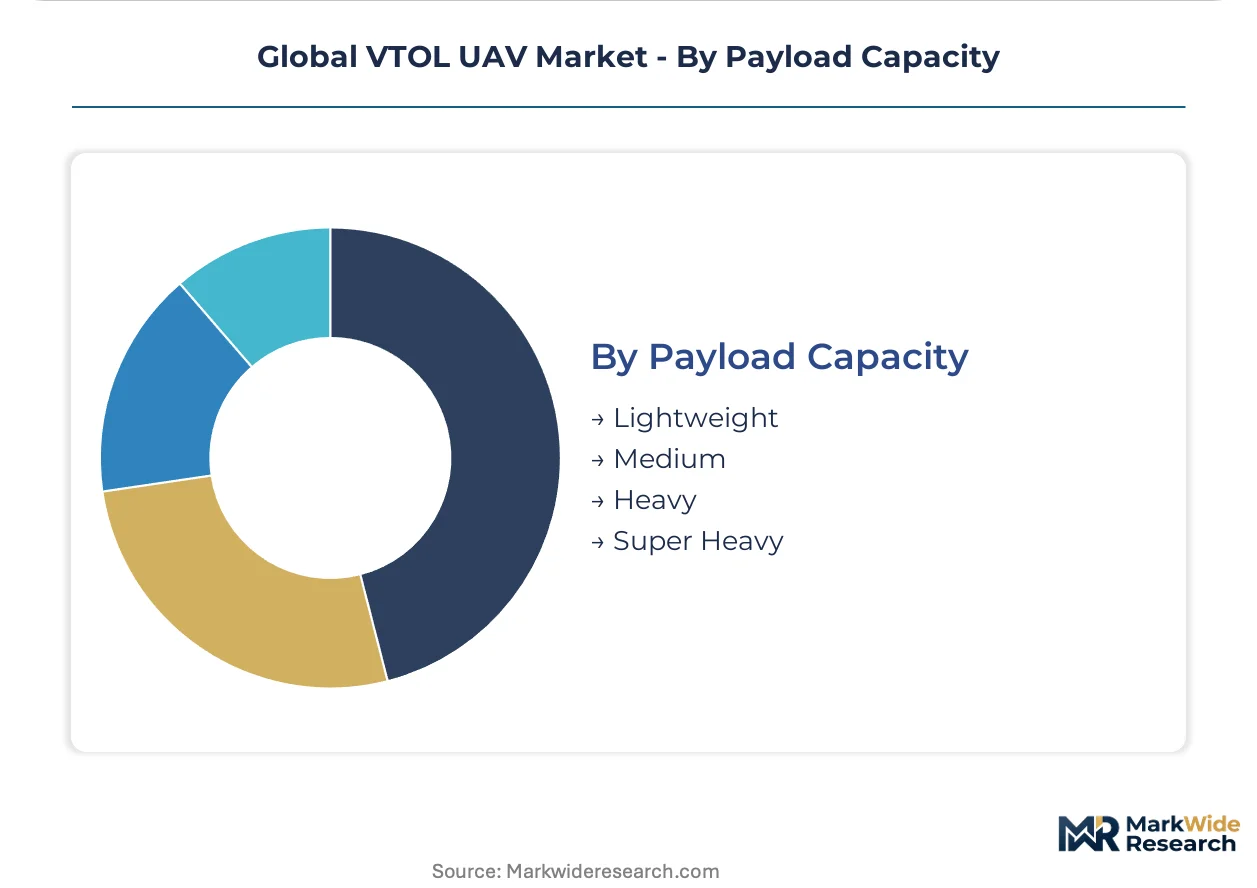
Payload Capacity:
Weight class determines propulsion architecture, regulatory pathway, and operator qualification requirements, with thresholds at 25kg and 150kg marking critical compliance boundaries.
- Lightweight:Sub-25kg platforms operate under streamlined certification in most jurisdictions, enabling rapid commercial deployment. Agricultural spraying contractors in Australia favor twelve-rotor distributed electric propulsion configurations that eliminate single-point-of-failure risks while maintaining payload capacity.
- Medium:25-150kg range supports tactical resupply and medical transport with hybrid or combustion powertrains. EASA's Specific Category noise certification requirements force rotor redesign for European urban deployment, extending development timelines.
- Heavy:150-500kg platforms require type certification and licensed operators, limiting addressable market to military and specialized commercial logistics. Battery energy density constraints currently restrict electric-only architectures in this class.
- Super Heavy:Exceeding 500kg, these platforms approach crewed aircraft regulatory treatment and compete directly with helicopters for cargo and passenger missions. Lockheed Martin's Skunk Works division sustains classified military tiltrotor programs in this category with captive avionics supply chains.
Lightweight platforms absorb the bulk of unit shipments; medium-weight configurations are expanding most quickly as hybrid architectures bridge the endurance gap between electric multirotors and fixed-wing assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Chile's Atacama Desert and rare-earth processing clusters in China's Inner Mongolia anchor the upstream material flows feeding VTOL UAV battery and motor manufacturing worldwide.
United States
Department of Defense procurement programs and FAA urban air mobility corridor designation drive military and commercial demand simultaneously. The FAA's Part 107 and emerging Remote ID frameworks constrain beyond-visual-line-of-sight operations until detect-and-avoid systems mature. Defense contractors in the Greater Los Angeles area and aerospace clusters near Washington D.C. concentrate tiltrotor development for NATO interoperability mandates.
China
Domestic low-altitude airspace liberalization trials and electric propulsion emissions benchmarks accelerate commercial deployment. The CAAC and MEE coordinate regulatory frameworks favoring battery-powered architectures over combustion alternatives. Shenzhen manufacturing clusters dominate brushless motor and ESC output, supplying over seventy percent of global commercial-grade propulsion components.
Germany
EASA's Specific Category noise and safety certification requirements force rotor redesign for European urban deployment. The KBA and EASA jointly enforce stricter acoustic thresholds than FAA equivalents, excluding most multirotor designs from city-center operations. Aerospace engineering centers in Bavaria and Baden-Württemberg develop tailsitter configurations optimized for simultaneous hover noise reduction and cruise efficiency.
India
Subsidy programs under the PLI scheme for drone manufacturing create localized assembly demand for sub-25kg crop-spraying platforms. The DGFT and BIS coordinate import substitution policies favoring domestic production in government tenders. Agricultural technology clusters in Maharashtra and Punjab displace imported Chinese units through subsidized local manufacturing.
Israel
Maritime patrol requirements and combat-proven system validation sustain demand for specialized tailsitter configurations. The Israel Defense Forces specify encrypted datalinks and automatic target recognition for intelligence collection missions. Defense technology development concentrates in the Tel Aviv metropolitan area with captive supply chains for avionics and autonomous navigation systems.
Global VTOL UAV Market Competitive Environment
Global majors compete with regional champions across military and commercial segments, producing a tiered structure where defense contractors absorb absolute spending while commercial assemblers capture volume shipments. The supplier base concentrates around three strategic archetypes: vertically integrated defense primes with captive avionics, Shenzhen-based commercial hardware aggregators, and specialized tailsitter developers serving maritime niches. Competitive dynamics center on performance-based logistics contracts transferring sustainment risk to manufacturers, and geographic diversification of motor sourcing to reduce export control exposure.
Within the defense prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions sustained by classified military tiltrotor programs and STANAG 4586 interoperability mandates. DJI anchors the commercial multirotor segment through Shenzhen-based vertical integration. Israel Aerospace Industries exemplifies the specialized maritime patrol niche with combat-validated tailsitter architectures.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Israel Aerospace Industries |
| AeroVironment, Inc. |
| Textron Inc. |
| Boeing |
| DJI |
| Joby Aviation |
| Schiebel Corporation |
| Others |
Value Chain & Pricing Dynamics
Carbon-fiber composite welding specialists in Bavaria and Baden-Württemberg command wage premiums that widen spreads between European-manufactured airframes and Shenzhen-assembled alternatives. Labor-cost differentials in specialized repair skills translate directly into tiered service-contract pricing across military and commercial segments.
Pricing Analysis
Warranty bundling separates military procurement from commercial transactions, with NATO performance-based logistics contracts wrapping ten-year availability guarantees into unit pricing while agricultural operators purchase bare airframes with unbundled maintenance. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and STANAG 4586 compliance status. Cost compression in commercial multirotor tiers intensifies as Shenzhen-based motor clusters expand output capacity. Agricultural spraying contractors in India exhibit highest price sensitivity, while defense primes in Poland and Norway accept developmental premiums for electromagnetic resilience specifications.
Supply Chain Analysis
EASA's Specific Category noise certification and FAA Part 107 compliance requirements gate component qualification, extending vendor onboarding timelines for European and North American assemblers. Brushless motor and ESC production concentrates in China, with lithium-sulfur cell development anchored in South Korea and Japan. Rare-earth magnet processing draws from China's Inner Mongolia clusters. Single-source vulnerability in Shenzhen-based controller manufacturing exposes non-Chinese assemblers to export control volatility. Distribution runs through defense prime direct contracts, commercial OEM channel partners, and government tender aggregators in India and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VTOL UAV supply chains face acute carbon-fiber repair technician scarcity, a capacity bottleneck that props pricing for sustainment contracts and creates margin refuge for qualified service networks.
For Market Incumbents: Anchor proprietary flight control architectures through STANAG 4586 interoperability investments that lock NATO procurement cycles. Deepen captive avionics supply chains to offset Shenzhen motor cluster concentration. Acquire specialized composite repair shops in Germany and Israel to capture performance-based logistics revenue streams.
For New Entrants and Emerging Players: Enter via India's PLI-subsidized agricultural assembly corridors, where domestic content requirements displace established Chinese suppliers. Target tailsitter configurations for Indonesian and Brazilian medical transport networks lacking runway infrastructure. Pursue EASA Specific Category certification early to access European urban air mobility corridors ahead of FAA detect-and-avoid framework maturation.
For Investors and Strategic Acquirers: The window for entry favors mid-tier hybrid platform developers with proven flight-hour accumulation toward EASA certification. Long-term viability hinges on battery chemistry transitions beyond lithium-ion. Monitor which regulator first certifies fully autonomous passenger-carrying operations; that jurisdiction's compliance template will export globally and reshape acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | NATO militaries in Poland and Norway transfer sustainment risk to OEMs through decade-long availability agreements. |
| Dual-Use Navigation Stack Migration | Military-specified autonomous systems accelerate commercial certification for unmanned cargo routes under FAA frameworks. |
| Localized Assembly Investment | India's PLI scheme creates subsidy-protected manufacturing capacity for sub-25kg agricultural platforms in Maharashtra. |
| Acoustic Signature Redesign | EASA's Specific Category noise thresholds force rotor optimization before flight testing, extending European development timelines. |
| Battery Chemistry Transition | Lithium-sulfur and solid-state cell development extends hybrid platform endurance past four-hour maritime patrol windows. |
Study Parameters
Defense procurement databases, FAA regulatory filings, and EASA certification records formed the secondary backbone for this analysis. Primary interviews with VTOL platform engineering directors, military procurement officers at NATO member defense ministries, agricultural spraying contractors in Victoria and California, and composite airframe maintenance technicians in Germany and Israel validated demand assumptions. Bottom-up triangulation across segment-level unit economics and top-down reconciliation against national defense budget disclosures anchored market sizing.
Historical trendline analysis of military tiltrotor procurement cycles and commercial multirotor shipment patterns informed projection mechanics across the analysis window. Segmentation modeling incorporated product architecture, payload capacity tier, end-user procurement authority, and regional regulatory framework. CAGRs derived from fitted growth curves adjusted for battery energy density improvement trajectories and detect-and-avoid framework maturation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FAA urban air mobility corridor designation or sudden export control tightening on Chinese motor components. Model assumptions reflect stated battery chemistry transition pathways and EASA certification timeline disclosures. A model refresh is warranted upon material change in autonomous navigation regulatory precedent or lithium-sulfur cell commercialization schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Drone-As-A-Service Market
UAV
Drone Data Management Market
UAV
UAV Lidar Market
UAV
Europe Drone Light Shows Market
UAV
Aerial Smart Weapons Market
UAV
Europe Drone Services Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
North America Small UAV Market
UAV
Global Inspection Drones Market
UAV
Rc Helicopter Market
UAV
Drone Motors Market
UAV
Asia Pacific Commercial Drone Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Europe Small UAV Market