
 Drone Tracking Antenna Market | 2026-2036
Drone Tracking Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Tracking Antenna Market Insights
Software-defined beamforming is hardening as the primary service layer vendors monetize, shifting revenue from hardware sales to recurring firmware subscriptions. RTX leverages its defense electronics heritage to sustain long-term service contracts across Pentagon tracking programs. Lockheed Martin Corporation anchors its position through classified R&D pipelines for next-generation directional arrays. Thales competes in European NATO markets with modular upgrade paths for legacy radar installations.
A drone tracking antenna is a radio frequency transducer engineered to acquire, track, and maintain communication links with unmanned aerial vehicles across variable aspect angles and doppler shifts, typically operating from 300 MHz through 12 GHz with gain specifications exceeding 15 dBi for precision applications. Its commercial purpose centers on providing assured telemetry, command, and video links for beyond-visual-line-of-sight operations in contested electromagnetic environments. Directional antennas still occupy the largest installed base for fixed-site defense installations, while phased array configurations represent the fastest-growing product category as solid-state transmit-receive modules displace gimbal mechanisms. Among end users, defense agencies command the dominant margin pool due to classified performance requirements and multi-year procurement cycles, though commercial operators in agricultural monitoring are expanding fastest as BVLOS waivers proliferate.
The FAA mandates remote identification and tracking capabilities under Part 89, directly stimulating antenna upgrades for commercial fleet operators seeking compliance. EASA's U-space regulatory framework imposes equivalent detect-and-avoid obligations across European member states, creating parallel certification requirements for manufacturers. FCC spectrum allocation proceedings for 5.9 GHz and C-band reconfiguration are forcing hardware redesigns to maintain link integrity. Stakeholders must monitor pending ITU harmonization efforts for drone command frequencies, as regional spectrum fragmentation threatens to bifurcate product architectures and complicate cross-border deployment strategies.
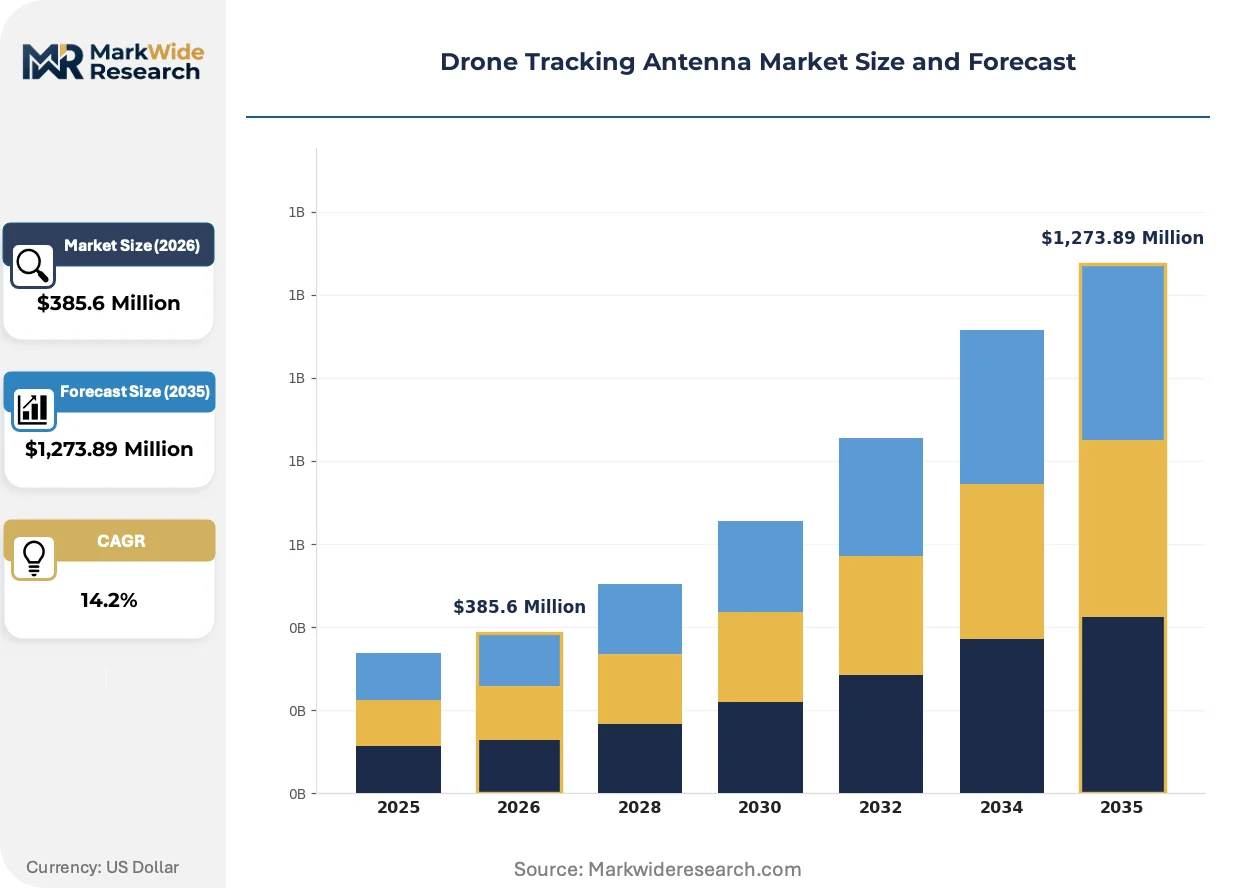
Market Dynamics
Phased array architectures are displacing mechanically steered gimbal systems across defense and border surveillance programs, compressing procurement cycles while elevating firmware subscription revenue over hardware margins. This hardware-to-service transition concentrates margin capture among vendors with classified R&D pipelines and long-term Pentagon service contracts.
Growth Catalysts
- FAA Part 89 Remote ID Mandate:Fleet operators across commercial aviation must upgrade antenna systems to maintain BVLOS operational waivers, forcing hardware refreshes through 2028 compliance deadlines.
- Solid-State TR Module Proliferation:Gallium nitride transmit-receive modules enable electronic beam steering without mechanical wear, extending mean-time-between-failures for fixed-site installations.
- NATO Counter-UAS Procurement Surge:Member state defense agencies are consolidating tracking infrastructure under unified electromagnetic spectrum management protocols.
Market Restraints
- Gallium Nitride Substrate Concentration:Foundry capacity for high-power RF semiconductors clusters in East Asian supply chains, exposing procurement timelines to geopolitical disruption.
- EASA U-Space Certification Friction:Detect-and-avoid hardware validation timelines extend 18-24 months, freezing commercial deployment schedules.
- Mechanical Gimbal Installed Base Lock-In:Legacy directional antennas with 15-20 year service lives delay upgrade cycles at fixed-site defense installations.
Strategic Opportunities
- Agricultural BVLOS Waiver Expansion:Crop monitoring operators in North American grain belts seek portable tracking arrays for seasonal field coverage.
- ITU Spectrum Harmonization:Pending international command frequency alignment would enable single-SKU product architectures for cross-border logistics corridors.
- 5.9 GHz Redesign Wave:FCC reconfiguration proceedings force hardware refreshes, opening upgrade windows for vendors with firmware-defined beamforming stacks.
Industry Challenges
- RF Engineer Talent Scarcity:Phased array design expertise concentrates among defense contractors, constraining commercial vendor hiring pipelines.
- Multi-Agency Certification Overlap:Products must simultaneously satisfy FCC emission limits, FAA airworthiness directives, and DoD cybersecurity frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Tracking Antenna Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,273.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional Antennas, Omnidirectional Antennas, Phased Array Antennas, Patch Antennas, Helical Antennas Frequency Band: UHF, VHF, L-Band, S-Band, C-Band, X-Band Application: Surveillance, Agriculture Monitoring, Infrastructure Inspection, Delivery Services, Disaster Management, Wildlife Tracking End User: Defense Agencies, Commercial Operators, Research Institutes, Emergency Responders, Construction Firms |
| Companies Covered | RTX, Northrop Grumman, Lockheed Martin Corporation, Thales, Elbit Systems Ltd., Antcom Corporation, Antenna Research Associates, Inc., Southwest Antennas, Inc., TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Tracking Antenna Market Trends and Innovations
Software-defined radio architectures are collapsing the boundary between hardware and firmware layers, enabling post-deployment capability upgrades that extend product lifecycles while shifting vendor revenue models toward recurring streams.
Digital beamforming is converging with artificial intelligence-driven threat classification algorithms. Defense agencies in NATO member states are deploying these integrated stacks for real-time drone identification against cluttered electromagnetic backgrounds. This convergence is compressing the competitive window for pure-play hardware manufacturers without embedded software competencies.
EASA's U-space regulatory framework is mandating detect-and-avoid capabilities for all unmanned operations above 120 meters altitude across European member states. Hardware manufacturers must redesign RF front-ends to satisfy both civilian certification and military electromagnetic compatibility standards. Commercial operators in German and French urban air mobility corridors face the steepest compliance cost gradients.
Service contract unbundling is separating hardware procurement from maintenance and firmware upgrade obligations. Defense prime contractors now bid tracking infrastructure as 10-year managed service agreements rather than capital equipment sales. This pattern is most visible in US Department of Defense programs, where total-cost-of-ownership evaluation criteria favor vendors with captive software development pipelines.
Drone Tracking Antenna Market Segmentation
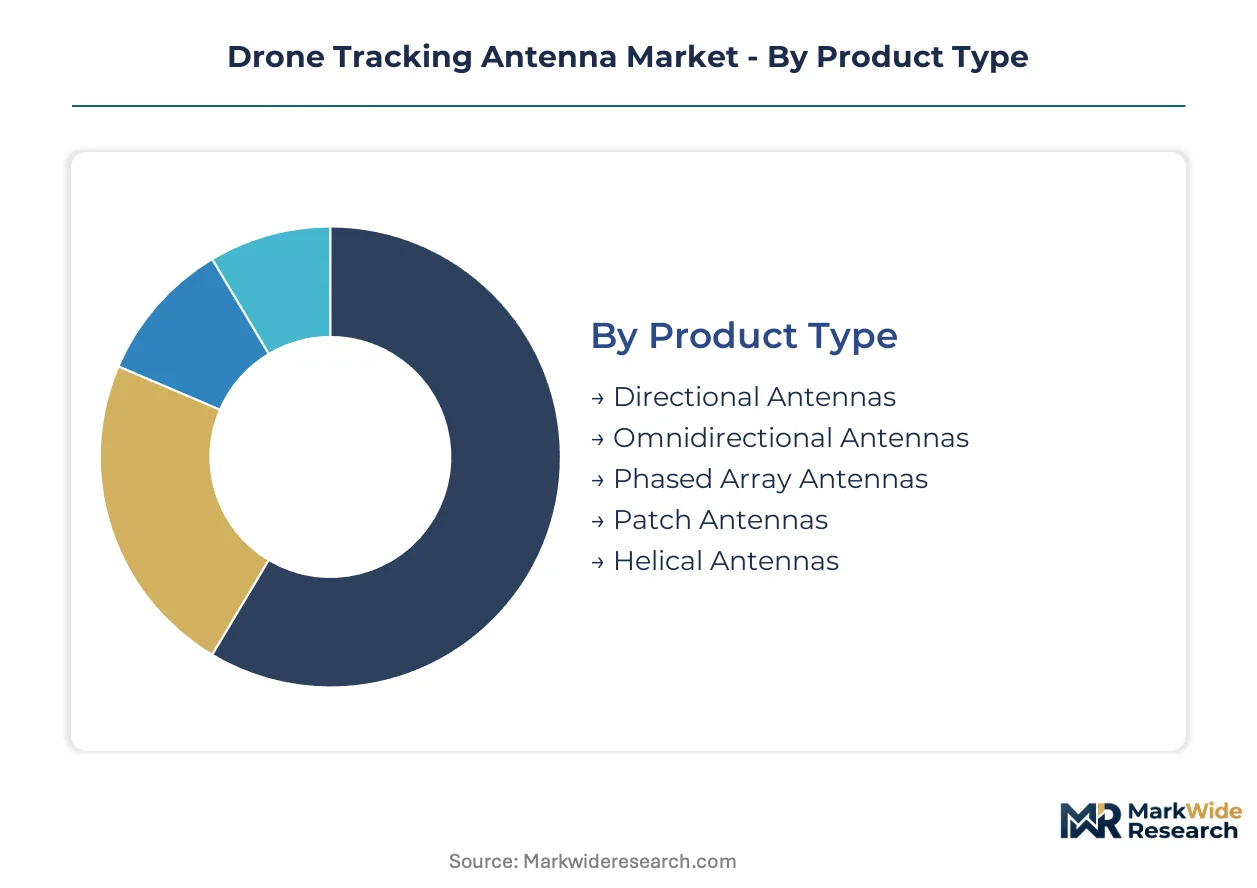
Drone tracking antenna procurement splits across technical specifications, operational frequencies, and mission profiles. Certification requirements from the FAA, EASA, and DoD cybersecurity frameworks create divergent compliance burdens across each dimension. Vendors must architect product lines that satisfy multiple regulatory regimes simultaneously.
Product Type:
FAA Part 89 compliance mandates specific gain and beamwidth characteristics for BVLOS operations, while DoD programs impose classified electromagnetic compatibility standards on defense-grade hardware. Each antenna architecture carries distinct certification pathways.
- Phased Array Antennas:Solid-state transmit-receive modules enable electronic beam steering without mechanical gimbals. Demand concentrates in Pentagon border surveillance programs where firmware-defined upgrades extend platform lifecycles. GaN substrate supply constraints from East Asian foundries compress delivery timelines for high-power variants.
- Directional Antennas:Parabolic and Yagi-Uda configurations dominate fixed-site defense installations with 15-20 year service lives. Legacy procurement cycles at NATO radar facilities delay replacement schedules despite electronic steering advantages. Mechanical wear on azimuth drives elevates maintenance costs for remote Arctic installations.
- Omnidirectional Antennas:Vertical whip and biconical designs serve short-range telemetry in agricultural monitoring where 360-degree coverage eliminates pointing requirements.
- Patch Antennas:Low-profile planar structures integrate into portable ground control stations for emergency responder rapid deployment kits.
- Helical Antennas:Circular polarization maintains link integrity through drone attitude variations in satellite relay applications.
Leading the category by volume: Directional Antennas. Growing fastest: Phased Array Antennas.
Frequency Band:
Spectrum allocation proceedings at the FCC and ITU harmonization efforts determine hardware redesign cycles. Each band carries distinct propagation characteristics and regulatory occupancy rules that shape end-use suitability.
- C-Band:4-8 GHz allocation supports high-data-rate video links for infrastructure inspection and delivery services. FCC reconfiguration proceedings force hardware refreshes among fleet operators. Rain fade susceptibility limits deployment in tropical agricultural corridors.
- L-Band:1-2 GHz propagation penetrates foliage and urban clutter for wildlife tracking and disaster management. EASA U-space detect-and-avoid mandates favor this band for beyond-visual-line-of-sight certification. Spectrum congestion from satellite navigation systems constrains channel availability.
- UHF:300 MHz-1 GHz ground-wave propagation serves long-range telemetry over maritime horizons.
- VHF:30-300 MHz legacy allocation persists in military command links with established interoperability protocols.
- S-Band:2-4 GHz balances bandwidth and atmospheric attenuation for weather-resistant surveillance networks.
- X-Band:8-12 GHz military allocation supports high-resolution tracking against cluttered electromagnetic backgrounds.
Highest revenue concentration: C-Band. Steepest expansion trajectory: L-Band.
Application:
Mission-specific link budgets and environmental hardening requirements segment demand across civilian and defense procurement channels. Each application imposes distinct size, weight, and power constraints on antenna selection.
- Surveillance:Directional arrays with sub-degree beamwidth track non-cooperative targets across contested airspace. NATO counter-UAS procurement consolidates requirements under unified electromagnetic spectrum management. Classification thresholds restrict vendor access to performance specifications.
- Agriculture Monitoring:Portable tracking stations serve seasonal crop monitoring across North American grain belts. FAA BVLOS waiver expansion accelerates fleet scaling for multispectral imaging operators. Dust and vibration tolerance drives sealed enclosure specifications.
- Infrastructure Inspection:High-gain directional links maintain video quality for power line and pipeline surveys.
- Delivery Services:Compact phased arrays enable urban vertiport coverage with rapid beam reconfiguration.
- Disaster Management:Rapidly deployable omnidirectional systems establish ad-hoc networks in communications-denied environments.
- Wildlife Tracking:Low-power L-Band tags and receivers monitor migration patterns across protected reserves.
Dominant procurement volume: Surveillance. Gaining share fastest: Agriculture Monitoring.
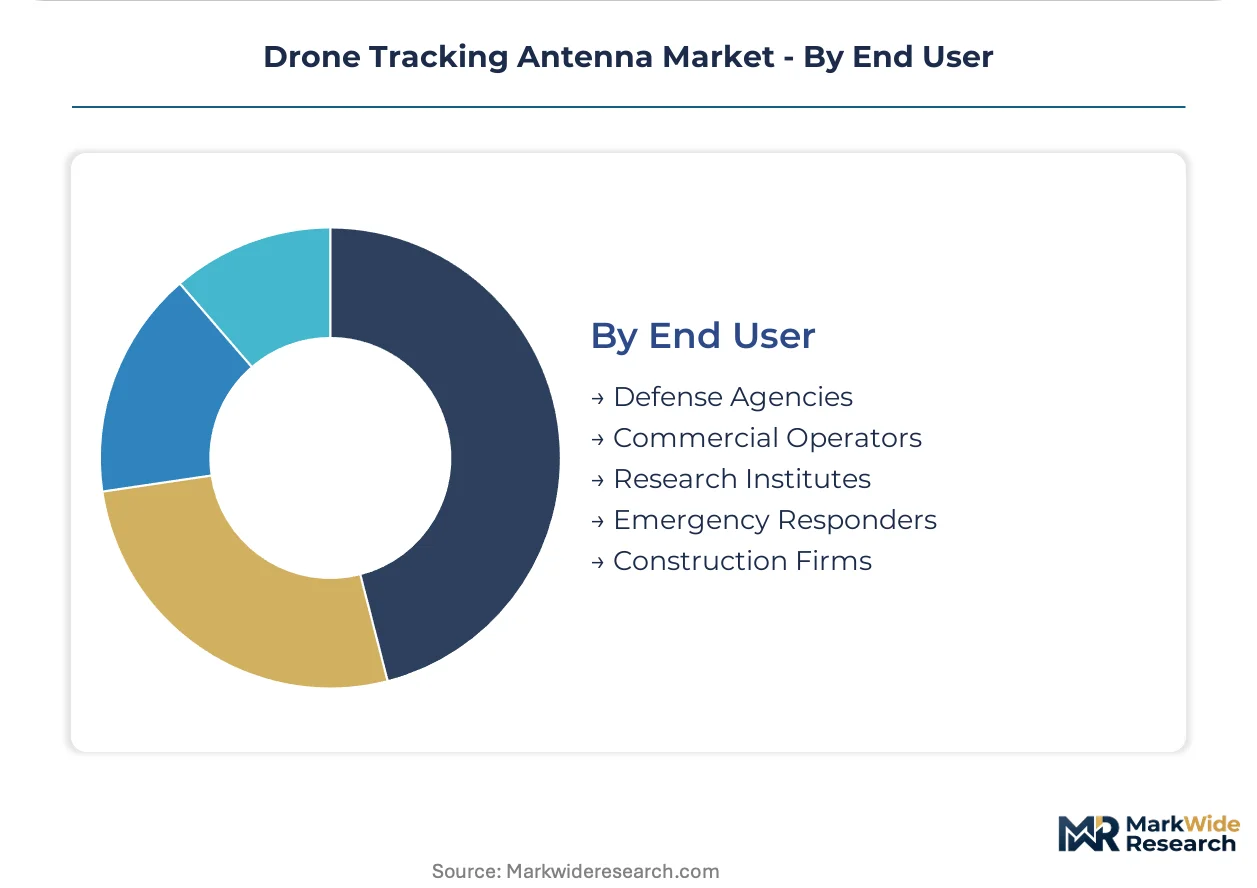
End User:
Procurement authority and evaluation criteria diverge sharply between classified defense programs and commercial fleet operations. Total-cost-of-ownership calculations favor vendors with captive software pipelines in federal channels.
- Defense Agencies:Multi-year managed service agreements replace capital equipment sales across Pentagon tracking infrastructure. Classified R&D pipelines anchor long-term vendor relationships. Cybersecurity framework compliance elevates barriers for non-traditional suppliers.
- Commercial Operators:Agricultural and delivery fleet managers prioritize firmware upgrade paths over hardware durability. Part 89 compliance deadlines compress procurement cycles through 2028. Price sensitivity concentrates demand on mid-tier phased array configurations.
- Research Institutes:Academic and government laboratory procurement favors software-defined architectures for experimental waveform development.
- Emergency Responders:Rapid deployment requirements drive demand for ruggedized portable systems with minimal setup complexity.
- Construction Firms:Infrastructure inspection contracts generate seasonal antenna demand tied to project bidding cycles.
Commanding the dominant margin pool: Defense Agencies. Expanding most quickly: Commercial Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Washington D.C.-Northern Virginia corridor anchors defense procurement concentration for drone tracking infrastructure, with Pentagon contracting offices and FAA headquarters co-located within fifty miles.
United States
Defense agencies command procurement volume through multi-year managed service agreements for border surveillance programs. FAA Part 89 mandates drive commercial fleet upgrades through 2028 compliance windows. The Arizona-California border corridor hosts fixed-site installations for counter-UAS testing.
Germany
EASA U-space framework implementation accelerates detect-and-avoid hardware certification for urban air mobility corridors. The country's national aerospace regulator enforces electromagnetic compatibility standards parallel to military specifications. Bavaria's Munich-Stuttgart technology belt concentrates radar engineering talent for phased array development.
United Kingdom
RAF procurement consolidates tracking infrastructure under unified electromagnetic spectrum management protocols. Civil Aviation Authority remote ID rules mirror FAA compliance timelines for commercial operators. The Farnborough-Aldershot defense cluster houses NATO counter-UAS program offices.
Israel
Border security programs generate sustained demand for portable tracking arrays in contested electromagnetic environments. The Ministry of Defense maintains classified performance specifications for electronic warfare-hardened systems. Tel Aviv's coastal technology corridor specializes in firmware-defined beamforming stacks.
South Korea
Agency for Defense Development funding accelerates domestic GaN transmit-receive module production for electronic steering applications. The national radio regulator allocates spectrum for drone command links under ITU harmonization preparations. Seoul Capital Area manufacturers supply compact phased arrays for urban vertiport coverage.
Drone Tracking Antenna Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the defense electronics supply chain, with foundry-dependent vendors facing substrate concentration risks while firmware specialists capture recurring revenue streams. The vendor base stratifies between Pentagon service contractors with classified pipelines and commercial hardware suppliers chasing Part 89 compliance deadlines. Three archetypes dominate: defense primes with captive software development, mid-tier phased array specialists, and legacy directional antenna fabricators. Competitive moves concentrate on strategic partnerships for GaN foundry access and portfolio diversification into agricultural monitoring segments.
Within the defense prime tier, RTX and Lockheed Martin Corporation occupy positions sustained by long-term Pentagon service contracts and classified R&D pipelines. Thales exemplifies the European NATO market specialist archetype, anchoring vendor relationships through modular upgrade paths for legacy installations. Elbit Systems Ltd. represents the border security-focused competitor, sitting within the segment where portable array demand concentrates in contested electromagnetic environments.
| Leading Market Players |
|---|
| RTX |
| Northrop Grumman |
| Lockheed Martin Corporation |
| Thales |
| Elbit Systems Ltd. |
| Antcom Corporation |
| Antenna Research Associates, Inc. |
| Southwest Antennas, Inc. |
| TE Connectivity |
| Others |
Pricing and Supply Chain Analysis
Captive GaN foundry partnerships anchor supply positioning for phased array vendors while simultaneously hardening pricing power against substrate volatility. Defense primes with in-house transmit-receive module production command premium positioning, whereas commercial antenna fabricators without substrate control face margin compression from East Asian supply concentration.
Pricing Analysis
Cost-down pressure on commercial phased array tiers accelerates because firmware-defined beam stacks commoditize hardware differentiation. Pricing stratifies across defense-grade classified configurations, FAA-certified commercial systems, and uncertified agricultural monitoring units. Certification tier and GaN substrate sourcing drive price differentiation. Commercial operators exhibit highest price sensitivity, while Pentagon service contractors prioritize total-cost-of-ownership over unit economics.
Supply Chain Analysis
Defense-grade electromagnetic compatibility certification gates supplier qualification, extending vendor onboarding timelines. GaN substrate production concentrates in Taiwan, Japan, and South Korea. Raw material dependencies include high-purity gallium nitride wafers, RF ceramic substrates, and precision machined aluminum enclosures. Single-source vulnerability from East Asian foundry concentration threatens delivery reliability. Distribution runs through defense prime contractor integration channels and direct commercial fleet operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
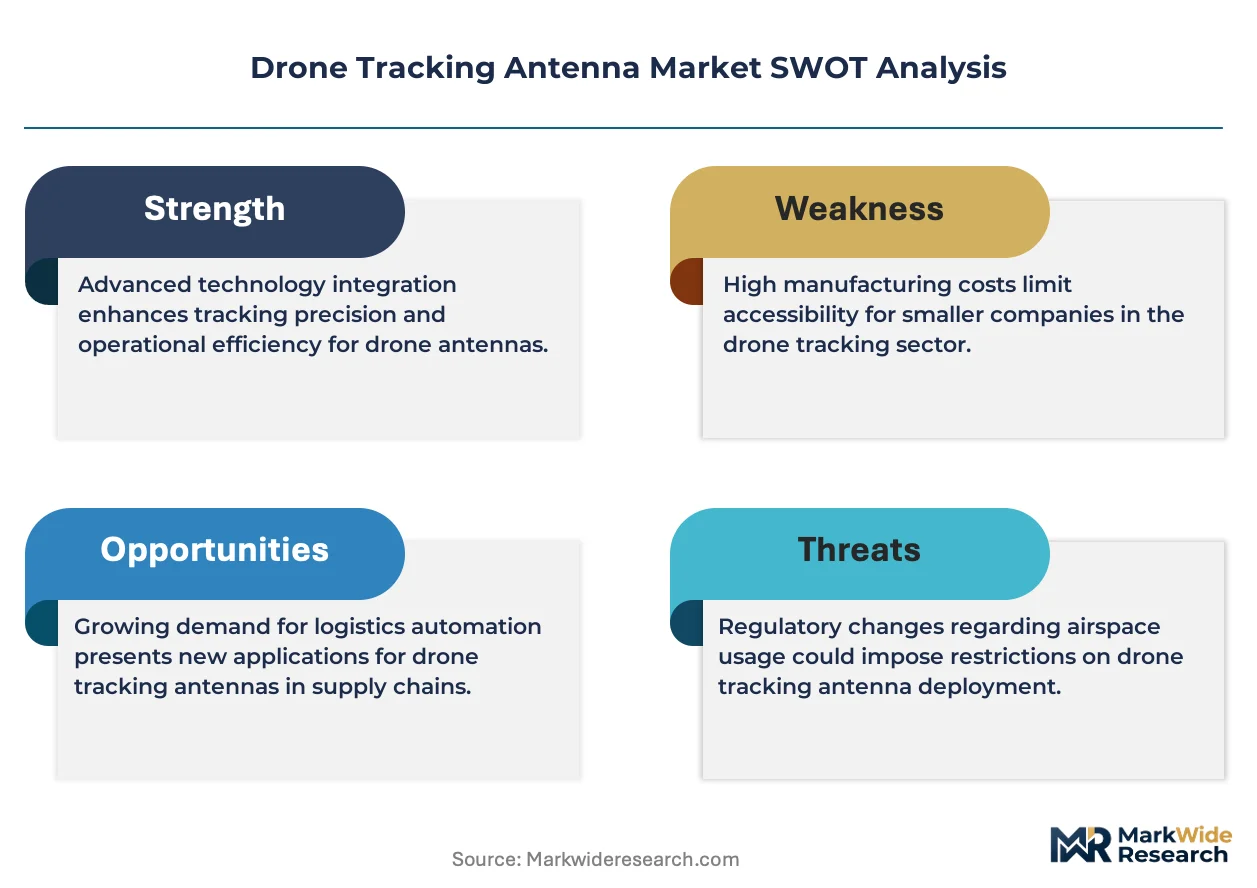
This market functions as a vertical-integration race where GaN substrate control and firmware development pipelines determine long-term margin capture. Players without captive foundry access or classified R&D relationships face structural disadvantage.
For Market Incumbents: Lock in GaN substrate offtake agreements before foundry capacity tightens further. Deepen firmware subscription bundling to extend customer switching costs against emerging software-defined radio competitors. Prioritize Pentagon service contract renewals over hardware margin expansion. For New Entrants and Emerging Players: Launch via portable phased array configurations for agricultural BVLOS waiver operators, bypassing defense certification barriers. Target North American grain belt monitoring fleets with seasonal rental models rather than capital sales. Pursue rapid EASA U-space certification to access European urban air mobility corridors ahead of incumbent hardware refresh cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime acquisition of firmware specialists and commercial antenna fabricators. Long-term viability hinges on software-defined architecture adoption and regulatory certification velocity. Watch FAA Part 89 enforcement intensity as inflection indicator for commercial hardware replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures substrate supply for high-power phased array production against East Asian concentration. |
| Firmware Subscription Unbundling | Shifts revenue from hardware sales to recurring service streams across Pentagon tracking programs. |
| EASA U-Space Certification Investment | Unlocks European urban air mobility corridor access ahead of detect-and-avoid mandates. |
| Agricultural BVLOS Waiver Targeting | Captures fastest-expanding commercial segment with portable tracking station demand. |
| Classified R&D Pipeline Expansion | Maintains defense prime positioning through next-generation directional array development. |
Research Methodology
Document review covered defense procurement databases, FCC spectrum allocation proceedings, and EASA regulatory filings, complemented by interviews with RF engineering directors at phased array manufacturers, Pentagon program managers, commercial drone fleet operators, and agricultural monitoring service providers. Secondary validation drew from FAA remote ID compliance records, NATO electromagnetic spectrum management protocols, and customs trade data for GaN substrate flows. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Historical shipment trajectories cross-referenced against expert panel input on solid-state TR module adoption curves across the projection horizon. Segmentation dimensions modeled include antenna architecture type, frequency band allocation, mission application profile, and end-user procurement authority. CAGRs derived from regression analysis of defense electronics spending patterns and commercial BVLOS waiver issuance rates. Industry-specific forecast inputs incorporated GaN foundry capacity expansion announcements and pending ITU harmonization timelines.
Geopolitical supply disruption, regulatory certification timeline slippage, and spectrum allocation reconfiguration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding defense procurement continuity and commercial fleet scaling trajectories. A model refresh is warranted upon material change in FAA Part 89 enforcement posture or GaN substrate trade flow restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Tethered Drones Market
UAV
Small Drone Market
UAV
Global Target Drone Market
UAV
Anti-Drone Market
UAV
Europe Drones Market
UAV
Global Drone Inspection and Monitoring Market
UAV
Global Drone Autopilots Market
UAV
Drone Defense System Market
UAV
UAV Payload Market
UAV
Enterprise Drone Management Solutions Market
UAV
UAV Navigation Systems Market
UAV
Commercial Drone-Enabled Services Market
UAV
Drone-Based Consulting Services Market
UAV
UAV Battery Market
UAV
Inspection Drones in Confined Space Market
UAV
UAV Simulator Market