
 GCC Drones Market | 2026-2036
GCC Drones Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Drones Market Foresight
Software-defined flight planning and predictive maintenance subscriptions are broadening recurring revenue streams beyond hardware sales. SZ DJI Technology Co., Ltd. leverages its integrated flight controller ecosystem to dominate consumer and prosumer segments across Gulf retail channels. General Atomics sustains its position in long-endurance military-grade platforms through direct government relationships in Saudi Arabia and the UAE. Parrot Drones SAS differentiates via open-source architecture that appeals to research institutions and custom integrators seeking payload flexibility.
Drones are unmanned aerial vehicles operating through remote piloting or autonomous navigation systems, typically incorporating GPS modules, inertial measurement units, and radio-frequency communication links with operational altitudes from ground level to regulated ceiling limits. These systems serve commercial and government end users by replacing manned aviation for hazardous, repetitive, or precision-dependent aerial tasks. Rotary-wing configurations lead current GCC procurement volumes due to vertical takeoff versatility in congested oil facilities and urban environments. AI Integration represents the fastest-expanding technology segment as operators demand automated defect recognition in infrastructure and energy assets. Fixed-wing platforms occupy mature margin pools in large-area agricultural surveying and coastal mapping applications where endurance outweighs maneuverability requirements.
GACA in Saudi Arabia and GCAA in the UAE enforce airspace classification and operator certification requirements that directly determine market access for foreign manufacturers and local service providers. The Saudi Communications and Information Technology Commission and UAE's Telecommunications and Digital Government Regulatory Authority coordinate spectrum allocation for command-and-control links and beyond-visual-line-of-sight data transmission. Stakeholders must monitor evolving national security screening protocols for imported components and emerging emirate-level urban air mobility frameworks that will reshape competitive licensing requirements.
Market Dynamics
GCAA and GACA regulations governing beyond-visual-line-of-sight operations are forcing equipment procurement standards that favor integrated system providers over component vendors across Saudi Arabia and the UAE.
Growth Catalysts
- BVLOS Regulatory Frameworks:GCAA certification pathways in the UAE and GACA approvals in Saudi Arabia are creating compliance-driven replacement cycles for legacy drone fleets in energy infrastructure.
- Flare Stack Monitoring:Oil and gas operators across the Arabian Peninsula are deploying thermal imaging payloads to replace manned helicopter inspections of elevated combustion systems.
- AI-Powered Defect Recognition:Machine vision algorithms trained on pipeline corrosion patterns are reducing inspection cycle times from weeks to hours in Abu Dhabi's onshore fields.
Market Restraints
- Import Component Screening:National security protocols for radio-frequency modules and GPS receivers are extending procurement timelines for foreign manufacturers serving Saudi and Emirati defense contracts.
- Lithium Battery Supply Concentration:Cell production concentrated in East Asian suppliers creates vulnerability for GCC operators requiring high-cycle endurance in desert temperature extremes.
- Spectrum Allocation Fragmentation:Divergent C-band and S-band assignments between Saudi Arabia's Communications and Information Technology Commission and UAE's Telecommunications and Digital Government Regulatory Authority complicate cross-border fleet standardization.
Strategic Opportunities
- Urban Air Mobility Corridors:Dubai's designated drone delivery zones are attracting logistics operators seeking first-mover positioning in last-mile aerial transport.
- Research Institution Partnerships:Open-source flight controller architectures are enabling custom payload integration for universities and national labs across the Gulf seeking experimental flexibility.
- Predictive Maintenance Subscriptions:Software-as-a-service flight planning tools are creating recurring revenue streams that decouple vendor economics from hardware replacement cycles.
Industry Challenges
- Certified Pilot Shortage:GCAA and GACA remote operator license requirements are outpacing training program capacity across Dubai, Abu Dhabi, and Riyadh.
- Legacy SCADA Integration:Oil facility operators face protocol translation complexity when connecting autonomous drone data streams to decades-old distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Drones Market |
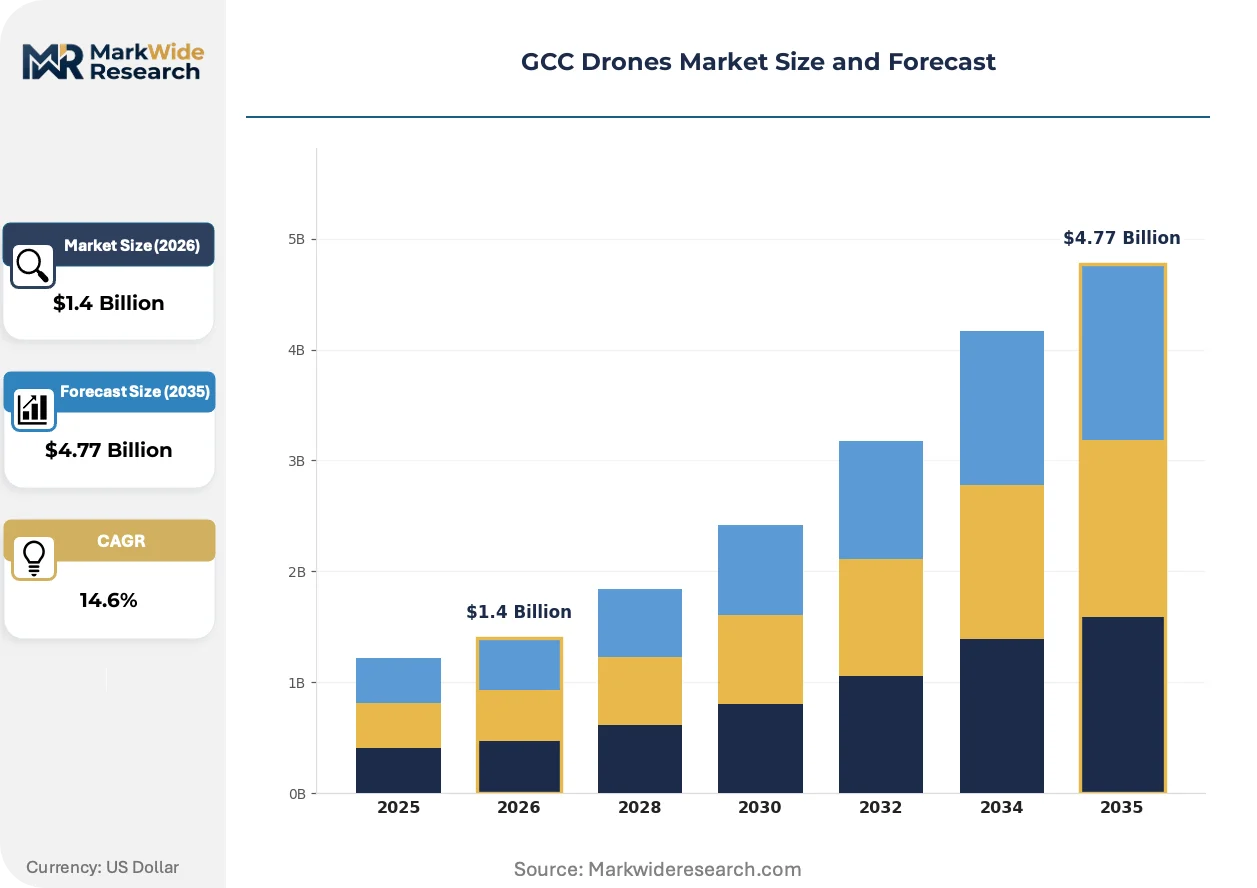
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid VTOL, Nano Drones, Micro Drones Technology: GPS Navigation, Infrared Sensors, Lidar, AI Integration, 5G Connectivity Application: Agricultural Surveying, Oil & Gas Inspection, Infrastructure Monitoring, Disaster Management, Security Surveillance End User: Government Agencies, Construction Firms, Energy Operators, Emergency Responders, Research Institutions |
| Companies Covered | Yuneec, Primoco UAV SE, SZ DJI Technology Co., Ltd., AgEagle Aerial Systems Inc., Terra Drone Corporation, Parrot Drones SAS, Autel Robotics Co., Ltd., General Atomics, FalconViz, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Drones Market Shifts & Advancements
Flight autonomy stacks are migrating from hardware-dependent controllers to software-defined architectures that enable over-the-air capability upgrades without airframe replacement.
Edge computing modules installed directly on rotary-wing platforms are converging with 5G network slicing to enable real-time defect classification without ground station dependency. Aramco and ADNOC inspection teams are piloting these configurations across Khurais and Bab onshore complexes. The compression of decision latency from hours to seconds is converging with predictive maintenance workflows to restructure contractor-vendor relationships around data service agreements rather than flight-hour billing.
GACA's 2024 unmanned aircraft systems regulations and GCAA's operational authorization frameworks are mandating detect-and-avoid capabilities for commercial BVLOS flights above 400 feet. These rules are accelerating procurement of acoustic and optical sense-and-avoid payloads. Energy sector operators in Saudi Arabia's Eastern Province and Abu Dhabi's Al Dhafra region are prioritizing certified systems to preempt airspace access restrictions.
Service contracts are fragmenting from bundled hardware-software-operator packages toward unbundled component sourcing that lets end users mix flight platforms, analytics software, and pilot services from separate vendors. ADNOC and Saudi Aramco maintenance divisions are leading this disaggregation in the GCC. The shift is most visible in Abu Dhabi, where system integrators now compete on API compatibility rather than vertical solution completeness.
GCC Drones Market Segmentation
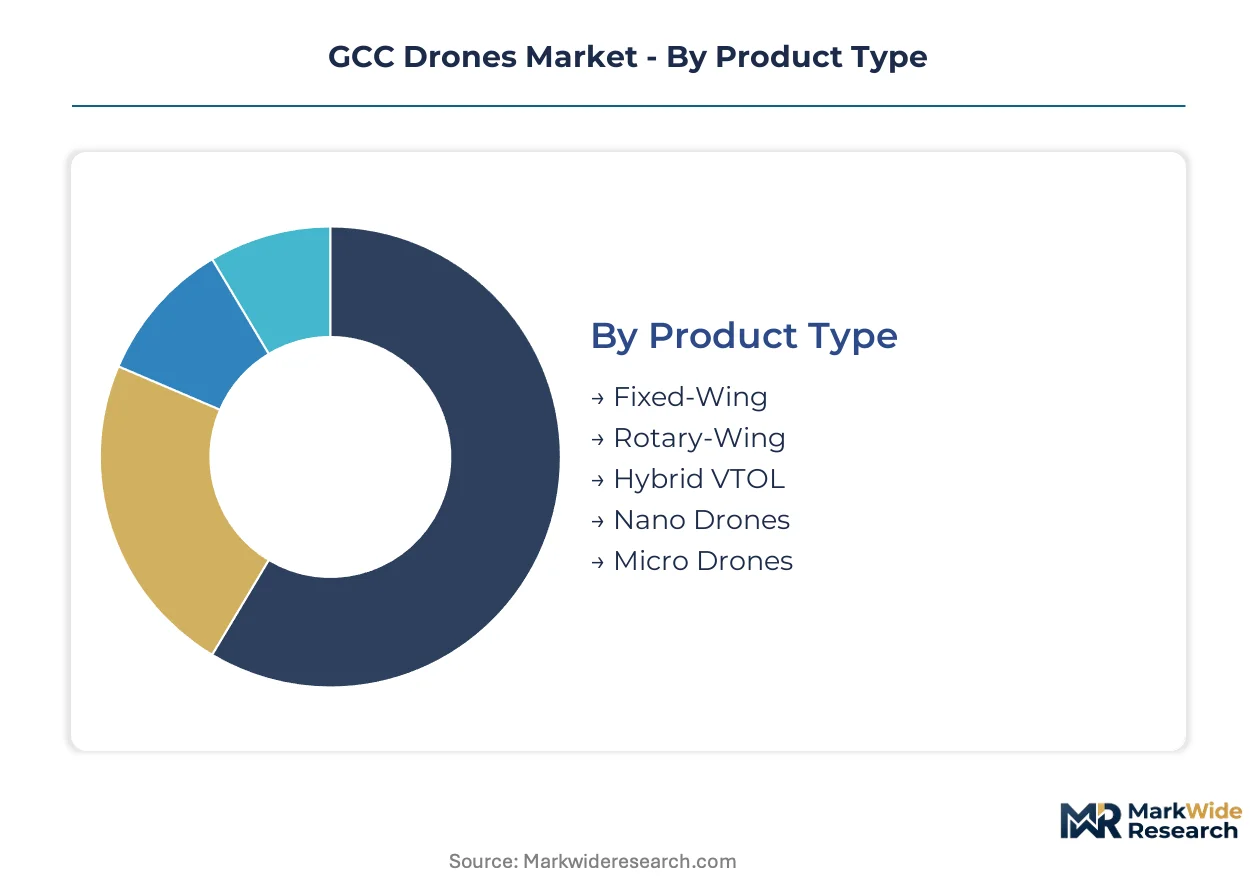
Segmentation in the GCC Drones Market reveals distinct procurement patterns across product architectures and operational domains. Understanding these divisions clarifies where technology investments concentrate and which user groups drive specification requirements.
Product Type:
Standalone rotary-wing platforms dominate fleet deployments across congested oil facilities and urban corridors, while fixed-wing and hybrid systems embed into integrated surveying networks requiring extended endurance.
- Fixed-Wing:These airframes maximize endurance through aerodynamic efficiency, carrying multispectral cameras across coastal mapping contracts in Abu Dhabi and large-area agricultural surveys in Saudi Arabia's Eastern Province. Energy operators prize their range for pipeline corridor monitoring where maneuverability matters less than coverage area.
- Rotary-Wing:Vertical takeoff capability eliminates runway dependency, making these the default choice for flare stack inspections at Saudi Aramco's Khurais complex and Dubai's dense urban delivery corridors. Thermal payload integration for elevated combustion monitoring drives specification priorities.
- Hybrid VTOL:Combines rotary launch with fixed-wing cruise efficiency, appealing to operators spanning both confined infrastructure and expansive terrain in a single mission profile.
- Nano Drones:Sub-250 gram platforms navigate indoor industrial environments and confined-space structural assessments where larger systems face airspace restrictions.
- Micro Drones:Compact form factors suit rapid deployment scenarios across emergency response units in Riyadh and Dubai Civil Defence operations.
Rotary-Wing leads volumes today; Hybrid VTOL is gaining share fastest as operators seek single-platform flexibility across mission types.
Technology:
Cost tiering separates foundational navigation layers from premium autonomy stacks, with mid-tier sensor fusion commanding the largest procurement budgets across GCC energy infrastructure.
- GPS Navigation:Satellite positioning modules provide baseline georeferencing for flight control and data tagging, embedded in virtually every commercial deployment across Saudi and Emirati fleets. GCAA and GACA certification requirements mandate redundant GNSS reception for BVLOS authorization.
- Infrared Sensors:Thermal imaging payloads detect pipeline leaks and flare stack anomalies, replacing manned helicopter inspections across ADNOC's onshore complexes. Desert heat dissipation challenges drive cooling system specifications.
- Lidar:Laser scanning generates centimeter-accurate digital elevation models for infrastructure digital twin construction in Dubai's smart city initiatives.
- AI Integration:Onboard defect recognition algorithms compress inspection cycle times from weeks to hours, with machine vision training concentrated on regional corrosion patterns.
- 5G Connectivity:Network slicing enables real-time data transmission without ground station tethering, piloted across Abu Dhabi's 5G-enabled industrial zones.
GPS Navigation anchors every deployment; AI Integration shows the steepest expansion trajectory as operators automate defect classification workflows.
Application:
Customer maturity varies sharply across use cases, with oil and gas inspection commanding premium pricing while agricultural surveying competes on per-hectare cost efficiency.
- Agricultural Surveying:Multispectral imaging monitors crop health and irrigation efficiency across Saudi Arabia's wheat belts and UAE date palm plantations. Fixed-wing platforms dominate due to acreage requirements, with service providers competing on survey speed per hectare.
- Oil & Gas Inspection:Thermal and visual payload combinations assess pipeline integrity, flare stack combustion efficiency, and tank farm structural conditions. Aramco and ADNOC maintenance divisions drive specification standards through direct vendor relationships.
- Infrastructure Monitoring:Bridge, road, and building assessments utilize high-resolution photogrammetry for defect documentation across Dubai's construction boom and Saudi giga-project developments.
- Disaster Management:Rapid damage assessment and search coordination deploy across flood and sandstorm events in Oman and UAE northern emirates.
- Security Surveillance:Perimeter monitoring and crowd management applications serve critical facility protection and event security across GCC government contracts.
Oil & Gas Inspection commands the highest contract values; Infrastructure Monitoring is expanding most quickly behind giga-project construction timelines.
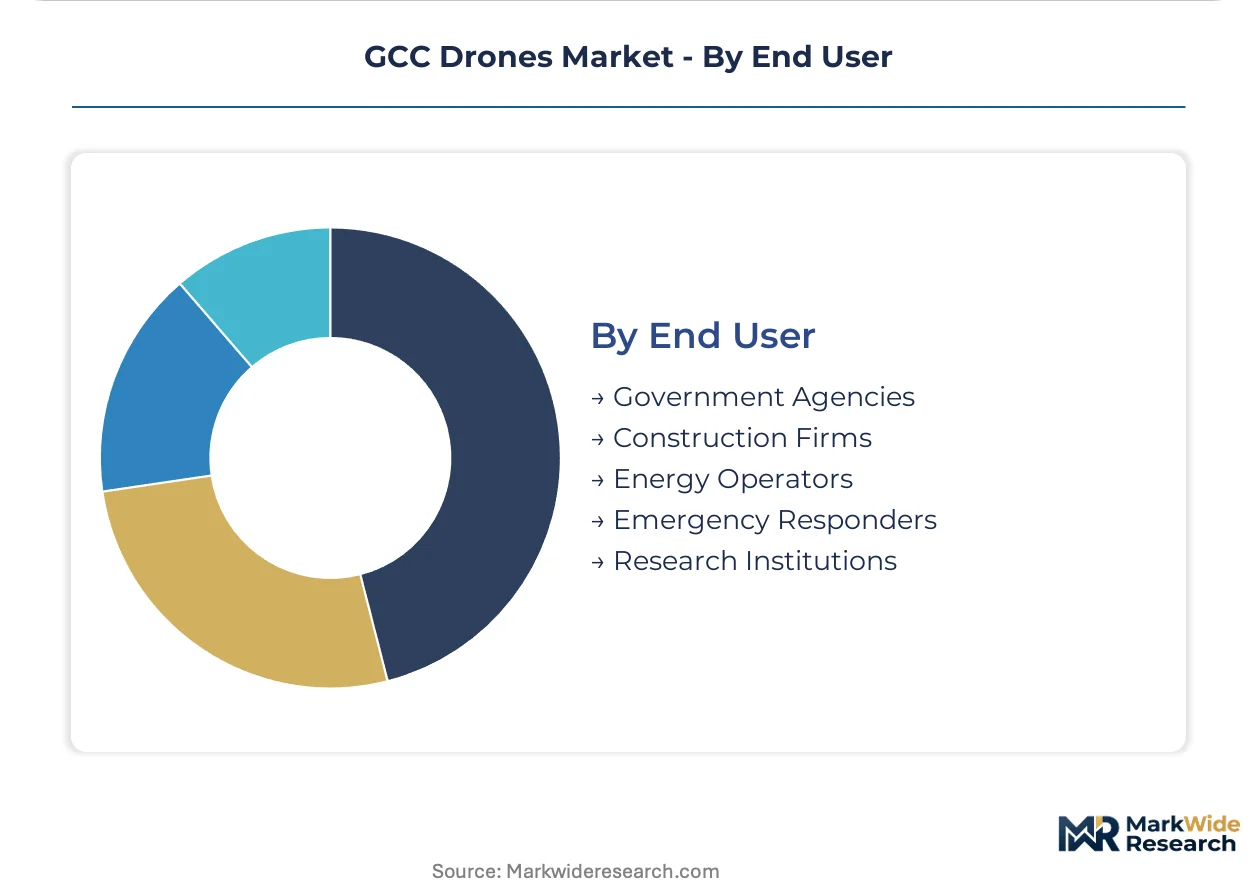
End User:
Procurement authority concentrates in government-linked entities, with energy operators and construction firms representing the fastest-growing commercial segments as BVLOS frameworks mature.
- Government Agencies:National security, border control, and municipal surveillance applications drive large-scale fleet acquisitions through defense and interior ministry budgets across Saudi Arabia and the UAE. GACA and GCAA regulatory development sits within these same institutional structures.
- Construction Firms:Progress monitoring, site surveying, and safety compliance documentation accelerate across Dubai's real estate developments and Saudi giga-projects. Drone-as-a-service models reduce capital barriers for mid-tier contractors.
- Energy Operators:Aramco, ADNOC, and their field service contractors standardize inspection protocols, with predictive maintenance integration reshaping vendor relationships around data service agreements.
- Emergency Responders:Civil defence and ambulance services pilot delivery and reconnaissance applications, with Dubai leading operational authorization for medical payload transport.
- Research Institutions:Universities and national labs across the Gulf leverage open-source architectures for experimental payload integration and autonomy algorithm development.
Government Agencies anchor procurement volumes; Construction Firms are climbing the fastest as project scale demands aerial monitoring scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling drone system procurement toward jurisdictions with clearer beyond-visual-line-of-sight authorization pathways. Operators in the Gulf Cooperation Council states face divergent compliance costs that reshape fleet investment timing and vendor selection across national boundaries.
United Arab Emirates
GCAA's operational authorization frameworks for commercial BVLOS flights above 400 feet are accelerating detect-and-avoid payload procurement. Dubai's designated drone delivery corridors attract logistics operators seeking first-mover positioning in last-mile aerial transport. Abu Dhabi's energy infrastructure investments at Al Dhafra onshore complexes concentrate thermal imaging deployments for flare stack monitoring.
Saudi Arabia
GACA's 2024 unmanned aircraft systems regulations mandate certified systems for airspace access above energy facilities in the Eastern Province. Aramco maintenance divisions standardize inspection protocols, reshaping vendor relationships around predictive maintenance data service agreements. Riyadh's smart city initiatives and giga-project construction timelines drive infrastructure monitoring demand.
Qatar
LNG facility operators deploy thermal payloads for pipeline integrity assessment across Ras Laffan Industrial City. The country's communications regulator coordinates spectrum allocation for command-and-control links in industrial zones. Doha's emergency response units pilot rapid deployment micro-drone configurations for confined-space structural assessments.
Kuwait
Oil sector maintenance divisions evaluate BVLOS certification pathways for refinery inspection applications. The national aviation authority develops alignment with GCC regulatory harmonization initiatives. Kuwait City's construction boom generates progress monitoring demand among mid-tier contractors adopting drone-as-a-service models.
Oman
Coastal mapping contracts across the Sultanate's maritime zones utilize fixed-wing endurance platforms for large-area surveying. Disaster management applications deploy across flood and sandstorm events in northern governorates. Muscat's civil defence operations pilot medical payload transport authorization frameworks.
GCC Drones Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers capturing procurement preference under compliance-driven replacement cycles. Market structure tilts toward consolidated positions among flight controller ecosystem owners while fragmenting across regional service integrators. Three archetypes dominate: full-stack platform vendors, open-source architecture specialists, and government-direct military-grade suppliers. Competitive moves concentrate on strategic partnerships for local certification support and portfolio diversification into predictive maintenance subscriptions.
Within the full-stack platform tier, SZ DJI Technology Co., Ltd. and Autel Robotics Co., Ltd. occupy positions shaped by retail channel penetration across Gulf consumer and prosumer segments. Parrot Drones SAS exemplifies the open-source architecture specialist archetype appealing to research institutions and custom integrators. General Atomics anchors the government-direct tier through long-endurance military-grade platforms. These three company patterns illustrate how vendor selection criteria diverge between commercial infrastructure operators seeking integrated ecosystems and institutional buyers prioritizing payload flexibility or direct government relationships.
| Leading Market Players |
|---|
| Yuneec |
| Primoco UAV SE |
| SZ DJI Technology Co., Ltd. |
| AgEagle Aerial Systems Inc. |
| Terra Drone Corporation |
| Parrot Drones SAS |
| Autel Robotics Co., Ltd. |
| General Atomics |
| FalconViz |
| Others |
Supply & Pricing Matrix
Sovereign-backed energy operators across Saudi Arabia and the UAE anchor procurement volumes through multi-year fleet contracts, compressing margin variability for foreign manufacturers while channeling price discipline through GCAA and GACA certification requirements that favor integrated system providers over component vendors.
Pricing Analysis
Capacity additions in China's flight controller manufacturing base are reshaping price floors for rotary-wing platforms serving GCC energy infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates GCAA-certified BVLOS systems from recreational-grade hardware and enterprise workhorse configurations. Cost compression in the standard tier is intensifying because SZ DJI Technology's ecosystem dominance enables bundled software-hardware pricing that undercuts modular competitors. Government agencies exhibit the least price sensitivity due to national security screening requirements, while mid-tier construction firms adopting drone-as-a-service models drive procurement toward operational-expense structures that reduce upfront capital barriers.
Supply Chain Analysis
GACA's local-content mandates and the UAE's In-Country Value programs are reshaping sourcing patterns for system integrators seeking government contracts. Component manufacturing concentrates in China, South Korea, and Taiwan for lithium battery cells, radio-frequency modules, and GPS receivers. Raw material dependencies span cobalt for thermal imaging sensors, rare earth elements for motor magnets, and advanced composites for airframe construction. Single-source vulnerability runs through East Asian battery cell suppliers, where desert temperature extremes accelerate degradation cycles and create inventory management complexity. Distribution runs through Dubai's Jebel Ali free zone logistics hubs, with regional system integrators handling last-mile certification support and pilot training bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCAA's operational authorization frameworks create a geographic-arbitrage window: operators establishing Dubai-based certification pipelines access BVLOS airspace faster than Saudi entrants facing GACA's extended approval timelines, compressing time-to-revenue for compliant fleet deployments.
For Market Incumbents: Anticipate disaggregation pressure from ADNOC and Saudi Aramco maintenance divisions unbundling hardware-software-operator packages into separate vendor relationships. Defend position by deepening API compatibility investments that preserve integration revenue as service contracts fragment. Prioritize predictive maintenance subscription development to decouple economics from hardware replacement cycles threatened by AI-powered defect recognition commoditization.
For New Entrants and Emerging Players: Launch via open-source flight controller partnerships with Khalifa University and King Abdullah University of Science and Technology research programs, where payload flexibility requirements outstrip incumbent ecosystem rigidity. Target the hybrid VTOL segment, where single-platform versatility across confined infrastructure and expansive terrain missions remains underserved by rotary-wing specialists. Pursue emirate-level urban air mobility framework pre-qualification before federal certification pathways mature.
For Investors and Strategic Acquirers: Defense and interior ministry procurement offices across Riyadh and Abu Dhabi are the most active acquirer in this space, consolidating vendor relationships around long-endurance platforms with direct government liaison capabilities. Five-to-ten year viability hinges on predictive maintenance data service economics replacing flight-hour billing models. Watch for GACA-GCAA regulatory harmonization announcements as the inflection signal for cross-border fleet standardization plays.
| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Investment | GCAA operational authorization unlocks commercial airspace above 400 feet across Dubai's drone delivery corridors. |
| Predictive Maintenance Platform Launch | Software-as-a-service flight planning tools create recurring revenue streams independent of hardware replacement cycles at Aramco facilities. |
| Research Institution Partnership | Open-source architecture integration with UAE and Saudi national labs enables custom payload development for experimental autonomy algorithms. |
| Detect-and-Avoid Payload Procurement | Acoustic and optical sense-and-avoid systems satisfy GACA's 2024 unmanned aircraft systems regulations for energy facility airspace access. |
| Local Content Compliance Program | In-Country Value certification qualifies system integrators for Abu Dhabi government-linked procurement preferences. |
Research Methodology
Multiple input streams — primary interviews with GCAA-certified remote operators and GACA regulatory affairs leads, secondary validation through customs records and telecommunications regulator spectrum allocation filings, and technical specification analysis of procurement tenders from ADNOC and Saudi Aramco maintenance divisions — were reconciled through bottom-up fleet deployment tracking and top-down market sizing across the GCC member states.
Data-stream reconciliation anchored volume projections to segment-specific adoption curves across rotary-wing, fixed-wing, and hybrid VTOL configurations, with technology tiering modeled for GPS navigation baseline systems through AI integration premium stacks. CAGRs were derived from regression analysis of replacement cycle timing, regulatory authorization velocity, and energy infrastructure capital expenditure patterns. Forecast inputs incorporated BVLOS certification pathway completion rates and lithium battery supply lead time variability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GACA-GCAA regulatory divergence scenarios or East Asian battery supply disruptions. Projections reflect assumptions regarding GCAA operational authorization framework stability and sovereign energy operator procurement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Asia-Pacific Drone Light Shows Market
UAV
Middle-East and Africa Drones Market
UAV
FPV Drone Goggles Market
UAV
Drone Defense System Market
UAV
Europe Drone Services Market
UAV
Small Drone Market
UAV
Fuel Cell UAV Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Drone Inspection Service Market
UAV
Drone Camera Market
UAV
Miniature Drone Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Drone-Based Consulting Services Market
UAV
Passenger Drones Market
UAV
Portable Drone Market
UAV
UAV Battery Market