
 North America Missiles and Missile Defense Systems Market | 2026-2036
North America Missiles and Missile Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Missiles and Missile Defense Systems Market Analytics
A widening capability gap in hypersonic tracking and kill-vehicle integration is rotating capital toward primes with established test infrastructure. Lockheed Martin leverages its Sunnyvale satellite integration campus to sustain long-range interceptor production lines. RTX Corporation anchors the radar and sensor layer through its consolidated airborne and space-based aperture programs.
Missiles and missile defense systems encompass propulsion, guidance, and intercept subsystems engineered to engage targets at velocities exceeding Mach 5 with centimeter-class accuracy, serving strategic deterrence and territorial defense missions for state and allied security architectures. Ballistic missiles occupy the mature revenue base, while interceptor technology captures expanding R&D allocations as layered defense architectures proliferate. Sea-based platforms dominate deployment economics through Aegis-equipped destroyer fleets, though space-enabled systems attract the fastest policy momentum.
The Missile Defense Agency governs system-of-systems architecture and test validation protocols, while the Department of Defense's Joint Requirements Oversight Council shapes funding priorities through capability-based assessments. Canada's Department of National Defence coordinates NORAD modernization commitments, tightening cross-border supplier qualification standards. Stakeholders must weigh sovereign production mandates against binational supply chain efficiencies as procurement rules tighten.
Market Dynamics
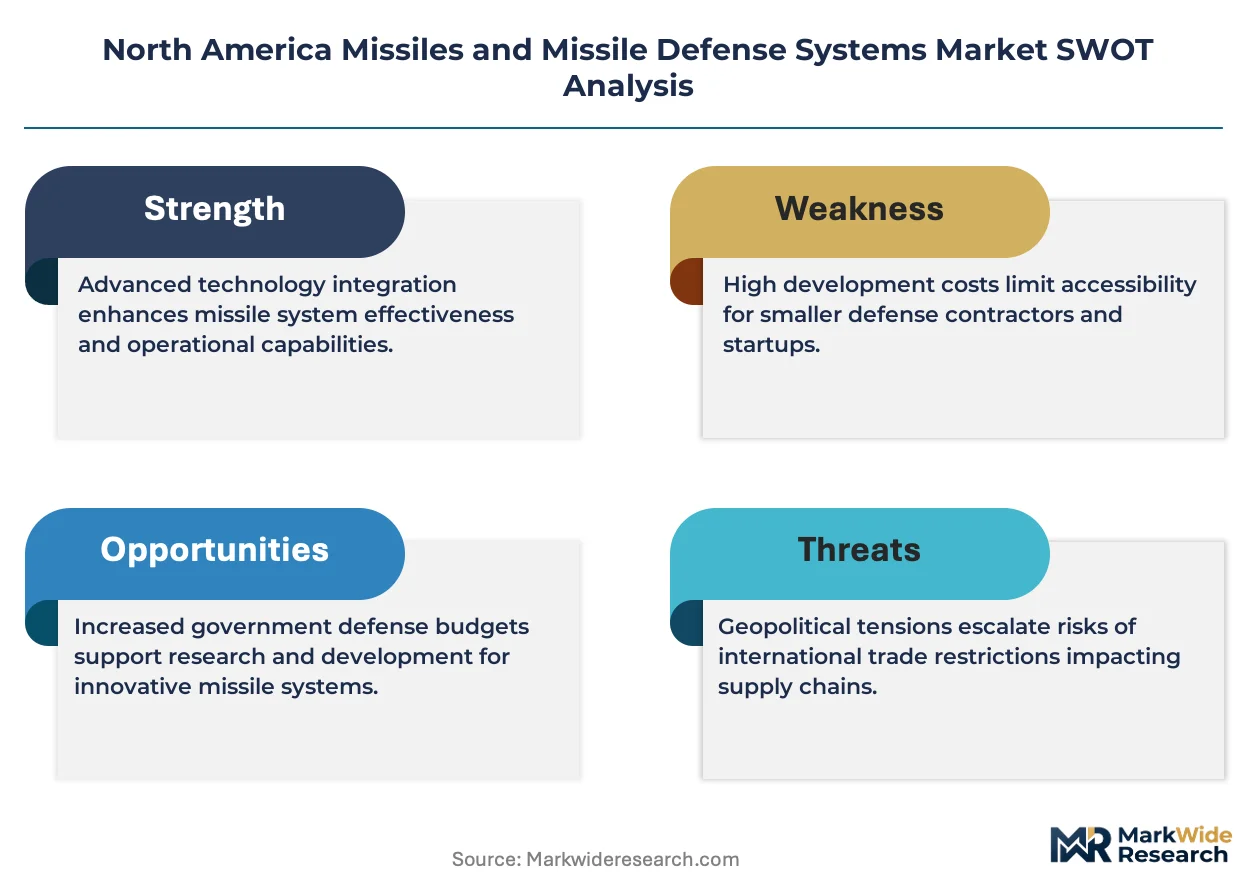
The Missile Defense Agency's layered architecture mandate is compressing development cycles for hypersonic interceptors while forcing primes to consolidate test infrastructure across the southwestern United States.
Growth Catalysts
- NORAD Modernization Commitments:Canada's Department of National Defence is accelerating binational procurement protocols for integrated air defense, tightening cross-border supplier qualification standards and expanding addressable contract pools.
- Hypersonic Threat Proliferation:Adversary advances in maneuverable re-entry vehicles are driving Pentagon acquisition priority shifts toward next-generation tracking and kill-vehicle integration programs.
- Arizona-New Mexico Test Cluster:Concentrated ranges and production facilities in these states are attracting specialized engineering talent and captive supply chain investments.
Market Restraints
- Rare Earth Magnet Dependency:Guidance system actuators and radar components rely on Chinese-processed neodymium and dysprosium, exposing programs to export restriction volatility.
- ITAR Compliance Friction:The Department of State's International Traffic in Arms Regulations impose multi-month licensing delays on Canadian subcontractor integration, compressing joint program margins.
- Silicon Carbide Substrate Scarcity:Power electronics for directed energy weapons face single-source supply concentration from a limited domestic foundry base.
Strategic Opportunities
- Space-Based Sensor Layer:Low-earth orbit constellations for hypersonic tracking represent an underpenetrated procurement channel with dedicated funding through the Space Development Agency.
- Canadian Arctic Infrastructure:NORAD's northern warning system upgrades create demand for hardened interceptors and over-the-horizon radar installations across Nunavut and the Northwest Territories.
- Digital Engineering Mandates:The Department of Defense's model-based systems engineering directives are opening procurement pathways for simulation and digital twin providers.
Industry Challenges
- Hypersonic Aerodynamics Talent Gap:Specialized expertise in high-Mach thermal protection and control systems remains concentrated at a handful of national laboratories and primes, constraining workforce scaling.
- Legacy System Integration Complexity:New interceptors must interface with decades-old command-and-control architectures, extending qualification timelines and inflating non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Missiles and Missile Defense Systems Market |
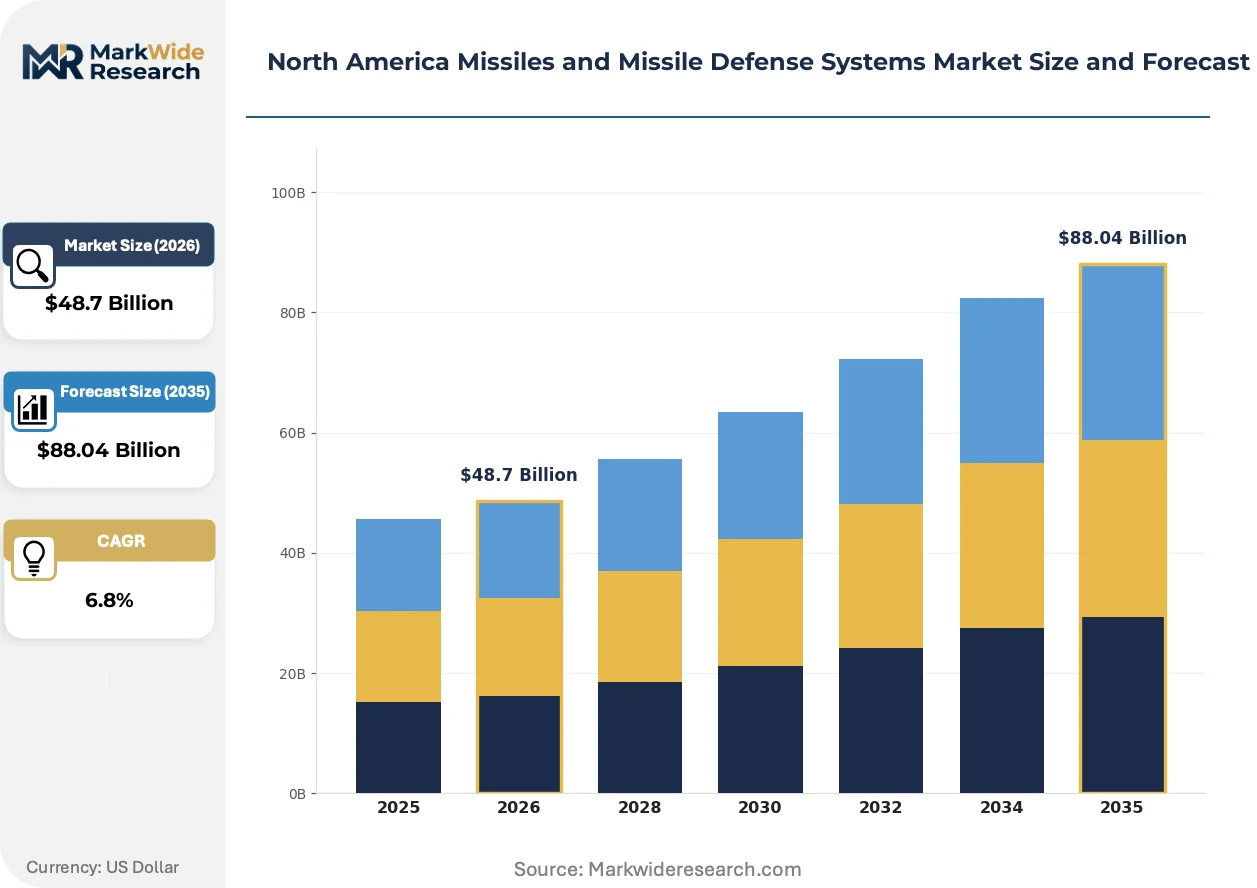
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Missiles, Cruise Missiles, Surface-to-Air Missiles, Air-to-Air Missiles Technology: Guided Systems, Unmanned Aerial Vehicles, Missile Defense Radars, Interceptor Technology End User: Military, Government, Homeland Security, Defense Contractors Deployment: Land-Based Systems, Sea-Based Platforms, Airborne Systems, Space-Enabled Systems |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, The Boeing Company, General Dynamics Corporation, L3Harris Technologies, BAE Systems Inc., Leidos, Kratos Defense & Security Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Missiles and Missile Defense Systems Market Evolving Landscape
Digital engineering workflows are compressing design-validation cycles while redirecting capital toward software-defined capabilities and modular hardware architectures that accommodate rapid threat evolution.
Solid-state laser emitters are supplanting chemical oxygen-iodine systems for directed energy interceptors. The Missile Defense Agency is funding diode-pumped architectures for airborne platforms. This transition is enabling smaller aperture sizes and faster recharge cycles that chemical systems cannot match.
The Department of Defense's software acquisition pathway is mandating continuous integration pipelines for weapon system updates. Contractors must now deliver iterative capability releases rather than monolithic block upgrades. Sea-based platforms are adapting fastest due to Aegis combat system's open architecture foundations.
Buyers are consolidating vendor relationships around primes with captive test infrastructure. The Pentagon's emphasis on speed-to-capability is compressing traditional competitive prototyping phases. Arizona and New Mexico facilities are capturing disproportionate program office attention due to range availability and cleared workforce density.
North America Missiles and Missile Defense Systems Market Segmentation
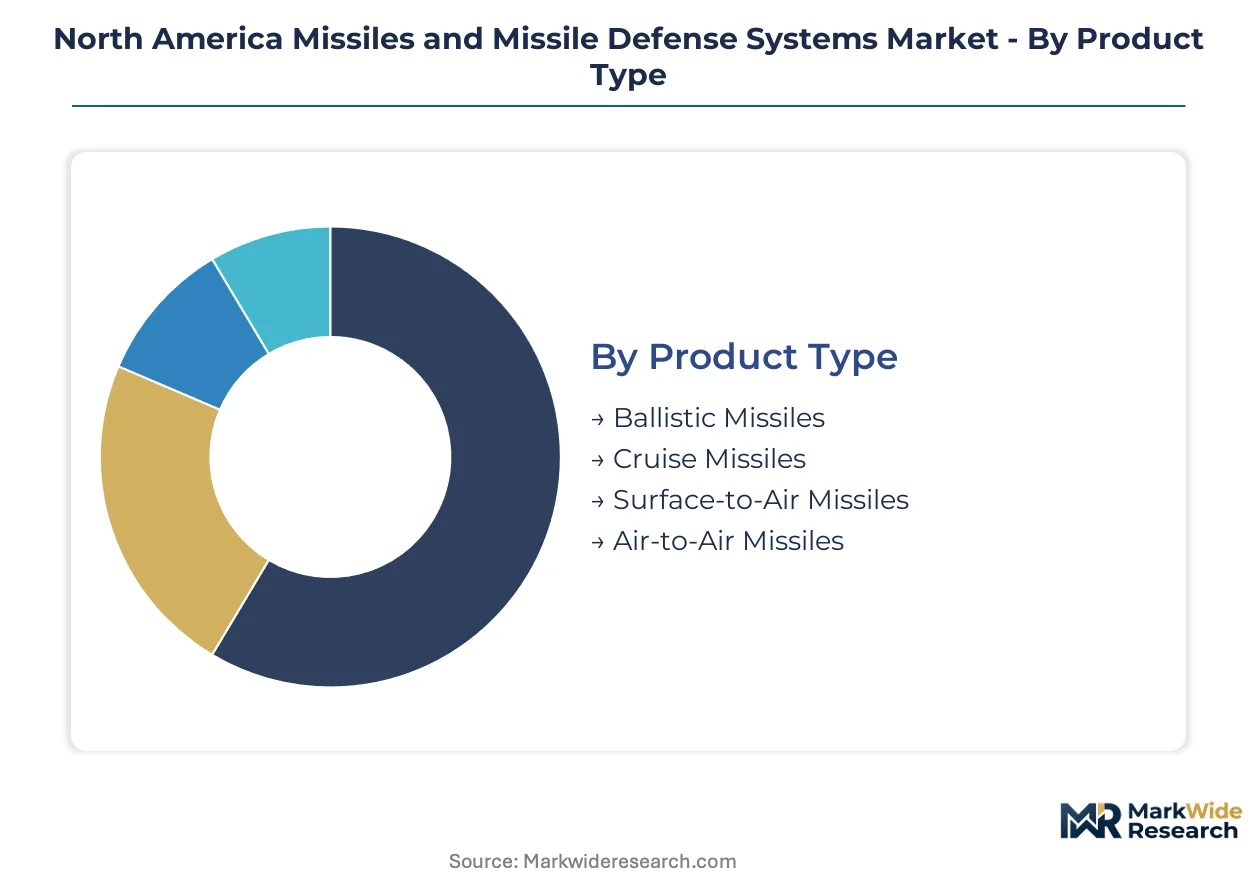
Segmentation in North American missiles and missile defense systems reveals how procurement priorities fragment across threat profiles and platform requirements. The Missile Defense Agency's layered architecture mandate creates distinct technology clusters, each demanding specialized supplier capabilities and test infrastructure access.
Product Type:
Domestic procurement dominates ballistic and cruise missile programs through Pentagon system-of-systems acquisitions, while interceptor exports to allied nations concentrate in surface-to-air and air-to-air categories.
- Ballistic Missiles:Solid and liquid propulsion systems designed for strategic deterrence missions with intercontinental range capabilities. Demand concentrates in the southwestern United States, where Arizona and New Mexico test ranges support qualification cycles for next-generation re-entry vehicles. The Missile Defense Agency's hypersonic tracking requirements are extending development timelines for maneuverable payloads.
- Cruise Missiles:Air-breathing propulsion with terrain-following guidance architectures for precision strike applications. Canadian Department of National Defence procurement is expanding addressable contract pools through NORAD modernization commitments, tightening cross-border supplier qualification standards for propulsion subsystems.
- Surface-to-Air Missiles:Area and point defense interceptors with active radar homing for territorial protection.
- Air-to-Air Missiles:Beyond-visual-range and short-range dogfight configurations for fighter aircraft integration.
Ballistic missiles command the established base. The steepest expansion runs through surface-to-air interceptors as layered defense architectures proliferate.
Technology:
Cost tier stratification separates mature guidance architectures from emerging directed energy and space-based sensor programs requiring premium R&D allocation.
- Guided Systems:Inertial navigation fused with GPS and terminal seekers for precision engagement. Defense contractors in the southwestern United States are consolidating captive test infrastructure to compress development cycles under Pentagon speed-to-capability mandates.
- Interceptor Technology:Kill vehicles, booster stacks, and divert-and-attitude-control systems for endoatmospheric and exoatmospheric engagement. The Missile Defense Agency's renewed emphasis on hypersonic defense is rotating capital toward thermal protection and control system specialists concentrated at national laboratories.
- Missile Defense Radars:Active electronically scanned arrays for acquisition, tracking, and discrimination functions.
- Unmanned Aerial Vehicles:Loitering munitions and reconnaissance platforms with modular payload architectures.
Guided systems anchor current procurement volume. Interceptor technology is climbing the fastest as hypersonic threat proliferation accelerates kill-vehicle integration programs.
End User:
Volume concentration follows Department of Defense acquisition pathways, with homeland security and contractor segments capturing specialized subsystem demand.
- Military:Unified combatant commands operating integrated air and missile defense networks across continental and forward-deployed theaters. The Pentagon's Joint Requirements Oversight Council shapes funding priorities through capability-based assessments that favor primes with established test infrastructure.
- Defense Contractors:Prime and subcontractor ecosystems performing subsystem integration and test validation. ITAR compliance friction from the Department of State imposes multi-month licensing delays on Canadian subcontractor integration, compressing joint program margins across binational supply chains.
- Government:Civilian agency requirements for counter-drone and critical infrastructure protection.
- Homeland Security:Border surveillance and domestic counter-missile installations.
Military end users command the established base. Defense contractors are expanding most quickly as digital engineering mandates open procurement pathways for simulation and digital twin providers.
Deployment:
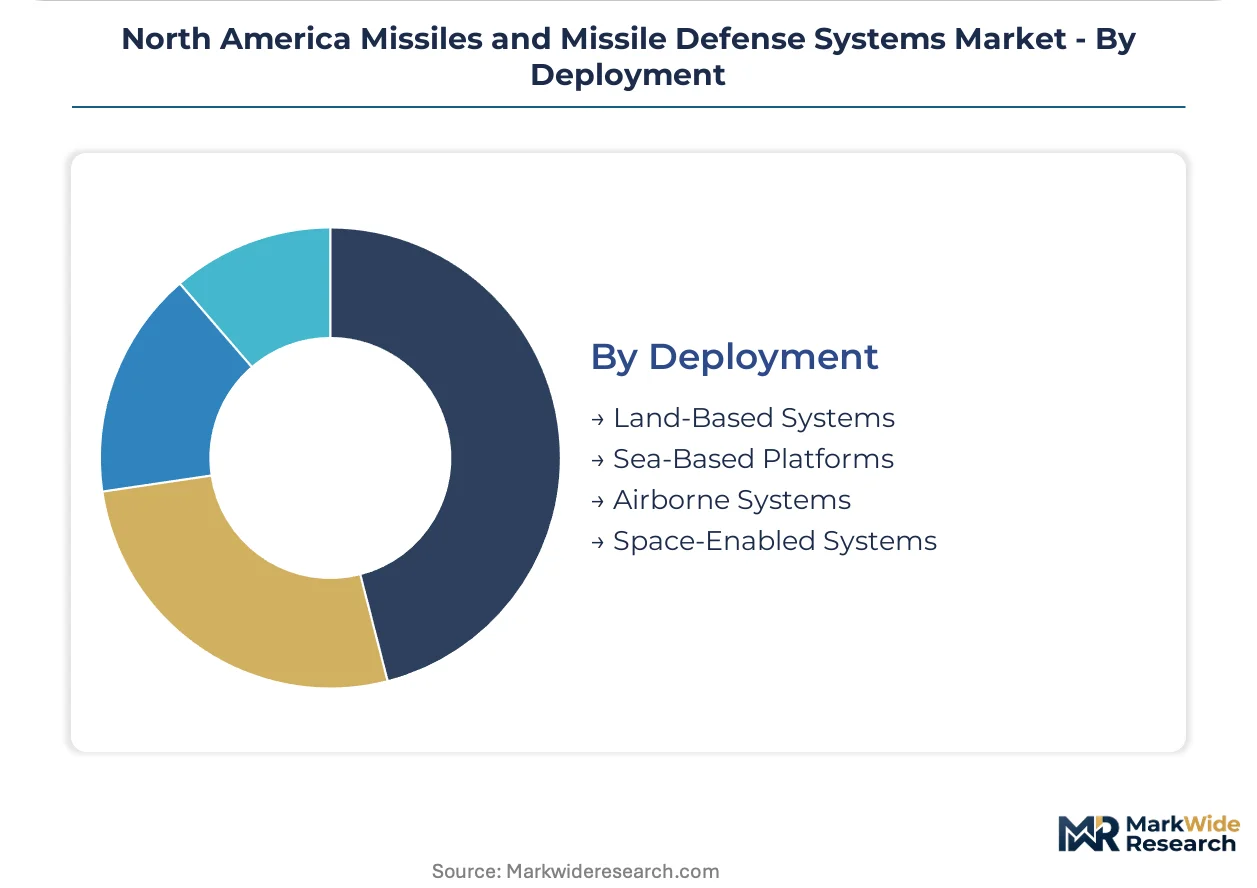
Maturity gradients separate decades-old land-based architectures from space-enabled systems attracting the fastest policy momentum through the Space Development Agency.
- Sea-Based Platforms:Aegis-equipped destroyer fleets with vertical launch system integration for regional ballistic missile defense. The Department of Defense's software acquisition pathway mandates continuous integration pipelines that the Aegis combat system's open architecture foundations accommodate faster than legacy alternatives.
- Space-Enabled Systems:Low-earth orbit constellations for hypersonic tracking and satellite-based intercept cueing. The Space Development Agency's dedicated funding for sensor layer proliferation is creating underpenetrated procurement channels for hardened space electronics.
- Land-Based Systems:Ground-based interceptors and terminal high-altitude area defense batteries.
- Airborne Systems:Directed energy and kinetic interceptors mounted on manned and unmanned aircraft.
Sea-based platforms command the established base. Space-enabled systems are gaining share fastest as hypersonic tracking requirements drive low-earth orbit constellation deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pentagon procurement commands premium pricing power against Canadian NORAD commitments, creating a bilateral asymmetry that shapes cross-border supplier economics and test infrastructure investment flows.
United States
Hypersonic interceptor acceleration and layered defense mandates drive procurement concentration in the southwestern test corridor. The Missile Defense Agency governs system-of-systems architecture validation protocols. Arizona and New Mexico facilities capture disproportionate program office attention through range availability and cleared workforce density.
Canada
Arctic infrastructure upgrades and northern warning system modernization expand addressable contract pools for hardened interceptors. The Department of National Defence coordinates binational procurement protocols under NORAD commitments. Nunavut and Northwest Territories installations concentrate over-the-horizon radar demand.
Mexico
Border surveillance requirements and domestic counter-missile installations generate specialized subsystem demand from homeland security agencies. The Secretariat of National Defense participates in regional threat assessment frameworks. Northern border states attract counter-drone and critical infrastructure protection investments.
North America Missiles and Missile Defense Systems Market Competitive Landscape
Concentration sits with vertically integrated primes possessing captive test infrastructure and long-running Pentagon relationships. The vendor base stratifies across three tiers: established system integrators with satellite campuses, radar and sensor specialists consolidated through airborne and space-based programs, and digital engineering providers capturing simulation procurement pathways. Competitive moves center on test infrastructure consolidation in the southwestern United States and strategic partnerships for binational supply chain qualification.
Among established system integrators, Lockheed Martin Corporation and RTX Corporation exemplify the prime-tier archetype through sustained interceptor production and radar layer anchoring respectively. Northrop Grumman Corporation occupies a position within the sensor and space-enabled systems specialization. These entities represent the consolidation pattern visible across Pentagon acquisition pathways, where speed-to-capability mandates compress traditional competitive prototyping phases toward vendors with demonstrated test range access and cleared workforce pipelines.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| General Dynamics Corporation |
| L3Harris Technologies |
| BAE Systems Inc. |
| Leidos |
| Kratos Defense & Security Solutions |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with southwestern test range operators lock in both supply access and price visibility for primes competing under Pentagon speed-to-capability mandates. These arrangements insulate qualified vendors from spot-market volatility in rare earth magnet procurement while compressing margins for subcontractors lacking cleared workforce pipelines.
Pricing Analysis
The customization-premium spread between configured-to-order kill-vehicle integration and standard radar component procurement runs wide across the Missile Defense Agency's layered architecture programs. Project-based contracting dominates prime-tier engagements, with price differentiation hinging on ITAR certification tier and captive test infrastructure access. Cost compression in interceptor subsystems is intensifying because Canadian subcontractor qualification delays extend non-recurring engineering timelines. Defense contractors represent the most price-sensitive segment, while primes with established range relationships command premium positioning.
Supply Chain Analysis
China and Malaysia anchor rare earth magnet processing for guidance system actuators, while domestic foundries in Texas and Arizona supply silicon carbide substrates for directed energy power electronics. The supply chain draws from neodymium-dysprosium concentrates, precision-machined titanium forgings, and radiation-hardened semiconductors. Single-source vulnerability in Chinese-processed rare earths exposes programs to export restriction volatility. Distribution runs through cleared prime contractor networks with direct Missile Defense Agency program office relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as NORAD modernization commitments and hypersonic threat proliferation drive sustained procurement acceleration across the analysis window.
For Market Incumbents: Fortify test infrastructure control through exclusive range partnerships in Arizona and New Mexico, locking out emerging competitors from qualification cycles. Deepen backward integration into rare earth magnet recycling to offset Chinese supply concentration risk. Priority investment in thermal protection system R&D addresses the specialized aerodynamics talent gap constraining workforce scaling. For New Entrants and Emerging Players: Anchor in Canadian Arctic infrastructure opportunities where NORAD's northern warning system upgrades create demand for hardened interceptors and over-the-horizon radar installations. Digital engineering and simulation services represent the most penetrable procurement channel under Department of Defense model-based systems engineering mandates. Go-to-market positioning as a cleared subcontractor with expedited ITAR licensing capabilities unlocks binational supply chain participation. For Investors and Strategic Acquirers: Mid-tier sensor fusion specialists with Space Development Agency relationships offer the strongest acquisition profile for capturing space-based sensor layer proliferation funding. Long-term viability rests on sustained bipartisan support for layered missile defense architectures against maneuverable re-entry vehicle threats. The signal to watch is Missile Defense Agency budget allocation shifts toward low-earth orbit constellation deployment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Test Infrastructure Consolidation | Exclusive range partnerships in Arizona and New Mexico compress competitor qualification timelines under Pentagon speed mandates. |
| Rare Earth Supply Agreement | Long-term offtake contracts with non-Chinese processors reduce export restriction exposure for guidance system actuators. |
| Digital Engineering Capability Buildout | Model-based systems engineering certification opens procurement pathways under Department of Defense software acquisition pathway mandates. |
| Arctic Infrastructure Partnership | NORAD northern warning system upgrades in Nunavut create demand for hardened interceptors and over-the-horizon radar. |
| Space Sensor Layer Integration | Low-earth orbit constellation participation captures Space Development Agency dedicated funding for hypersonic tracking architectures. |
Research Methodology
Initial hypotheses were tested against primary input from Missile Defense Agency program officers, prime contractor capture executives, Canadian Department of National Defence procurement leads, and southwestern test range operators, then refined through secondary validation. Bottom-up and top-down triangulation combined defense budget justification documents, Pentagon acquisition pathway disclosures, NORAD modernization white papers, and congressional appropriations committee records with trade flow data from customs filings and rare earth magnet import registries.
Variance decomposition across product type, technology tier, deployment platform, and end-user category shaped the analytical framework over the projection horizon. CAGRs emerged from segment-level demand modeling against Department of Defense Joint Requirements Oversight Council capability-based assessments and Space Development Agency funding trajectories. Hypersonic interceptor production ramp rates and Canadian subcontractor qualification timelines served as critical industry-specific forecast inputs.
Material uncertainties — ITAR licensing friction, rare earth export restriction volatility, and hypersonic aerodynamics workforce availability — sit outside the modeled envelope. Forecasts reflect assumptions about sustained bipartisan commitment to layered defense architectures and NORAD binational procurement protocol stability. Recalibration cycles align with material shifts in Pentagon acquisition priority rankings and Space Development Agency constellation deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Short Range Air Defense Systems Market
Air Defense
Americas Air Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Airborne Fire Control Radar Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Global Missile Interceptor Market
Air Defense
Asia-Pacific Air Defense Systems Market