
 Passenger Drones Market | 2026-2036
Passenger Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Drones Market Outlook
Germany is reconfiguring its aerospace manufacturing footprint around eVTOL final assembly and composite airframe production. Joby Aviation leverages extensive flight test data from its California operations to anchor certification discussions with the FAA. Volocopter GmbH sustains European market presence through its Stuttgart engineering hub and EASA design organization approval.
Passenger drones are electric vertical take-off and landing aircraft designed to carry one or more occupants over short to medium distances at speeds typically below 300 km/h, utilizing distributed electric propulsion and fly-by-wire control systems. Their primary purpose is to enable point-to-point aerial transport in congested urban environments without requiring traditional runway infrastructure. Multirotor configurations dominate early commercial deployments due to mechanical simplicity and redundancy, while hybrid architectures are capturing investment flows from operators seeking extended range for inter-city routes. Autonomous technology segments attract the deepest R&D allocation, though semi-autonomous systems retain near-term revenue primacy as regulators finalize piloted transition protocols.
The FAA, EASA, and China's CAAC each impose distinct airworthiness criteria that fragment certification timelines and force platform-specific design adaptations. These divergent standards compel manufacturers to maintain parallel regulatory teams, inflating compliance costs but also creating first-mover advantages for entities achieving dual FAA-EASA validation. Stakeholders must monitor which jurisdiction establishes the dominant certification precedent, as this will determine where production scales first and which operational models receive insurance market support.
Market Dynamics
Certification pathway divergence between FAA Part 23 reforms and EASA's SC-VTOL framework is fragmenting development timelines and forcing parallel engineering tracks across Atlantic manufacturing bases.
Growth Catalysts
- FAA Part 23 Powered-Lift Reforms:Streamlined type certification timelines compress regulatory approval cycles for eVTOL developers seeking US market entry. The framework eliminates procedural bottlenecks that previously stalled novel aircraft categories.
- Urban Air Mobility Infrastructure:Vertiport construction mandates in congested metropolitan corridors create dedicated takeoff and landing nodes. Municipal zoning adaptations in Germany and Singapore accelerate site approvals.
- Battery Energy Density Gains:Solid-state lithium-metal cell improvements extend operational range without airframe weight penalties. Cell manufacturers are tailoring formats for aviation duty cycles.
Market Restraints
- Lithium Supply Concentration:Cathode precursor refining clusters in single-source jurisdictions create input vulnerability. Diversification requires multi-year offtake negotiations.
- Dual Certification Cost Burden:Parallel FAA-EASA validation teams inflate compliance overhead. Engineering documentation must satisfy mutually non-recognizable technical standards.
- Helicopter Substitution Economics:Existing rotorcraft fleets serve emergency medical and executive transport at lower capital cost. eVTOL unit economics require volume production scale to achieve parity.
Strategic Opportunities
- Inter-City Route Networks:Hybrid-electric architectures unlock 200+ kilometer segments connecting secondary cities. Operators in Germany's Rhine-Ruhr corridor pilot scheduled services.
- Autonomous Flight Protocols:Sensor fusion and machine vision convergence enable single-pilot and pilotless operations. Regulators in UAE and Singapore issue experimental permits.
- Composite Airframe Localization:Carbon fiber layup and resin transfer molding capabilities shift to regional final assembly sites. Stuttgart and Munich engineering hubs capture design organization functions.
Industry Challenges
- Flight Control Software Verification:DO-178C compliance for fly-by-wire systems demands specialized aviation software engineers. Talent pools concentrate in legacy aerospace centers.
- Vertiport Grid Electrification:Megawatt-scale charging infrastructure requires distribution network upgrades. Utility coordination timelines extend deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Drones Market |
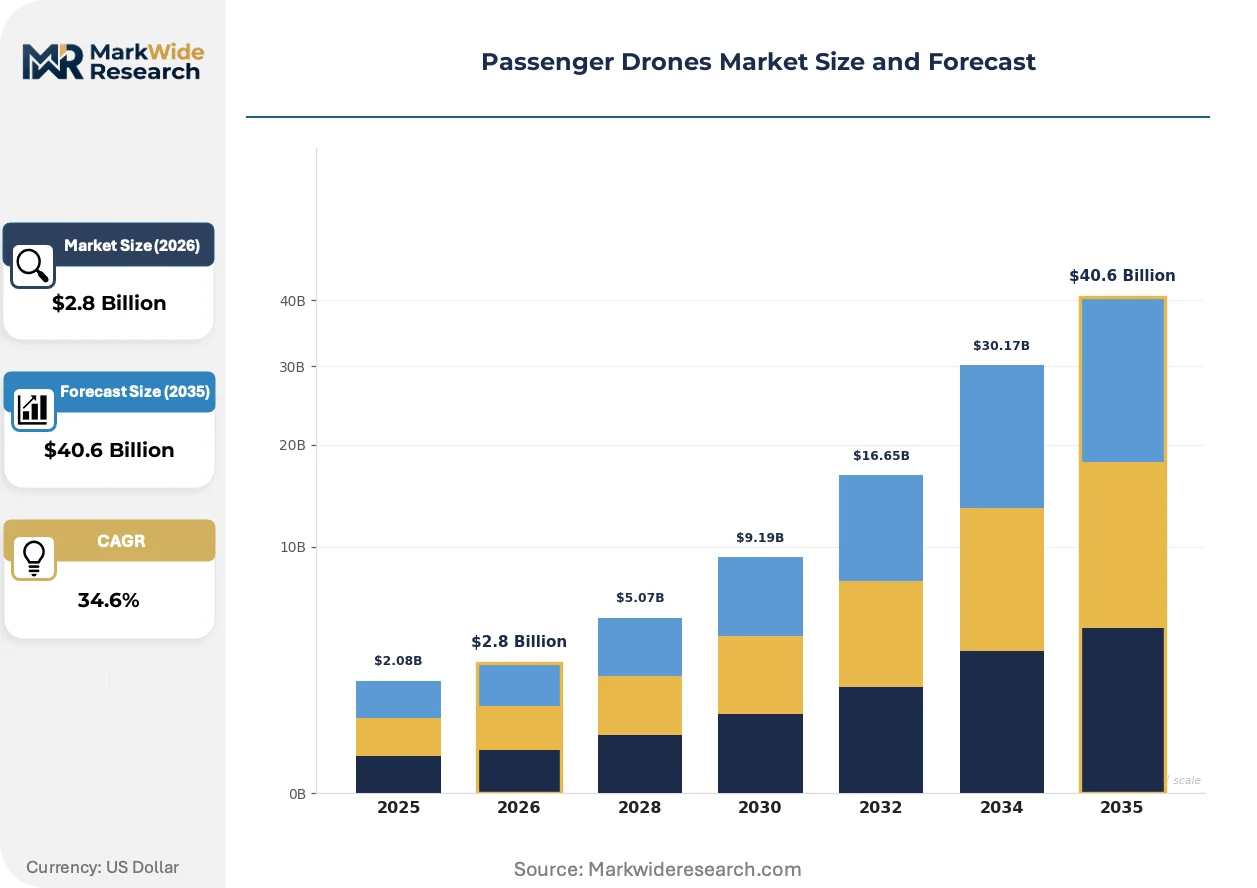
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $40.6 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor, Fixed-Wing, Hybrid, VTOL Technology: Autonomous, Semi-Autonomous, Remote-Controlled, Electric End User: Airlines, Private Owners, Logistics Companies, Government Agencies Application: Urban Air Mobility, Cargo Transport, Emergency Services, Tourism |
| Companies Covered | Joby Aviation, Archer Aviation, Volocopter GmbH, EHang, Airbus SE, Lilium, Wisk Aero, Boeing, Vertical Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Drones Market Strategic Shifts
Propulsion architecture decisions are locking in competitive positioning for the next decade as manufacturers commit to fixed technical roadmaps before certification baselines stabilize.
Distributed electric propulsion is hybridizing with turbine range extenders for inter-city configurations. Regional airline operators evaluating fleet renewal are prioritizing platforms with 300+ kilometer unrefueled reach. This convergence is compressing the distinction between urban air mobility and regional aviation segments.
EASA's SC-VTOL special condition framework is mandating fault-tolerant flight control architectures. Manufacturers must demonstrate continued safe flight after single-point failures without pilot intervention. The requirement is accelerating adoption of triple-redundant avionics in European-targeted designs.
Airline procurement departments are unbundling aircraft acquisition from ground infrastructure and pilot training packages. Fleet planners negotiate separate contracts with vertiport developers and simulator providers. This disaggregation is most visible in Germany where Lufthansa Group structures multi-vendor operational ecosystems.
Passenger Drones Market Segmentation
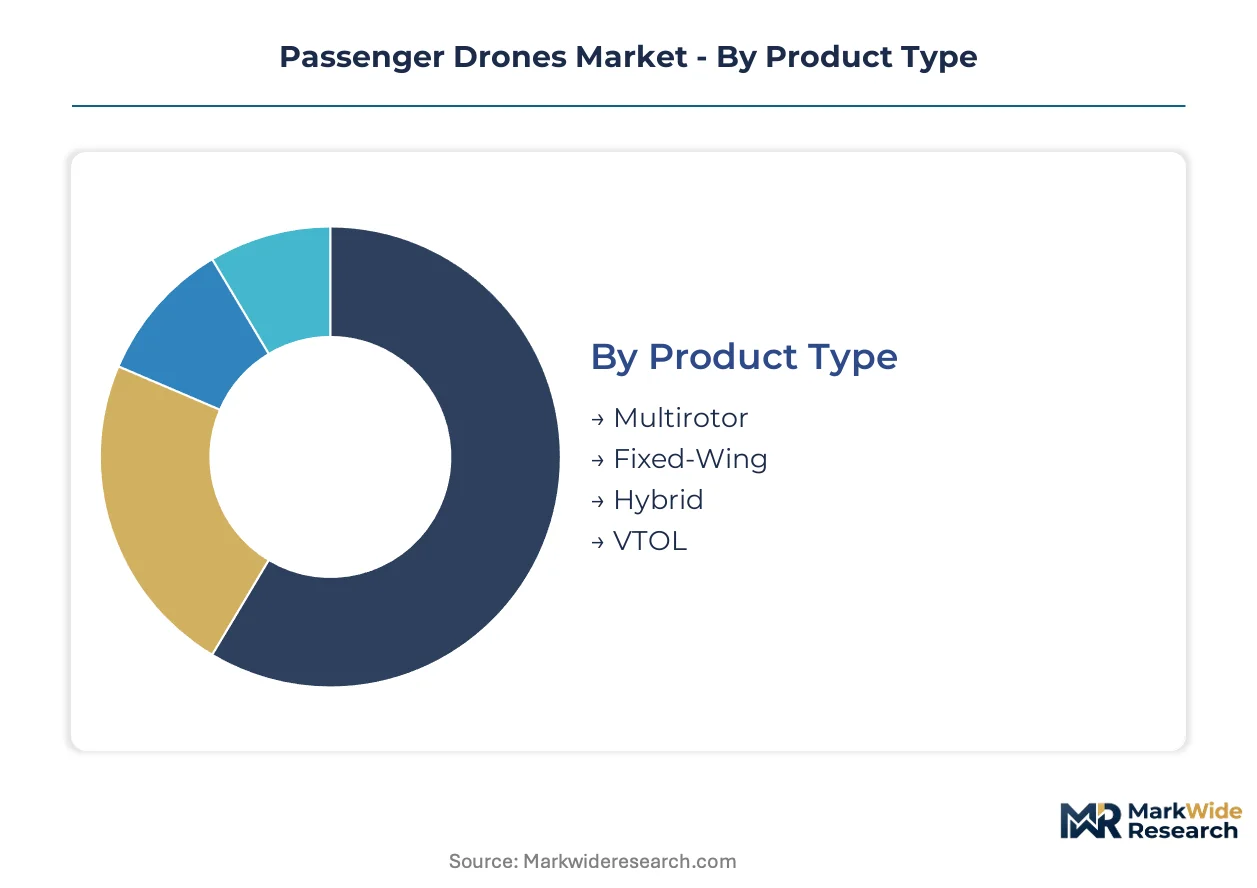
Segmentation in passenger drones reveals how propulsion architecture, autonomy levels, and operational missions fragment manufacturing priorities and certification pathways. Each dimension creates distinct engineering requirements and regulatory submission strategies that shape vendor specialization.
Product Type:
Propulsion configuration determines range envelope, certification complexity, and infrastructure compatibility for platform developers and operators.
- Multirotor:Distributed electric propulsion with eight to eighteen rotors enables vertical lift without runway dependency. Stuttgart and Shenzhen manufacturing clusters concentrate early commercial volume for intra-city shuttles where range requirements stay below fifty kilometers and noise restrictions dominate site selection.
- Fixed-Wing:Conventional aerodynamic surfaces prioritize energy efficiency for extended transit corridors. Logistics operators evaluating inter-city cargo routes favor this architecture where vertiport spacing permits glide-path approaches and battery swap logistics align with hub-and-spoke distribution models.
- Hybrid:Turbine-electric combinations extend operational radius beyond pure battery limitations. Regional airline procurement departments assess these platforms for 200-plus kilometer segments connecting secondary cities.
- VTOL:Tilt-rotor or ducted-fan mechanisms vector thrust for vertical ascent and efficient cruise. Military and emergency medical operators specify these configurations for terrain-agnostic deployment.
Multirotor holds installed capacity. Hybrid is rotating up the share rankings.
Technology:
Autonomy tier determines crewing requirements, insurance pricing, and regulatory submission scope for operational approval.
- Autonomous:Sensor fusion and machine vision systems enable pilotless navigation through controlled airspace. UAE and Singapore regulators issue experimental permits for designated corridors where ground-based detect-and-avoid infrastructure supplements onboard systems.
- Semi-Autonomous:Single-pilot oversight with automated flight control retains human intervention capability. EASA SC-VTOL mandates for fault-tolerant architectures concentrate European development investment here.
- Remote-Controlled:Ground-based piloting via telemetry links suits cargo applications and restricted test environments. Logistics operators pilot freight routes in Germany's Rhine-Ruhr corridor using this modality.
- Electric:Battery-only propulsion dominates urban air mobility specifications where charging infrastructure and noise profiles constrain operational design. Solid-state cell improvements are expanding mission endurance without airframe weight penalties.
Semi-Autonomous commands current revenue. Autonomous is climbing the fastest.
End User:
Customer category shapes procurement scale, financing structures, and operational risk tolerance across deployment scenarios.
- Airlines:Scheduled service operators unbundle aircraft acquisition from ground infrastructure and pilot training. Lufthansa Group structures multi-vendor ecosystems in Germany where fleet planners negotiate separate contracts with vertiport developers.
- Private Owners:Individual acquisition for executive transport concentrates in high-net-worth segments where capital cost tolerance exceeds commercial operator thresholds.
- Logistics Companies:E-commerce and parcel carriers evaluate payload-specific configurations for hub bypass and last-mile aerial delivery. DHL and UPS pilot programs inform airworthiness requirements for automated cargo loading systems.
- Government Agencies:Defense, emergency medical, and law enforcement procurement drives specifications for ruggedized systems and secure communications. Coast guard and search-and-rescue operators mandate extended hover endurance and all-weather operational envelopes.
Airlines anchor committed order volume. Logistics Companies are expanding most quickly.
Application:
Mission profile determines payload requirements, route structures, and regulatory oversight intensity for platform specification.
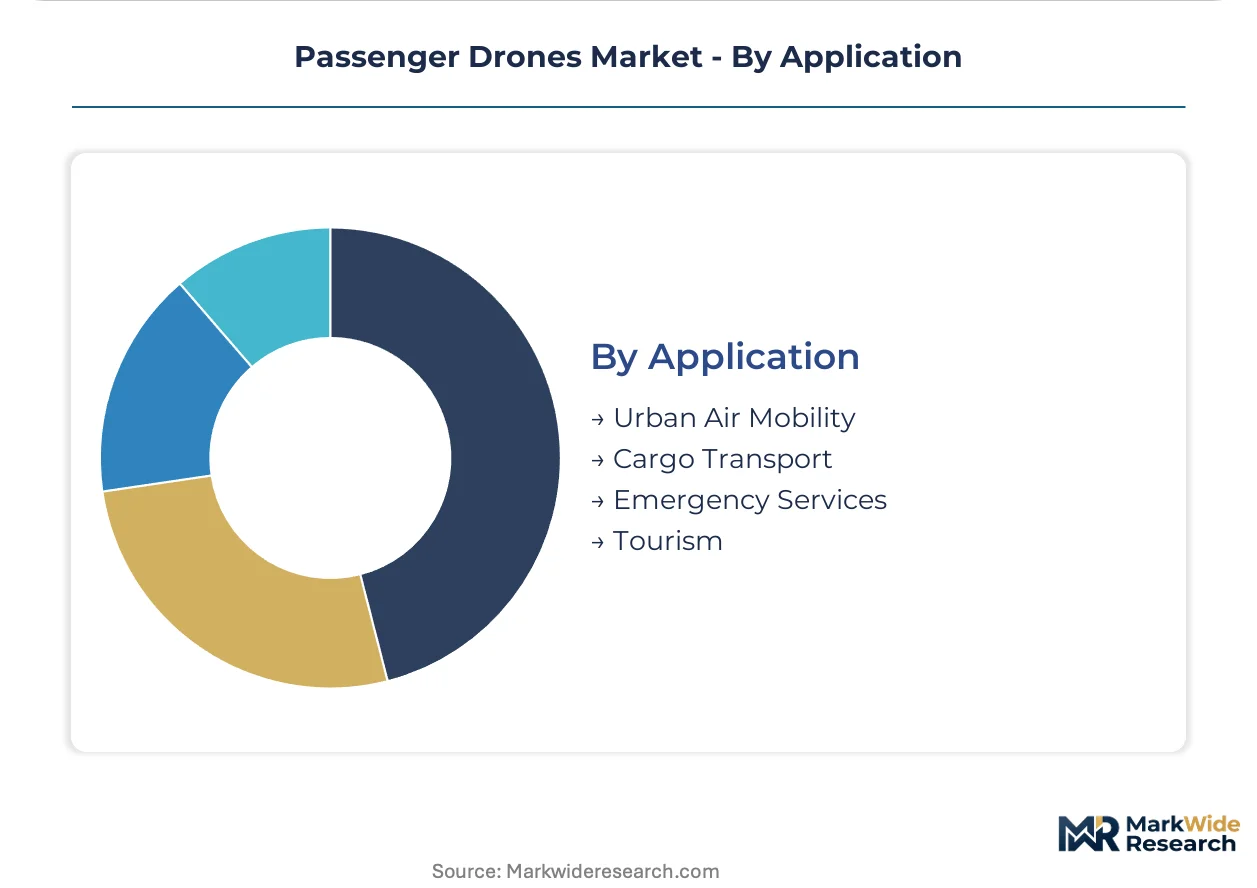
- Urban Air Mobility:Point-to-point passenger transit in congested metropolitan corridors drives multirotor adoption. Singapore and Munich municipal zoning adaptations accelerate vertiport site approvals for scheduled shuttle services.
- Cargo Transport:Unmanned freight operations prioritize payload density and automated ground handling. Inter-city route networks in Germany's industrial belt pilot scheduled services connecting distribution centers.
- Emergency Services:Medical evacuation and disaster response require rapid deployment and terrain-independent landing. Helicopter substitution economics here favor eVTOL where capital cost amortization aligns with public procurement budgets.
- Tourism:Aerial sightseeing and experience flights emphasize cabin visibility and acoustic comfort. Dubai and Grand Canyon operators specify low-noise profiles for scenic corridor access.
Urban Air Mobility holds committed fleet orders. Cargo Transport is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Final assembly and composite airframe manufacturing concentrate in Germany and the United States, where eVTOL developers anchor engineering teams near legacy aerospace talent pools and regulatory pre-certification pathways.
United States
FAA Part 23 powered-lift reforms compress type certification timelines for eVTOL developers seeking commercial airworthiness approval. California flight test centers generate operational data that anchors certification discussions with federal regulators. Joby Aviation leverages extensive California test operations to validate aircraft performance envelopes.
Germany
Stuttgart and Munich engineering hubs sustain European market presence through EASA design organization approvals and composite manufacturing capabilities. The country's national aviation regulator mandates fault-tolerant flight control architectures under SC-VTOL special conditions. Volocopter GmbH anchors final assembly operations at its Stuttgart facility with regulatory pre-certification pathways.
China
CAAC airworthiness criteria for powered-lift aircraft establish distinct certification timelines that fragment development tracks from Western regulatory frameworks. Shenzhen manufacturing clusters concentrate early commercial volume for multirotor configurations serving intra-city shuttle markets. EHang occupies a position within the autonomous flight tier of domestic developers.
Singapore
Municipal zoning adaptations accelerate vertiport site approvals for scheduled urban air mobility services in congested metropolitan corridors. The country's civil aviation authority issues experimental permits for pilotless operations in designated airspace corridors. Sensor fusion and machine vision convergence enables single-pilot and pilotless operational trials.
United Arab Emirates
Dubai tourism operators specify low-noise eVTOL profiles for scenic corridor access and aerial sightseeing experiences. The country's aviation regulator permits experimental autonomous flight protocols in controlled airspace environments. Vertiport construction mandates create dedicated takeoff and landing nodes for commercial service deployment.
Passenger Drones Market Competitive Environment
Vertically integrated airframers and specialist propulsion developers split the market between certification-heavy platform builders and subsystem component suppliers. The vendor base organizes around three strategic archetypes: full-stack aircraft developers pursuing type certification, Tier-1 subsystem specialists supplying distributed electric propulsion, and vertiport infrastructure operators bundling ground services. Dominant competitive moves include strategic partnerships between airframers and battery cell manufacturers, plus geographic expansion through regulatory dual-validation strategies.
Within the full-stack developer tier, Joby Aviation and Volocopter GmbH exemplify the certification-first approach, while Archer Aviation occupies a position among tilt-rotor specialists targeting regional airline procurement channels. These entities anchor distinct technical roadmaps—distributed multirotor versus vectored thrust—that lock in competitive positioning before certification baselines stabilize across FAA and EASA jurisdictions.
| Leading Market Players |
|---|
| Joby Aviation |
| Archer Aviation |
| Volocopter GmbH |
| EHang |
| Airbus SE |
| Lilium |
| Wisk Aero |
| Boeing |
| Vertical Aerospace |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's composite airframe manufacturing cluster anchors European eVTOL production capacity, concentrating supply-side leverage among German Tier-1 suppliers who command premium pricing for certified components. This geographic concentration feeds downstream cost structures, where battery cell qualification and airframe certification expenses dominate platform economics.
Pricing Analysis
FAA Part 23 powered-lift reforms dictate the pricing tier structure across certification-grade segments, separating experimental permit holders from type-certified platforms. Three-tier pricing structure across premium certified, pre-certified, and experimental levels reflects airworthiness validation investment and insurance market access. Cost compression in the experimental tier is intensifying because Chinese manufacturers flood intra-city shuttle markets with uncertified multirotor units. Logistics operators demonstrate highest price sensitivity, while emergency medical procurement tolerates premium positioning for terrain-agnostic VTOL configurations.
Supply Chain Analysis
Lithium carbonate feedstock from Chile, Australia, and China feeds cathode precursor refining clusters that anchor battery cost structures. Solid-state cell development draws from specialized electrolyte chemistry and ceramic separator manufacturing concentrated in Japan and South Korea. Single-source vulnerability in rare earth permanent magnet supply creates input risk for distributed electric propulsion motors. Distribution runs through airframer-direct contracts with vertiport operators and regional airline fleet planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passenger drones represent high-growth aviation disruption where FAA-EASA regulatory convergence and solid-state battery maturation constitute simultaneous inflection points. Stakeholder positioning must account for certification timeline compression and propulsion architecture lock-in effects.
For Market Incumbents: Harden certification-first positioning by accelerating dual FAA-EASA validation timelines before regulatory baselines stabilize. Vertical integration into battery cell qualification and composite layup capabilities defends margin position against Chinese cost-led entrants. Anchor production scale in Stuttgart or California engineering hubs where regulatory pre-certification pathways concentrate talent access. For New Entrants and Emerging Players: Build out cargo transport specialization where pilotless operational permits in Singapore and UAE create faster regulatory pathways than passenger certification. Target autonomous flight tier development for logistics operators in Germany's Rhine-Ruhr corridor, where DHL and UPS pilot programs establish demand validation. Pursue vertiport infrastructure partnerships as primary go-to-market anchor rather than airframe-only sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-stack developers with EASA design organization approval and existing flight test data archives. Long-term viability hinges on which entities achieve dual-jurisdiction certification before hybrid-electric architecture roadmaps lock in competitive positioning. Monitor EASA SC-VTOL special condition adoption velocity as the signal indicating which technical standards will dominate European operational approval.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel FAA-EASA validation teams compress time-to-revenue for type-approved platforms. |
| Battery Supply Agreement | Long-term offtake contracts with solid-state cell manufacturers secure aviation-grade energy density. |
| Vertiport Infrastructure Partnership | Municipal zoning adaptations in Munich and Singapore accelerate dedicated takeoff node deployment. |
| Autonomous Flight Permit Pursuit | Experimental operational approvals in UAE and Singapore enable pilotless revenue generation ahead of passenger certification. |
| Composite Manufacturing Scale-Up | Carbon fiber layup capabilities in Stuttgart capture design organization functions for European market access. |
Study Parameters
Initial hypotheses were tested against primary input from eVTOL program managers, EASA certification leads, vertiport development officers, and airline fleet planners and refined through secondary validation against FAA type certification filings, EASA SC-VTOL special condition documentation, battery manufacturer technical datasheets, and municipal zoning adaptation records. Bottom-up platform deployment modeling triangulated with top-down urban air mobility demand projections across the analysis window.
Demand-supply-balance framing anchored the quantitative framework, with segmentation across propulsion architecture, autonomy tier, end-user category, and application mission profile modeled throughout the forecast period. CAGRs were derived from installed base growth trajectories and replacement cycle assumptions, incorporating battery energy density improvement curves and regulatory approval timeline distributions as industry-specific forecast inputs.
Stress conditions across lithium supply concentration, certification timeline divergence, and vertiport electrification rollout speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory convergence and solid-state battery commercialization. Cross-checking against FAA type certification backlog data and EASA design organization approval velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
UAV Battery Market
UAV
Auto-Follow Drone Market
UAV
Enterprise Drone Management Solutions Market
UAV
Latin America Small UAV Market
UAV
Commercial UAV Market
UAV
Military UAV Sensor Market
UAV
Global Renewable Drones Market
UAV
Solar Powered Drones Market
UAV
Racing Drone Market
UAV
Global Target Drone Market
UAV
Drone Leasing Market
UAV
Tethered Drones Market
UAV
Aerial Smart Weapons Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Electric Unmanned Aerial Vehicle Market