
 Europe Tactical UAV Market | 2026-2036
Europe Tactical UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tactical UAV Market Foresight
A shortage of certified unmanned systems engineers is reorganizing production timelines across European defense supply chains. Leonardo S.p.A. leverages its vertically integrated rotorcraft heritage to dominate naval VTOL deployments. Thales Group anchors its position through captive command-and-control software stacks that reduce third-party dependency. Safran SA competes on propulsion miniaturization, sustaining advantage in endurance-critical rotary-wing segments.
Tactical UAVs denote military-grade uncrewed aircraft with maximum takeoff weights below 600 kilograms, operating at ranges up to 300 kilometers with modular sensor payloads for real-time intelligence dissemination. Fixed-wing configurations lead in maritime patrol and long-endurance reconnaissance due to superior fuel efficiency, while hybrid platforms represent the fastest-expanding category as operators demand runway-independent vertical launch combined with fixed-wing cruise efficiency. Rotary-wing systems retain entrenched demand in urban close-quarters operations where hover stability determines mission success.
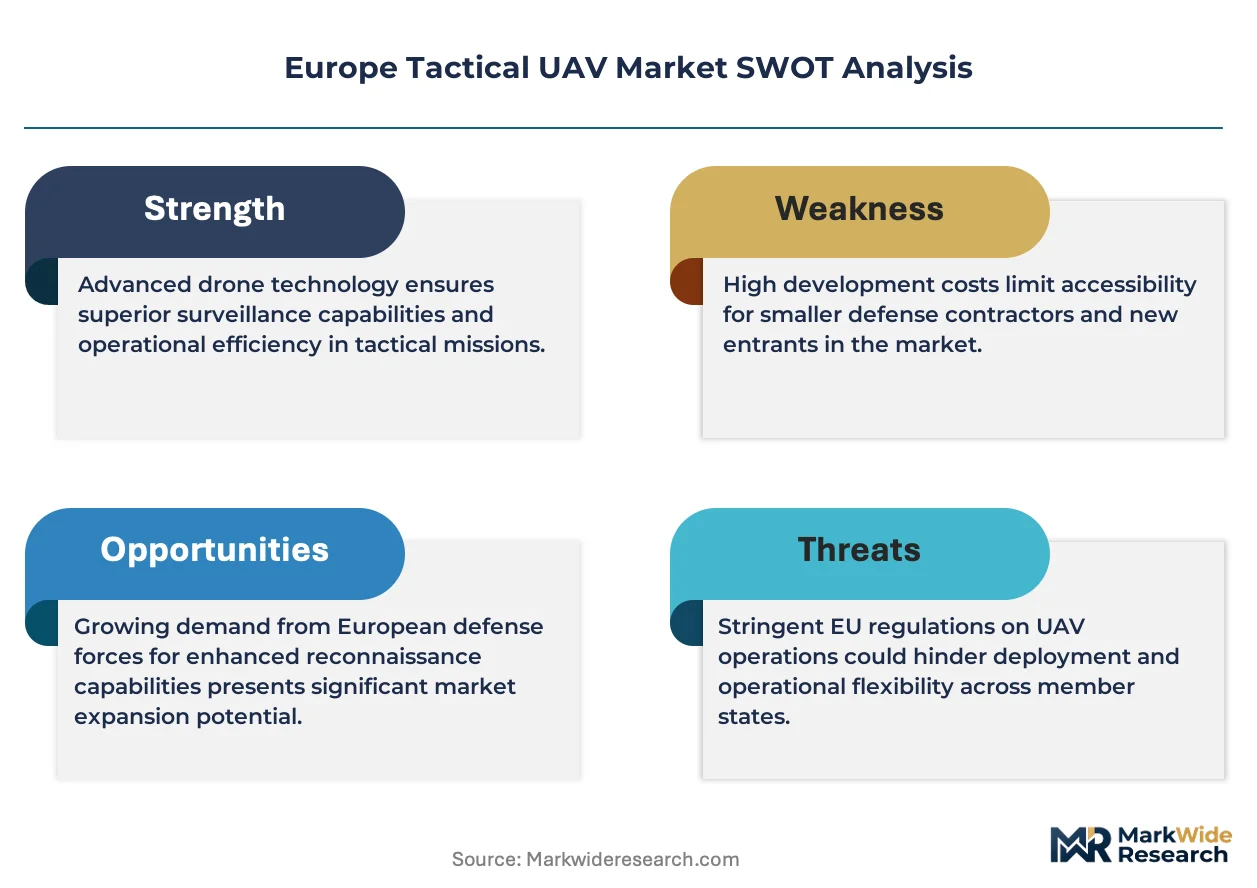
CE marking under the EU Drone Regulation, EASA airworthiness standards for military-type certification, and national military aviation authorities in France, Germany, and Italy collectively shape product development roadmaps and cross-border sales eligibility. The EU AI Act introduces emerging compliance obligations for autonomous targeting and decision-support algorithms that will reshape R&D investment allocation. Stakeholders must monitor how EASA adapts civilian certification frameworks to accommodate accelerated military fielding requirements without compromising safety benchmarks.
Market Dynamics
Border patrol agencies across Eastern Europe are accelerating surveillance platform procurement while the EU Green Deal compresses development timelines for lighter composite airframes and reduced-emission propulsion systems.
Growth Catalysts
- NATO Forward Deployment:Poland's fleet modernization commitments under NATO's eastern flank posture are pulling fixed-wing and hybrid VTOL systems into active service faster than replacement cycles.
- EU Green Deal Mandates:Emission reduction targets for defense procurement are forcing propulsion miniaturization investments that simultaneously improve endurance metrics for rotary-wing segments.
- Composite Airframe Advances:Lighter carbon-fiber manufacturing processes are extending operational ranges without violating the 600-kilogram MTOW ceiling that defines tactical classification.
Market Restraints
- Certified Engineer Scarcity:European defense supply chains face production timeline compression due to insufficient unmanned systems engineers holding EASA military-type certification.
- Sensor Payload Cost Volatility:Electro-optical/infrared gimbal assemblies depend on germanium and indium supply concentration in non-European refining operations.
- CE Marking Friction:Divergent national military aviation authority requirements in France, Germany, and Italy create redundant compliance pathways for cross-border sales eligibility.
Strategic Opportunities
- Romanian Border Infrastructure:Danube Delta and Black Sea coastline surveillance gaps present runway-independent deployment opportunities for hybrid platforms.
- EU AI Act Autonomy Pathways:Emerging compliance frameworks for autonomous targeting algorithms will reward first-movers with captive command-and-control software stacks.
- Maritime Patrol Convergence:Integration of synthetic aperture radar with automatic identification system correlation creates new payload configurations for Baltic and Mediterranean operators.
Industry Challenges
- EASA Adaptation Timeline:Civilian certification frameworks require restructuring to accommodate accelerated military fielding without degrading safety benchmarks, compressing R&D allocation decisions.
- Legacy System Integration:NATO interoperability standards demand backward-compatible datalinks that constrain bandwidth for real-time intelligence dissemination from newer modular payloads.
- Software Stack Fragmentation:Proprietary command-and-control architectures from dominant vendors create vendor lock-in that complicates multi-national fleet standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tactical UAV Market |
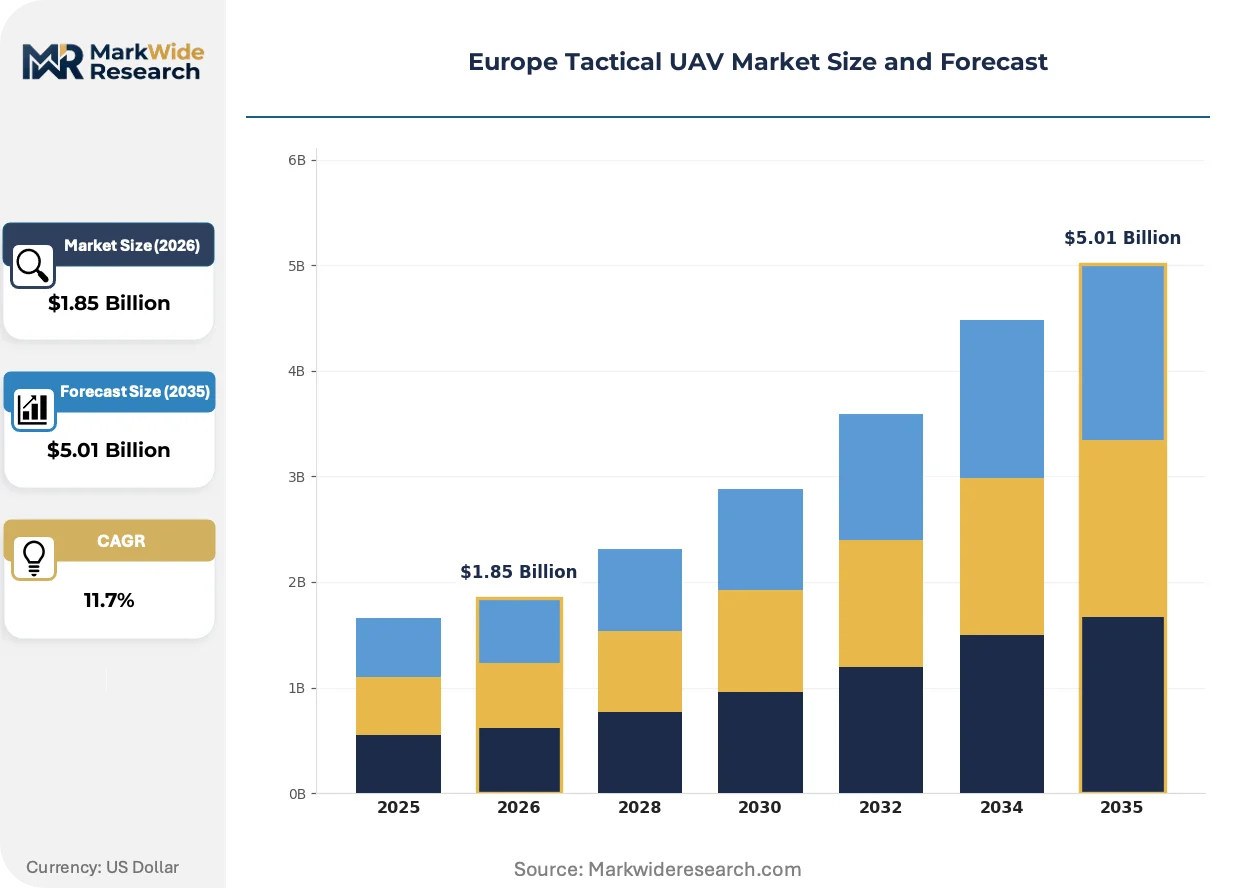
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano End User: Military, Law Enforcement, Security Agencies, Civil Defense Application: Surveillance, Reconnaissance, Combat, Search & Rescue Technology: Electro-Optical, Infrared, GPS, Communication Systems |
| Companies Covered | Leonardo S.p.A., Thales Group, Safran SA, Airbus SE, BAE Systems plc, Rheinmetall AG, Saab AB, UMS Skeldar AG, Quantum-Systems GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tactical UAV Market Shifts & Advancements
Propulsion miniaturization and autonomous algorithm development are restructuring competitive advantage around software-defined mission flexibility rather than airframe heritage alone.
Hybrid-electric propulsion architectures are decomposing the traditional trade-off between vertical launch capability and cruise efficiency. Naval operators in the Baltic and Mediterranean are adopting these platforms for shipboard deployment where runway independence determines mission feasibility. The technology is decomposing procurement categories that previously separated rotary-wing and fixed-wing acquisition budgets into unified platform decisions.
The EU AI Act introduces emerging compliance obligations for autonomous targeting and decision-support algorithms that will reshape R&D investment allocation. Industrial consequence includes mandatory algorithmic transparency requirements that increase documentation burdens but reduce liability exposure for defense contractors. Autonomous navigation segments operating beyond visual line of sight face the most stringent adaptation timelines as EASA develops military-type certification pathways.
Defense procurement authorities are consolidating vendor relationships around full-mission-system providers rather than airframe-only suppliers. Traditional distribution through national integrators is yielding to direct OEM relationships for command-and-control software and sensor payload packages. This concentration is most visible in Poland and the Baltic states where NATO interoperability requirements favor standardized fleet architectures over national customization.
Europe Tactical UAV Market Segmentation
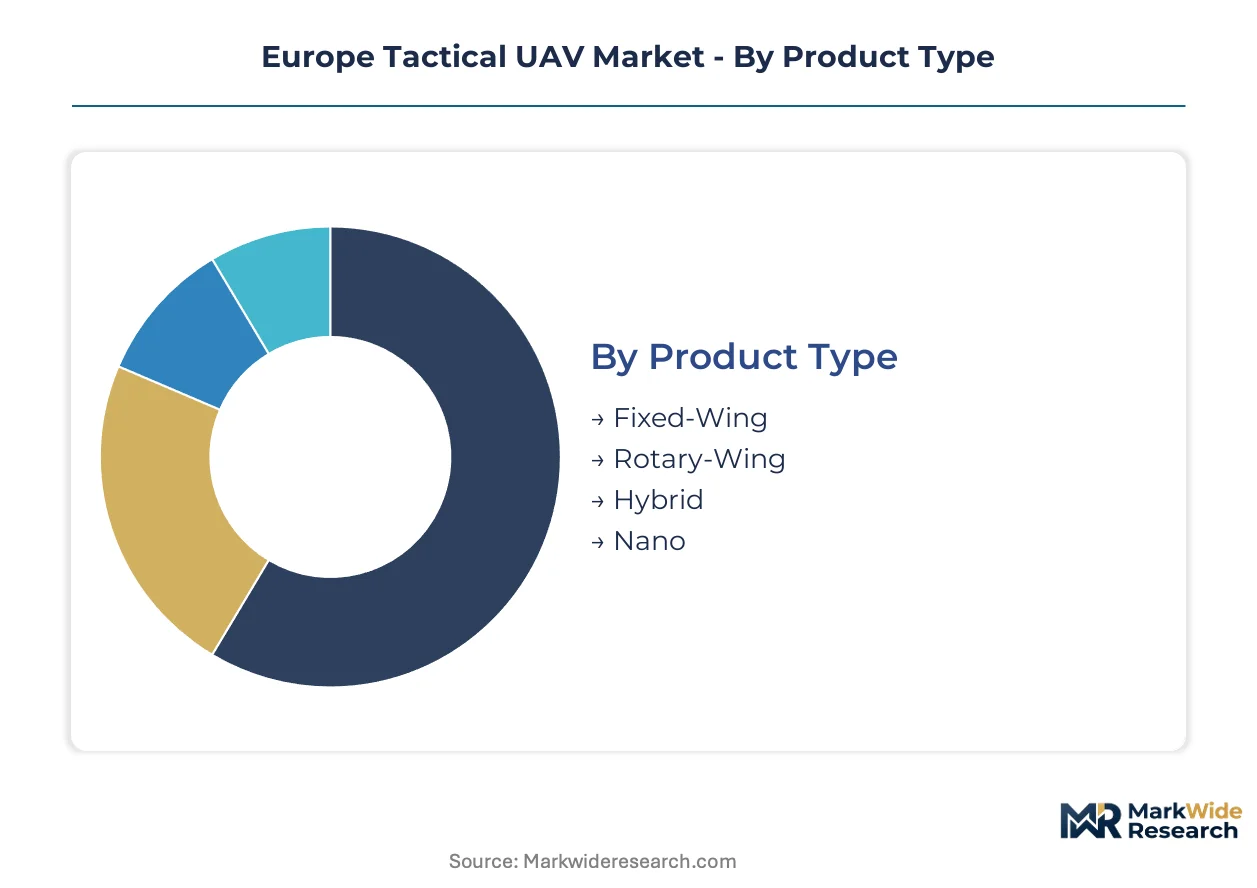
Tactical UAV procurement across Europe fragments across mission requirements, certification thresholds, and operational environments. Understanding how these dimensions intersect with EASA military-type certification pathways enables suppliers to align R&D investment with addressable demand pools.
Product Type:
EASA airworthiness standards apply differential certification burdens based on maximum takeoff weight and propulsion architecture, creating compliance cost tiers that reshape competitive positioning.
- Fixed-Wing:These systems exploit superior fuel efficiency to extend operational range within the 600-kilogram MTOW ceiling. Maritime patrol agencies in Poland and the Baltic states concentrate procurement here for long-endurance reconnaissance missions over coastal waters.
- Rotary-Wing:Hover stability determines mission success in urban close-quarters operations. Law enforcement end-users in France and Germany favor these platforms for crowd monitoring and tactical response scenarios where runway independence is mandatory.
- Hybrid:Vertical launch capability combined with fixed-wing cruise efficiency is expanding fastest among naval operators. Shipboard deployment in the Mediterranean and Black Sea drives adoption where deck space constraints prohibit conventional runway operations.
- Nano:Sub-250-gram platforms face reduced regulatory scrutiny under EU Drone Regulation thresholds. Special forces units leverage these for covert reconnaissance in contested airspace where radar signature minimization outweighs payload limitations.
Fixed-Wing handles the majority of throughput; Hybrid is the fastest mover on share.
End User:
Procurement authority and budget cycles vary sharply across institutional categories, with NATO interoperability requirements imposing standardization pressures on some segments while national sovereignty concerns preserve fragmentation in others.
- Military:Defense ministries command the largest procurement volumes and longest replacement cycles. Forward-deployment commitments in Poland are pulling fixed-wing and hybrid VTOL systems into active service faster than traditional modernization timelines.
- Law Enforcement:National police forces operate under stricter operational rules of engagement than military counterparts. German Landespolizei and French Gendarmerie Nationale drive demand for rotary-wing platforms with reduced kinetic payload integration.
- Security Agencies:Border patrol organizations across Eastern Europe are accelerating surveillance platform procurement. Romanian authorities present specific opportunities for Danube Delta and Black Sea coastline coverage using runway-independent systems.
- Civil Defense:Fire services and emergency response coordinators prioritize search and rescue configurations. Alpine regions in Switzerland and Austria concentrate demand for high-altitude operational capability with adverse weather tolerance.
Military absorbs the dominant procurement volume; Security Agencies are expanding most quickly as border infrastructure investment accelerates.
Application:
Mission type dictates sensor payload integration priorities and datalink bandwidth requirements, with NATO interoperability standards constraining backward-compatible architecture choices.
- Surveillance:Continuous area monitoring demands electro-optical/infrared gimbal stability and extended endurance. Baltic maritime operators integrate synthetic aperture radar with automatic identification system correlation for coastal patrol.
- Reconnaissance:Time-sensitive targeting requires rapid deployment and real-time intelligence dissemination. Polish military procurement emphasizes this application for NATO eastern flank posture requirements.
- Combat:Kinetic payload delivery faces the most stringent EU AI Act scrutiny for autonomous targeting algorithms. Development timelines stretch as EASA formulates military-type certification pathways for beyond-visual-line-of-sight engagement.
- Search & Rescue:Thermal signature detection and communication relay dominate payload specifications. Alpine civil defense authorities in Austria and Switzerland prioritize adverse weather operational envelopes.
Surveillance commands the installed base; Reconnaissance is climbing the fastest as NATO forward-deployment accelerates fleet modernization.
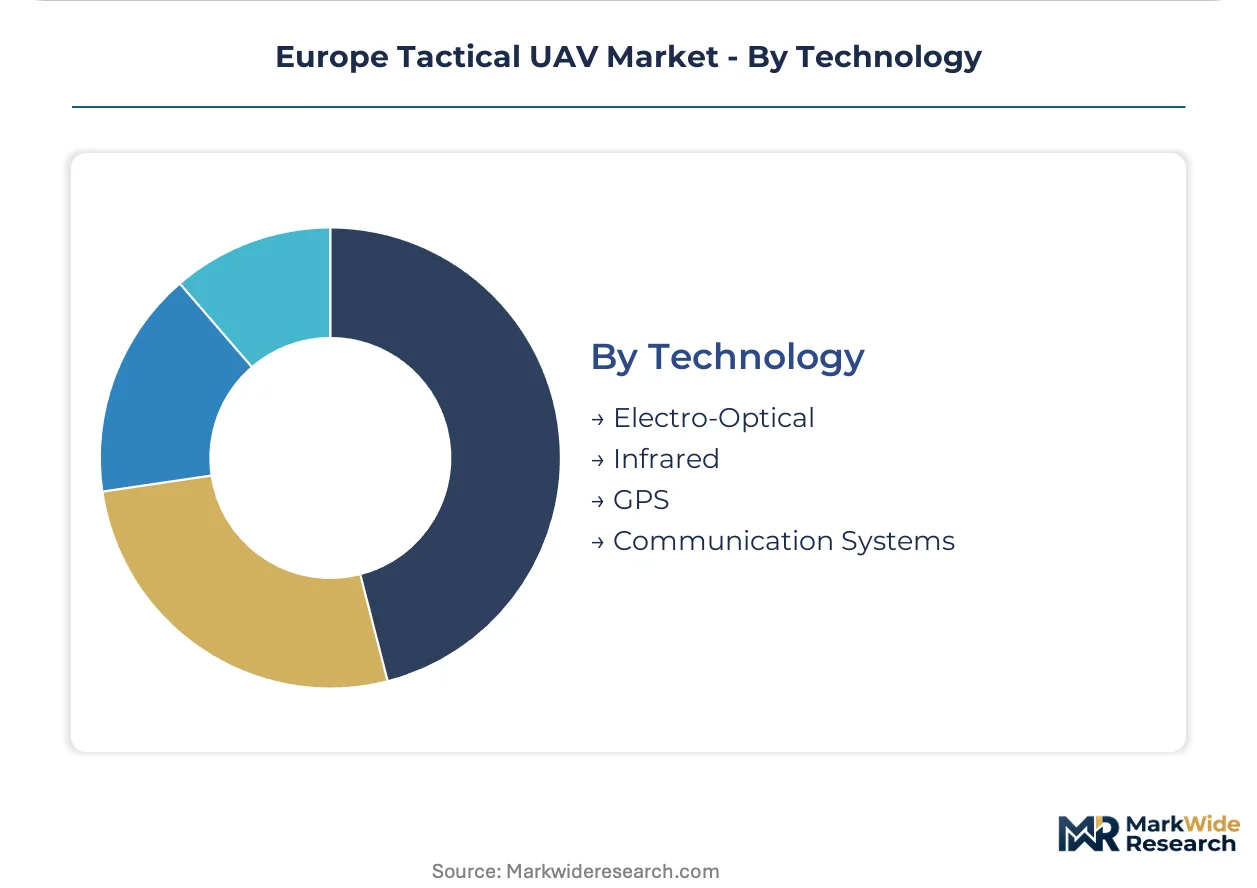
Technology:
Supply concentration in non-European refining operations for critical sensor materials creates cost volatility that propagates through electro-optical and infrared subsystem pricing.
- Electro-Optical:Daylight imaging systems depend on germanium lens supply chains concentrated outside European refining capacity. Maritime surveillance platforms prioritize these payloads for vessel identification at extended ranges.
- Infrared:Thermal detection capability requires indium antimonide or mercury cadmium telluride focal plane arrays. Border patrol applications in Eastern Europe drive demand for all-weather detection independent of illumination conditions.
- GPS:Navigation resilience against jamming determines military specification tiers. NATO interoperability standards mandate encrypted military signal reception for operational deployment in contested electromagnetic environments.
- Communication Systems:Datalink bandwidth constraints from legacy NATO standards limit real-time intelligence throughput. Proprietary command-and-control architectures from dominant vendors create integration challenges for multi-national fleet standardization.
Electro-Optical represents the largest installed technology base; Communication Systems are gaining share fastest as software-defined mission flexibility restructures competitive advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA airworthiness standards anchor procurement frameworks across European defense ministries, with national military aviation authorities in France, Germany, and Italy layering additional compliance requirements that reshape cross-border sales eligibility.
Poland
NATO forward-deployment commitments pull fixed-wing and hybrid VTOL systems into active service faster than traditional replacement cycles. The Polish Ministry of Defence accelerates fleet modernization under eastern flank posture requirements. Warsaw defense clusters concentrate procurement authority for surveillance platforms addressing Baltic maritime patrol gaps.
Germany
Bundeswehr procurement prioritizes rotary-wing platforms for urban close-quarters operations where hover stability determines mission success. The KBA coordinates with EASA on military-type certification pathways for autonomous navigation segments. Bavarian aerospace clusters around Munich drive propulsion miniaturization investments that improve endurance metrics.
France
The ANSM and national military aviation authority impose stringent operational rules of engagement on law enforcement UAV deployments. French Gendarmerie Nationale drives demand for rotary-wing systems with reduced kinetic payload integration. Toulouse aerospace corridors anchor command-and-control software development for captive stack architectures.
Romania
Border patrol agencies accelerate surveillance platform procurement for Danube Delta and Black Sea coastline coverage. Runway-independent deployment opportunities favor hybrid platforms where deck space constraints prohibit conventional operations. Bucharest defense procurement offices consolidate vendor relationships around full-mission-system providers.
United Kingdom
BAE Systems plc anchors domestic supply chains for NATO interoperability standards demanding backward-compatible datalinks. UK Ministry of Defence procurement emphasizes reconnaissance applications for time-sensitive targeting missions. Southwest England defense clusters concentrate synthetic aperture radar integration with automatic identification system correlation.
Europe Tactical UAV Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated command-and-control software stacks displacing fragmented national integrator relationships. Defense procurement authorities now favor full-mission-system providers over airframe-only suppliers. Three archetypes dominate: vertically integrated rotorcraft heritage players, propulsion miniaturization specialists, and captive software stack developers. Competitive moves concentrate on strategic partnerships for sensor payload integration and geographic expansion into Baltic and Black Sea markets.
Within the integrated leader tier, Leonardo S.p.A. and Thales Group exemplify divergent strategic positions. Leonardo leverages vertically integrated rotorcraft heritage to anchor naval VTOL deployments, while Thales occupies a position defined by captive command-and-control architectures that reduce third-party dependency. Safran SA represents the propulsion miniaturization specialist archetype, sustaining advantage in endurance-critical rotary-wing segments through upstream control over engine development.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Thales Group |
| Safran SA |
| Airbus SE |
| BAE Systems plc |
| Rheinmetall AG |
| Saab AB |
| UMS Skeldar AG |
| Quantum-Systems GmbH |
| Others |
Supply & Pricing Matrix
Carbon-fiber prepreg capacity utilization above 80% at Bavarian and Toulouse manufacturing clusters concentrates airframe cost leverage among three European suppliers, compressing price floors for sub-600-kilogram platforms while elevating margins for qualified composite providers.
Pricing Analysis
Polish defense procurement offices pay 15-25% premiums versus Romanian border agencies for identical hybrid VTOL specifications due to NATO interoperability certification requirements and accelerated delivery timelines. Three-tier pricing structure across EASA-certified, national-military-type, and uncertified commercial tiers separates platforms by airworthiness documentation depth. Pricing pressure stems from germanium lens supply bottlenecks propagating through electro-optical subsystem costs. Security agencies exhibit highest price sensitivity due to fragmented national budgets, while naval operators absorb premiums for shipboard-certified configurations.
Supply Chain Analysis
Just-in-time carbon-fiber delivery from Germany and France dominates airframe production, while indium antimonide focal plane arrays draw from strategic stockpiles held by Thales and Safran to buffer against semiconductor foundry allocation volatility. German precision machining clusters, French avionics corridors, and Polish final-assembly facilities anchor geographic supply concentration. Single-source vulnerability concentrates in non-European germanium refining operations. Distribution runs through national military procurement offices with direct OEM relationships displacing traditional integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's tactical UAV sector sits in early-cycle expansion as NATO eastern flank commitments accelerate fleet modernization timelines beyond traditional defense procurement rhythms.
For Market Incumbents: Secure captive command-and-control software architectures before EU AI Act transparency requirements harden compliance burdens for autonomous navigation segments. Consolidate backward integration into carbon-fiber airframe production to defend margin position against emerging Polish and Baltic assembly challengers. Prioritize EASA military-type certification investments that create regulatory moats around NATO interoperability contracts. For New Entrants and Emerging Players: Anchor in Romanian Danube Delta surveillance gaps where runway-independent hybrid platforms face limited incumbent saturation. Target security agency procurement workflows with reduced kinetic payload requirements that bypass lengthy military certification pathways. Pursue direct relationships with Bucharest defense procurement offices rather than competing for Warsaw's consolidated vendor shortlists. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors propulsion miniaturization specialists with upstream engine control and hybrid-electric architecture patents. Long-term viability hinges on software-defined mission flexibility rather than airframe heritage alone. Acquisition targets should demonstrate captive sensor payload integration capabilities. The signal to monitor is EASA's publication of military-type certification pathways for beyond-visual-line-of-sight autonomous engagement.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Software Stack Development | Reduces third-party dependency for EU AI Act algorithmic transparency compliance. |
| Hybrid-Electric Propulsion Investment | Decomposes vertical launch versus cruise efficiency trade-offs for naval operators. |
| Carbon-Fiber Backward Integration | Secures airframe cost leverage against qualified European prepreg suppliers. |
| EASA Certification Pre-Positioning | Accelerates cross-border sales eligibility before national authority divergence hardens. |
| Maritime Payload Integration | Captures Baltic and Mediterranean synthetic aperture radar correlation demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with defense procurement officers at Polish and Romanian ministries, EASA certification specialists, naval VTOL program managers, and composite airframe production directors. Secondary validation drew from NATO interoperability standards documentation, EASA military-type certification bulletins, EU Drone Regulation implementation reports, and customs records of germanium and indium import flows. Bottom-up platform deployment estimates triangulated against top-down defense budget allocation analysis.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across fixed-wing, rotary-wing, hybrid, and nano product types; military, law enforcement, security agency, and civil defense end users; surveillance, reconnaissance, combat, and search and rescue applications; and electro-optical, infrared, GPS, and communication systems technologies. CAGRs were derived from weighted average of deployment trajectory scenarios and procurement pipeline visibility. Industry-specific forecast inputs included NATO forward-deployment commitment timelines and EU Green Deal propulsion miniaturization investment flows.
Decision-makers should treat outputs as directional under assumptions of sustained NATO eastern flank posture and EASA regulatory adaptation timelines; material deviation in either would warrant model refresh. Specific risk factors include abrupt germanium supply disruption, divergent national military aviation authority requirements fragmenting cross-border sales eligibility, and EU AI Act implementation delays compressing autonomous system fielding schedules. Revision becomes warranted when EASA certification backlog crosses twelve-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Toy Drones Market
UAV
United States Drone Services Market
UAV
Drone Lens Market
UAV
Drone Wireless Charging Station Market
UAV
Tethered Drones Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Delivery Drones Market
UAV
Drone-Based Consulting Services Market
UAV
Global Drone Autopilots Market
UAV
UAV Navigation Systems Market
UAV
Asia-Pacific Drone Software Market
UAV
Counter Drone System Market
UAV
Drone Defense System Market
UAV
Global Drone Analytics Market
UAV
Passenger Drones Market
UAV
Global Aerial Imaging Market