
 Acute Heart Failure (AHF) Therapeutics Market | 2026-2036
Acute Heart Failure (AHF) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Heart Failure (AHF) Therapeutics Market Insights
A shortage of interventional cardiologists trained in acute hemodynamic management is reorganizing how hospitals deploy AHF treatment protocols. Bayer AG leverages its established IV diuretic portfolio to sustain presence in emergency departments across North America and Europe. Novartis AG anchors its competitive position through chronic-to-acute heart failure therapeutic continuity, while Cytokinetics, Inc. differentiates by specializing in novel cardiac myosin activators for acute decompensated cases.
Acute heart failure therapeutics comprise pharmacological agents administered to stabilize patients experiencing sudden cardiac decompensation, typically involving intravenous vasodilators, inotropes, and loop diuretics formulated for rapid hemodynamic effect. These agents function to restore perfusion pressure, reduce pulmonary congestion, and prevent end-organ damage during critical episodes. Diuretics occupy the largest revenue share within product type segmentation due to their universal application in fluid overload management, while subcutaneous delivery modes represent the fastest-expanding category as manufacturers reduce hospital length-of-stay through outpatient-compatible formulations. Emergency medical services constitute a concentrated growth vector among end users, driven by pre-hospital administration protocols that compress time-to-treatment intervals.
The FDA maintains stringent cardiovascular safety requirements through its Division of Cardiology and Nephrology, compelling sponsors to demonstrate mortality or hospitalization benefits in large outcome trials. The EMA's Committee for Medicinal Products for Human Use applies similar evidentiary standards through centralized marketing authorization procedures, while Japan's PMDA imposes additional ethnic bridging study requirements for inotropic agents. Stakeholders must monitor evolving regulatory postures toward surrogate endpoint acceptability, as biomarker-based approvals could fundamentally alter development economics and competitive entry timelines for novel AHF mechanisms.
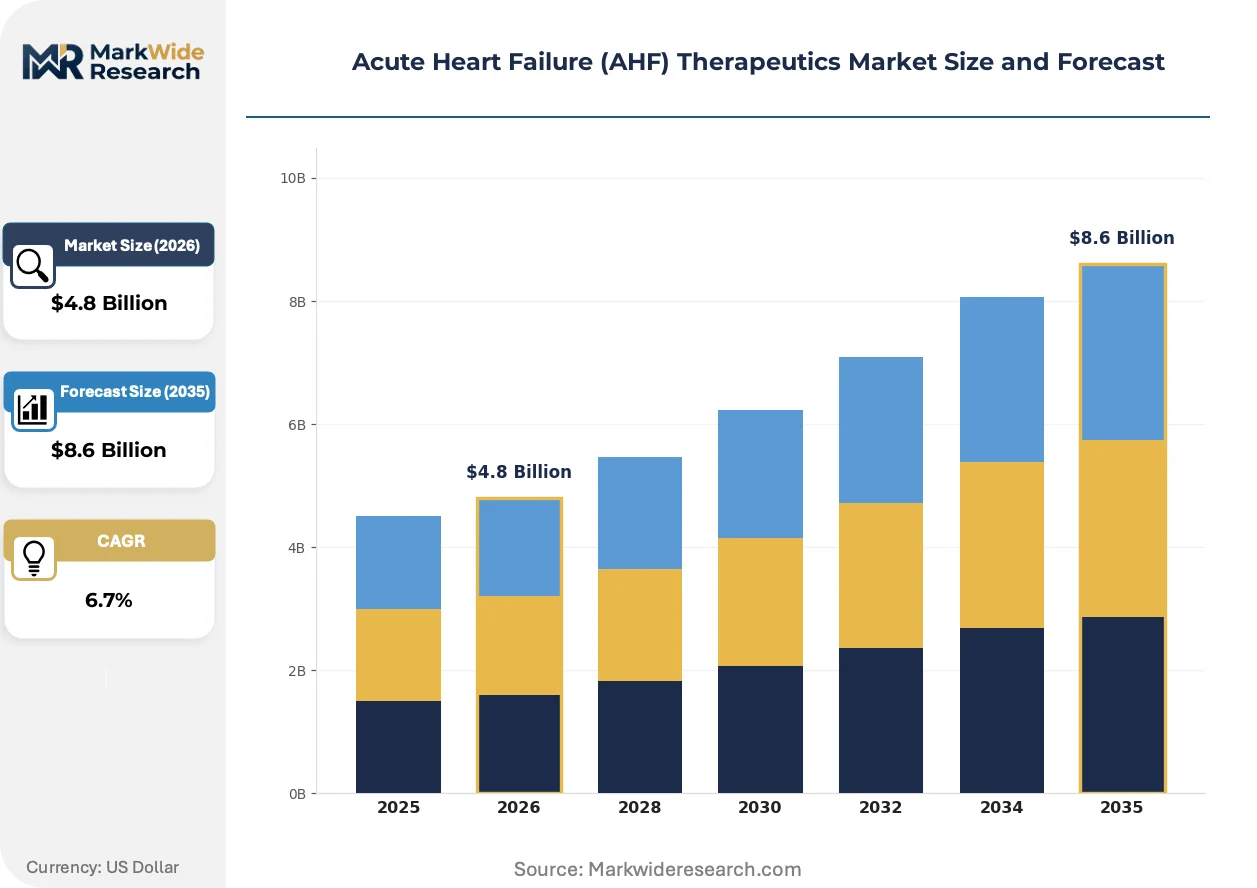
Market Dynamics
The FDA's accelerated approval pathways for cardiovascular drugs are compressing development timelines and forcing sponsors to front-load mortality outcome trials, restructuring how capital flows into acute heart failure R&D pipelines.
Growth Catalysts
- Pre-hospital administration protocols:Emergency medical services in the United States are deploying rapid-acting intravenous therapies in ambulances, compressing time-to-treatment intervals and expanding addressable patient capture before hospital arrival.
- Subcutaneous delivery innovation:Manufacturers are reducing hospital length-of-stay through outpatient-compatible formulations, creating new revenue streams in post-acute care settings previously unreachable with IV-only agents.
- EMA centralized marketing authorization:The streamlined procedure enables simultaneous multi-country entry across EU member states, reducing regulatory duplication costs for sponsors targeting European emergency departments.
Market Restraints
- Interventional cardiologist shortage:The scarcity of specialists trained in acute hemodynamic management limits protocol deployment in tertiary centers, constraining volume growth in high-acuity settings.
- Large outcome trial costs:Demonstrating mortality or hospitalization benefits requires massive patient populations, elevating capital barriers for novel mechanism entrants without established cardiovascular portfolios.
- Ethnic bridging study requirements:Japan's PMDA imposes additional clinical obligations for inotropic agents, extending timelines and costs for Asia-Pacific market access.
Strategic Opportunities
- Critical care infrastructure gaps:Emerging economies with aging demographics but underdeveloped emergency department networks present first-mover advantages for rapid-acting formulation sponsors.
- Biomarker-based approval pathways:Evolving FDA posture toward surrogate endpoint acceptability could fundamentally alter development economics, rewarding sponsors with validated hemodynamic biomarkers.
- Chronic-to-acute therapeutic continuity:Integrated portfolios spanning stable heart failure through decompensated episodes enable longitudinal patient capture and formulary consolidation.
Industry Challenges
- Cardiovascular safety evidentiary burden:The FDA Division of Cardiology and Nephrology maintains stringent mortality demonstration requirements, forcing sponsors to maintain expensive outcome trial infrastructure throughout development.
- Post-approval surveillance complexity:Accelerated approvals mandate rigorous confirmatory study execution, creating operational risk for sponsors whose confirmatory trials fail to replicate surrogate endpoint signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Heart Failure (AHF) Therapeutics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angiotensin Receptor Blockers, Beta-Blockers, Diuretics, ACE Inhibitors Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Specialty Clinics, Homecare, Emergency Medical Services Indication: Heart Rate Control, Fluid Overload Management, Blood Pressure Regulation, Cardiac Output Improvement |
| Companies Covered | Bayer AG, Bristol-Myers Squibb Company, Novartis AG, Cytokinetics, Inc., Merck & Co., Cardiorentis AG, CVie Therapeutics Limited, Windtree Therapeutics, Adrenomed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Heart Failure (AHF) Therapeutics Market Trends and Innovations
Acute heart failure therapeutics are undergoing rapid formulation evolution as manufacturers compete to compress treatment initiation windows and extend care settings beyond traditional hospital boundaries.
Wearable hemodynamic monitoring technology is miniaturizing. Emergency medical services in the United States are piloting patch-based sensors that transmit preload and afterload data during ambulance transport. This capability is miniaturizing the diagnostic gap between symptom onset and therapeutic decision-making, enabling pre-hospital vasodilator titration previously impossible without catheterization laboratory access.
The FDA's Division of Cardiology and Nephrology is tightening evidentiary standards for novel inotropic mechanisms. Sponsors must now demonstrate cardiovascular mortality benefits rather than symptom relief alone, elevating trial complexity and favoring established players with outcome trial infrastructure. Intravenous cardiac myosin activators face the steepest compliance burden under this posture.
Hospital procurement committees are unbundling acute heart failure drug selection from bundled payment contracts. Emergency departments in Germany and France are negotiating standalone pharmaceutical budgets separate from diagnosis-related group reimbursements, enabling faster adoption of premium rapid-acting agents when length-of-stay reductions justify incremental cost.
Acute Heart Failure (AHF) Therapeutics Market Segmentation
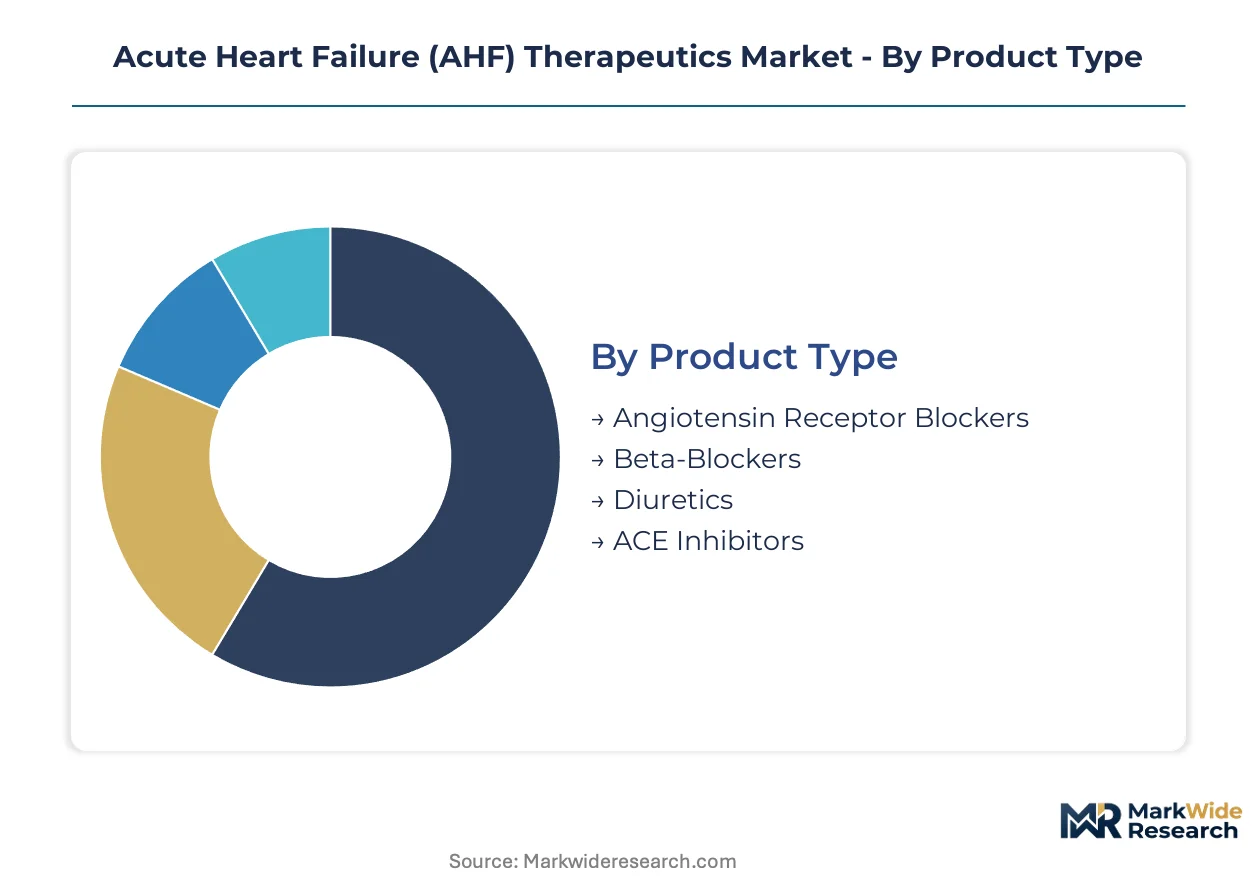
Acute heart failure therapeutics traverse distinct distribution channels based on formulation urgency and care setting. Channel economics determine which segments command procurement priority in emergency departments versus outpatient environments.
Product Type:
Hospital pharmacies and emergency department formularies stock different therapeutic classes based on hemodynamic intervention speed and protocol standardization requirements.
- Diuretics:Loop diuretics administered intravenously remain the cornerstone of pulmonary congestion management in emergency departments. Demand concentrates in United States tertiary centers where fluid overload protocols mandate immediate decongestion. Aging demographics sustain volume through recurrent decompensation episodes.
- ACE Inhibitors:These agents interrupt the renin-angiotensin-aldosterone system to reduce afterload during acute stabilization. German and French emergency departments prioritize early oral transition to shorten intensive care stays. Regulatory pressure from EMA cardiovascular safety divisions elevates mortality outcome requirements for novel entrants.
- Angiotensin Receptor Blockers:Substitute therapy for ACE inhibitor-intolerant patients with similar hemodynamic endpoints.
- Beta-Blockers:Rate control in tachyarrhythmia-driven decompensation, with intravenous esmolol favored for titratability.
By volume, Diuretics leads hospital procurement. By growth pace, ACE Inhibitors is climbing the fastest as oral transition protocols expand.
Delivery Mode:
Cost tier stratification separates premium rapid-acting formulations from maintenance therapies, with reimbursement codes reinforcing channel boundaries.
- Intravenous:Direct vascular administration achieves therapeutic thresholds within minutes for critical hemodynamic collapse. United States emergency medical services deploy pre-hospital IV vasodilators under standing orders. FDA Division of Cardiology and Nephrology mandates cardiovascular mortality demonstrations for novel IV mechanisms.
- Subcutaneous:Depot formulations enable observation-unit discharge without inpatient admission. Japanese regulators impose ethnic bridging study requirements that extend Asia-Pacific access timelines. Outpatient-compatible delivery captures post-acute revenue streams previously unreachable.
- Oral:Maintenance dosing following stabilization, with bioavailability concerns in gut edema patients.
- Inhalation:Pulmonary delivery for select vasodilators, limited by formulation stability challenges.
By revenue concentration, Intravenous dominates emergency procurement. By expansion trajectory, Subcutaneous gains share fastest as length-of-stay reduction incentives intensify.
End User:
Customer type fragmentation creates distinct purchasing behaviors across institutional buyers, with procurement authority residing at different administrative levels.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts spanning emergency departments through step-down units. United States health systems consolidate formularies to maximize rebate capture from cardiovascular portfolios. Critical care infrastructure concentration in tertiary centers limits protocol deployment in community settings.
- Emergency Medical Services:Municipal and private ambulance operators purchase through regional cooperative agreements. Pre-hospital administration protocols compress time-to-treatment intervals before hospital arrival. Regulatory variance across United States state pharmacy boards complicates interstate protocol standardization.
- Specialty Clinics:Cardiology-focused outpatient facilities managing post-acute transitions.
- Homecare:Infusion services for stable patients requiring ongoing diuretic or inotropic support.
By patient volume throughput, Hospitals leads. By growth momentum, Emergency Medical Services is expanding most quickly as pre-hospital scope-of-practice broadens.
Indication:
Application urgency determines formulary tier placement, with life-threatening presentations commanding unrestricted access.
- Fluid Overload Management:Pulmonary congestion and peripheral edema drive the majority of acute presentations requiring immediate intervention. Loop diuretic resistance in advanced heart failure creates demand for combination therapy. Renal function monitoring requirements complicate dosing in cardiorenal syndrome patients.
- Cardiac Output Improvement:Low-output states unresponsive to volume management require inotropic or mechanical support. Inotrope dependency carries mortality risk that shapes informed consent protocols. PMDA ethnic bridging requirements specifically target this indication for Asia-Pacific market entry.
- Heart Rate Control:Tachyarrhythmia management to reduce myocardial oxygen demand.
- Blood Pressure Regulation:Afterload reduction in hypertensive emergency presentations.
By clinical encounter frequency, Fluid Overload Management leads. By unmet need intensity, Cardiac Output Improvement shows the steepest expansion trajectory as novel inotropic mechanisms advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acute heart failure therapeutics consumption diverges sharply between established critical care infrastructure and emerging emergency medicine networks. The United States deploys rapid-acting intravenous agents through pre-hospital protocols, while Japan and Germany emphasize length-of-stay reduction through subcutaneous transitions.
United States
Emergency medical services in the United States deploy rapid-acting intravenous therapies under standing orders, compressing time-to-treatment intervals before hospital arrival. The FDA's Division of Cardiology and Nephrology mandates cardiovascular mortality demonstrations for novel mechanisms, elevating development barriers. Tertiary centers in Boston and Cleveland concentrate protocol deployment, though community hospital access remains constrained by interventional cardiologist shortages.
Germany
German emergency departments prioritize early oral transition protocols to shorten intensive care stays, driving ACE inhibitor demand. The EMA's Committee for Medicinal Products for Human Use applies centralized marketing authorization procedures, streamlining multi-country entry. Procurement committees in Berlin and Munich unbundle AHF drug selection from diagnosis-related group reimbursements, enabling premium rapid-acting agent adoption.
Japan
Japanese regulators impose ethnic bridging study requirements for inotropic agents, extending Asia-Pacific market access timelines. The PMDA maintains additional clinical obligations for cardiac output improvement indications that shape sponsor development strategies. Tokyo and Osaka medical centers concentrate subcutaneous formulation trials, reducing hospital length-of-stay through outpatient-compatible delivery.
United Kingdom
UK emergency departments face National Health Service formulary constraints that favor cost-effective diuretic protocols over premium mechanisms. The MHRA applies EMA-aligned cardiovascular safety standards through post-Brexit recognition procedures. London and Manchester tertiary centers pilot wearable hemodynamic monitoring for pre-hospital diagnostic gaps.
India
Indian emergency medicine networks confront underdeveloped critical care infrastructure that limits protocol deployment outside metropolitan hospitals. The CDSCO requires local clinical trial data for novel cardiovascular mechanisms, extending registration timelines. Cardiology-focused centers in Mumbai and Delhi concentrate fluid overload management capacity, though rural access remains fragmented.
Acute Heart Failure (AHF) Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in acute heart failure therapeutics. Large pharmaceutical conglomerates leverage established cardiovascular portfolios and outcome trial infrastructure to dominate emergency department formularies. Specialist biopharmaceutical developers concentrate on novel mechanisms such as cardiac myosin activators. Competitive positioning depends on chronic-to-acute therapeutic continuity and accelerated regulatory pathway navigation.
Among integrated pharmaceutical conglomerates, Bayer AG and Novartis AG exemplify portfolio breadth spanning chronic through decompensated heart failure episodes. Cytokinetics, Inc. occupies a specialist position focused on novel cardiac myosin activators for acute decompensated presentations. These three entities represent distinct strategic archetypes: diuretic-based emergency presence, longitudinal therapeutic continuity, and mechanism-specific innovation.
| Leading Market Players |
|---|
| Bayer AG |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Cytokinetics, Inc. |
| Merck & Co. |
| Cardiorentis AG |
| CVie Therapeutics Limited |
| Windtree Therapeutics |
| Adrenomed |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at sterile injectable manufacturing sites in Ireland and Puerto Rico shapes both supply availability and price floors for intravenous diuretics and vasodilators. Scale economies at these FDA-inspected facilities concentrate production of rapid-acting AHF formulations, enabling incumbent sponsors to maintain premium positioning while newer entrants face capital barriers to GMP-compliant capacity.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement, with integrated delivery networks negotiating enterprise-wide rebates spanning emergency departments through step-down units. Price differentiation rests on FDA approval tier and cardiovascular outcome trial pedigree, with mortality-demonstrated mechanisms commanding formulary preference over symptom-relief alternatives. Cost compression in the generic diuretic segment is intensifying because of Indian API import competition, though patented subcutaneous formulations retain pricing power. Community hospitals exhibit the highest price sensitivity due to constrained pharmacy budgets, while tertiary academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Active pharmaceutical ingredient synthesis for cardiac glycosides and loop diuretics draws from China, India, and Italy, with intermediate chemical production concentrated in the Yangtze River Delta region. Key inputs include digoxin raw material, furosemide precursors, and specialized fermentation media for biologic inotropes. Single-source vulnerability for sterile fill-finish capacity at contract manufacturing organizations in Switzerland and Germany elevates supply continuity risk. Distribution runs through cold-chain logistics networks serving hospital central pharmacies and emergency medical services regional depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-hospital administration protocol adoption represents an early-cycle expansion opportunity, with emergency medical services scope-of-practice broadening across United States state pharmacy boards to enable ambulance-based vasodilator initiation before hospital arrival.
For Market Incumbents: Fortify emergency department formulary position through chronic-to-acute therapeutic continuity, leveraging longitudinal patient data to demonstrate reduced rehospitalization rates. Expand sterile injectable capacity in Puerto Rico to offset tariff exposure on European-sourced finished goods. Invest in cardiovascular outcome trial infrastructure to meet FDA Division of Cardiology and Nephrology mortality demonstration requirements for novel mechanism defense.
For New Entrants and Emerging Players: Anchor in the subcutaneous delivery segment, where outpatient-compatible formulations face less entrenched competition than intravenous emergency protocols. Target Japanese and German markets for premium positioning, as these geographies emphasize length-of-stay reduction over acquisition cost. Pursue biomarker-based approval pathways to compress development timelines and circumvent large outcome trial capital requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with validated hemodynamic biomarkers and established cardiac myosin activator platforms. Long-term viability over the next decade hinges on regulatory pathway navigation capability and outcome trial execution infrastructure. Watch FDA posture toward surrogate endpoint acceptability as the critical inflection signal for development economics transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular mortality demonstrations satisfy FDA Division of Cardiology requirements for novel inotropic mechanisms. |
| Regulatory Approval Pathway | Accelerated approval via biomarker endpoints compresses time-to-market for acute decompensated heart failure indications. |
| Manufacturing Scale-Up | Sterile injectable capacity expansion in Ireland and Puerto Rico secures supply continuity for emergency department formularies. |
| Hospital System Partnership | Integrated delivery network contracts enable longitudinal patient capture from chronic through acute decompensated episodes. |
| Pipeline Diversification | Subcutaneous formulation development captures post-acute revenue streams previously unreachable with IV-only agents. |
Research Methodology
A spread of perspectives from emergency department pharmacy directors, interventional cardiologists, regulatory affairs specialists at cardiovascular sponsors, and emergency medical services medical directors converged on the working assumptions. Primary interviews combined with secondary validation from FDA advisory committee transcripts, EMA CHMP assessment reports, ClinicalTrials.gov cardiovascular trial registries, and hospital formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Segmentation dimensions modeled include product type, delivery mode, end user, and indication severity tier across the projection horizon. CAGRs were derived from epidemiological trend extrapolation, protocol adoption curve analysis, and pricing trajectory assumptions. Key inputs encompassed acute heart failure hospitalization incidence projections, pre-hospital administration protocol penetration rates, and regulatory pathway timeline distributions.
Material uncertainties — confirmatory trial outcome replication, FDA surrogate endpoint policy evolution, and interventional cardiologist workforce expansion — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as accelerated approval confirmatory study results and biomarker validation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Ischemia Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Global Statin Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Global Deep Vein Thrombosis Market