
 Tachycardia Market | 2026-2036
Tachycardia Market Size, Share, and Industry Trends Forecast 2026-2036
Tachycardia Market Outlook
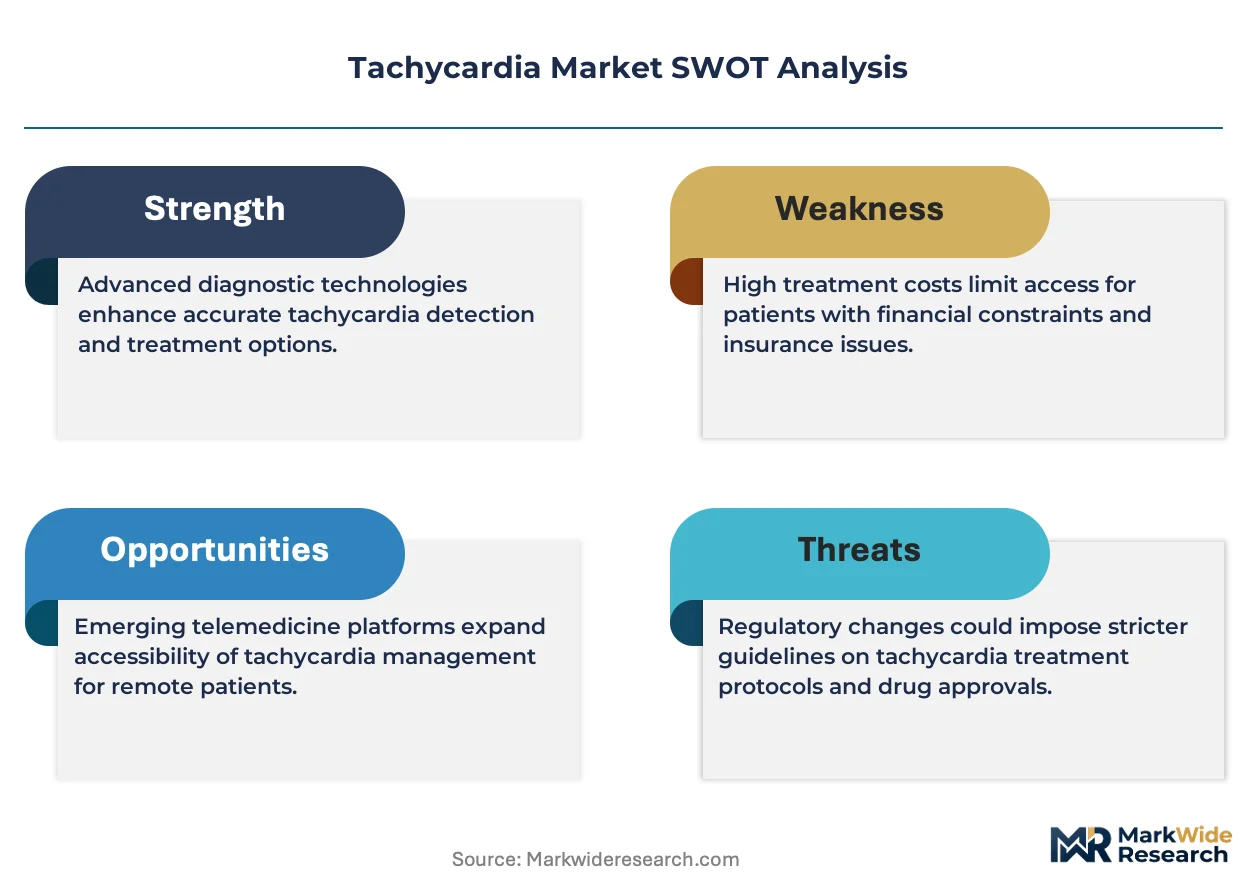
A widening R&D-to-manufacturing scale gap is redrawing competitive boundaries across the tachycardia landscape. Medtronic plc leverages its vertically integrated catheter production to sustain price competitiveness in cardiac ablation systems. Abbott Laboratories anchors its position through proprietary mapping and navigation technologies that differentiate complex procedure workflows.
Tachycardia encompasses pathological heart rhythms exceeding 100 beats per minute, typically diagnosed via 12-lead electrocardiography, ambulatory Holter monitoring, or invasive electrophysiological study with 3D cardiac mapping. The condition demands pharmacological suppression, electrical cardioversion, or catheter-based ablation to restore normal sinus rhythm and prevent hemodynamic compromise. Antiarrhythmic Drugs and Beta-Blockers dominate current prescription volumes, though catheter ablation for Atrial Fibrillation now captures the fastest-growing share of interventional spending as outcomes data shift clinical guidelines toward earlier procedural intervention. Hospitals remain the primary site of acute diagnosis and intervention, while Homecare Settings are expanding for post-ablation monitoring and chronic antiarrhythmic drug management.
FDA premarket approval pathways and EU MDR technical documentation requirements shape device development timelines and market access costs for ablation catheters and implantable monitors. Japan's PMDA enforces stringent clinical evidence standards that delay entry but confer durable competitive moats for compliant manufacturers. Stakeholders must weigh regulatory investment intensity against the procedure volume trajectories emerging from updated ACC/AHA and ESC guideline recommendations.
Market Dynamics
Catheter ablation systems are displacing chronic pharmaceutical management as first-line therapy for symptomatic atrial fibrillation, forcing manufacturers to reallocate R&D budgets from drug-device combinations toward pure-play electrophysiology hardware.
Growth Catalysts
- EU MDR compliance timelines:Accelerated device recertification cycles are compressing competitive windows, rewarding manufacturers with established quality management systems. German hospital procurement groups now prioritize MDR-certified ablation platforms.
- Japan's aging demographic:PMDA fast-track pathways for breakthrough devices are shortening time-to-reimbursement for novel cardiac mapping systems. Tokyo's tertiary electrophysiology centers drive procedure volume expansion.
- Pulsed field ablation:This non-thermal energy modality reduces esophageal injury risk compared to radiofrequency. Adoption concentrates in US academic medical centers with established electrophysiology fellowship programs.
Market Restraints
- Platinum-iridium electrode supply:Russian-sourced precious metal concentration creates input cost volatility for catheter tip manufacturing. Alternative metallurgy R&D remains capital-intensive.
- PMDA clinical evidence requirements:Japan's demand for domestic patient cohort data extends registration timelines by 18-24 months versus FDA pathways. This structural barrier protects incumbent positions.
- Antiarrhythmic drug substitution:Generic sotalol and amiodarone availability sustains pharmacological management as a low-cost alternative for rate-control patients. Payers in Germany enforce step-therapy protocols.
Strategic Opportunities
- Remote cardiac monitoring:Post-ablation ambulatory ECG patch services create recurring revenue streams outside acute hospital settings. US cardiology groups are unbundling device implantation from longitudinal monitoring.
- AI-enabled arrhythmia detection:Machine learning algorithms applied to consumer wearables expand addressable screening populations. Integration with electronic health records in Japanese clinics accelerates referral pathways.
- US hospital-at-home waivers:CMS reimbursement flexibility for acute-level monitoring outside traditional facilities opens channel innovation for implantable loop recorders. Health systems in Florida and Texas pilot decentralized electrophysiology follow-up.
Industry Challenges
- Electrophysiologist training pipeline:Fellowship slot constraints in US academic medical centers limit procedure capacity expansion. Competency certification for novel energy modalities adds curriculum burden.
- EU MDR technical documentation:Clinical evaluation report requirements for legacy ablation catheters demand retrospective data aggregation. Notified body backlogs extend recertification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tachycardia Market |
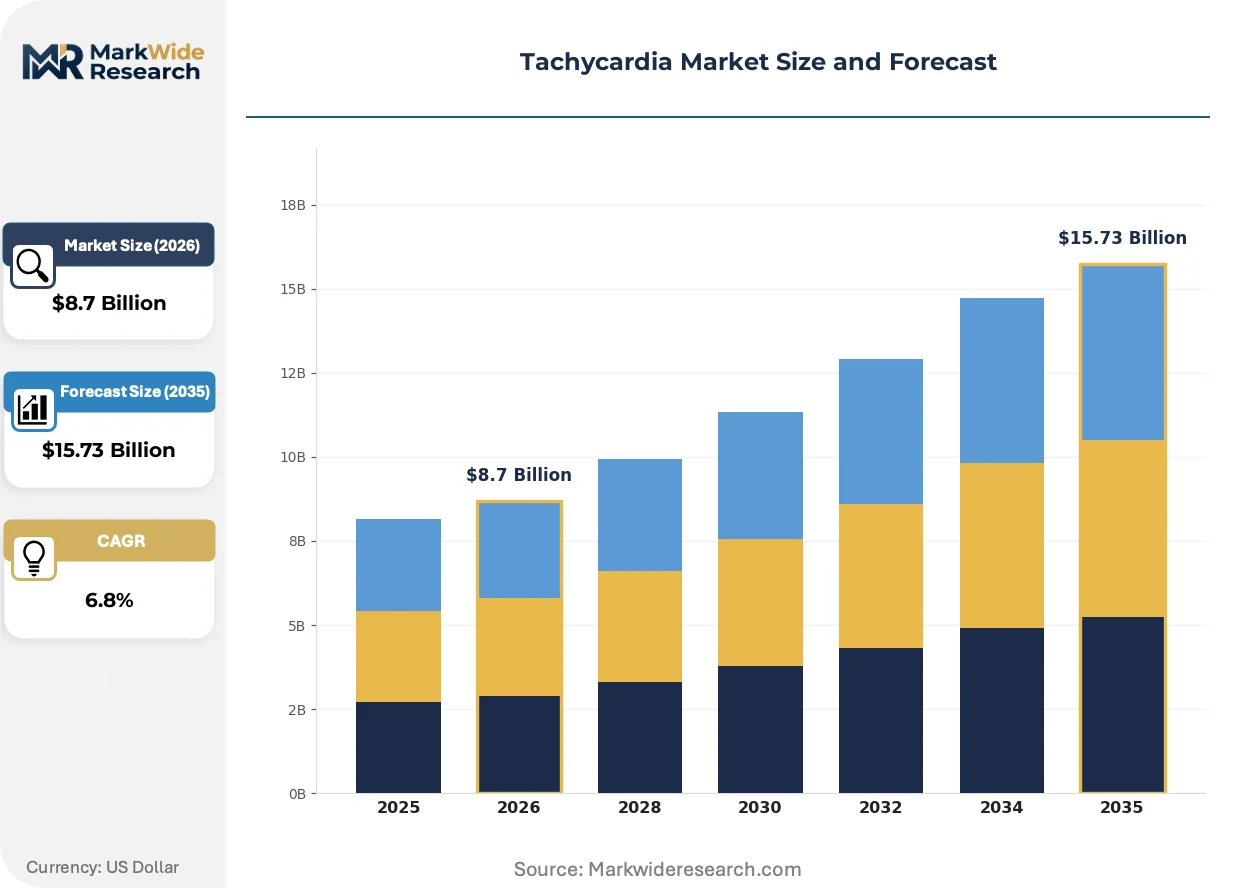
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiarrhythmic Drugs, Beta-Blockers, Calcium Channel Blockers, Heart Rate Monitors Therapy Area: Atrial Fibrillation, Supraventricular Tachycardia, Ventricular Tachycardia, Postoperative Tachycardia End User: Hospitals, Clinics, Homecare Settings, Outpatient Facilities Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal |
| Companies Covered | Pfizer Inc., GSK plc, Novartis AG, AstraZeneca, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tachycardia Market Strategic Shifts
Electrophysiology workflows are converging toward single-procedure definitive therapy, compressing the traditional trial-and-error sequence of drug escalation that defined tachycardia management for decades.
Dielectric sensing technology integrated into ablation catheter tips enables real-time tissue contact assessment without fluoroscopic confirmation. Academic electrophysiology labs in the United States and Germany are adopting these sensor-augmented platforms for complex atrial substrate mapping. This hardware layer is miniaturizing previously standalone mapping systems into disposable catheter components, collapsing the capital equipment footprint required for new lab startups.
FDA breakthrough device designation pathways are compressing premarket review timelines for novel cardiac ablation modalities. The industrial consequence is a concentration of regulatory investment among manufacturers with dedicated FDA liaison capabilities. Atrial fibrillation ablation platforms with pulsed field energy delivery are most affected, with sponsors accelerating clinical trial enrollment to secure priority review vouchers.
Hospital purchasing committees are unbundling capital equipment procurement from disposable catheter supply agreements. Integrated delivery networks in the United States now separate imaging system acquisitions from ablation catheter vendor selection. This behavioral shift is most visible in Texas and California health systems, where electrophysiology service line directors negotiate multi-source supply contracts to mitigate single-manufacturer dependency.
Tachycardia Market Segmentation
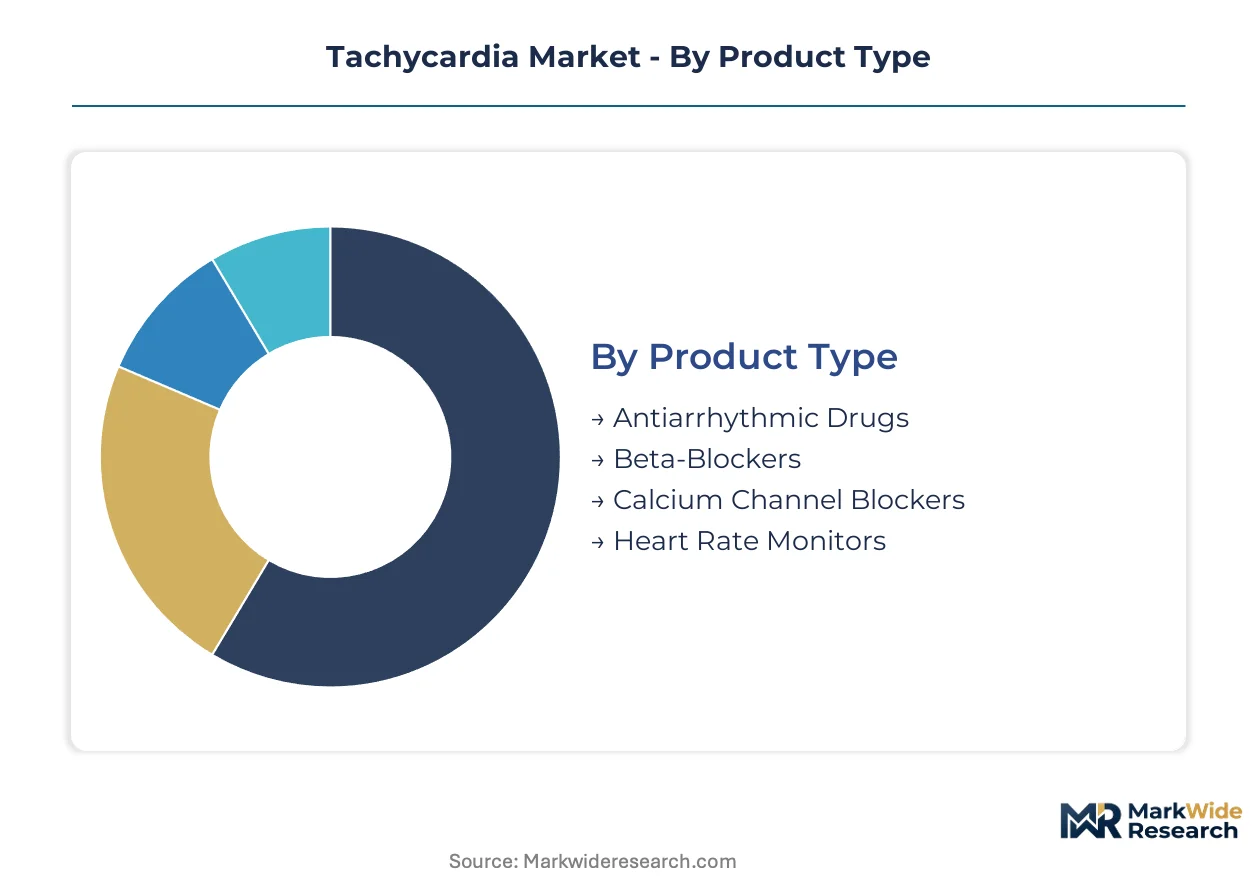
Tachycardia treatment pathways fragment across pharmacological, interventional, and monitoring modalities with distinct margin profiles and reimbursement dynamics. Understanding segment boundaries clarifies where capital deployment yields sustainable returns versus commoditized competition.
Product Type:
Premium margins concentrate in device-based monitoring and catheter-based interventions, while pharmaceutical segments compete on volume scale and generic substitution defense.
- Antiarrhythmic Drugs:Pharmacological agents including amiodarone, sotalol, and flecainide suppress arrhythmia initiation through sodium, potassium, or calcium channel modulation. Demand clusters in Germany and Japan where step-therapy protocols delay procedural escalation, though generic erosion compresses pricing power.
- Beta-Blockers:Rate-control medications such as metoprolol and esmolol reduce ventricular response in atrial fibrillation without restoring sinus rhythm. Prescription volumes dominate US outpatient cardiology practices as first-line symptomatic management, particularly among elderly patients with comorbid hypertension.
- Calcium Channel Blockers:Non-dihydropyridine agents like verapamil and diltiazem provide alternative rate control for beta-blocker-intolerant patients.
- Heart Rate Monitors:Wearable ECG patches and implantable loop recorders enable ambulatory rhythm surveillance with recurring service revenue models.
The dominant share belongs to Antiarrhythmic Drugs, while Heart Rate Monitors are closing the gap fastest.
Therapy Area:
Procedure complexity and reimbursement intensity vary sharply across arrhythmia substrates, with atrial pathologies offering scale and ventricular conditions commanding premium intervention pricing.
- Atrial Fibrillation:The most prevalent sustained arrhythmia characterized by chaotic atrial electrical activity driving irregular ventricular response. Catheter ablation volumes concentrate in US academic medical centers and Tokyo tertiary hospitals where pulsed field energy adoption accelerates procedural throughput.
- Supraventricular Tachycardia:Re-entrant circuits involving atrioventricular nodal or accessory pathway mechanisms typically presenting in younger patients. Ablation cure rates exceed 95%, driving one-and-done procedural economics in German electrophysiology labs with high fixed-cost utilization.
- Ventricular Tachycardia:Life-threatening rhythms arising from ventricular myocardium demanding urgent intervention with implantable defibrillator backup.
- Postoperative Tachycardia:Iatrogenic arrhythmias following cardiac surgery managed through temporary pacing or pharmacological suppression in intensive care settings.
Atrial Fibrillation captures the largest patient volume, though Ventricular Tachycardia commands the highest per-procedure reimbursement intensity.
End User:
Site-of-care economics determine capital equipment requirements and staffing models, with acute settings absorbing technology investment and ambulatory channels extracting recurring monitoring value.
- Hospitals:Inpatient facilities house electrophysiology labs with 3D mapping systems and catheter ablation capabilities. German hospital procurement groups and US integrated delivery networks drive capital equipment decisions with multi-year disposable supply contracting.
- Clinics:Outpatient cardiology practices manage stable patients through diagnostic workup and antiarrhythmic titration.
- Homecare Settings:Post-ablation monitoring and chronic drug management shift to remote care models.
- Outpatient Facilities:Ambulatory surgery centers perform low-complexity ablations with streamlined reimbursement.
Hospitals retain the procedural revenue concentration, while Homecare Settings are expanding most quickly through remote monitoring unbundling.
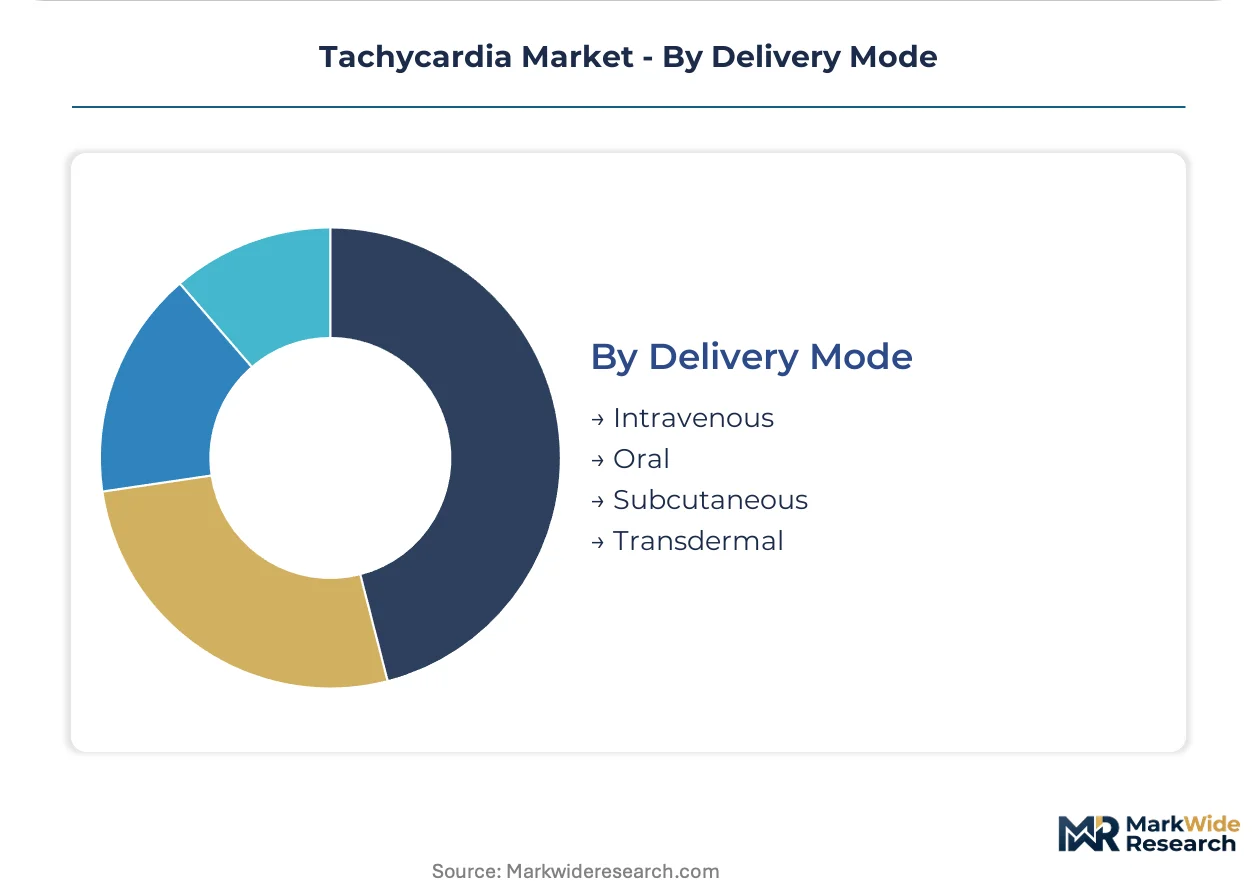
Delivery Mode:
Route of administration shapes pharmacokinetic profiles, patient compliance economics, and manufacturing complexity with distinct competitive moats.
- Intravenous:Acute administration in emergency departments and electrophysiology labs enables rapid rate or rhythm control. US hospital formularies prioritize IV amiodarone and esmolol for hemodynamically unstable presentations.
- Oral:Chronic outpatient maintenance therapy dominates prescription volumes with once-daily dosing convenience.
- Subcutaneous:Emerging delivery for novel antiarrhythmic formulations and implantable drug-device combinations.
- Transdermal:Patch-based delivery systems under development for sustained beta-blocker release.
Oral formulations command the chronic patient base, while Intravenous delivery anchors acute intervention economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for platinum-iridium electrodes shapes regional manufacturing economics, with supply chain rerouting accelerating catheter production localization in Germany and Japan while the United States absorbs premium device premiums.
United States
Academic medical centers in Boston and Cleveland drive pulsed field ablation adoption through electrophysiology fellowship expansion. FDA breakthrough device designations compress premarket timelines for novel cardiac mapping systems. Texas Health Systems and California integrated delivery networks unbundle capital equipment from disposable catheter contracts.
Germany
Hospital procurement groups in Bavaria and North Rhine-Westphalia enforce MDR-certified platform purchasing for catheter ablation systems. EU MDR technical documentation requirements extend recertification cycles for legacy devices. Heidelberg and Berlin tertiary electrophysiology labs concentrate complex atrial fibrillation procedure volumes.
Japan
Tokyo's aging demographic accelerates PMDA fast-track utilization for breakthrough cardiac devices. Domestic clinical evidence requirements protect compliant manufacturers through extended registration timelines. Osaka and Nagoya medical centers expand electrophysiology capacity for ventricular tachycardia interventions.
United Kingdom
NHS England step-therapy protocols sustain antiarrhythmic drug volumes before procedural escalation. MHRA recognition of EU MDR certificates streamlines device market access post-Brexit. London and Manchester cardiac centers pilot AI-enabled arrhythmia detection from consumer wearables.
India
CDSCO medical device rules harmonization attracts catheter manufacturing investment toward Gujarat and Karnataka. Domestic price controls on cardiac implants pressure multinational premium positioning. Hyderabad and Chennai hospital chains expand electrophysiology lab capacity for supraventricular tachycardia ablations.
Tachycardia Market Competitive Environment
Concentration sits with diversified cardiovascular conglomerates controlling integrated catheter production and proprietary mapping ecosystems. Three to five manufacturers capture the majority of ablation system revenue through captive electrode metallurgy and 3D navigation software. Strategic moves center on M&A for electrophysiology data platforms and backward integration into precious metal refining to offset supply volatility.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories occupy positions spanning device hardware through disposable catheter supply. Pfizer Inc., Novartis AG, and AstraZeneca exemplify pharmaceutical archetypes defending antiarrhythmic franchises against procedural substitution. Boston Scientific Corporation and Johnson & Johnson sit within the interventional cardiology tier competing on ablation catheter energy delivery modalities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc |
| Novartis AG |
| AstraZeneca |
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Boehringer Ingelheim International GmbH |
| Others |
Value Chain & Pricing Dynamics
Long-term catheter supply agreements with German hospital procurement groups lock in platinum-iridium electrode access and ablation system price visibility across multi-year contracting windows. These arrangements insulate manufacturers from spot-market precious metal volatility while anchoring reimbursement predictability for electrophysiology service lines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in catheter ablation systems. FDA breakthrough designation and EU MDR certification tiers command brand premiums, while generic antiarrhythmic substitution in Germany intensifies cost compression in pharmaceutical segments. Price erosion runs through beta-blocker and sotalol categories where step-therapy protocols enforce volume purchasing. US academic medical centers show lowest price sensitivity for pulsed field ablation platforms, while Indian hospital chains prioritize economy-tier procurement under domestic price controls.
Supply Chain Analysis
Russian-sourced platinum-iridium concentrate creates chokepoint vulnerability for catheter tip electrode manufacturing. Production draws from metallurgical refining clusters in Germany, Japan, and the United States, with dielectric sensor components sourced from South Korean semiconductor foundries. Single-source dependency on precious metal suppliers exposes margin compression when commodity volatility spikes. Distribution runs through captive catheter production facilities operated by diversified cardiovascular conglomerates, bypassing third-party logistics for sterile disposable integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tachycardia market exhibits cyclical recovery characteristics as deferred catheter ablation procedures clear post-pandemic backlogs and pulsed field energy adoption accelerates replacement cycles in mature electrophysiology labs.
For Market Incumbents: Consolidate mapping software ecosystems with disposable catheter hardware to defend against unbundling pressures from US integrated delivery networks. Backward integration into precious metal refining secures electrode supply continuity amid Russian sourcing disruption. Expand MDR-certified production capacity in Germany to capture EU hospital procurement preference for compliant platforms.
For New Entrants and Emerging Players: FDA breakthrough device fast-track pathways offer expedited market access for novel cardiac ablation modalities with superior esophageal safety profiles. Remote cardiac monitoring services present the most penetrable white-space segment, with post-ablation ambulatory ECG patch demand outpacing supply in Texas and Florida health systems. Partner with Japanese PMDA consultants to navigate domestic clinical evidence requirements for Tokyo tertiary center adoption.
For Investors and Strategic Acquirers: Electrophysiology data platform specialists with AI-enabled arrhythmia detection algorithms represent priority acquisition targets as workflow software becomes the differentiation layer. Long-term viability hinges on procedural volume trajectories shifting toward earlier intervention per updated ACC/AHA guidelines. Watch for PMDA fast-track designation announcements as inflection indicators for Japanese reimbursement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Refining | Captive platinum-iridium supply secures catheter electrode manufacturing cost stability against Russian sourcing volatility. |
| FDA Breakthrough Device Submission | Priority review compresses premarket timelines for pulsed field ablation platforms competing in US academic centers. |
| EU MDR Certification Pathway | Technical documentation compliance unlocks German hospital procurement group contracting for legacy catheter recertification. |
| Hospital System Partnership | Integrated delivery network agreements in Texas and California unbundle capital equipment from disposable catheter supply. |
| Software Companion Development | AI-enabled arrhythmia detection integration with consumer wearables expands addressable screening populations in Japanese clinics. |
Study Parameters
A standing panel of electrophysiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers provided ongoing calibration for primary interview findings. Secondary validation drew from FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up procedure volume estimates triangulated against top-down electrophysiology lab capacity assessments across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks from ACC/AHA registry data and ESC procedural surveys. Segmentation modeling incorporated product type, therapy area complexity, end-user site-of-care economics, and delivery mode pharmacokinetics. CAGRs derived from compound growth trajectory analysis applied to historical procedure volumes and reimbursement rate evolution. Forecast inputs included electrophysiologist fellowship expansion rates and pulsed field ablation adoption curves in US academic medical centers.
Underlying assumptions cover stable platinum-iridium supply continuity, FDA breakthrough pathway integrity, and EU MDR notified body capacity, with deviation risk concentrated in Russian metal export restrictions and PMDA clinical evidence timeline extensions. Revision becomes warranted when catheter ablation procedure volumes in German hospitals diverge from guideline-recommended thresholds or when CMS hospital-at-home waiver permanence crosses legislative decision points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Angina Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market