
 US External Counterpulsation Devices Market | 2026-2036
US External Counterpulsation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US External Counterpulsation Devices Market Insights
Aftermarket service revenue is fragmenting across independent service organizations and original equipment manufacturers. Medtronic sustains extensive field engineering networks that lock in hospital maintenance contracts. Vaso Corporation specializes in counterpulsation-specific technical training and remote monitoring services. Scottcare Corporation competes through regional service density in cardiology-focused ambulatory surgical centers.
External counterpulsation therapy employs pneumatic cuffs wrapped around the lower extremities that inflate sequentially during diastole to augment coronary perfusion pressure, typically delivering treatment sessions of thirty-five hours across seven weeks. The equipment requires ECG-gated timing systems with pressure calibration within five millimeters of mercury for therapeutic efficacy. Portable devices capture expanding margin pools as home-based cardiac rehabilitation gains reimbursement traction, while electromechanical technology leads installed base volumes due to proven clinical outcomes in refractory angina populations. Hospitals remain the dominant end-user channel, though rehabilitation centers represent the fastest-growing site of care as bundled payment models shift post-acute services outside inpatient settings.
FDA 510(k) premarket notification requirements govern device commercialization, with the agency evaluating substantial equivalence to predicate counterpulsation systems. CMS national coverage determinations and local coverage article updates directly influence physician prescribing patterns and capital acquisition timelines. Stakeholders must monitor upcoming CMS physician fee schedule rulemaking for outpatient cardiac rehabilitation add-on payments that could reshape site-of-care economics.
Market Dynamics
CMS reimbursement coding updates for outpatient cardiac rehabilitation are compressing capital acquisition timelines and redirecting device procurement toward hospital outpatient departments and freestanding rehabilitation centers across Medicare-eligible populations.
Growth Catalysts
- Reimbursement Expansion:CMS national coverage determinations for external counterpulsation therapy under Medicare Part B are expanding addressable patient populations in ambulatory settings.
- Refractory Angina Prevalence:Southeast and Midwest states with aging demographics and elevated cardiovascular disease burden are concentrating eligible patient pools for non-invasive intervention.
- Portable Technology Maturation:Electromechanical systems with ECG-gated timing and pressure calibration precision are enabling site-of-care migration beyond traditional hospital infrastructure.
Market Restraints
- Capital Intensity:Electromechanical counterpulsation systems requiring pneumatic cuff arrays and precision pressure calibration represent substantial upfront investment for smaller rehabilitation centers.
- Supply Concentration:Technical training and remote monitoring capabilities concentrate among specialized service organizations, creating vendor lock-in risks for maintenance-dependent providers.
- Clinical Validation Thresholds:FDA 510(k) substantial equivalence requirements predicate on established coronary perfusion outcome data, limiting novel mechanism pathways.
Strategic Opportunities
- Home-Based Rehabilitation:Portable device form factors are capturing reimbursement traction as CMS evaluates add-on payments for remote cardiac monitoring in Medicare Advantage plans.
- Bundled Payment Alignment:Hospital outpatient departments in value-based care arrangements are integrating counterpulsation into episode-based cardiac rehabilitation protocols.
- Technical Training Services:Specialized education programs for pneumatic system maintenance and ECG synchronization are creating recurring revenue streams independent of device sales.
Industry Challenges
- Field Engineering Scarcity:Technicians capable of pressure calibration within five millimeters of mercury and ECG-gated timing troubleshooting are concentrated among original equipment manufacturer networks.
- Legacy System Interoperability:Integration of portable counterpulsation devices with existing hospital electronic health record systems and telemetry infrastructure requires custom interface development.
- Certification Timeline Compression:FDA 510(k) review cycles for predicate-dependent devices face variability as novel pneumatic control algorithms require additional clinical validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US External Counterpulsation Devices Market |
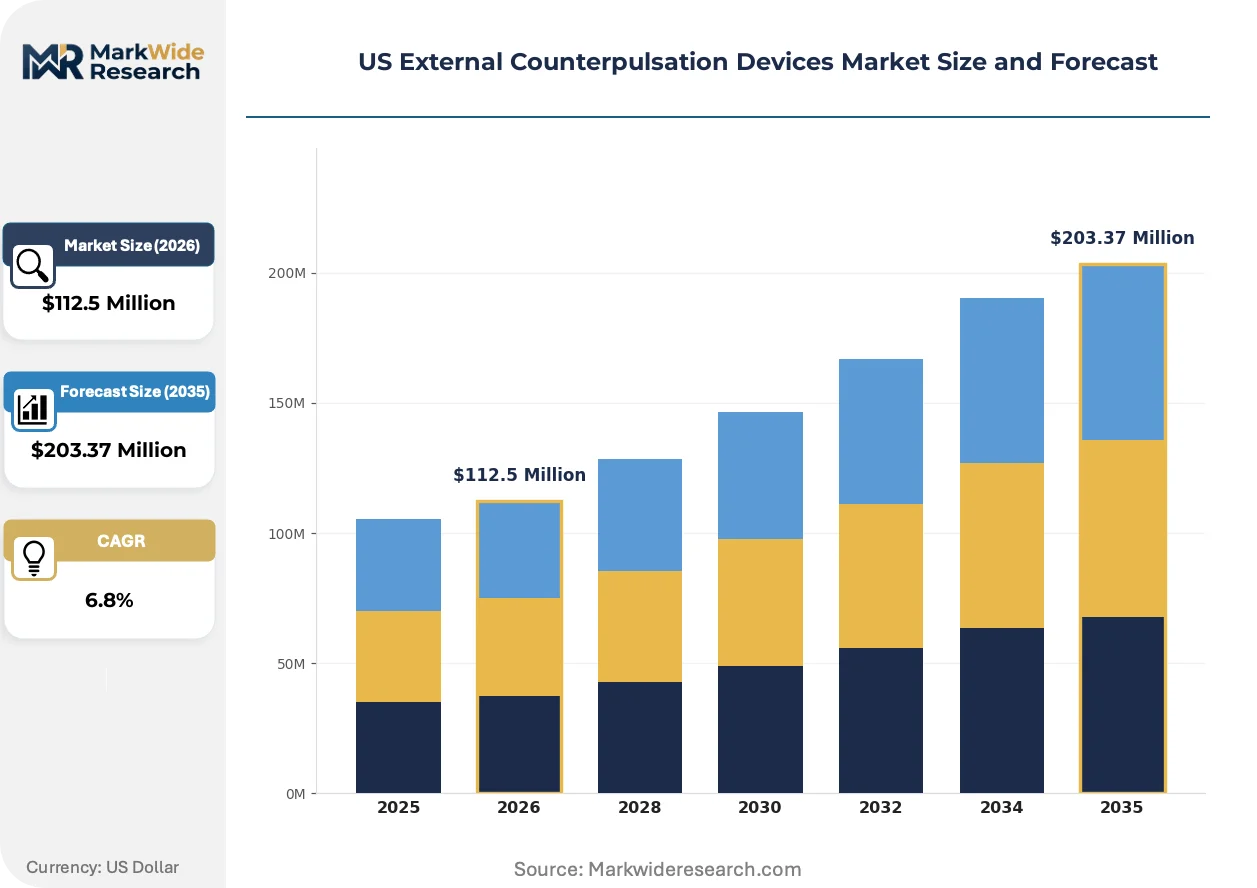
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $203.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Patient Device, Multi-Patient Device, Portable Device, Adjustable Device End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Providers Technology: Electromechanical, Biomechanical, Hybrid, Advanced Imaging Application: Cardiac Rehabilitation, Pain Management, Sports Medicine, Research |
| Companies Covered | Scottcare Corporation, Renew Group Private Limited, Vaso Corporation, St. Jude Medical, Medtronic, ACS Diagnostics, Applied Cardiac Systems, Teleflex, CardioMedics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US External Counterpulsation Devices Market Trends and Innovations
Three distinct vectors are compressing traditional treatment delivery models: pneumatic control virtualization, reimbursement policy recalibration, and procurement decentralization toward post-acute sites of care.
Electromechanical counterpulsation systems with software-defined pneumatic sequencing are virtualizing hardware-dependent timing mechanisms. Hospital outpatient departments in the Southeast are adopting these platforms to reduce on-site engineering dependency. The technology is virtualizing maintenance workflows and enabling remote pressure calibration oversight that previously required field technician dispatch.
CMS physician fee schedule rulemaking for outpatient cardiac rehabilitation add-on payments is recalibrating site-of-care economics. Hospital systems are responding by consolidating counterpulsation service lines into dedicated cardiovascular rehabilitation centers. Freestanding facilities in Midwest states with favorable Medicare administrative contractor determinations are expanding capacity fastest.
After-sales service unbundling is fragmenting traditional manufacturer-captive maintenance relationships. Independent service organizations are capturing technical training and remote monitoring contracts previously held by original equipment providers. Regional ambulatory surgical centers in cardiology-focused markets are sourcing maintenance through specialized third parties to reduce per-session overhead.
US External Counterpulsation Devices Market Segmentation
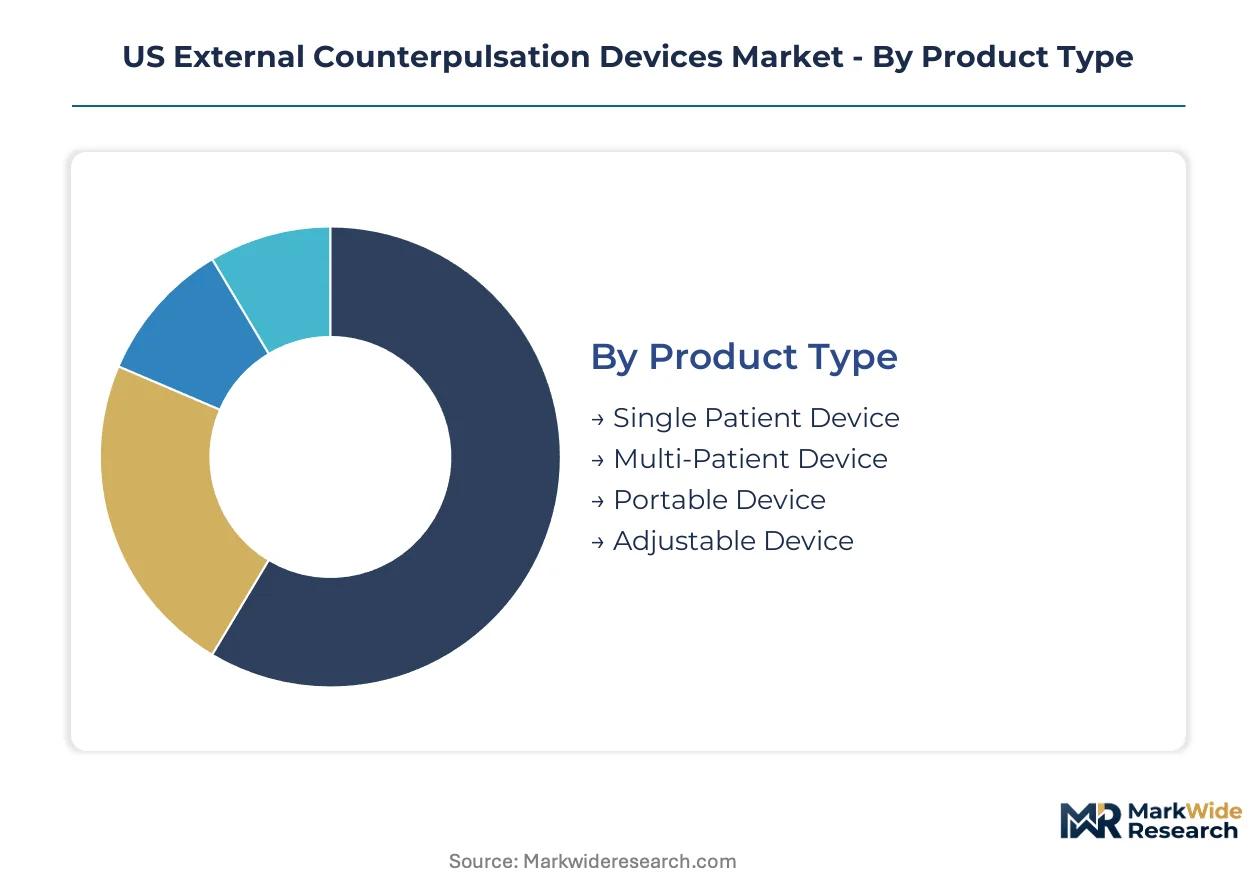
Device segmentation in the US external counterpulsation market reveals divergent capital deployment strategies across acute care and post-acute settings. Product architecture and reimbursement coding alignment determine procurement patterns more than clinical indication alone.
Product Type:
Mature hospital infrastructure favors multi-patient systems, while emerging portable platforms are capturing reimbursement traction in Medicare Advantage networks.
- Single Patient Device:Dedicated pneumatic cuff arrays with fixed calibration parameters serve high-throughput cardiac rehabilitation centers in Florida and Texas. Medicare Part B reimbursement stability concentrates procurement among hospital outpatient departments with established cardiovascular service lines.
- Multi-Patient Device:Modular pneumatic systems enable sequential patient scheduling across shared ECG-gated timing infrastructure. Southeast health systems deploy these platforms to amortize capital costs across bundled payment episodes for refractory angina populations.
- Portable Device:Compact electromechanical units with battery-backed operation are expanding into home care channels as CMS evaluates remote monitoring add-on payments.
- Adjustable Device:Programmable pressure calibration ranges accommodate variable limb circumference across diverse patient demographics in Midwest rehabilitation networks.
Multi-Patient Device retains volume leadership; Portable Device holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital systems from leaner ambulatory operators seeking per-session margin protection.
- Hospitals:Academic medical centers in the Northeast maintain the largest installed bases of electromechanical counterpulsation systems. Cardiac catheterization laboratory proximity enables rapid referral pathways for refractory angina patients failing revascularization.
- Rehabilitation Centers:Freestanding cardiovascular rehabilitation facilities in Ohio and Illinois are expanding capacity fastest under favorable Medicare administrative contractor determinations for outpatient cardiac rehabilitation.
- Clinics:Cardiology-focused ambulatory surgical centers in regional markets source maintenance through independent service organizations to reduce overhead.
- Home Care Providers:Durable medical equipment suppliers are piloting portable device distribution models pending CMS home health benefit clarifications.
Hospitals retain volume leadership; Rehabilitation Centers are climbing the fastest.
Technology:
Application requirements differentiate precision therapeutic platforms from diagnostic-adjacent systems in research settings.
- Electromechanical:Pneumatic cuff inflation systems with ECG-gated timing and five-millimeter mercury pressure calibration precision dominate clinical outcomes data for refractory angina. FDA 510(k) predicate pathways favor this established technology category.
- Hybrid:Integrated platforms combining pneumatic counterpulsation with peripheral hemodynamic monitoring are gaining traction in value-based care arrangements requiring outcome documentation.
- Biomechanical:Passive compression alternatives without active pneumatic control serve cost-constrained rehabilitation markets with lower reimbursement rates.
- Advanced Imaging:Research-focused systems incorporating real-time coronary perfusion visualization remain confined to investigative protocols at Cleveland Clinic and Mayo Clinic facilities.
Electromechanical retains volume leadership; Hybrid is gaining share fastest.
Application:
Customer type segmentation separates recurring reimbursement streams from episodic research funding.
- Cardiac Rehabilitation:Thirty-five-hour treatment protocols across seven weeks constitute the core reimbursable indication under CMS national coverage determinations. Hospital outpatient departments in Medicare-eligible populations anchor demand concentration.
- Pain Management:Off-label utilization for peripheral vascular disease symptoms is expanding in pain clinics across Texas and Arizona with favorable prior authorization patterns.
- Sports Medicine:Athletic recovery applications at university medical centers in California and North Carolina remain investigational without established reimbursement codes.
- Research:NIH-funded cardiovascular outcome studies at academic medical centers drive limited demand for advanced imaging-integrated platforms.
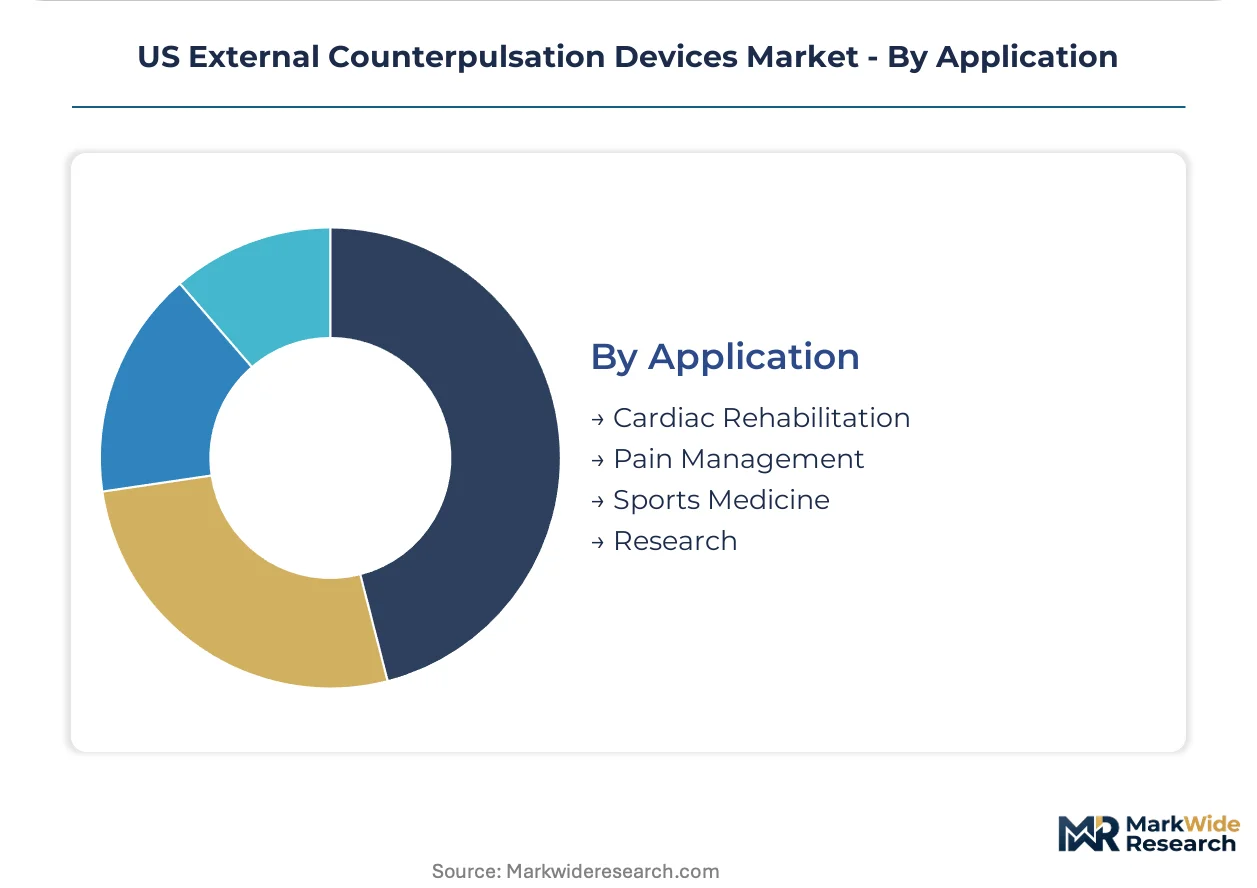
Cardiac Rehabilitation retains volume leadership; Pain Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast states deploy external counterpulsation systems predominantly through hospital outpatient departments, while Midwest networks favor freestanding rehabilitation centers under favorable Medicare administrative contractor determinations. This geographic divergence in site-of-care economics shapes capital deployment patterns across Medicare-eligible populations.
Southeast
Florida and Georgia concentrate the highest density of cardiac rehabilitation programs serving refractory angina populations. Medicare Part B reimbursement stability under CMS national coverage determinations anchors procurement in hospital outpatient departments. Tampa and Atlanta health systems maintain the largest installed bases of multi-patient electromechanical systems.
Midwest
Ohio and Illinois rehabilitation centers expand capacity fastest under favorable local coverage article interpretations for outpatient cardiac rehabilitation. CMS physician fee schedule rulemaking compresses capital acquisition timelines across Medicare administrative contractor jurisdictions. Cleveland Clinic anchors clinical validation research for hybrid technology platforms integrating peripheral hemodynamic monitoring.
Southwest
Texas pain clinics drive off-label utilization for peripheral vascular disease symptoms with favorable prior authorization patterns. FDA 510(k) clearance pathways for predicate electromechanical systems support rapid commercial deployment. Houston medical centers pilot portable device distribution models pending durable medical equipment supplier network expansions.
Northeast
Academic medical centers in Massachusetts and New York maintain proximity between cardiac catheterization laboratories and counterpulsation service lines for rapid refractory angina referrals. NIH-funded cardiovascular outcome studies at Boston and New York City facilities drive limited demand for advanced imaging-integrated research platforms.
West
California university medical centers investigate athletic recovery applications in sports medicine without established reimbursement codes. Medicare Advantage plan evaluations of remote monitoring add-on payments shape home-based rehabilitation pilot programs. Stanford and UCLA facilities concentrate biomechanical passive compression research for cost-constrained markets.
US External Counterpulsation Devices Market Competitive Landscape
Capability concentration sits with specialized service organizations; scale advantage sits with diversified medical technology conglomerates. The vendor base separates into maintenance-dependent technical training providers and capital equipment manufacturers with captive field engineering networks. Three archetypes dominate: original equipment manufacturers with integrated service arms, independent service organizations unbundling aftermarket revenue, and cardiovascular-focused ambulatory specialists. Consolidation pressures favor strategic partnerships between device manufacturers and regional rehabilitation networks; vertical integration into technical training represents the second dominant competitive move.
Within the diversified medical technology tier, Medtronic exemplifies scale-driven field engineering networks that lock in hospital maintenance contracts through extensive service coverage. Vaso Corporation occupies a position among specialized counterpulsation service providers with technical training and remote monitoring capabilities. Scottcare Corporation represents the regional service density archetype, anchoring cardiology-focused ambulatory surgical center relationships across Midwest and Southeast markets.
| Leading Market Players |
|---|
| Scottcare Corporation |
| Renew Group Private Limited |
| Vaso Corporation |
| St. Jude Medical |
| Medtronic |
| ACS Diagnostics |
| Applied Cardiac Systems |
| Teleflex |
| CardioMedics |
| Others |
Pricing and Supply Chain Analysis
Minneapolis-St. Paul anchors domestic electromechanical system assembly, where concentrated pneumatic component manufacturing capacity translates directly into pricing leverage for multi-patient device platforms serving hospital outpatient departments across the Midwest and Southeast.
Pricing Analysis
Long-term service contracts dominate procurement structures, with hospitals locking in five-year maintenance agreements that bundle technical training and remote calibration oversight. Price differentiation rests on FDA 510(k) predicate pathway status and field engineering network density, with academic medical centers showing lowest sensitivity due to bundled payment protections while freestanding rehabilitation centers face acute margin compression from Medicare administrative contractor rate variability.
Supply Chain Analysis
Export control restrictions on precision pressure sensor technology limit component flows from select East Asian manufacturing hubs, constraining domestic assembly capacity for ECG-gated timing systems. Supply chains draw from Germany for pneumatic valve arrays, Taiwan for semiconductor timing controllers, and domestic Michigan-based machine shops for cuff fabrication arrays. Single-source vulnerability concentrates in ECG synchronization chipsets, while distribution runs through GPO contracts at integrated delivery networks and direct manufacturer relationships at independent rehabilitation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital outpatient departments as health system consolidation in the Southeast and Midwest compresses vendor negotiation leverage for original equipment manufacturers.
For Market Incumbents: Build captive field engineering moats through exclusive technical certification programs that lock in rehabilitation center maintenance dependencies. Deepen backward integration into pneumatic component fabrication to offset supply concentration risks from East Asian sensor suppliers. Counter portable device substitution threats by embedding software-defined remote monitoring capabilities that require proprietary calibration protocols. For New Entrants and Emerging Players: Medicare Advantage home-based rehabilitation pilots in Florida and Texas represent the most penetrable entry point for portable device platforms pending CMS remote monitoring add-on payment finalization. Cardiology-focused ambulatory surgical centers in Ohio and Illinois offer secondary white-space opportunity through independent service organization partnerships that bypass incumbent manufacturer field engineering networks. Pursue GPO contract exclusion strategies targeting mid-size rehabilitation networks outside academic medical center orbits. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized counterpulsation service organizations with technical training and remote monitoring capabilities. Long-term viability favors acquisition targets with established Medicare administrative contractor relationships and bundled payment episode participation. Watch FDA 510(k) review cycle variability for novel pneumatic control algorithms as the signal indicating whether predicate-dependent pathways remain viable or clinical validation thresholds are tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts secure volume commitments across bundled cardiac rehabilitation episodes. |
| Reimbursement Strategy | CMS national coverage determination alignment determines addressable patient population expansion trajectories. |
| Software Companion Development | Remote monitoring platforms capture add-on payment eligibility under Medicare Advantage network evaluations. |
| Backward Integration | In-house pneumatic component production reduces dependency on East Asian pressure sensor supply concentration. |
| Technical Training Certification | Exclusive education programs create maintenance revenue streams independent of capital equipment sales cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cardiac rehabilitation program directors, biomedical engineering managers at hospital outpatient departments, GPO contracts specialists, and field service technicians at original equipment manufacturers. Secondary validation drew from FDA 510(k) premarket notification databases, CMS national coverage determination records, Medicare administrative contractor local coverage articles, and hospital procurement databases. Bottom-up installed base estimates were triangulated against top-down reimbursement claim volume analyses across the projection horizon.
Calibration approaches anchored volume and value outputs to electromechanical system replacement cycles, portable device adoption curves in Medicare Advantage networks, and site-of-care migration patterns from inpatient to ambulatory settings. Segmentation dimensions modeled included product architecture, end-user channel, technology category, and application indication. CAGRs were derived from regression analysis of historical reimbursement claim growth rates and capital equipment shipment patterns, with sensitivity testing around CMS physician fee schedule rulemaking outcomes and FDA 510(k) review cycle durations.
Practitioners should monitor CMS outpatient cardiac rehabilitation add-on payment finalization and Medicare administrative contractor coverage article updates for early signals of forecast revision triggers. Forecasts reflect assumptions regarding reimbursement stability and predicate pathway viability. Material shifts in FDA substantial equivalence requirements or Medicare national coverage determination scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurostimulation Market
Medical Devices
Organ Preservation Market
Medical Devices
Knee Braces Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Venturi Mask Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market