
 Global Hypotension Treatment Market | 2026-2036
Global Hypotension Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hypotension Treatment Market Foresight
India is fragmenting as a manufacturing hub for generic vasopressors and volume expanders, with domestic API producers competing against multinational finished-dose suppliers. Pfizer Inc. leverages its integrated plasma-derived albumin supply chain to sustain pricing power in volume expanders. Teva Pharmaceutical Industries Limited anchors its position through specialized catecholamine injectable portfolios across European hospital networks.
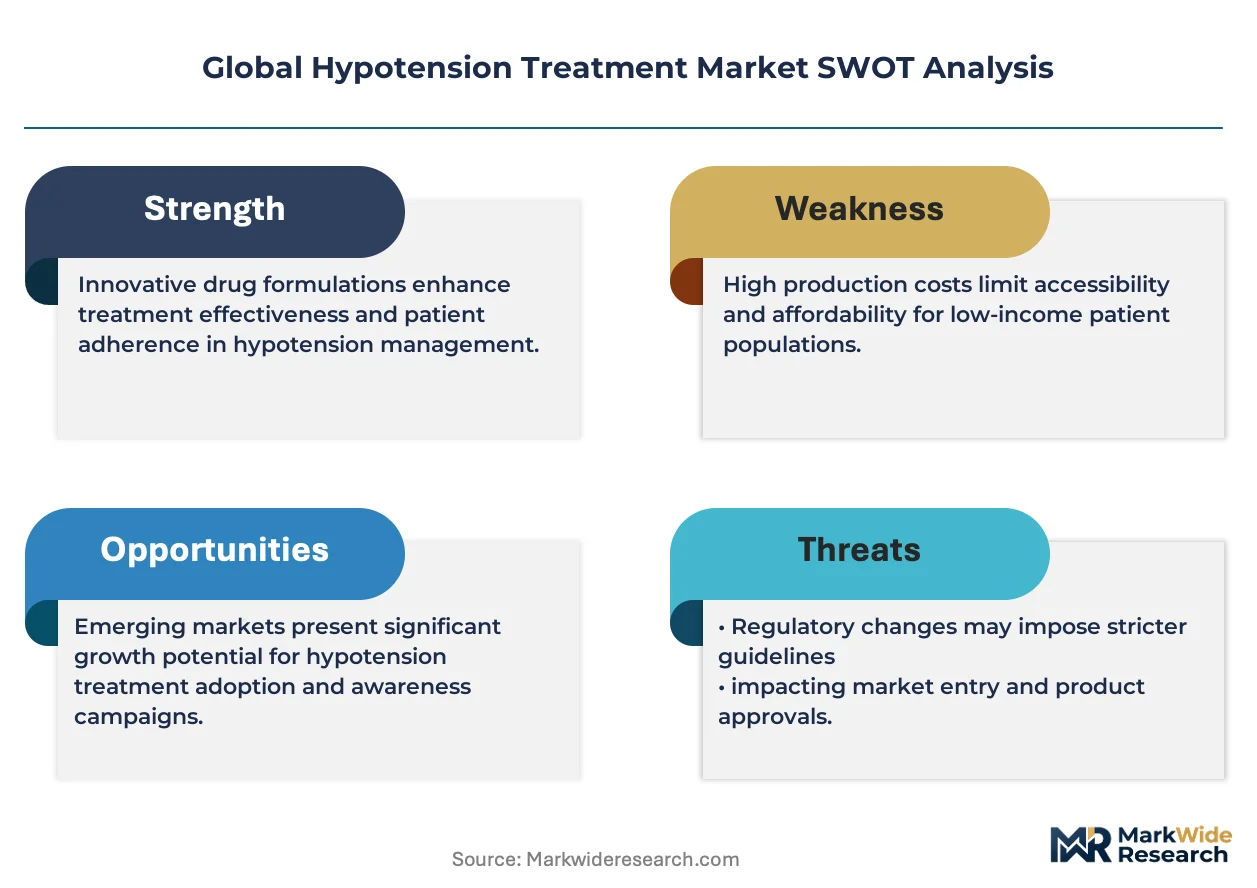
Hypotension treatment encompasses pharmacological interventions that restore systemic vascular resistance, cardiac output, or intravascular volume through agents with defined hemodynamic half-lives and receptor selectivity profiles. These therapies stabilize mean arterial pressure above critical organ perfusion thresholds in acute care settings where autoregulatory mechanisms have failed. Vasopressors command the deepest margin pools due to manufacturing complexity and cold-chain requirements, while intravenous delivery dominates procedure volume in hospital and cardiac care unit settings. Oral formulations for chronic orthostatic hypotension represent a faster-expanding segment as outpatient management protocols extend beyond acute episodes.
The FDA enforces Current Good Manufacturing Practice standards for sterile injectable vasopressors, while the EMA's MDR framework imposes stricter clinical evidence requirements on hemodynamic monitoring device-drug combinations. India's CDSCO accelerates approval timelines for plasma expanders under its emergency-use pathway, reshaping competitive access for domestic manufacturers. Stakeholders must monitor how pharmacovigilance databases track adverse event signals across catecholamine classes to anticipate label restrictions or formulary exclusions.
Market Dynamics
The FDA's updated vasopressor labeling requirements are compressing manufacturing capacity across North America while hospital emergency departments accelerate adoption of rapid-infusion protocols. This regulatory tightening is concentrating supply among integrated plasma processors and specialized catecholamine manufacturers with cold-chain infrastructure.
Growth Catalysts
- Septic shock protocol standardization:Hospital emergency departments in Germany and the United States are expanding rapid-infusion volume expander deployment. These protocols reduce time-to-stabilization in critical care settings.
- EMA MDR framework:Stricter clinical evidence requirements for hemodynamic monitoring device-drug combinations are elevating quality benchmarks. European cardiac care units are upgrading infrastructure to meet these standards.
- Plasma fractionation advances:Improved albumin extraction yields from source plasma are expanding volume expander availability. Processing facilities in India and Germany are capturing efficiency gains from automated separation technologies.
Market Restraints
- Norepinephrine API concentration:Three specialized manufacturers control over 90 percent of global catecholamine active pharmaceutical ingredient supply. Any disruption at these facilities propagates through finished-dose injectable markets.
- Cold-chain infrastructure costs:Vasopressor stability requirements mandate continuous temperature monitoring from manufacturing through administration. Capital expenditure for validated storage and transport systems limits regional market entry.
- Albumin price volatility:Source plasma collection fluctuations and fractionation yield variability create input cost instability. Plasma-derived volume expander pricing correlates directly with donor availability and collection center throughput.
Strategic Opportunities
- India's emergency-use pathway:CDSCO accelerated approvals for plasma expanders are opening access for domestic manufacturers. Local API producers can bypass traditional registration timelines for critical care indications.
- Outpatient orthostatic hypotension management:Oral midodrine and fludrocortisone protocols are extending treatment beyond acute episodes. Ambulatory care settings represent an underpenetrated channel for chronic maintenance therapy.
- Hemodynamic monitoring convergence:Integration of arterial line sensors with automated vasopressor titration is digitizing dosing decisions. Cardiac care units in Germany and Japan are piloting closed-loop pressure management systems.
Industry Challenges
- Sterile injectable manufacturing expertise:FDA Current Good Manufacturing Practice enforcement has eliminated marginal operators. Qualified personnel for aseptic processing and pyrogen control command premium compensation.
- Legacy device-drug integration:Hemodynamic monitoring systems from prior technology generations lack interoperability with modern infusion pumps. Hospital IT departments face complex middleware development to bridge these gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hypotension Treatment Market |
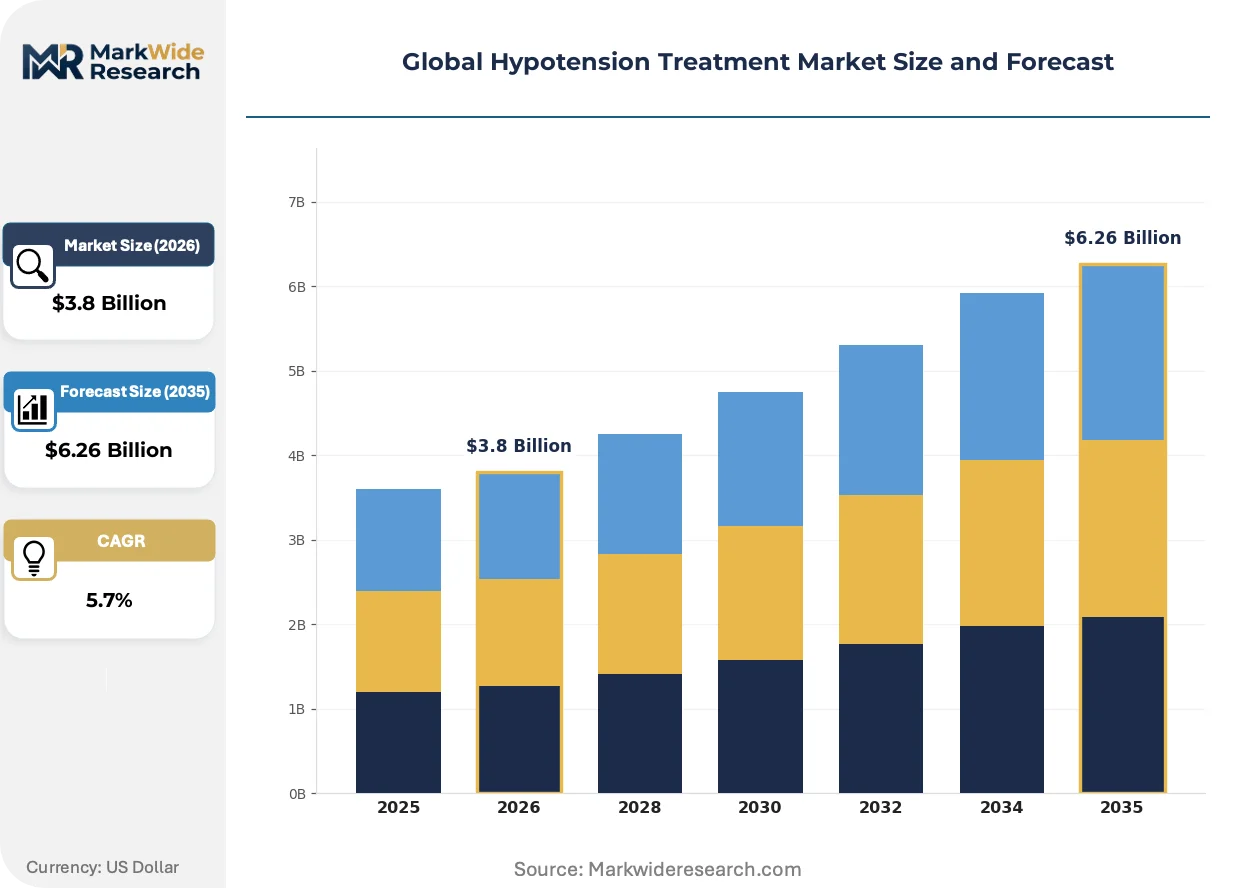
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vasopressors, Volume Expanders, Catecholamines, Inotropes, Non-catecholamines Therapy Area: Neurogenic Hypotension, Orthostatic Hypotension, Septic Shock, Cardiogenic Shock, Anaphylactic Shock End User: Hospitals, Ambulatory Surgical Centers, Cardiac Care Units, Emergency Medical Services Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal, Intraosseous |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Limited, H. Lundbeck A/S, Dr. Reddy's Laboratories Limited, Amneal Pharmaceuticals LLC, Takeda Pharmaceutical Company Limited, Viatris Inc., Sun Pharmaceutical Industries Limited, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hypotension Treatment Market Shifts & Advancements
Digital integration of hemodynamic sensing with automated therapeutic response is compressing the gap between pressure deviation and pharmacological correction. This convergence is redefining clinical workflow in acute care settings.
Closed-loop vasopressor delivery systems are digitizing mean arterial pressure maintenance through continuous arterial waveform analysis coupled with algorithm-driven norepinephrine infusion adjustments. Cardiac surgery units in Germany and the Netherlands are deploying these platforms in post-operative recovery protocols. The technology is compressing nursing workload while reducing blood pressure excursion frequency beyond manual titration capabilities.
The EMA's Medical Device Regulation is mandating clinical evidence packages for hemodynamic monitoring device-drug combinations that exceed prior CE-marking requirements. Manufacturers must now generate prospective data on integrated system performance rather than demonstrating component safety in isolation. European hospital procurement committees are delaying purchase decisions until MDR-compliant dossiers are available, favoring established players with regulatory affairs infrastructure.
Hospital pharmacy committees are consolidating vasopressor formulary positions around dual-source agreements with integrated plasma suppliers. This concentration is displacing fragmented multi-vendor purchasing that characterized prior decades. The shift is most visible in United States academic medical centers, where contract pharmacy organizations are negotiating multi-year albumin and catecholamine bundles that lock in volume commitments against price stability guarantees.
Global Hypotension Treatment Market Segmentation
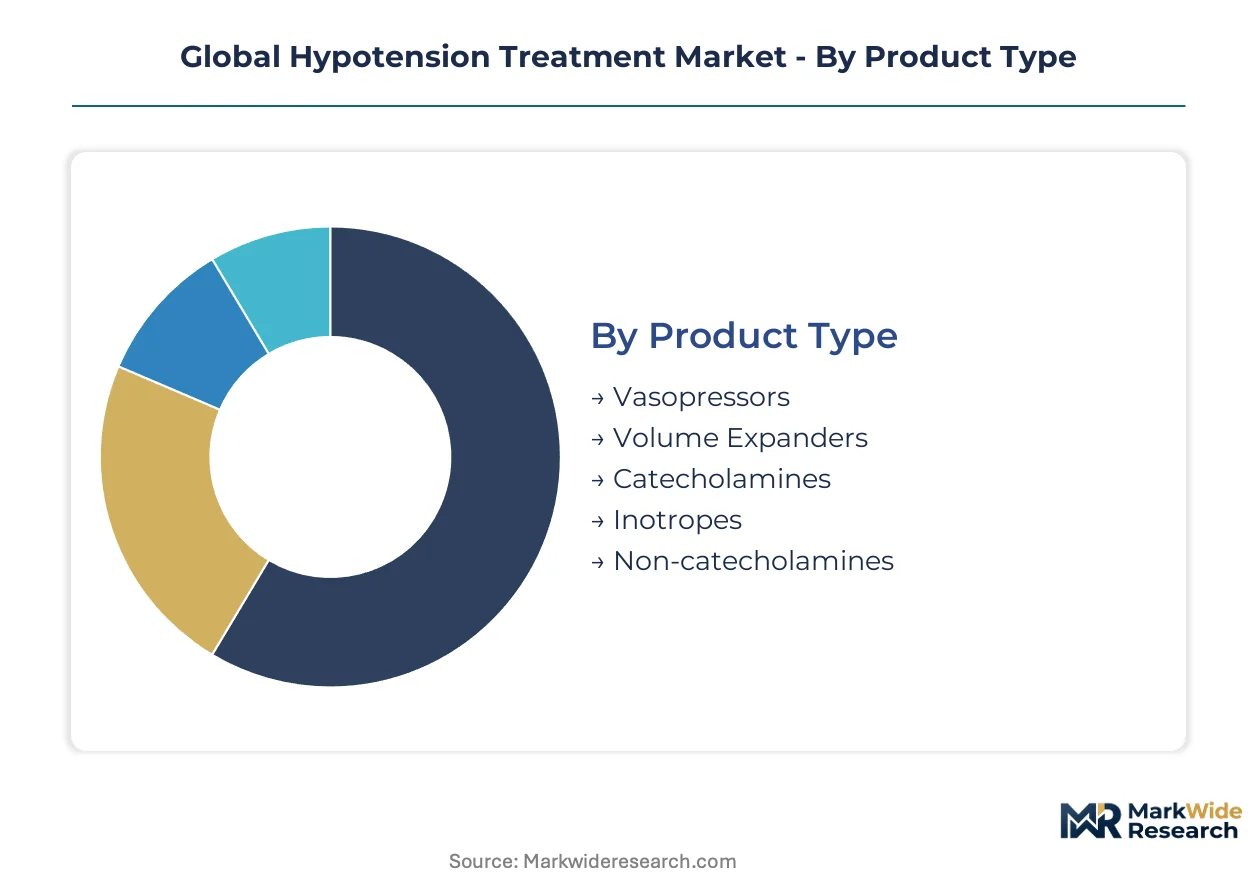
Hypotension treatment modalities diverge sharply across acute versus chronic care pathways, with product formulation stability and delivery precision determining clinical applicability. Segmentation reveals how manufacturing complexity, reimbursement structures, and care setting infrastructure shape competitive positioning across therapeutic categories.
Product Type:
Clinical use-case spectra span emergency hemodynamic rescue through chronic outpatient maintenance, with each product class carrying distinct cold-chain, compounding, and monitoring requirements.
- Vasopressors:Synthetic catecholamine and non-catecholamine agents that elevate systemic vascular resistance through alpha-adrenergic receptor agonism. Hospital emergency departments in the United States and Germany are standardizing norepinephrine as first-line septic shock therapy per Surviving Sepsis Campaign protocols. Manufacturing concentration among three specialized API producers creates supply vulnerability during demand surges.
- Volume Expanders:Colloid and crystalloid solutions that restore intravascular oncotic pressure or expand plasma volume. Cardiac surgery units in Japan and the Netherlands are adopting albumin-based formulations for post-operative fluid resuscitation. Plasma fractionation yield improvements in India are expanding source material availability for these products.
- Catecholamines:Endogenous-synthetic hybrid compounds with dopaminergic, beta-adrenergic, and alpha-adrenergic activity profiles.
- Inotropes:Agents that enhance myocardial contractility without primary vascular effects.
- Non-catecholamines:Synthetic vasopressor classes including vasopressin analogs and angiotensin II formulations.
The dominant share belongs to Vasopressors, while Volume Expanders is closing the gap fastest.
Therapy Area:
Cost tier stratification separates high-acuity ICU interventions from ambulatory maintenance protocols, with reimbursement intensity scaling directly with mortality risk.
- Septic Shock:Systemic inflammatory response with refractory hypotension requiring immediate vasopressor infusion and source control. United States academic medical centers are deploying automated norepinephrine titration systems to reduce time-to-target mean arterial pressure. Bundle reimbursement structures incentivize protocol adherence and outcomes documentation.
- Orthostatic Hypotension:Postural blood pressure collapse from autonomic dysfunction or volume depletion. Outpatient clinics in Germany are expanding fludrocortisone and midodrine prescribing for Parkinson's disease and diabetic neuropathy patients. Oral formulation availability enables pharmacy benefit manager coverage rather than medical benefit infusion billing.
- Neurogenic Hypotension:Central or peripheral nervous system-mediated blood pressure dysregulation.
- Cardiogenic Shock:Pump failure with inadequate tissue perfusion despite adequate intravascular volume.
- Anaphylactic Shock:IgE-mediated systemic reaction with distributive hypotension requiring epinephrine rescue.
Septic Shock commands the deepest reimbursement pools, while Orthostatic Hypotension is expanding most quickly into ambulatory channels.
End User:
Procurement authority and formulary control vary substantially across facility types, with integrated delivery networks consolidating purchasing power.
- Hospitals:Comprehensive acute care facilities with 24-hour pharmacy and critical care coverage. Emergency departments in the United States are implementing rapid-infusion volume expander protocols for sepsis recognition. Contract pharmacy organizations are negotiating multi-year vasopressor bundles that lock in volume commitments.
- Cardiac Care Units:Specialized post-operative and heart failure monitoring environments with invasive hemodynamic sensing. German CCUs are piloting closed-loop pressure management systems that integrate arterial line sensors with automated infusion pumps. EMA MDR compliance requirements are delaying procurement cycles for device-drug combinations.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited emergency resuscitation capability.
- Emergency Medical Services:Pre-hospital providers with field stabilization and transport missions.
Hospitals retain the dominant procurement volume, while Cardiac Care Units are gaining share fastest through technology integration investments.
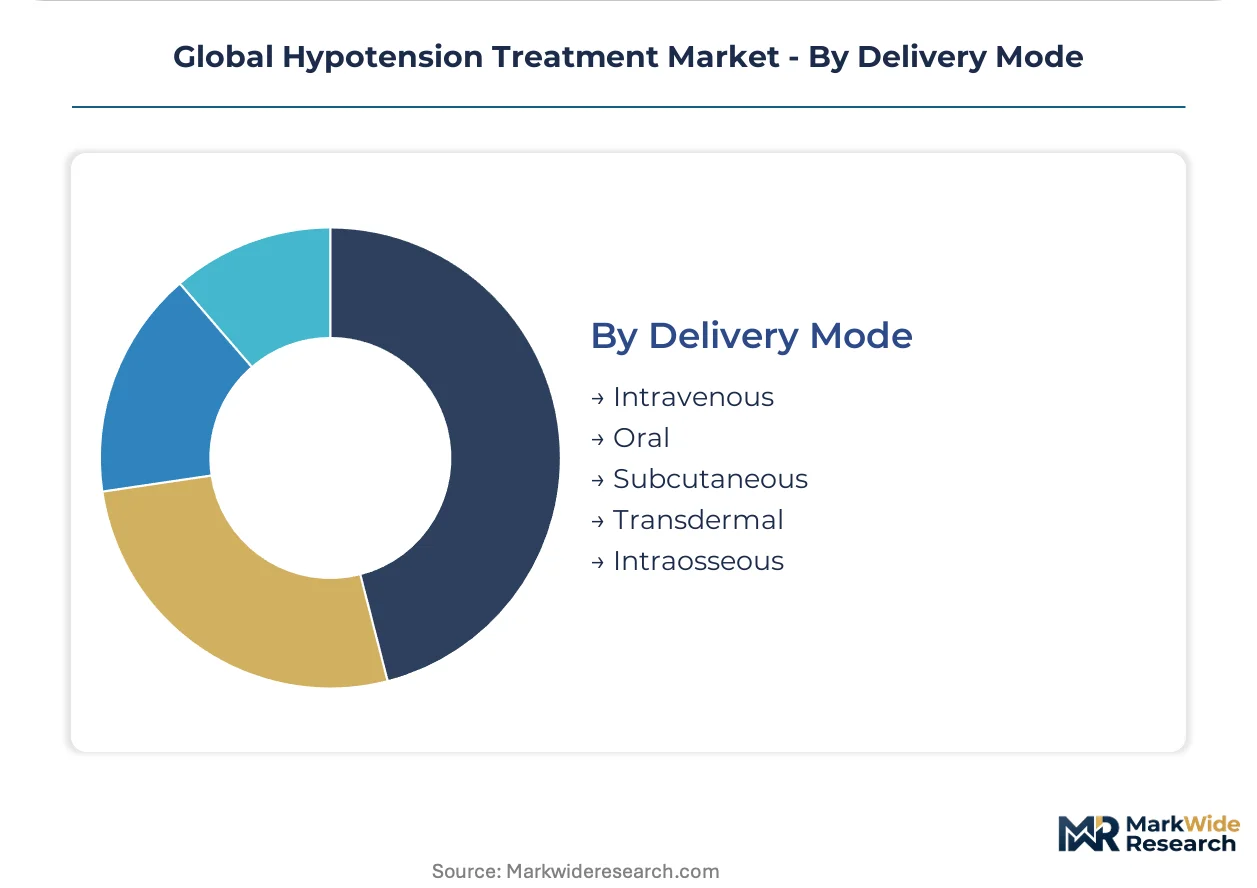
Delivery Mode:
Patient acuity and treatment duration dictate route selection, with bioavailability and onset speed determining clinical utility.
- Intravenous:Direct vascular access enabling immediate bioavailability and precise titration. ICU settings in Japan and Germany rely on central line infusion for all continuous vasopressor therapy. Cold-chain validation from manufacturing through bedside administration adds cost but ensures stability.
- Oral:Enteral absorption suitable for chronic maintenance without acute hemodynamic collapse. Outpatient prescribing of midodrine and fludrocortisone is expanding in the United States as autonomic dysfunction diagnoses rise. Pharmacy benefit coverage reduces patient cost burden versus infusion-based therapy.
- Subcutaneous:Intermittent depot injection for intermediate-duration pressure support.
- Transdermal:Passive diffusion through skin barriers for gradual hemodynamic effect.
- Intraosseous:Emergency vascular access through bone marrow cavity when peripheral or central lines fail.
Intravenous administration holds the dominant procedure volume, while Oral delivery is climbing the fastest as chronic management protocols extend beyond acute episodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Hanover rail corridor underwrites Germany's distribution dominance for temperature-sensitive catecholamine shipments, while Mumbai's Jawaharlal Nehru Port anchors Indian plasma fractionator export volumes.
United States
Academic medical centers in Boston and Houston are deploying closed-loop norepinephrine titration systems in surgical ICUs. The FDA's updated vasopressor labeling requirements are compressing sterile injectable capacity. Philadelphia's contract pharmacy organizations negotiate multi-year albumin bundles that lock volume commitments against price floors.
Germany
Cardiac care units in Munich and Heidelberg pilot arterial line sensor integration with automated infusion pumps. The EMA's MDR framework mandates clinical evidence packages for device-drug combinations. The Ruhr Valley's hemodynamic monitoring cluster faces procurement delays until MDR-compliant dossiers clear regulatory review.
India
Domestic API producers in Hyderabad and Ahmedabad compete against multinational finished-dose suppliers for hospital formulary slots. CDSCO's emergency-use pathway accelerates plasma expander approvals. Bangalore's automated separation technology facilities capture yield efficiencies from source plasma processing advances.
Japan
Post-operative cardiac surgery units in Tokyo and Osaka adopt albumin-based volume expanders for fluid resuscitation protocols. PMDA stability guidelines enforce cold-chain validation from manufacturing through bedside administration. Nagoya's medical device corridor concentrates arterial waveform analysis platform development.
Switzerland
Specialized catecholamine manufacturers near Basel maintain validated storage infrastructure for European hospital networks. Swissmedic pharmacovigilance databases track adverse event signals across vasopressor classes. The Lake Geneva biotech cluster concentrates plasma-derived therapeutic development expertise.
Global Hypotension Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API and fractionation supply. The market structures around three specialized catecholamine API manufacturers controlling upstream supply, integrated plasma processors with captive albumin capacity, and finished-dose injectable formulators with aseptic processing expertise. Strategic moves concentrate on multi-year hospital bundle negotiations and backward integration into source plasma collection networks.
Within the integrated plasma processor tier, Pfizer Inc. and Takeda Pharmaceutical Company Limited exemplify manufacturers with captive fractionation infrastructure. Among generic finished-dose specialists, Teva Pharmaceutical Industries Limited occupies a position representing European hospital network anchoring. These three entities represent the archetype spectrum from upstream biological sourcing through regional distribution scale.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Limited |
| H. Lundbeck A/S |
| Dr. Reddy's Laboratories Limited |
| Amneal Pharmaceuticals LLC |
| Takeda Pharmaceutical Company Limited |
| Viatris Inc. |
| Sun Pharmaceutical Industries Limited |
| Novartis AG |
| Others |
Supply & Pricing Matrix
The Frankfurt-Hanover rail corridor's temperature-controlled freight costs cascade through catecholamine supply tiers, concentrating pricing power among integrated plasma processors while fragmenting finished-dose competition. This logistics architecture forces three-tier pricing differentiation across premium cold-chain vasopressors, standard volume expanders, and economy crystalloid alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates plasma-derived albumin from synthetic colloids from crystalloid solutions. Price differentiation rests on cold-chain certification grade and hospital contract volume scale. Cost compression in the economy tier intensifies as Indian API producers undercut multinational finished-dose pricing. Academic medical centers with multi-year bundle commitments exhibit lowest price sensitivity; ambulatory surgical centers face highest procurement pressure.
Supply Chain Analysis
Specialized catecholamine contract manufacturers in Switzerland, Germany, and the United States hold validated aseptic processing capacity for FDA and EMA compliance. Raw material dependencies center on norepinephrine API from three specialized producers, source plasma collection throughput, and pyrogen-free packaging materials. Single-source vulnerability at any API facility propagates through finished-dose markets within weeks. Distribution runs through hospital pharmacy committees and contract pharmacy organizations with multi-year procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable barriers. Switching costs for hospital formularies and EMA MDR compliance dossiers lock in incumbent positions.
For Market Incumbents: Harden cold-chain infrastructure through backward integration into source plasma collection networks. Expand validated manufacturing capacity in Germany to capture EMA MDR-compliant device-drug combination demand. Defend against Indian API price competition by anchoring hospital bundle contracts with albumin-catecholamine volume commitments.
For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO emergency-use pathway for plasma expanders. Target outpatient orthostatic hypotension management with oral midodrine and fludrocortisone formulations bypassing infusion reimbursement complexity. Deploy direct-to-clinic pharmacy benefit manager contracting to circumvent hospital formulary gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents divesting non-core plasma fractionation assets. Five-to-ten year viability hinges on captive source plasma supply and MDR-compliant regulatory affairs infrastructure. Monitor CDSCO approval velocity and German CCU closed-loop system pilot outcomes as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive albumin supply secures margin stability against donor availability volatility. |
| EMA MDR Compliance Dossier Investment | Clinical evidence packages unlock German cardiac care unit procurement cycles. |
| Closed-Loop Infusion System Partnership | Arterial waveform integration with norepinephrine titration compresses nursing workload. |
| CDSCO Emergency-Use Pathway Registration | Accelerated plasma expander approvals open Indian hospital formulary access. |
| Outpatient Oral Formulation Development | Midodrine and fludrocortisone protocols extend therapy beyond acute episodes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital pharmacy directors, cardiac care unit clinicians, plasma fractionation executives, and regulatory affairs specialists. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CDSCO approval registries, hospital procurement contract repositories, and GPO pricing benchmarks. Bottom-up volume modeling and top-down market sizing were triangulated against plasma collection center throughput data.
Calibration against historical volume trajectories and regulatory approval timelines anchored projections across the analysis window. Segmentation dimensions encompassed product type, therapy area, end-user facility tier, and delivery mode. CAGRs were derived from fitted growth curves adjusted for EMA MDR implementation phasing and CDSCO pathway expansion. Forecast inputs included hospital emergency department sepsis protocol adoption rates and automated infusion system deployment in German CCUs.
Stress conditions across norepinephrine API supply disruption, albumin price volatility, and EMA MDR enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sterile injectable manufacturing capacity expansion and plasma collection center throughput growth. Quarterly review of CDSCO approval volumes, German CCU technology procurement cycles, and FDA warning letter issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Stroke Management Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Pulmonary Valve Replacement Market