
 Bifurcation Lesions Market | 2026-2036
Bifurcation Lesions Market Size, Share, and Industry Trends Forecast 2026-2036
Bifurcation Lesions Market Intelligence
CE marking under the EU Medical Device Regulation is unwinding competitive access across European territories, forcing portfolio reallocations among manufacturers. Boston Scientific Corporation leverages its Synergy stent platform to sustain leadership in dedicated bifurcation systems. Abbott anchors its position through structural heart and coronary portfolios that compete across multiple lesion morphologies. Medtronic differentiates via integrated cath lab ecosystems that extend beyond standalone devices into procedure optimization.
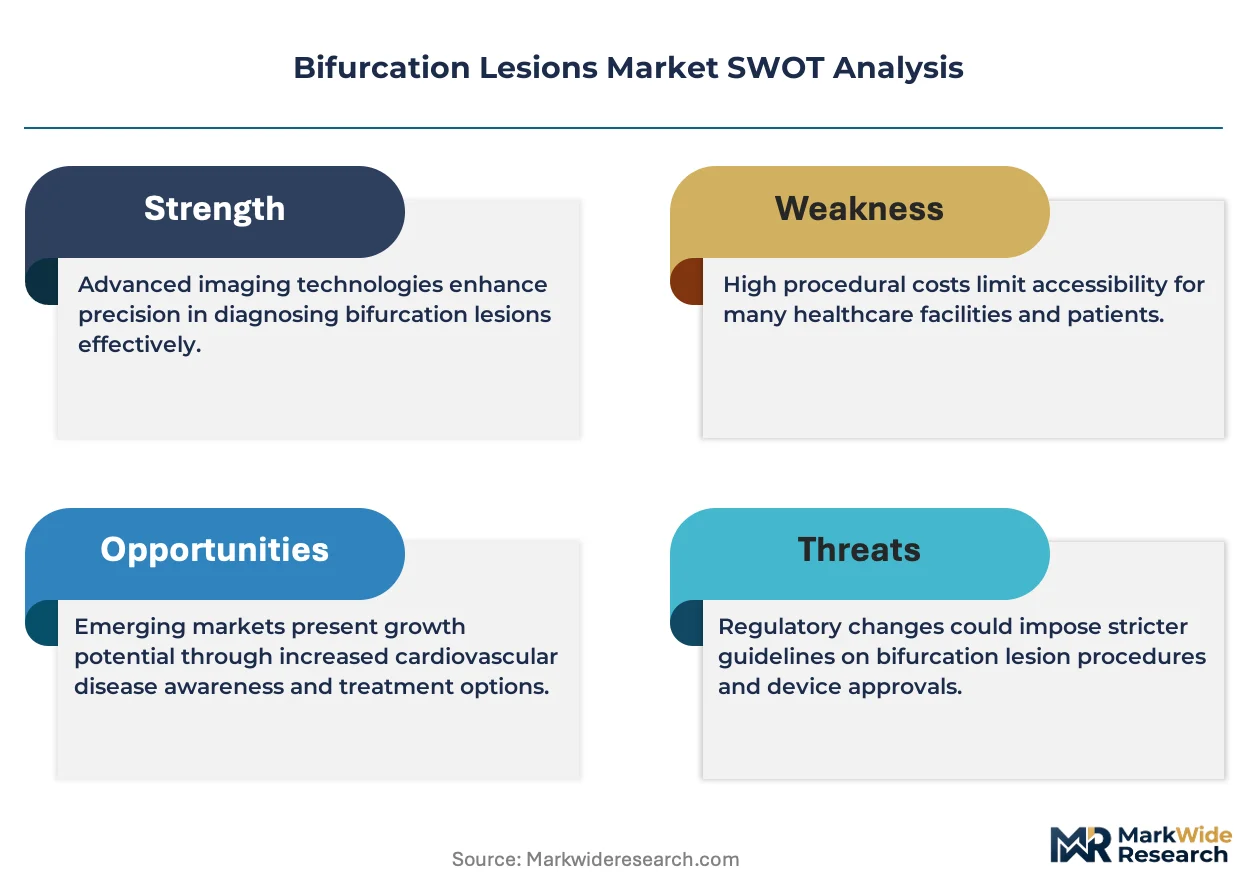
Bifurcation lesions represent coronary artery narrowings occurring at vessel branch points where a parent artery divides into two daughter branches, typically classified by the Medina system based on involvement of the proximal main vessel, distal main vessel, and side branch. These lesions require specialized interventional techniques because standard angioplasty approaches risk side branch occlusion, with treatment selection depending on bifurcation angle, vessel diameter ratios, and plaque distribution. Drug-eluting balloons within the technology segment are gaining fastest procedural traction as operators seek to reduce dual antiplatelet therapy duration compared with metallic stent strategies. Stents retain the largest installed revenue base across product types, though bioabsorbable platforms face reimbursement headwinds that compress margin pools in elective settings. Hospitals dominate end user demand, yet surgical centers are capturing share in straightforward cases where same-day discharge protocols apply.
The FDA's premarket approval requirements and the EU MDR's clinical evidence mandates shape trial design investments and market entry sequencing for novel bifurcation platforms. Japan's PMDA maintains distinct pharmacokinetic standards for drug-eluting devices that add country-specific development costs. Stakeholders must monitor evolving randomized trial data comparing provisional versus two-stent techniques, as practice guideline updates will redirect procurement priorities regardless of individual product performance claims.
Market Dynamics
Hospital-based interventional cardiology programs are consolidating purchasing power around dedicated bifurcation stenting systems, compressing vendor margins while elevating clinical evidence requirements for device selection.
Growth Catalysts
- Complex PCI volume concentration:The United States, Germany, and Japan maintain the highest procedural densities for bifurcation interventions, creating concentrated demand pools that justify specialized device development.
- Drug-eluting balloon protocols:Operators are expanding use of drug-eluting balloons to reduce dual antiplatelet therapy duration, pulling procedural share from metallic stent strategies.
- CE marking pathway evolution:The EU Medical Device Regulation's premarket notification requirements are filtering out undercapitalized competitors, tightening competitive access for surviving manufacturers.
Market Restraints
- Bioabsorbable platform reimbursement:Payers in elective settings are compressing margin pools for bioabsorbable stents through restricted coverage policies.
- Japan PMDA pharmacokinetic standards:Country-specific development costs for drug-eluting devices add regulatory friction that delays market entry sequencing.
- Two-stent technique complexity:Technical limitations in provisional versus dual-stent randomized trial data create clinical uncertainty that slows protocol standardization.
Strategic Opportunities
- Surgical center same-day discharge:Ambulatory settings are capturing share in straightforward bifurcation cases where streamlined protocols apply.
- Integrated cath lab ecosystems:Procedure optimization platforms that extend beyond standalone devices into workflow management represent expansion white space.
- Randomized trial evidence generation:Guideline updates comparing stenting techniques will redirect procurement priorities toward sponsors with robust clinical programs.
Industry Challenges
- EU MDR clinical evidence mandates:The expanded requirements for CE marking are extending certification timelines and increasing trial design investments.
- Operator technique standardization:Skill gaps in bifurcation-specific wiring and stent deployment techniques limit adoption velocity in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bifurcation Lesions Market |
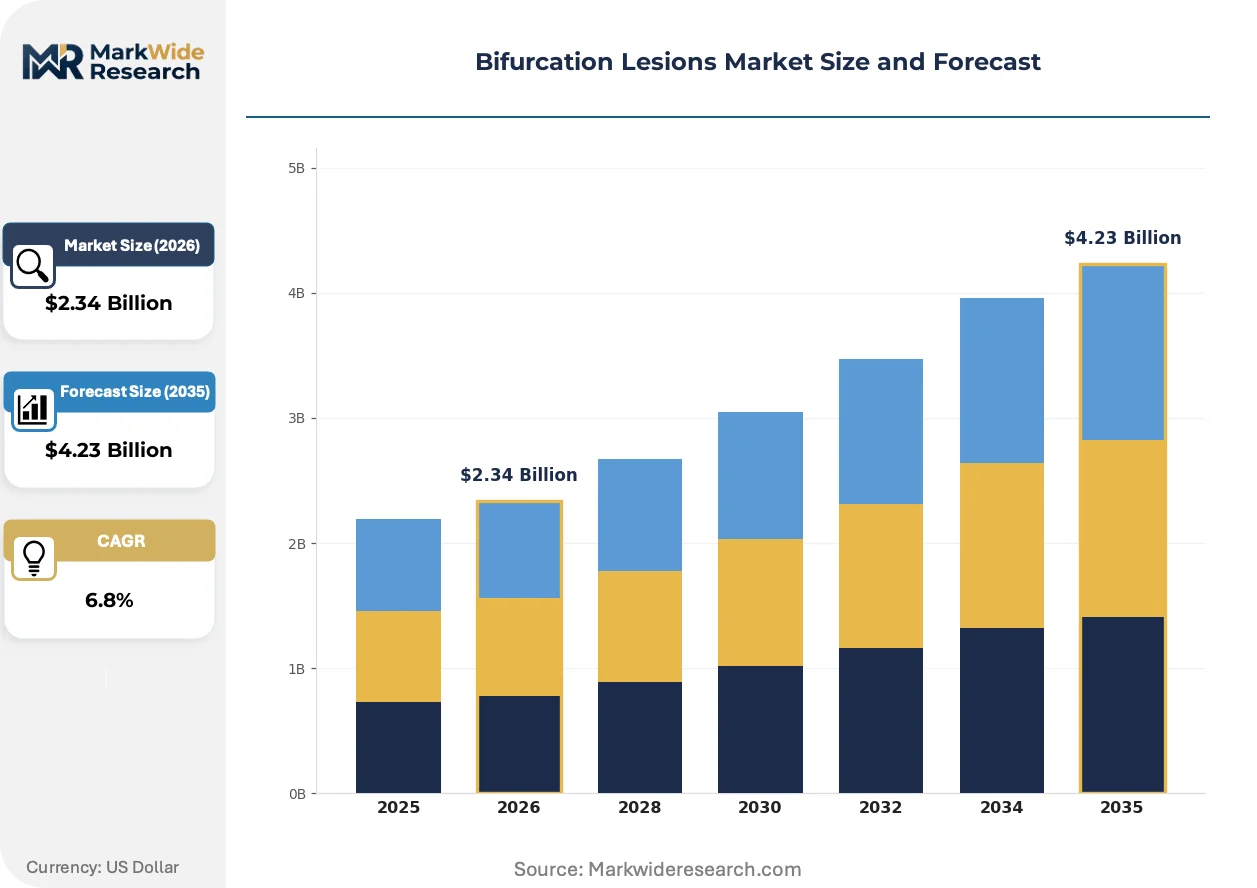
| Market Size in 2026 | $2.34 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
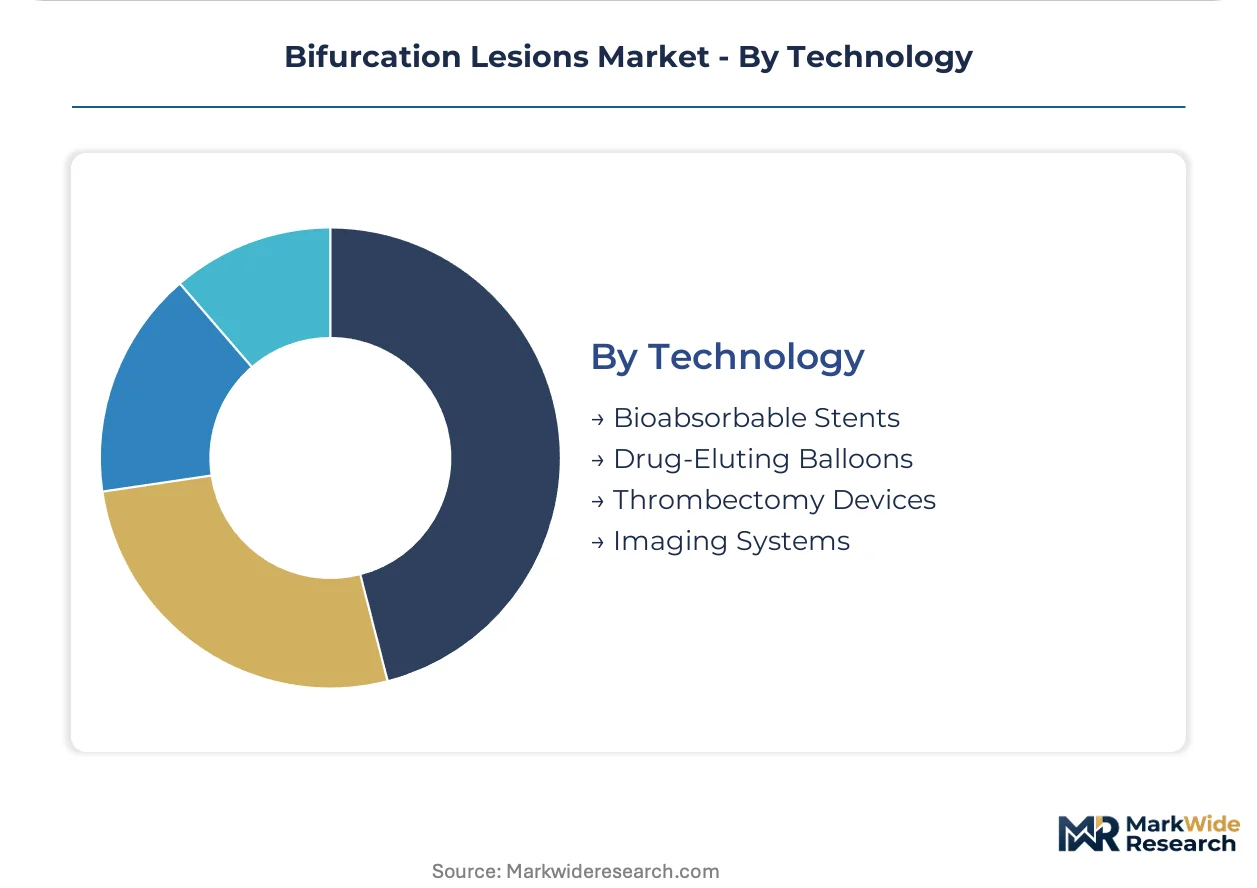
| Segmentation | Product Type: Stents, Balloons, Guidewires, Implants Application: Coronary Interventions, Peripheral Procedures, Endovascular Surgery, Cardiac Electrophysiology End User: Hospitals, Surgical Centers, Cardiology Clinics, Research Institutions Technology: Bioabsorbable Stents, Drug-Eluting Balloons, Thrombectomy Devices, Imaging Systems |
| Companies Covered | Boston Scientific Corporation, Abbott, Medtronic, Cardinal Health, Terumo Corporation, Johnson & Johnson Services, Inc., C. R. Bard, Inc., Spectranetics, Cook Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bifurcation Lesions Market Strategic Shifts & Innovations
Device manufacturers are repositioning around procedural workflow integration rather than standalone product performance, embedding software and optimization tools into hardware platforms.
Drug-eluting balloon technology is bifurcating treatment pathways for bifurcation lesions. Interventional cardiologists in high-volume European centers are adopting these platforms for side-branch management at accelerating rates. The technology is bifurcating the historical stent-dominated market into lesion-specific strategies that reduce long-term pharmaceutical burden.
EU Medical Device Regulation enforcement is tightening market access conditions for novel coronary platforms. Manufacturers must now submit expanded clinical evidence packages that satisfy notified body scrutiny. Smaller device sponsors are withdrawing from European territories rather than absorbing compliance costs, concentrating competitive presence among well-capitalized incumbents.
Hospital procurement committees are consolidating vendor relationships around full-procedure contracts rather than transactional device purchasing. Integrated supply agreements that bundle stents, balloons, and optimization software are displacing category-specific tenders. This concentration is most visible in United States academic medical centers where value-based care metrics influence supplier selection.
Bifurcation Lesions Market Segmentation
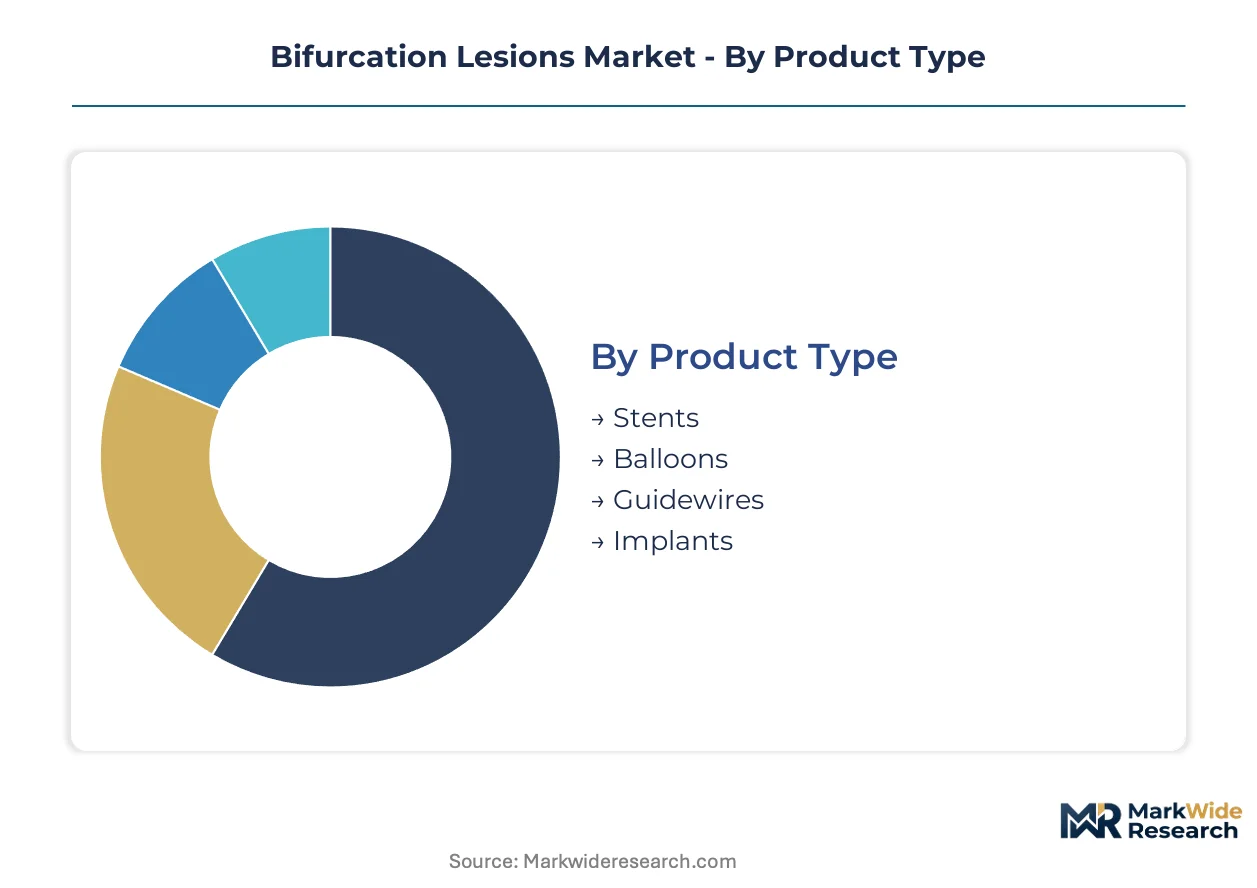
Bifurcation lesion treatment pathways diverge sharply based on lesion complexity and care setting economics. Device selection cascades through procurement hierarchies that prioritize clinical evidence, reimbursement coverage, and operator training infrastructure.
Product Type:
Stents dominate hospital purchase orders through bundled cath lab contracts, while balloons penetrate ambulatory channels via procedure-specific tenders.
- Stents:Metallic platforms with polymer-based drug delivery systems remain the revenue anchor for interventional cardiology programs. United States academic medical centers concentrate demand around thin-strut cobalt-chromium designs with biodegradable polymer coatings.
- Balloons:Drug-eluting balloon catheters are gaining procedural traction in German and Japanese high-volume centers seeking to reduce dual antiplatelet therapy burden. Operators deploy these for side-branch management in provisional stenting protocols.
- Guidewires:Hydrophilic-coated and polymer-jacketed wires enable access to angulated side branches.
- Implants:Dedicated bifurcation stent systems include Y-shaped and modular designs for complex anatomy.
By volume, stents lead. By growth pace, balloons are expanding most quickly.
Application:
Coronary interventions absorb the majority of device development investment due to procedural volume concentration and reimbursement stability.
- Coronary Interventions:Percutaneous coronary intervention for left main and distal bifurcations drives dedicated device innovation. Complex PCI programs in Germany and Japan generate concentrated demand for specialized stenting systems.
- Peripheral Procedures:Iliac and femoral bifurcation treatments utilize adapted coronary technologies with larger diameter specifications.
- Endovascular Surgery:Aortic and visceral vessel bifurcations require covered stent grafts and branched endografts.
- Cardiac Electrophysiology:Pulmonary vein isolation and left atrial appendage closure involve bifurcation-adjacent anatomy.
Coronary applications command the largest installed base. Peripheral procedures are climbing the fastest as vascular programs expand.
End User:
Hospital procurement committees consolidate purchasing power through integrated supply agreements that span multiple device categories.
- Hospitals:Tertiary cardiac centers perform the majority of complex bifurcation cases requiring two-stent techniques and intravascular imaging. United States hospital systems negotiate multi-year contracts with stent manufacturers.
- Surgical Centers:Ambulatory settings capture straightforward cases where same-day discharge protocols apply. German outpatient clinics increasingly perform provisional stenting with drug-eluting balloons.
- Cardiology Clinics:Office-based labs handle diagnostic angiography and low-complexity interventions.
- Research Institutions:Academic medical centers conduct randomized trials comparing stenting strategies.
Hospitals retain the dominant volume position. Surgical centers are gaining share fastest as ambulatory reimbursement expands.
Technology:
Technology selection tracks directly to dual antiplatelet therapy duration goals and vessel remodeling objectives.
- Drug-Eluting Balloons:Paclitaxel-coated balloons deliver antiproliferative agents without permanent metallic scaffolding. European operators are adopting these platforms for side-branch treatment at accelerating rates.
- Bioabsorbable Stents:Polymeric and metallic scaffolds designed for complete vessel restoration face reimbursement compression in elective settings. Japanese PMDA pharmacokinetic standards add development cost layers.
- Thrombectomy Devices:Aspiration catheters and mechanical thrombectomy systems manage bifurcation thrombus.
- Imaging Systems:Intravascular ultrasound and optical coherence tomography guide stent sizing and optimization.
Imaging systems anchor procedure volume. Drug-eluting balloons represent the steepest expansion trajectory as operators seek pharmaceutical burden reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in high-volume cardiac centers drive concentrated demand for dedicated bifurcation systems. Complex PCI programs cluster in territories with mature interventional cardiology infrastructure and favorable device reimbursement pathways.
United States
Academic medical centers in Cleveland Clinic and Mayo Clinic networks perform the highest density of left main bifurcation cases requiring two-stent techniques. FDA premarket notification pathways shape product development timelines for novel coronary platforms. The Texas Medical Center in Houston anchors device evaluation protocols that diffuse to community hospital systems nationwide.
Germany
Outpatient cardiology clinics in Bavaria and North Rhine-Westphalia increasingly adopt drug-eluting balloons for provisional stenting protocols. CE marking under EU MDR filters competitor access and extends certification timelines for surviving manufacturers. The Leipzig Heart Center drives randomized trial enrollment that influences European practice guidelines.
Japan
PMDA pharmacokinetic standards for drug-eluting devices add country-specific development costs that delay market entry sequencing. Tokyo and Osaka metropolitan areas concentrate procedural volume for complex distal bifurcation interventions. The Sakakibara Heart Institute in Okayama generates clinical evidence that shapes regional adoption patterns.
Switzerland
Swissmedic maintains distinct quality system requirements that parallel EU MDR stringency for coronary device approvals. University Hospital Zurich and Geneva University Hospitals anchor French-German bilingual training networks. The Bern catheterization corridor serves as a trial site hub for European multicenter studies.
United Kingdom
NICE technology appraisals constrain bioabsorbable stent reimbursement in elective National Health Service settings. London teaching hospitals and Manchester cardiac centers concentrate complex PCI training infrastructure. The Golden Jubilee National Hospital in Glasgow runs dedicated bifurcation technique workshops that standardize operator skill acquisition.
Bifurcation Lesions Market Key Industry Players
Player mix skews toward diversified cardiovascular conglomerates with integrated cath lab portfolios. Market structure concentrates around three to five manufacturers capable of absorbing EU MDR compliance costs and sustaining multi-year clinical trial programs. Strategic archetypes include full-procedure contractors bundling hardware with optimization software, dedicated bifurcation specialists with narrow technology focus, and diversified medtech incumbents leveraging coronary cross-selling. Dominant competitive moves encompass M&A for imaging integration capabilities and strategic partnerships with academic medical centers for evidence generation.
Within the diversified cardiovascular tier, Boston Scientific Corporation, Abbott, and Medtronic occupy positions shaped by their respective stent platform legacies and cath lab ecosystem strategies. Boston Scientific represents the dedicated bifurcation system archetype through its Synergy stent platform positioning. Abbott exemplifies structural heart and coronary portfolio breadth competing across multiple lesion morphologies. Medtronic anchors the integrated workflow optimization vector extending beyond standalone devices into procedure management platforms.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott |
| Medtronic |
| Cardinal Health |
| Terumo Corporation |
| Johnson & Johnson Services, Inc. |
| C. R. Bard, Inc. |
| Spectranetics |
| Cook Group |
| Others |
Cost & Logistics Intelligence
Multi-year bundled cath lab contracts lock in device access and price visibility for United States hospital systems negotiating with stent manufacturers. These agreements tie metallic platform pricing to procedural volume commitments and imaging software integration tiers.
Pricing Analysis
Cost-plus contracts with cobalt-chromium alloy indexation dominate metallic stent procurement between United States academic medical centers and diversified cardiovascular manufacturers. Three-tier pricing structure across premium thin-strut designs, standard cobalt-chromium platforms, and economy bare-metal alternatives reflects FDA PMA tier and polymer biodegradability. Pricing pressure stems from German outpatient clinics adopting drug-eluting balloons for provisional stenting protocols. Ambulatory surgical centers exhibit highest price sensitivity; tertiary cardiac centers with bundled contracts show lowest.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States hospital systems maintaining lean cath lab consignment stock, while Japanese distributors maintain strategic stockpiles of PMDA-approved drug-eluting devices to buffer pharmacokinetic review delays. Manufacturing concentrates in United States, Ireland, and Costa Rica for FDA-inspected facilities; cobalt-chromium alloy feedstock draws from German and Belgian specialty metal suppliers. Single-source vulnerability runs through polymer coating chemistries controlled by two specialty chemical houses. Distribution runs through GPO contracts and direct hospital agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from intravascular imaging software subscriptions and procedure optimization platforms is expanding faster than standalone stent hardware sales. Recurring licensing fees for cath lab workflow management tools now exceed device margin contributions in United States academic medical center accounts.
For Market Incumbents: Shield market position by deepening backward integration into cobalt-chromium alloy casting and securing exclusive polymer coating supply agreements. Acquire imaging software specialists to bundle optimization platforms with stent contracts. Drug-eluting balloon substitution in German outpatient settings threatens metallic stent volume; CE marking investment under EU MDR filters competitor access and extends certification timelines for surviving manufacturers. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market entry for novel bifurcation platforms addressing left main anatomy. Target ambulatory surgical centers in Germany and United States with simplified provisional stenting systems and same-day discharge protocols. Partner with GPOs for distribution access rather than building direct sales infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified cardiovascular conglomerates with integrated cath lab portfolios. Long-term viability hinges on software-hardware bundling capabilities and multi-year hospital contract renewal rates. Watch for inflection in randomized trial data comparing provisional versus two-stent techniques; guideline updates will redirect procurement priorities regardless of individual product performance claims.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence mandates filter competitor access across European territories. |
| Hospital System Partnership | Multi-year bundled contracts with Cleveland Clinic networks lock in stent volume commitments. |
| Software Companion Development | Intravascular imaging integration extends revenue beyond standalone device sales. |
| Reimbursement Strategy | NICE technology appraisals constrain bioabsorbable stent coverage in United Kingdom elective settings. |
| FDA Submission | Premarket notification pathways shape product development timelines for novel coronary platforms. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body decisions, hospital procurement databases, and GPO contract disclosures. Interviews with interventional cardiologists, cath lab directors, biomedical engineers, and GPO contracts managers informed procedural adoption patterns and purchasing committee priorities. Bottom-up device shipment analysis triangulates against top-down hospital procedure volume estimates.
Segmentation dimensions modeled include product type, application, end user, technology, and regional regulatory cluster across the analysis window. CAGRs derive from trend extrapolation of complex PCI volumes, drug-eluting balloon adoption curves, and bundled contract renewal rates. Forecast inputs incorporate PMDA pharmacokinetic review timelines and EU MDR certification velocity.
Decision-makers should treat outputs as directional under assumptions of stable reimbursement for metallic stent platforms and continued CE marking enforcement stringency; material deviation in guideline recommendations or regulatory pathway changes would warrant model refresh. Practitioners should keep alternative scenarios live as randomized trial evidence comparing stenting techniques evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Cardiovascular Enterprise Viewer Market