
 Myocardial Infarction Market | 2026-2036
Myocardial Infarction Market Size, Share, and Industry Trends Forecast 2026-2036
Myocardial Infarction Market Intelligence
Biodegradable polymer coatings in drug-eluting stents is recalibrating device economics across the myocardial infarction treatment landscape. Pfizer Inc. leverages its anticoagulant portfolio to anchor hospital formulary positioning in acute coronary syndrome protocols. AstraZeneca plc sustains competitive intensity through its oral antiplatelet franchise and integrated cardiovascular-metabolic development strategy. Novartis AG differentiates via siRNA-based lipid management programs that extend therapeutic reach into post-infarction secondary prevention pathways.
Myocardial infarction denotes acute myocardial necrosis precipitated by sustained coronary artery occlusion, typically quantified by elevated cardiac troponin I or T exceeding the 99th percentile of normal reference populations with attendant ischemic symptoms or electrocardiographic changes. The primary commercial purpose spans immediate revascularization, myocardial salvage, and long-term event prevention across acute and chronic care settings. Medications and Devices command the dominant value pools, with Devices capturing premium pricing in acute intervention while Medications drive recurring revenue through chronic adherence protocols. Diagnostics is accelerating as high-sensitivity troponin assays and point-of-care platforms compress time-to-diagnosis intervals in emergency departments.
The FDA governs premarket approval and post-market surveillance for stents, antithrombotics, and diagnostic assays, while the Centers for Medicare & Medicaid Services shapes reimbursement thresholds that determine hospital procurement calculus. European Medicines Agency REACH-aligned material safety requirements and CE marking under the Medical Device Regulation impose conformity costs that filter market access for smaller device manufacturers. Stakeholders must monitor evolving FDA guidance on combination product classification and CMS technology add-on payment determinations, as these regulatory levers will dictate capital allocation between pharmaceutical and interventional device portfolios.
Market Dynamics
FDA accelerated approval pathways are compressing cardiovascular therapy commercialization timelines while hospital procurement consolidates around integrated cardiac networks that standardize device selection across multi-site systems.
Growth Catalysts
- High-sensitivity troponin assays:Emergency departments compress time-to-diagnosis intervals through point-of-care platforms. Diagnostic throughput accelerates patient triage decisions.
- Hospital-based acute care protocols:Healthcare systems prioritize rapid intervention frameworks. Standardized revascularization pathways reduce door-to-balloon times.
- Biodegradable polymer coatings:Drug-eluting stents eliminate permanent foreign material burden. Device economics shift toward reduced long-term complication management.
Market Restraints
- Platinum-iridium alloy supply concentration:Stent manufacturing depends on concentrated precious metal sourcing. Input cost volatility pressures device margin structures.
- REACH-aligned material safety compliance:European Medical Device Regulation imposes conformity costs. Smaller manufacturers face filtered market access.
- Oral anticoagulant substitution pressure:Novel agents displace legacy injectable protocols. Formulary switching threatens established revenue streams.
Strategic Opportunities
- siRNA-based lipid management:Post-infarction secondary prevention pathways extend therapeutic reach beyond acute intervention. Chronic adherence protocols create recurring revenue anchoring.
- Rural emergency department connectivity:Telemedicine-integrated diagnostic platforms address underpenetrated geographies. Hub-and-spoke models compress specialist consultation delays.
- CMS technology add-on payments:Reimbursement incentives reward innovative device adoption. Hospital procurement calculus favors premium technologies with separate payment tracks.
Industry Challenges
- Interventional cardiologist training pipeline:Complex percutaneous coronary intervention skill scarcity constrains procedure volume expansion. Fellowship program capacity limits workforce growth.
- Combination product classification uncertainty:FDA guidance evolution creates regulatory timeline risk. Drug-device hybrid submissions face prolonged review pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myocardial Infarction Market |
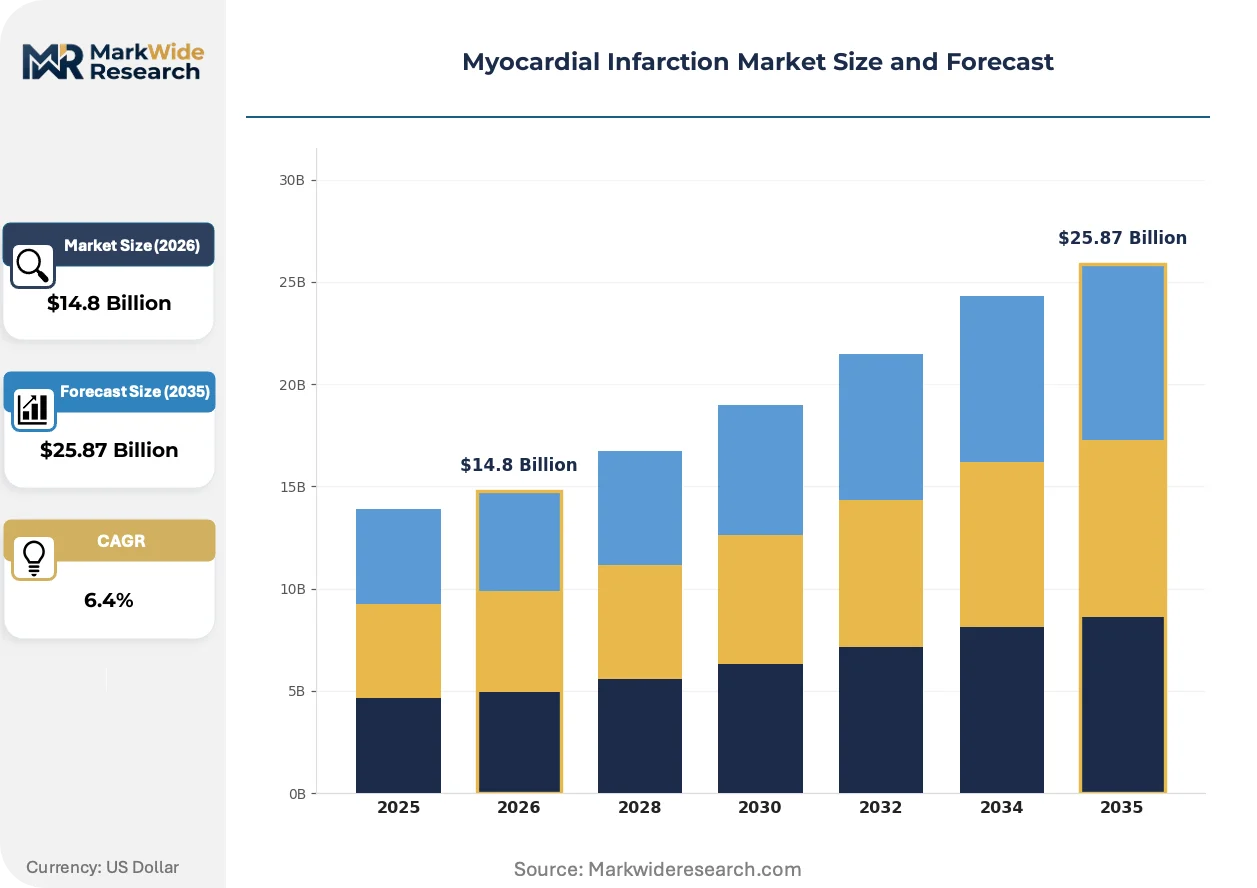
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Diagnostics, Rehabilitation Delivery Mode: Intravenous, Oral, Transdermal, Subcutaneous End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Treatment, Prevention, Diagnosis, Research |
| Companies Covered | Pfizer Inc., AstraZeneca plc, Novartis AG, Bristol-Myers Squibb Company, Boehringer Ingelheim, Merck & Co., Inc., Daiichi Sankyo Company Limited, Eli Lilly and Company, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myocardial Infarction Market Strategic Shifts & Innovations
Cardiovascular therapy development is pivoting toward molecular precision and connected care infrastructure, with regulatory frameworks accelerating approval velocity while procurement consolidation reshapes commercial access.
Bioresorbable vascular scaffolds is modularizing coronary intervention by eliminating permanent metallic implants from vessel architecture. Academic medical centers in Germany and Japan pilot programmable degradation timelines matched to endothelial healing curves. This technology is modularizing the treatment episode from permanent implant management to temporary support with biological resolution.
The EU Medical Device Regulation's enhanced clinical evidence requirements are extending post-market surveillance obligations for stent manufacturers. European notified bodies demand expanded patient follow-up registries. Class III implantable device sponsors face compressed transition timelines that favor established players with dedicated regulatory affairs infrastructure.
Hospital value analysis committees now mandate total cost-of-ownership documentation before device contract approval. Integrated delivery networks in the United States consolidate purchasing across 15-20 facility systems. Texas and Florida cardiac clusters lead this behavioral shift, requiring manufacturers to submit complication-rate data tied to readmission cost projections.
Myocardial Infarction Market Segmentation
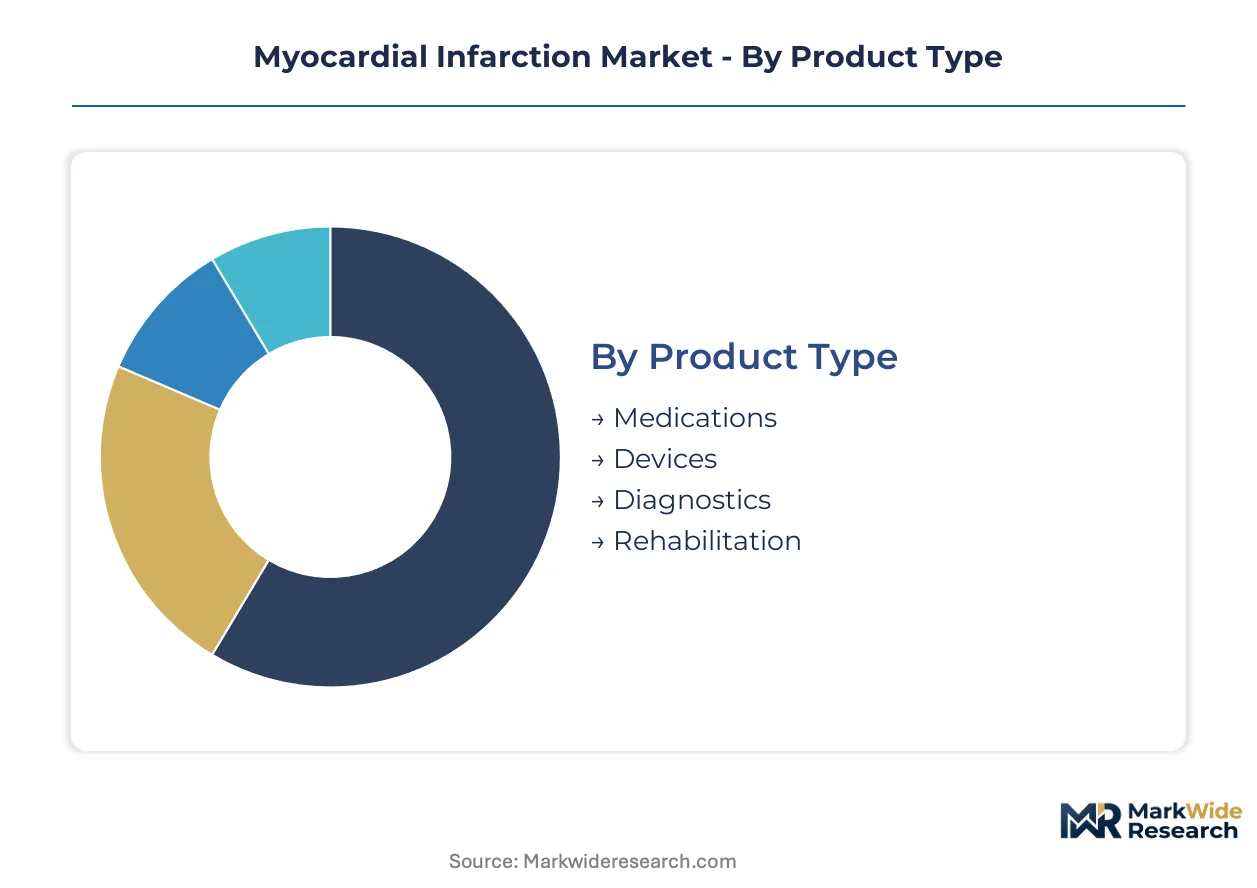
Segmentation in myocardial infarction care separates acute intervention economics from chronic management revenue streams. Each dimension reveals distinct procurement patterns, regulatory pathways, and margin structures that determine competitive positioning across the treatment continuum.
Product Type:
Devices command premium pricing in acute settings while Medications drive recurring revenue through chronic adherence protocols.
- Medications:Antithrombotics, antiplatelets, beta-blockers, and statins form the pharmacological backbone of acute and secondary prevention protocols. Hospital formularies in the United States anchor procurement through integrated cardiac networks, with oral anticoagulant substitution pressure threatening legacy injectable revenue streams.
- Devices:Drug-eluting stents, balloon catheters, and aspiration systems capture immediate revascularization value pools. Biodegradable polymer coatings eliminate permanent foreign material burden, shifting device economics toward reduced long-term complication management in tertiary care centers.
- Diagnostics:High-sensitivity troponin assays and point-of-care platforms compress time-to-diagnosis intervals.
- Rehabilitation:Cardiac monitoring systems and exercise therapy equipment support post-infarction recovery pathways.
Today's leader: Devices. Tomorrow's challenger: Diagnostics.
Delivery Mode:
Route selection determines reimbursement coding complexity and hospital pharmacy inventory management intensity.
- Intravenous:Heparin and glycoprotein IIb/IIIa inhibitors deliver immediate anticoagulation in catheterization laboratories. Emergency departments in Germany and Japan maintain 24-hour infusion capability as part of standardized revascularization pathways.
- Oral:P2Y12 inhibitors and direct oral anticoagulants enable transition to outpatient management. Formulary positioning battles between Bristol Myers Squibb and Pfizer shape hospital contracting dynamics in the United States.
- Transdermal:Nitroglycerin patches provide sustained vasodilation with reduced nursing burden.
- Subcutaneous:Low-molecular-weight heparin bridges patients to oral therapy in step-down units.
Intravenous dominates acute episodes; oral protocols are expanding most quickly into ambulatory settings.
End User:
Site-of-care migration is redistributing revenue between capital-intensive hospitals and distributed care locations.
- Hospitals:Catheterization laboratories and emergency departments concentrate high-acuity intervention volume. Value analysis committees in Texas and Florida cardiac clusters mandate total cost-of-ownership documentation before device contract approval.
- Clinics:Outpatient cardiology practices manage stable post-infarction patients. Hub-and-spoke models in rural United States geographies compress specialist consultation delays through telemedicine integration.
- Home Care:Remote patient monitoring extends surveillance beyond facility walls.
- Rehabilitation Centers:Structured exercise programs reduce readmission risk in Medicare populations.
Hospital procurement consolidation strengthens pricing power; home care represents the steepest expansion trajectory.
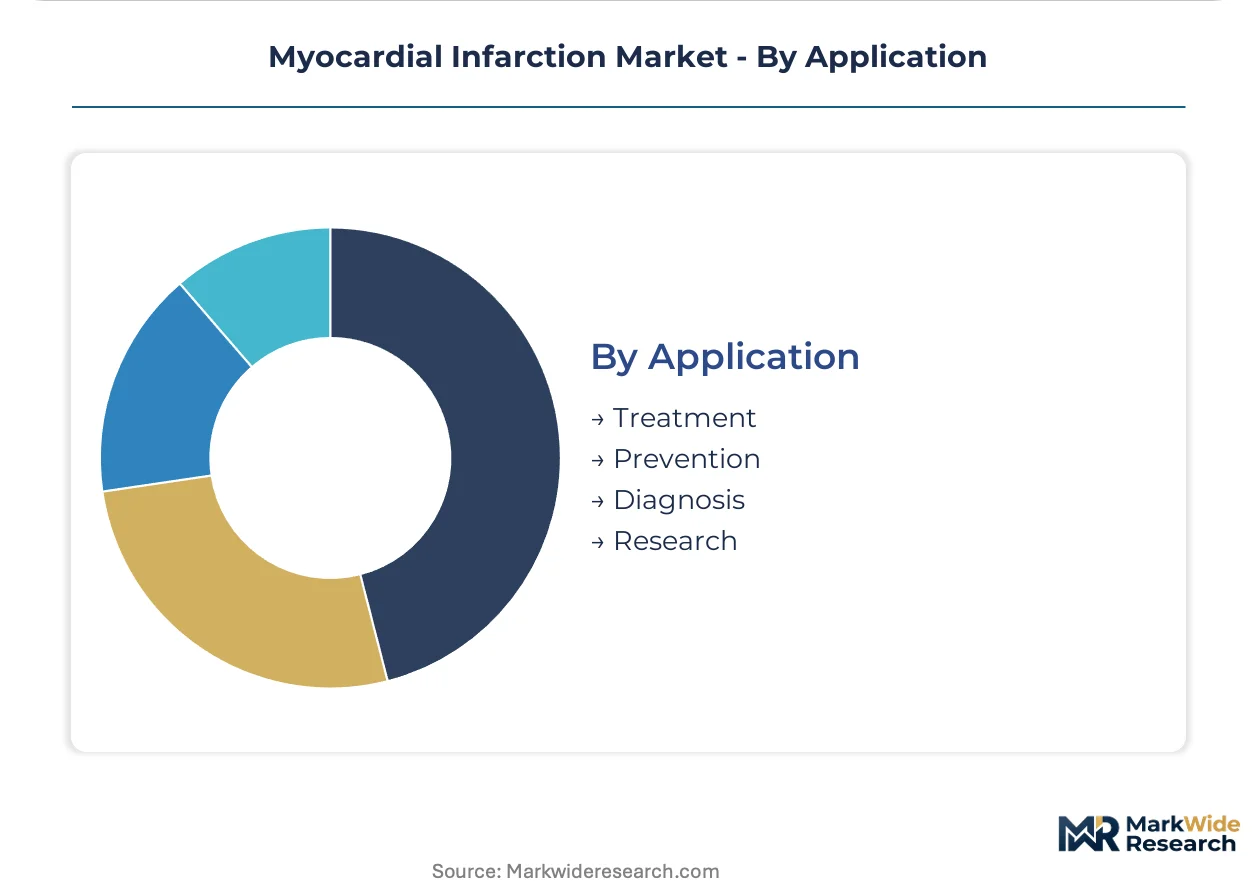
Application:
Purpose-based segmentation separates episodic intervention revenue from longitudinal prevention economics.
- Treatment:Immediate revascularization and myocardial salvage command the highest per-episode reimbursement. FDA accelerated approval pathways compress cardiovascular therapy commercialization timelines for novel antithrombotic entrants.
- Prevention:Secondary prevention through lipid management and lifestyle modification extends therapeutic reach. Novartis AG differentiates via siRNA-based programs that anchor chronic adherence revenue.
- Diagnosis:High-sensitivity troponin platforms enable rule-out protocols in emergency departments.
- Research:Academic medical centers in Germany and Japan pilot bioresorbable vascular scaffold programs with programmable degradation timelines.
Treatment captures immediate value; prevention is gaining share fastest as risk-stratification improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas and Florida cardiac clusters anchor hospital procurement consolidation for myocardial infarction devices, driving standardized revascularization protocols across integrated delivery networks.
United States
Hospital value analysis committees in Texas and Florida mandate total cost-of-ownership documentation before device contract approval. FDA accelerated approval pathways compress cardiovascular therapy commercialization timelines for novel antithrombotic entrants. Integrated cardiac networks in the Southeast consolidate purchasing across 15-20 facility systems.
Germany
Academic medical centers pilot bioresorbable vascular scaffolds with programmable degradation timelines matched to endothelial healing curves. EMA REACH-aligned material safety requirements impose conformity costs that filter market access for smaller device manufacturers. The Bavarian cardiac intervention cluster leads European adoption of biodegradable polymer coatings in drug-eluting stents.
Japan
Emergency departments maintain 24-hour infusion capability for intravenous anticoagulation as part of standardized revascularization pathways. PMDA governs premarket approval for stents and diagnostic assays with post-market surveillance obligations. The Kansai region anchors domestic manufacturing of high-sensitivity troponin assay platforms.
China
NMPA regulatory reforms accelerate domestic cardiovascular device approvals while hospital procurement centralization drives price compression. National reimbursement catalog updates determine formulary positioning for oral antiplatelet agents. The Yangtze River Delta concentrates catheterization laboratory expansion in tertiary care centers.
India
CDSCO regulatory pathways for stent registration create compliance timelines that favor established multinational manufacturers. Government price controls on coronary stents compress device margins while expanding patient access. The Maharashtra cardiac care corridor concentrates private hospital catheterization laboratory investment.
Myocardial Infarction Market Key Industry Players
Portfolio diversification dominates the current landscape as pharmaceutical and device manufacturers extend across acute intervention and chronic prevention pathways. The vendor base concentrates around integrated cardiovascular-metabolic portfolios with antithrombotic and lipid management anchors. Three archetypes prevail: large-cap pharmaceutical conglomerates with anticoagulant franchises, mid-cap device specialists with stent manufacturing capabilities, and emerging biotech entrants with siRNA-based programs. M&A activity and strategic partnerships represent the dominant competitive moves, with technology licensing agreements accelerating access to biodegradable polymer and bioresorbable scaffold platforms.
Within the large-cap pharmaceutical tier, Pfizer Inc. and AstraZeneca plc occupy positions anchored by antithrombotic and antiplatelet portfolios that shape hospital formulary dynamics. Novartis AG exemplifies the cardiovascular-metabolic integration archetype through differentiated positioning in post-infarction secondary prevention. These three entities represent the competitive core around which procurement consolidation and regulatory navigation revolve.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca plc |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Boehringer Ingelheim |
| Merck & Co., Inc. |
| Daiichi Sankyo Company Limited |
| Eli Lilly and Company |
| Amgen |
| Others |
Cost & Logistics Intelligence
Interventional cardiologist concentration in the Texas and Florida cardiac clusters widens pricing spreads between premium device tiers and standard offerings, as labor-cost differentials in catheterization laboratories amplify procurement budget constraints across integrated delivery networks.
Pricing Analysis
Platinum-iridium alloy cost pass-through dominates device margin structures, with manufacturers absorbing volatility through three-tier pricing stratification across premium biodegradable polymer stents, standard durable polymer platforms, and economy bare-metal alternatives. FDA certification tier and hospital system volume scale drive price differentiation, while oral anticoagulant substitution pressure compresses legacy injectable pricing. Cost compression in the economy tier intensifies because government price controls in India and China expand patient access. Public hospital procurement committees exhibit highest price sensitivity; private cardiac clusters in the United States demonstrate lowest sensitivity due to CMS technology add-on payment eligibility.
Supply Chain Analysis
Dual-sourcing mandates from hospital value analysis committees require stent manufacturers to qualify secondary platinum-iridium suppliers in Japan and Germany alongside primary channels. Raw material dependencies center on precious metal alloys, biodegradable polymer substrates, and high-sensitivity troponin assay reagents. Single-source vulnerability in platinum-iridium concentrate supply from South African mining operations creates procurement risk. Distribution runs through integrated cardiac network contracting offices that consolidate purchasing across 15-20 facility systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The myocardial infarction market operates as a regulatory compounder, with FDA accelerated approval pathway expansion driving demand compression for extended commercialization timelines.
For Market Incumbents: Hedge against oral anticoagulant substitution pressure by deepening backward integration into siRNA manufacturing capacity in Switzerland. Anchor hospital formulary positioning through vertical integration into point-of-care diagnostic platform development, neutralizing emerging biotech entrants with lipid management franchises. For New Entrants and Emerging Players: Telemedicine-integrated rural emergency departments represent the most penetrable white-space target, with hub-and-spoke models in the United States Southeast offering immediate addressable volume. Pursue regulatory fast-track qualification for biodegradable polymer coating technologies to bypass incumbent device contracts. For Investors and Strategic Acquirers: Large-cap pharmaceutical conglomerates with anticoagulant franchises are the most active acquirer in this space, seeking cardiovascular-metabolic portfolio diversification. Long-term viability hinges on chronic adherence protocol anchoring rather than acute intervention episodic revenue. Monitor FDA combination product classification guidance evolution as the critical inflection signal for drug-device hybrid valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Coating Development | Eliminates permanent implant burden and shifts economics toward reduced complication management in tertiary centers. |
| High-Sensitivity Troponin Assay Platform Launch | Compresses emergency department time-to-diagnosis intervals through point-of-care deployment. |
| Hospital System Partnership Expansion | Secures integrated cardiac network formulary positioning across 15-20 facility procurement consolidations. |
| siRNA-Based Lipid Management Pipeline Advancement | Extends therapeutic reach into post-infarction secondary prevention with recurring revenue anchoring. |
| Reimbursement Strategy Optimization | Aligns device premium pricing with CMS technology add-on payment eligibility criteria. |
Research Approach
Direct dialogue with interventional cardiologists, hospital procurement managers, GPO contracts specialists, and regulatory affairs directors grounded qualitative insights, cross-referenced with FDA premarket approval filings, CMS reimbursement determinations, hospital procurement databases, and clinical trial registries. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation validated segmentation outputs.
Market size and growth trajectory outputs across the projection horizon reflect disaggregated modeling of device, medication, diagnostic, and rehabilitation revenue streams. Segmentation dimensions span product type, delivery mode, end user, and application purpose. CAGRs were derived from procedure volume elasticity to regulatory approval velocity and hospital capital expenditure cycles. Forecast inputs incorporated interventional cardiologist fellowship pipeline capacity and REACH-aligned material safety compliance cost trajectories.
Platinum-iridium supply disruption, FDA combination product reclassification, and oral anticoagulant formulary substitution acceleration are the dominant revision risks to modeled outcomes. Deviation in FDA guidance timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Global Statin Market