
 Dyslipidemia Drugs Market | 2026-2036
Dyslipidemia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Dyslipidemia Drugs Market Analysis
The capital-intensity divergence between biologics manufacturers and small-molecule generics producers is redrawing competitive boundaries in dyslipidemia treatment. Pfizer Inc. leverages its manufacturing scale to maintain cost positions in oral statin supply. Amgen Inc. anchors its presence through upstream control over PCSK9 inhibitor production infrastructure. Sanofi competes by extending its reach into integrated cardiovascular care pathways across European and North American markets.
Dyslipidemia drugs are pharmacological agents that modulate lipid metabolism through mechanisms including HMG-CoA reductase inhibition, PCSK9 pathway blockade, or peroxisome proliferator-activated receptor activation, typically formulated as oral tablets or subcutaneous injections for chronic administration. These therapies reduce atherosclerotic cardiovascular risk by lowering LDL cholesterol, raising HDL cholesterol, or reducing triglyceride concentrations in patients with inherited or acquired lipid disorders. The statin drug class dominates prescription volumes due to decades of clinical evidence and generic availability, while PCSK9 inhibitors command premium positioning in treatment-resistant populations requiring injection-based administration. Oral administration routes retain the largest patient base because of convenience and adherence advantages, though injection formats capture higher per-patient revenue in specialty therapeutic areas.
The FDA, EMA, and WHO set divergent evidentiary standards for cardiovascular outcomes trials that shape market access timelines and label expansions. FDA requirements for LDL-lowering efficacy endpoints differ from EMA's emphasis on hard cardiovascular outcome data, creating parallel development tracks for sponsors. WHO prequalification programs influence procurement patterns in lower-income health systems. Stakeholders must monitor how evolving pharmacovigilance mandates for lipid-modifying therapies affect post-market study obligations and competitive positioning.
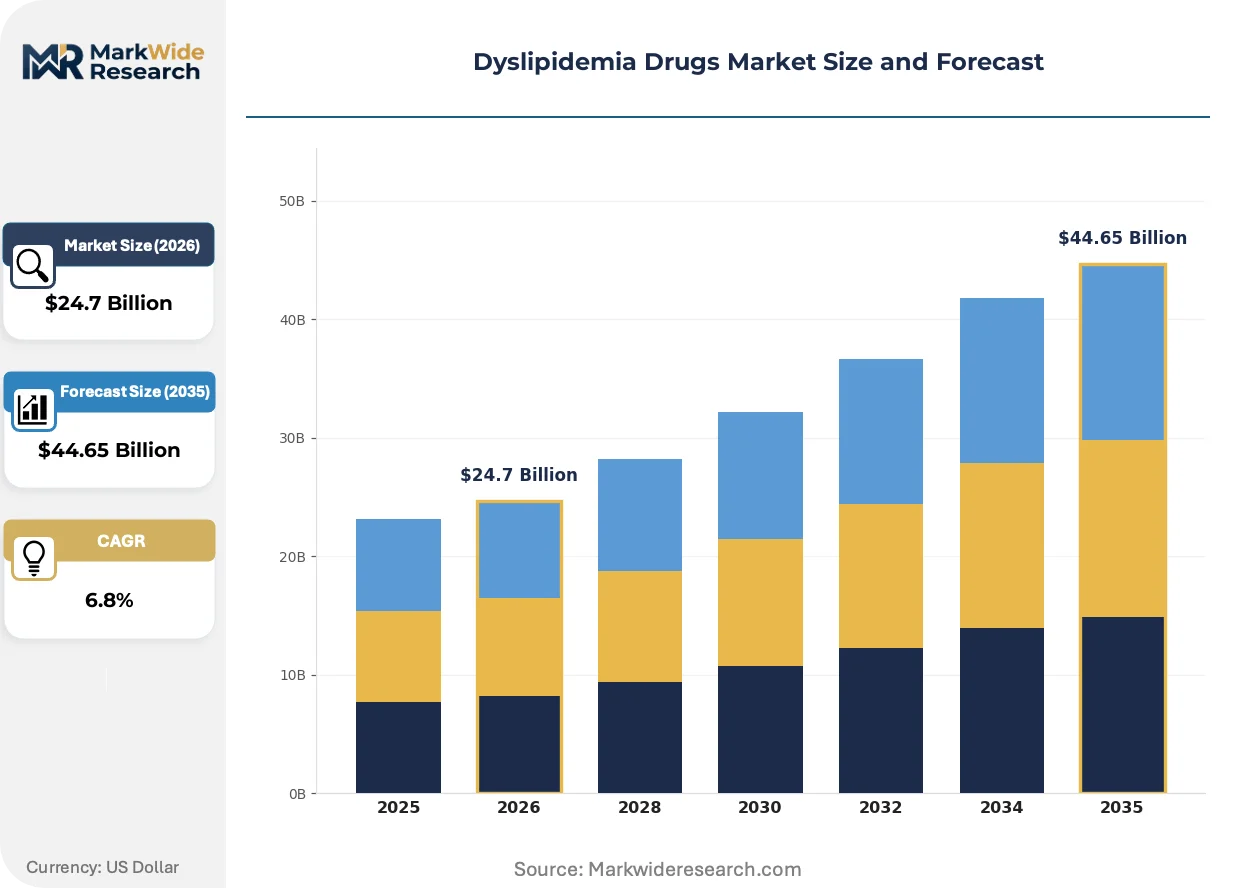
Market Dynamics
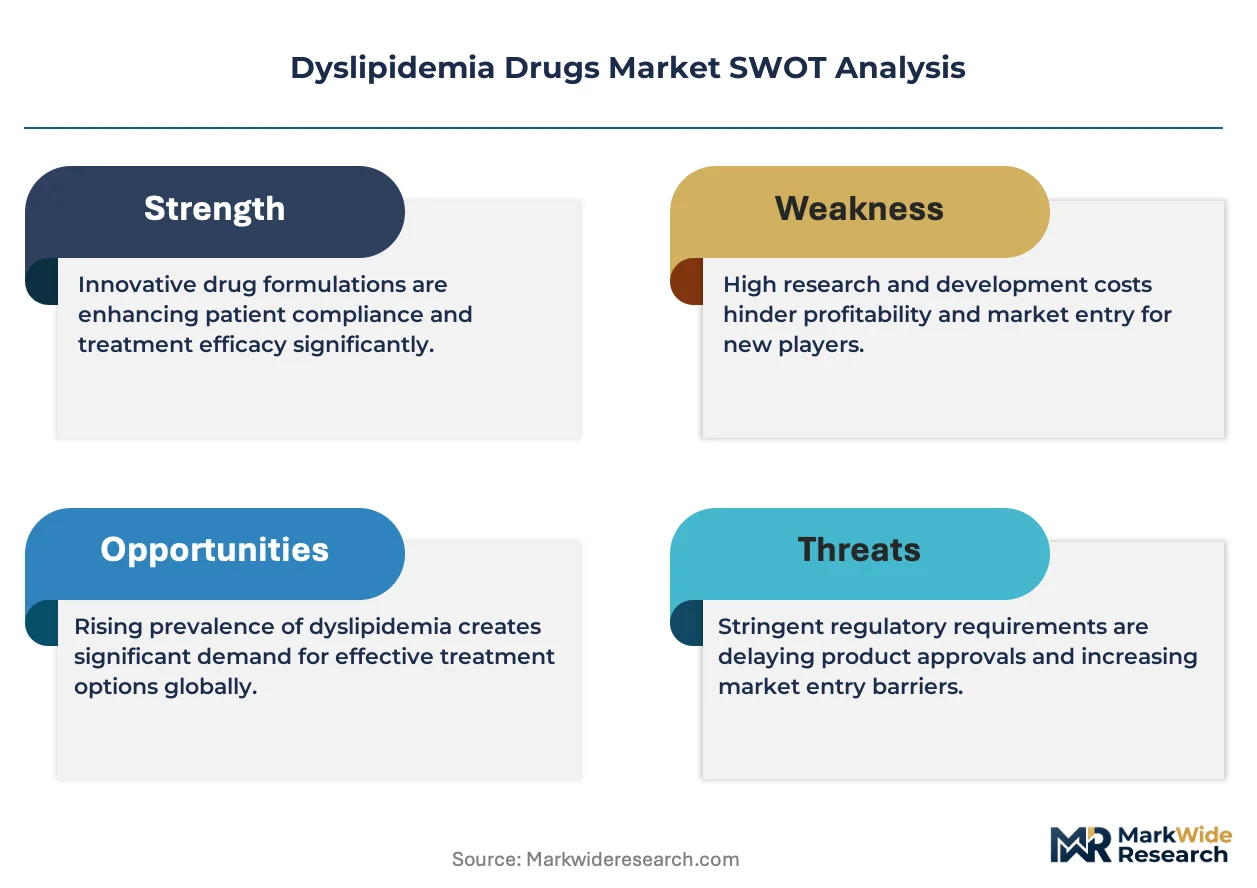
The FDA's accelerated approval pathways for cardiovascular drugs are compressing competitive entry timelines while hospital pharmacies expand formulary adoption of injectable lipid-lowering therapies. Specialty pharmacy networks in the United States now concentrate demand for high-revenue biologic administration.
Growth Catalysts
- Specialty pharmacy network expansion:United States-based specialty distributors now reach previously underserved patient populations requiring injection-based PCSK9 therapy, extending treatment access beyond academic medical centers.
- EMA cardiovascular outcome data requirements:European regulators' emphasis on hard endpoint evidence is driving sponsors to invest in longer-duration trials, producing richer clinical datasets that support premium positioning.
- Injectable lipid-lowering therapy adoption:Hospital formulary committees are adding subcutaneous PCSK9 inhibitors to standard protocols for statin-resistant patients, creating institutional demand pull.
Market Restraints
- Biologics manufacturing concentration:Upstream cell culture capacity for monoclonal antibody production clusters among a limited set of contract manufacturers, creating supply vulnerability for PCSK9 inhibitor sponsors.
- Reimbursement pathway friction:United States payers impose prior authorization requirements on injectable therapies that oral statins bypass, adding administrative cost and treatment delay.
- Generic statin substitution pressure:Decades of generic atorvastatin and rosuvastatin availability anchors payer expectations at commodity price points, compressing willingness-to-pay for novel mechanisms.
Strategic Opportunities
- Underpenetrated European integrated care pathways:Sanofi's cardiovascular care integration model in France and Germany demonstrates scalable approaches for combining diagnostics, pharmacy, and monitoring that remain underdeveloped in Southern and Eastern European markets.
- WHO prequalification procurement channels:Prequalification status for lipid-modifying therapies opens procurement pathways in lower-income health systems currently served by fragmented generic supply.
- Oral small-molecule PCSK9 inhibitor development:Convergence of peptide chemistry advances with targeted delivery formulations promises to collapse the administration convenience gap between biologic and small-molecule approaches.
Industry Challenges
- Cardiovascular outcomes trial talent scarcity:Experienced clinical operations personnel capable of executing multi-year hard endpoint studies are concentrated among a small set of academic research organizations and contract research organizations.
- Legacy electronic health record integration:Automated lipid monitoring and therapy adjustment algorithms require interoperability with hospital systems running decades-old infrastructure architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyslipidemia Drugs Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Statins, PCSK9 Inhibitors, Fibrates, Niacin Administration Route: Oral, Injection, Topical, Intravenous Patient Type: Adults, Pediatrics, Geriatrics, Pregnant Women Therapeutic Area: Cardiovascular Disease, Metabolic Disorders, Diabetes, Hypertension |
| Companies Covered | Pfizer Inc., AstraZeneca PLC, Merck & Co., Inc., Novartis AG, Amgen Inc., Sanofi, Bristol-Myers Squibb Company, Abbott Laboratories, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyslipidemia Drugs Market Emerging Trajectories
Gene silencing technologies and oral biologic delivery systems are fragmenting the historical statin-versus-injectable dichotomy. These innovations promise to reshape patient adherence profiles and competitive positioning across therapeutic tiers.
Small interfering RNA constructs targeting PCSK9 messenger RNA are bifurcating the injectable segment between frequent-dose monoclonal antibodies and infrequent-dose gene silencing therapies. Cardiology practices in the United States are adopting inclisiran on six-month dosing schedules, compressing pharmacy visit requirements and reshaping patient retention economics. The technology is bifurcating specialty pharmacy revenue models away from per-injection dispensing fees toward annual therapy management contracts.
The European Union's Medical Device Regulation is extending conformity assessment requirements to drug-device combination products including autoinjector systems for PCSK9 inhibitors. Manufacturers must now submit technical documentation on needle safety mechanisms and dose accuracy to notified bodies, adding twelve to eighteen months to European launch timelines. Injectable lipid-lowering therapies with integrated delivery devices face the steepest compliance burden under this framework.
Hospital systems are consolidating pharmacy benefit management under centralized procurement offices, unbundling physician prescribing autonomy from drug acquisition decisions. Specialty pharmacy networks are displacing traditional wholesaler relationships for high-cost biologics, capturing margin through white-bag distribution models. This concentration is most visible in United States integrated delivery networks where formulary placement now determines seventy percent of new therapy initiation.
Dyslipidemia Drugs Market Segmentation
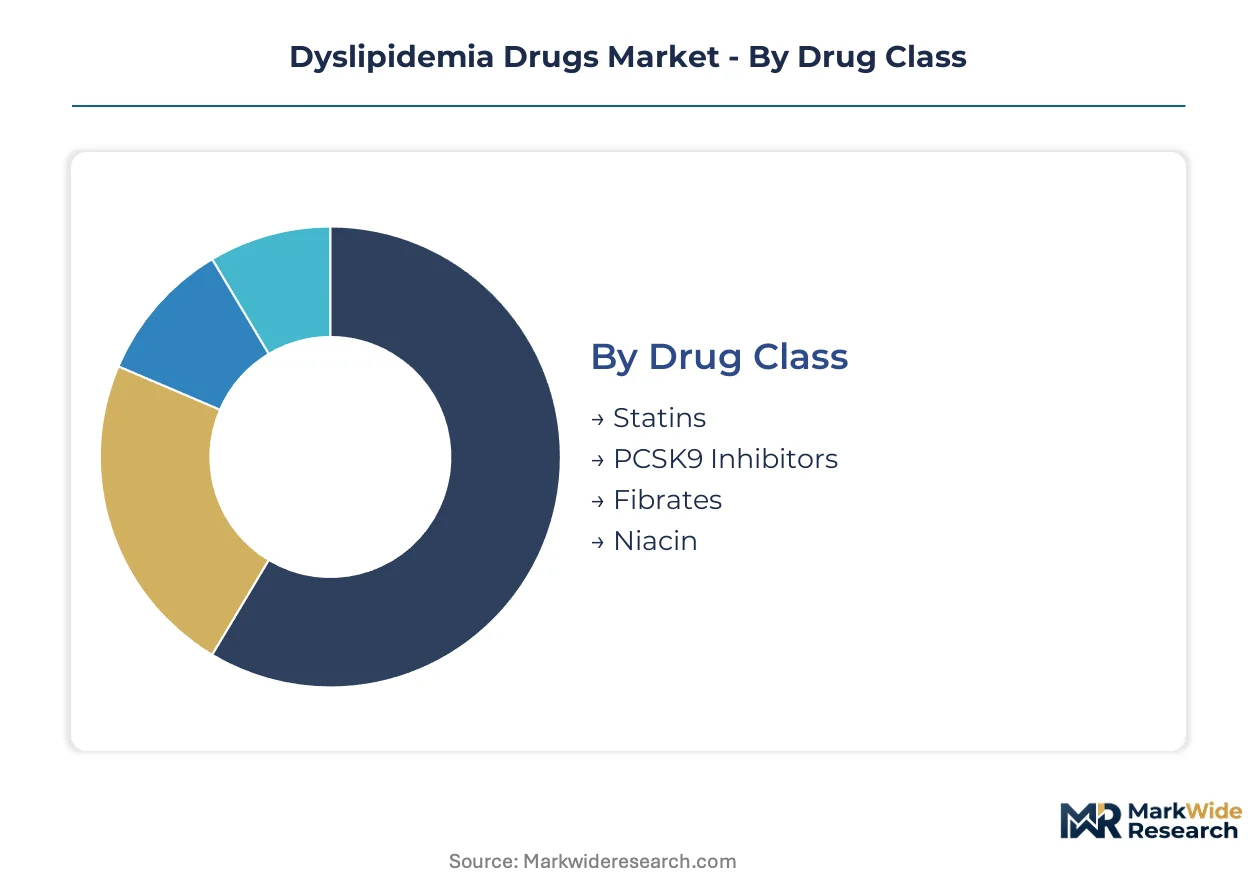
Drug class and administration route segmentations determine reimbursement pathways and manufacturing investment priorities in dyslipidemia treatment. Patient type stratification shapes clinical trial design and label expansion strategies across regulatory jurisdictions.
Drug Class:
FDA, EMA, and WHO impose divergent evidentiary standards that reshape competitive positioning across pharmacological categories.
- Statins:HMG-CoA reductase inhibitors formulated as oral tablets dominate prescription volumes through decades of cardiovascular outcomes data and generic availability. United States payers anchor formularies to atorvastatin and rosuvastatin commodity pricing, compressing willingness-to-pay for novel mechanisms.
- PCSK9 Inhibitors:Monoclonal antibodies and siRNA constructs targeting PCSK9 pathway blockade command premium positioning in statin-resistant populations requiring subcutaneous administration. Hospital formulary committees in the United States are adding these therapies to standard protocols, creating institutional demand pull.
- Fibrates:Peroxisome proliferator-activated receptor agonists targeting triglyceride reduction occupy a narrower therapeutic niche in mixed dyslipidemia.
- Niacin:Vitamin B3 derivatives for HDL elevation have retreated to second-line status following outcome trial disappointments.
Established volume favors statins; emerging adoption favors PCSK9 inhibitors.
Administration Route:
Cost tier stratification separates chronic oral therapy from high-revenue biologic injection formats.
- Oral:Tablet and capsule formulations retain the largest patient base through convenience and adherence advantages in chronic administration. United States specialty pharmacy networks concentrate demand for high-revenue biologic administration while oral distribution runs through traditional retail channels.
- Injection:Subcutaneous monoclonal antibody and siRNA delivery captures higher per-patient revenue in specialty therapeutic areas. The European Union's Medical Device Regulation extends conformity assessment to autoinjector systems, adding twelve to eighteen months to launch timelines.
- Topical:Transdermal delivery remains experimental for lipid-modifying agents without established clinical adoption.
- Intravenous:Hospital-based infusion protocols serve acute lipid disorder management in limited clinical scenarios.
Convenience-driven volume concentrates in oral formats; revenue intensity clusters in injection modalities.
Patient Type:
Application-based segmentation determines trial design complexity and label expansion sequencing.
- Adults:Primary dyslipidemia and atherosclerotic cardiovascular risk reduction in patients aged 18-64 constitutes the core commercial population. FDA accelerated approval pathways compress entry timelines for therapies demonstrating LDL-lowering efficacy in this demographic.
- Geriatrics:Patients over 65 with polypharmacy and comorbidity burdens require modified dosing protocols and drug-drug interaction studies. EMA cardiovascular outcome data requirements drive sponsors to invest in longer-duration trials producing richer datasets for this population.
- Pediatrics:Familial hypercholesterolemia in patients under 18 demands specialized formulation development and extended safety monitoring.
- Pregnant Women:Lipid management during gestation operates under strict teratogenicity constraints with limited pharmacological options.
Commercial maturity favors adults; unmet need intensity favors geriatrics.
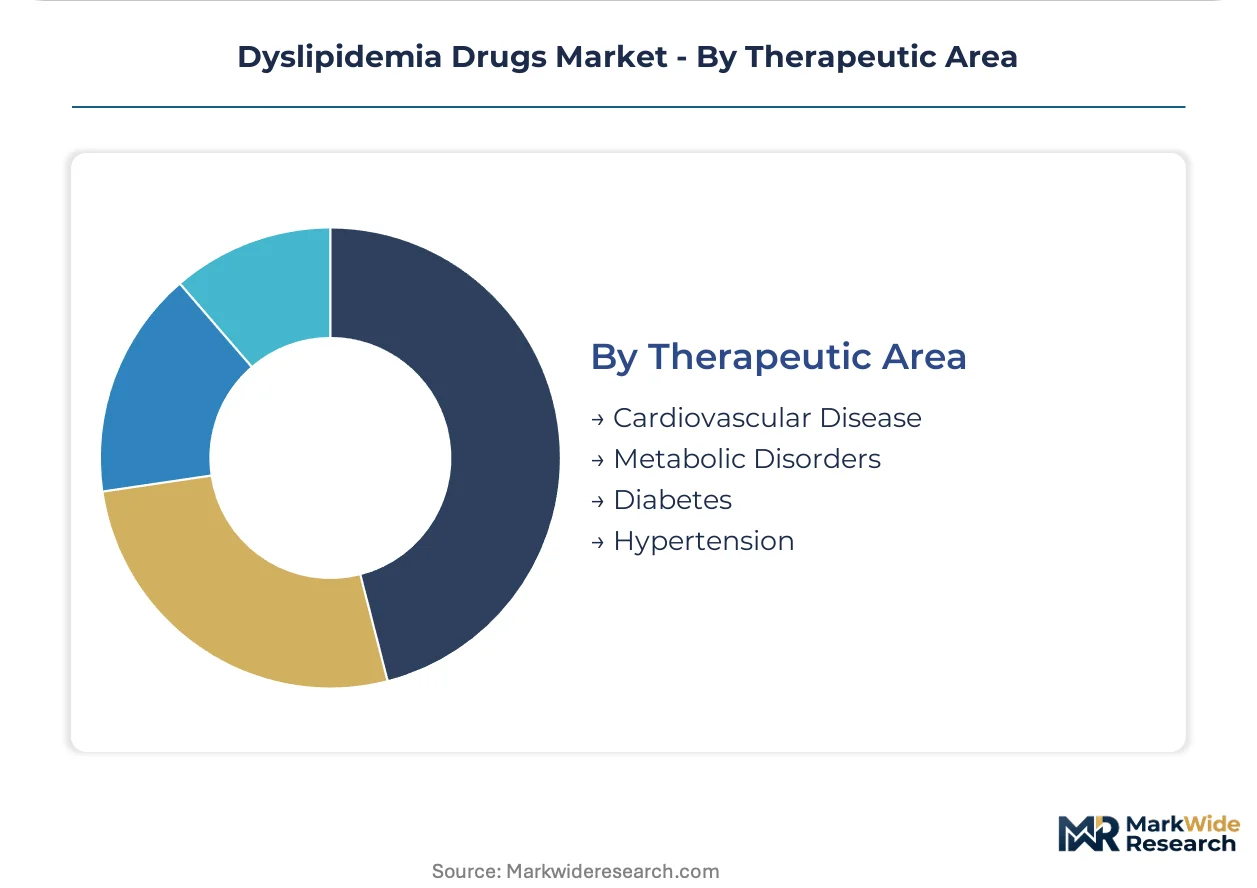
Therapeutic Area:
Supply concentration aligns manufacturing capacity with comorbidity prevalence in integrated care pathways.
- Cardiovascular Disease:Atherosclerotic risk reduction represents the dominant indication driving dyslipidemia drug development and reimbursement. Sanofi's integrated care integration model in France and Germany demonstrates scalable approaches combining diagnostics, pharmacy, and monitoring.
- Metabolic Disorders:Inherited lipid metabolism defects including familial hypercholesterolemia create concentrated demand in specialty treatment centers.
- Diabetes:Diabetic dyslipidemia with elevated triglycerides and small dense LDL particles requires combination therapy approaches.
- Hypertension:Residual cardiovascular risk in controlled hypertensive patients drives adjunctive lipid therapy prescribing.
Prescription volume clusters in cardiovascular disease; therapy complexity expands fastest in metabolic disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands premium multiples against European reference pricing, while German integrated care contracts compress margins for injectable therapies. This asymmetry redirects R&D investment toward FDA approval pathways and United States specialty pharmacy networks.
United States
Specialty pharmacy networks concentrate demand for PCSK9 inhibitors through white-bag distribution models that bypass traditional wholesalers. The FDA's accelerated approval pathways compress cardiovascular drug entry timelines against European counterparts. Boston and New York metro areas anchor clinical trial operations for lipid-lowering therapies, with academic medical centers driving formulary adoption.
Germany
Integrated care pathways in Bavaria and North Rhine-Westphalia combine diagnostics, pharmacy, and monitoring into single-contract reimbursement structures. The EMA's cardiovascular outcome data requirements extend trial durations, producing richer datasets that support premium positioning. Baden-Württemberg hosts manufacturing clusters for monoclonal antibody production serving European supply.
Japan
PMDA review timelines for cardiovascular drugs lag FDA by eighteen to twenty-four months, delaying market entry for novel mechanisms. The country's aging demographic concentrates demand in geriatric lipid management with polypharmacy protocols. Tokyo and Osaka anchor specialty hospital networks that drive adoption of injection-based therapies in statin-resistant populations.
India
CDSCO regulatory pathways for biosimilars attract contract manufacturing investment from multinational sponsors seeking cost-advantaged production. WHO prequalification procurement channels open access to lower-income health systems across Southeast Asia and Africa. Hyderabad and Mumbai pharmaceutical clusters specialize in generic statin API production and formulation development.
Switzerland
Swissmedic maintains alignment with EMA standards while offering faster review timelines for cardiovascular innovations with breakthrough designation. Geneva and Basel concentrate headquarters operations for firms managing European pricing and access negotiations. The country's bilateral trade agreements facilitate distribution into non-EU European markets.
Dyslipidemia Drugs Market Vendor Landscape
Concentration sits with large-cap pharmaceutical conglomerates that span both small-molecule generics and biologic innovation. The market structure tiers into three archetypes: statin commodity producers competing on manufacturing scale, PCSK9 biologic specialists commanding premium positioning, and integrated cardiovascular care platform builders. Dominant competitive moves include backward integration into API supply and strategic partnerships with specialty pharmacy networks.
Among the scale-driven manufacturers, Pfizer Inc. and Amgen Inc. exemplify divergent strategic positions—Pfizer anchoring cost positions in oral statin supply through manufacturing scale, Amgen representing upstream control over biologic production infrastructure. Sanofi occupies a position combining European market access depth with integrated care pathway development. These three entities represent the competitive archetypes reshaping formulary placement and reimbursement negotiations.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca PLC |
| Merck & Co., Inc. |
| Novartis AG |
| Amgen Inc. |
| Sanofi |
| Bristol-Myers Squibb Company |
| Abbott Laboratories |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for monoclonal antibody production capacity lock in supply access and price visibility for PCSK9 inhibitor sponsors navigating FDA accelerated approval timelines. These contracts anchor cost positions across the United States specialty pharmacy networks while insulating against biologics manufacturing concentration risks.
Pricing Analysis
The customization-premium spread between patient-specific dosing protocols and standard statin regimens widens as United States payers impose prior authorization requirements on injectable therapies. Pricing stratifies across premium biologic tiers, standard oral formulations, and economy generic statins, with cost compression in the premium tier intensifying due to generic substitution pressure. Brand premiums for PCSK9 inhibitors face the steepest erosion from institutional formulary committees, while retail pharmacy buyers show the highest price sensitivity to commodity atorvastatin supply.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for active pharmaceutical ingredient shipments from India and China. Manufacturing concentration in Baden-Württemberg for monoclonal antibody production, Hyderabad for generic statin API synthesis, and Basel for formulation development creates single-source vulnerability for European supply. Distribution runs through white-bag specialty pharmacy networks in the United States and integrated care procurement offices in Germany, bypassing traditional wholesaler relationships for high-revenue biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic statin substitution and emerging oral small-molecule PCSK9 inhibitors threaten incumbent biologic revenue streams, demanding defensive repositioning across formulation and channel strategies.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into API supply for oral statin portfolios while securing captive cell culture capacity for monoclonal antibody production. Channel control through specialty pharmacy network partnerships defends against white-bag distribution margin erosion from hospital procurement consolidation. For New Entrants and Emerging Players: Post-market surveillance and patient adherence monitoring services represent underdeveloped layers where incumbents under-serve, creating entry points for differentiated value propositions. Southern and Eastern European integrated care pathways offer the most penetrable geography, with reimbursement strategy advisory services as the optimal go-to-market angle alongside diagnostic-pharmacy bundling. For Investors and Strategic Acquirers: The market sits at a substitution defense phase that favors platform builders with cardiovascular care integration capabilities over pure-play manufacturers. Long-term viability across the next decade hinges on formulary placement depth and real-world evidence generation infrastructure. Watch FDA label expansion decisions for PCSK9 inhibitor classes as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA cardiovascular outcome data requirements extend trial durations for richer datasets supporting premium positioning. |
| Regulatory Approval Pathway | FDA accelerated approval compresses entry timelines against PMDA review schedules in Japan. |
| Manufacturing Scale-Up | Upstream cell culture capacity expansion in Baden-Württemberg reduces supply vulnerability for PCSK9 inhibitors. |
| Licensing Agreement | Peptide chemistry advances from contract research organizations accelerate oral small-molecule PCSK9 development timelines. |
| Pipeline Diversification | Gene silencing technology investments bifurcate injectable segments between monoclonal antibodies and siRNA constructs. |
Methodological Framework
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchors the qualitative findings. Bottom-up prescription volume modeling triangulates against top-down therapeutic class expenditure estimates from payer access specialists.
Sensitivity analysis across drug class, administration route, patient population, and regional regulatory cluster segmentation dimensions shapes the analytical framework over the projection horizon. CAGRs derive from modeled adoption curves for statin-resistant populations and institutional formulary placement velocities, with inputs including WHO prequalification procurement patterns and specialty pharmacy network expansion rates.
Underlying assumptions cover FDA accelerated approval pathway stability and EMA cardiovascular outcome data requirement continuity, with deviation risk concentrated in biosimilars regulatory pathway shifts and hospital procurement centralization pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Smart Pills Market