
 Analytics As a Service (Aaas) Market | 2026-2036
Analytics As a Service (Aaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Analytics As a Service (Aaas) Market Intelligence
India's expanding hyperscaler data center footprint is reshaping regional delivery economics for AaaS providers. Microsoft Corporation leverages its Azure Synapse platform to anchor enterprise workloads across South Asian markets. Amazon Web Services, Inc. competes through backward integration into custom silicon, reducing inference costs for real-time analytics customers.
Analytics As a Service denotes the remote provisioning of statistical modeling, data processing, and insight generation through cloud-native architectures, typically delivered via API endpoints or managed dashboards with sub-second query latency for operational decision support. The service type dimension stratifies across predictive, descriptive, prescriptive, and real-time analytics, with prescriptive offerings commanding premium positioning as organizations automate resource allocation and supply chain responses. Deployment configurations span public cloud, private cloud, hybrid, and on-premises installations, though hybrid architectures are gaining traction among financial services firms seeking to partition sensitive training data from inference workloads.
The EU AI Act and GDPR impose layered compliance obligations on AaaS vendors processing personal data or deploying automated decision systems within European jurisdictions. In the United States, HIPAA governs analytics platforms handling protected health information, while the SEC's disclosure rules shape how predictive models inform material financial reporting. Stakeholders must monitor evolving algorithmic accountability frameworks across multiple jurisdictions to anticipate certification requirements that could restrict market access or inflate compliance costs.
Market Dynamics
Cloud hyperscalers are consolidating control over AaaS infrastructure through proprietary silicon and vertically integrated data pipelines, compressing margins for independent analytics vendors while forcing specialization at the application layer.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face mandatory algorithmic transparency requirements for automated decision systems, driving procurement of certified AaaS platforms with built-in audit trails and explainability frameworks.
- Healthcare predictive analytics:Hospital systems deploy cloud-native platforms to reduce readmission rates and optimize resource allocation, with HIPAA-compliant architectures accelerating vendor qualification cycles.
- India's data center expansion:Hyperscaler facility investments in Mumbai, Hyderabad, and Chennai reduce latency for South Asian enterprises, enabling real-time analytics workloads previously restricted to Singapore or European nodes.
Market Restraints
- GPU supply concentration:Inference acceleration hardware relies on foundry capacity concentrated in Taiwan and South Korea, creating input cost volatility and allocation risk for real-time analytics providers.
- GDPR-EU AI Act layering:Dual compliance obligations impose structural friction on vendors processing European personal data, requiring redundant legal engineering and documentation systems.
- On-premises legacy persistence:Financial services firms maintain captive data lakes for model training, limiting addressable market for pure public cloud AaaS offerings in regulated segments.
Strategic Opportunities
- Prescriptive analytics automation:Supply chain and manufacturing verticals seek platforms that autonomously trigger procurement and logistics responses, creating premium pricing power for vendors with reinforcement learning capabilities.
- Hybrid deployment architectures:Financial institutions partition sensitive training data on private infrastructure while pushing inference to public cloud, opening systems integration and orchestration service revenue streams.
- SEC disclosure rule alignment:US public companies require predictive models that support material financial reporting, creating demand for AaaS platforms with audit-grade documentation and model lineage tracking.
Industry Challenges
- MLOps talent scarcity:Production deployment of machine learning pipelines requires engineers with combined cloud infrastructure and statistical modeling expertise, a skill intersection with limited labor market depth.
- Model drift monitoring:Real-time analytics customers demand continuous validation of predictive accuracy, forcing vendors to build expensive telemetry infrastructure or risk contractual penalties.
- Cross-border data localization:Divergent sovereignty requirements across India, China, and EU jurisdictions fragment platform architectures and inflate engineering overhead for multinational deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytics As a Service (Aaas) Market |
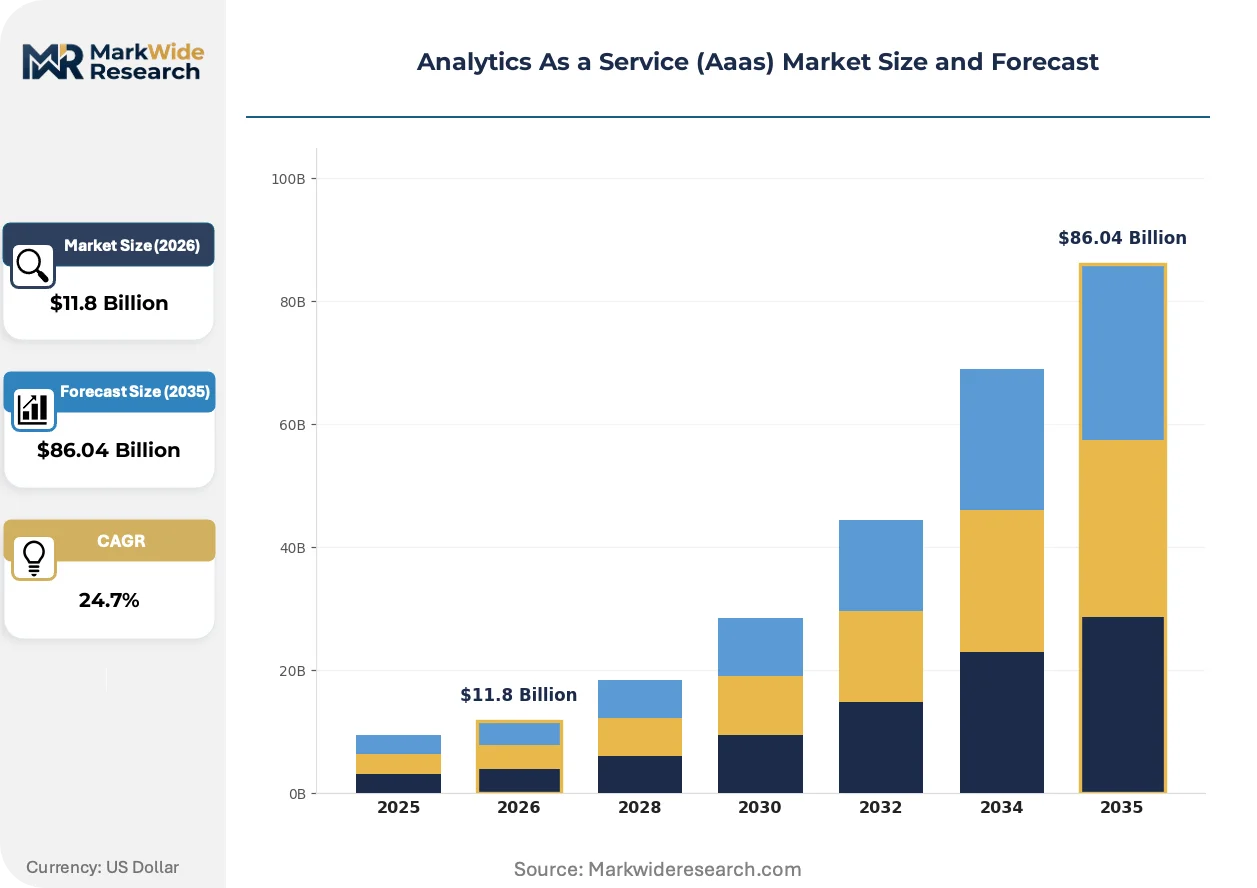
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $86.04 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Retail, Healthcare, Education, Manufacturing Service Type: Predictive Analytics, Descriptive Analytics, Prescriptive Analytics, Real-Time Analytics Solution: Business Intelligence, Data Visualization, Data Mining, Machine Learning |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Inc., Google LLC, IBM Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., Snowflake Inc., Tableau Software, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytics As a Service (Aaas) Market Strategic Shifts & Innovations
Generative AI architectures are compressing traditional analytics workflows, embedding natural language interfaces and automated insight generation directly into operational systems rather than requiring dedicated analyst intermediaries.
Serverless query engines are collapsing the cost structure for ad-hoc analytical workloads. Retail and logistics operators now embed sub-second analytics directly into customer-facing applications without provisioning persistent compute clusters. This compression eliminates the upfront capacity planning that previously gated real-time use cases.
The EU AI Act's risk classification system imposes documentation and human oversight requirements on high-risk automated decision systems. AaaS vendors serving European credit scoring, recruitment, and public benefit allocation must rebuild product architectures around built-in explainability and contestability features. Healthcare and financial services procurement teams now require algorithmic impact assessments as standard contract terms.
Consumption-based pricing is displacing seat-based subscriptions for enterprise analytics procurement. Chief data officers negotiate throughput commitments rather than user licenses, aligning vendor compensation with actual query volume and compute consumption. This shift concentrates contract value with platforms demonstrating superior query optimization and caching efficiency, particularly visible in US technology and media verticals.
Analytics As a Service (Aaas) Market Segmentation
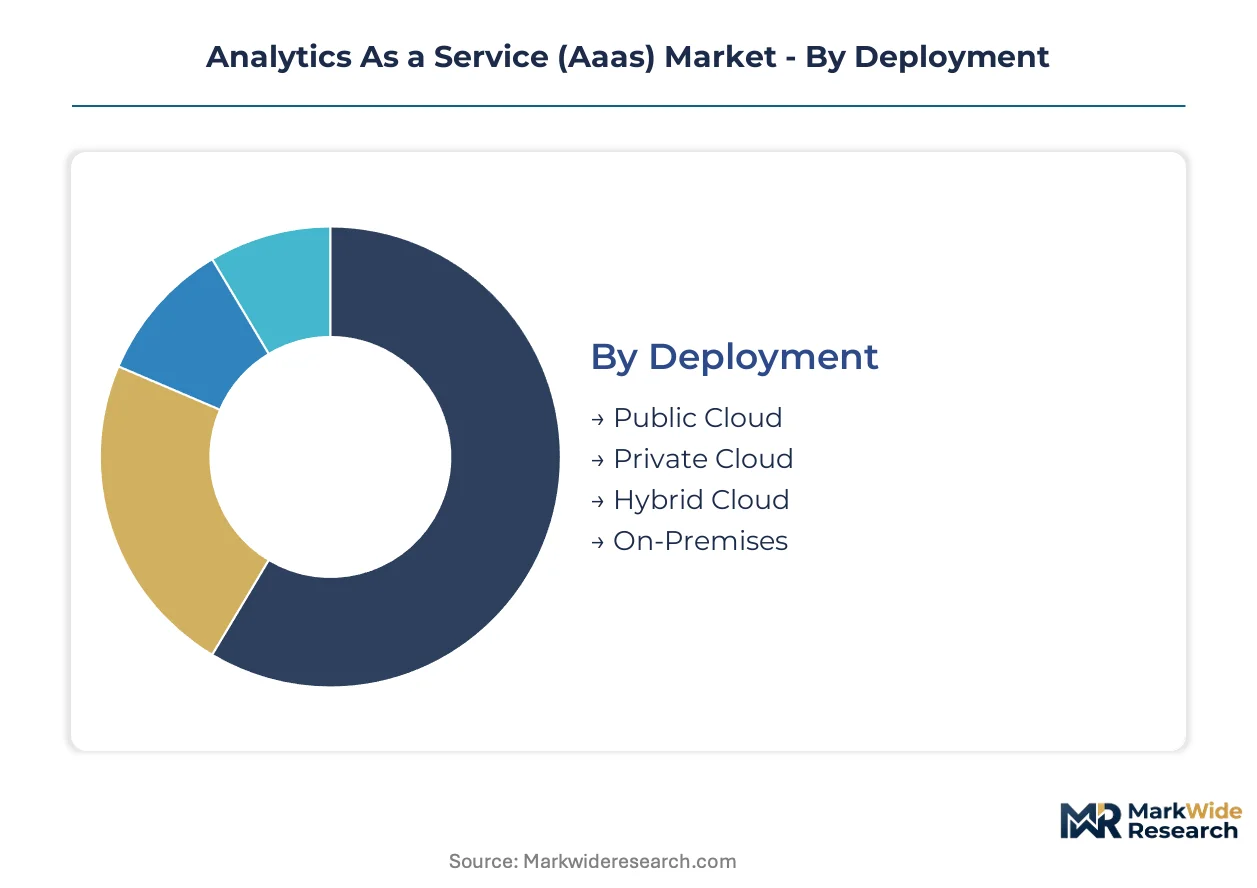
Analytics As a Service architectures fragment across deployment models, end-use verticals, and solution layers. Procurement teams negotiate contracts based on latency requirements, data sovereignty constraints, and the specific statistical techniques required for operational decision support.
Deployment:
Mature configurations dominate transaction volume, while emerging hybrid architectures capture the fastest-growing workload categories.
- Public Cloud:Multi-tenant infrastructure delivers sub-second query latency through distributed compute clusters. Healthcare systems in the United States route de-identified patient flows to public nodes while reserving PHI processing for private environments.
- Hybrid Cloud:Partitioned architectures separate sensitive training data from inference workloads, enabling financial services firms to maintain HIPAA and SEC compliance without sacrificing elastic scaling. Indian enterprises leverage Mumbai hyperscaler nodes for real-time inference while retaining core data lakes on-premises.
- Private Cloud:Single-tenant deployments serving defense contractors and government agencies with strict data residency mandates.
- On-Premises:Captive installations persisting in legacy manufacturing and regulated European banking segments with legacy infrastructure lock-in.
Public Cloud handles the majority of throughput; Hybrid Cloud is the fastest mover on share.
End User:
Cost tier stratification separates premium healthcare deployments from standardized retail implementations.
- Healthcare:Predictive readmission modeling and resource optimization drive procurement of HIPAA-compliant platforms with built-in audit trails. Hospital systems negotiate throughput commitments tied to bed occupancy forecasting accuracy.
- Retail:Inventory velocity analytics and demand sensing embed directly into ERP systems, with serverless query engines collapsing costs for seasonal demand spikes.
- Manufacturing:Prescriptive maintenance and supply chain automation require reinforcement learning capabilities with premium pricing power.
- Education:Student retention modeling and enrollment forecasting represent emerging use cases with constrained procurement budgets.
Healthcare commands the highest contract values; Retail is expanding most quickly on deployment volume.
Service Type:
Application complexity separates diagnostic capabilities from autonomous decision systems.
- Prescriptive Analytics:Autonomous resource allocation engines trigger procurement and logistics responses without human intervention. Manufacturing verticals pay premiums for reinforcement learning platforms that optimize production schedules against material constraints.
- Predictive Analytics:Forecasting models for demand, risk, and patient outcomes represent the largest installed base, with EU AI Act compliance requirements reshaping vendor qualification criteria.
- Real-Time Analytics:Sub-second inference for fraud detection and operational monitoring, constrained by GPU supply concentration in Taiwan and South Korea.
- Descriptive Analytics:Historical reporting and dashboard visualization facing commoditization pressure from embedded BI tools.
Predictive Analytics retains the largest revenue base; Prescriptive Analytics shows the steepest expansion trajectory.
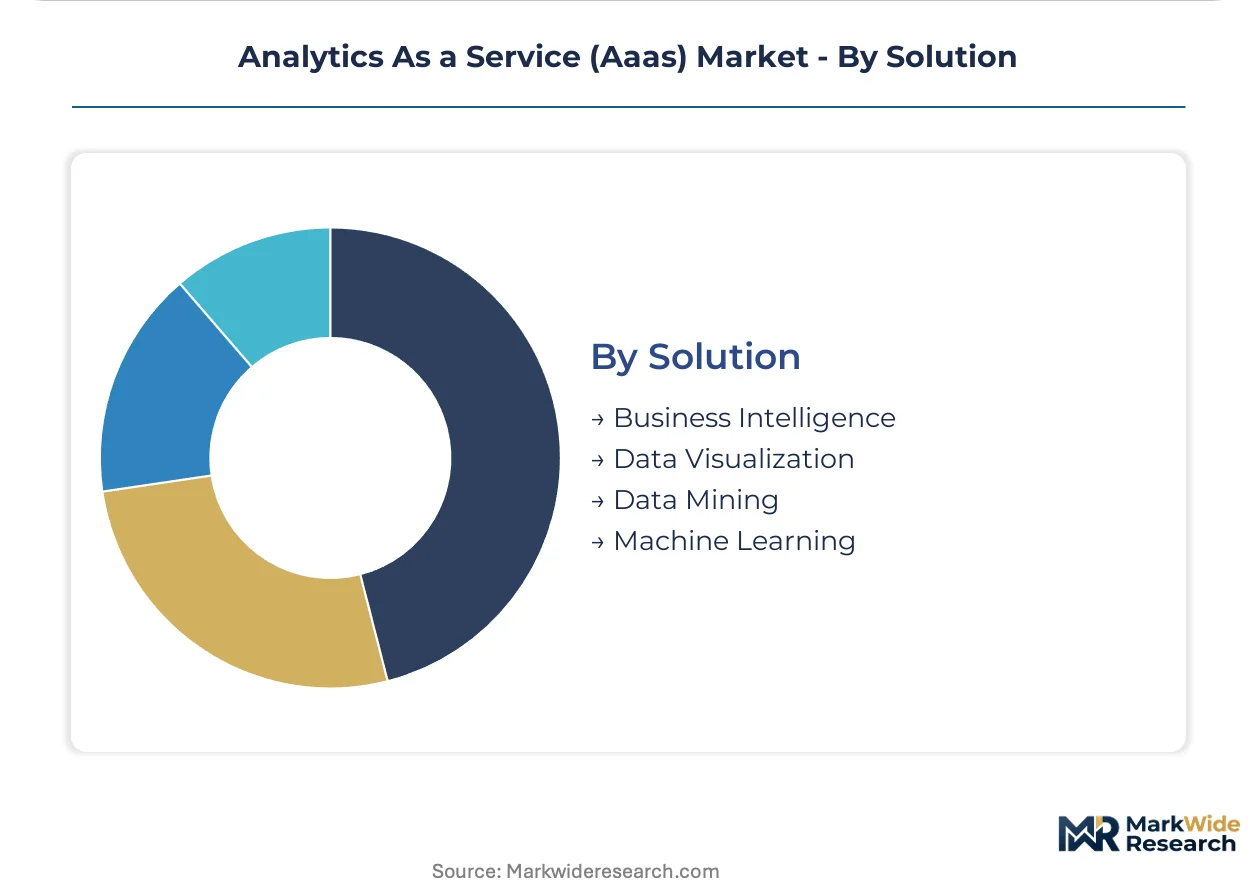
Solution:
Margin concentration flows toward specialized machine learning infrastructure versus commoditized visualization layers.
- Machine Learning:Production MLOps pipelines require combined cloud infrastructure and statistical modeling expertise, a skill intersection with limited labor market depth. Vendors differentiate through automated model monitoring and drift detection telemetry.
- Business Intelligence:Consumption-based pricing is displacing seat-based subscriptions, with chief data officers negotiating throughput commitments rather than user licenses.
- Data Visualization:Natural language interfaces and automated insight generation compress traditional analyst workflows.
- Data Mining:Pattern extraction from unstructured sources, increasingly embedded within generative AI architectures rather than standalone offerings.
Business Intelligence handles the largest query volumes; Machine Learning is climbing the fastest on pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler data center investments concentrate cloud infrastructure capacity in specific national markets, reshaping latency economics for real-time analytics workloads. Regulatory fragmentation across data sovereignty regimes forces vendors to engineer jurisdiction-specific deployment architectures. Enterprise procurement teams negotiate contracts based on local compliance certifications and sub-second query performance guarantees.
United States
Enterprise data modernization budgets scale across healthcare systems and financial services firms deploying HIPAA-compliant predictive platforms. The SEC mandates audit-grade documentation for models informing material financial reporting, tightening vendor qualification criteria. Hospital networks in Boston and New York Metro route de-identified patient flows to public cloud nodes while reserving protected health information processing for private environments.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria procure prescriptive analytics for autonomous production scheduling against material constraints. The EU AI Act imposes mandatory algorithmic transparency requirements for automated decision systems, driving demand for certified platforms with built-in explainability frameworks. Frankfurt's financial district anchors hybrid deployment architectures that partition sensitive training data from elastic inference workloads.
India
Hyperscaler facility investments in Mumbai, Hyderabad, and Chennai reduce latency for South Asian enterprises previously restricted to Singapore or European nodes. The RBI and SEBI impose data localization requirements on financial analytics processing domestic transaction records. Bangalore's technology corridor concentrates MLOps engineering talent for production machine learning pipeline deployment.
United Kingdom
London-based asset managers and insurance underwriters negotiate consumption-based pricing for real-time risk analytics rather than seat-based subscriptions. The Information Commissioner's Office enforces GDPR obligations on platforms processing European personal data, requiring redundant legal engineering systems. The Cambridge-Oxford corridor anchors research partnerships between cloud vendors and university statistical modeling groups.
Japan
Manufacturing conglomerates in the Nagoya industrial belt deploy reinforcement learning platforms for supply chain automation with premium pricing tolerance. METI guidelines on AI governance shape enterprise procurement standards for algorithmic accountability and human oversight. Tokyo's financial district drives demand for sub-second fraud detection inference constrained by GPU supply concentration in Taiwan and South Korea.
Analytics As a Service (Aaas) Market Key Industry Players
Cloud hyperscalers and independent analytics specialists split the market along infrastructure-versus-application fault lines. Hyperscalers consolidate control through proprietary silicon and vertically integrated data pipelines, compressing margins for vendors without captive compute capacity. Three archetypes dominate: infrastructure-anchored platforms with backward integration into custom silicon, application-layer specialists with vertical-specific model libraries, and hybrid orchestration providers bridging private training environments with public inference. Competitive moves concentrate on M&A for talent acquisition and strategic partnerships for regulatory certification across GDPR-EU AI Act jurisdictions.
Within the infrastructure-anchored tier, Microsoft Corporation and Amazon Web Services, Inc. exemplify the hyperscaler archetype through Azure and AWS platform dominance. Google LLC occupies a position between infrastructure scale and applied machine learning research. IBM Corporation and Oracle Corporation sit within the enterprise legacy migration segment, anchoring hybrid cloud orchestration for regulated financial services and healthcare workloads. SAP SE represents the ERP-integrated analytics archetype, embedding statistical modeling directly into operational system workflows. These players illustrate how competitive positioning flows from control over compute infrastructure, regulatory certification depth, or vertical application specialization rather than interchangeable feature sets.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| Google LLC |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| Snowflake Inc. |
| Tableau Software, LLC |
| Others |
Cost & Logistics Intelligence
GPU foundry capacity concentrated in Taiwan and South Korea anchors cost structures for real-time inference workloads, concentrating margin pools with hyperscalers possessing captive silicon design capabilities while forcing independent vendors toward application-layer specialization.
Pricing Analysis
The EU AI Act dictates the pricing tier structure through its risk-classification documentation mandates. Three-tier pricing separates certified explainability platforms from standard predictive offerings and economy-grade descriptive dashboards. Price differentiation rests on algorithmic audit depth and cross-border data residency guarantees. Cost compression in the standard tier intensifies as hyperscalers bundle analytics into compute contracts. Healthcare systems demonstrate the lowest price sensitivity due to HIPAA compliance premiums, while education sector procurement shows acute budget constraints.
Supply Chain Analysis
US semiconductor export controls on advanced AI accelerators limit hardware flows to Chinese analytics providers. Inference hardware supply concentrates in Taiwan, South Korea, and the United States. Cloud infrastructure draws from NVIDIA GPU architectures, custom TPU silicon, and ARM-based server processors. Single-source vulnerability around TSMC advanced-node production creates allocation risk for real-time analytics vendors. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with consumption-based metering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in this market hinge on API interoperability standards reshaping vendor switching costs and data gravity dynamics across hybrid deployments.
For Market Incumbents: Harden regulatory certification moats by pre-integrating EU AI Act explainability frameworks and GDPR audit trails into core product architectures. Expand Mumbai and Hyderabad data center capacity to capture latency-sensitive South Asian financial services workloads. Prioritize MLOps talent acquisition in Bangalore's technology corridor to defend against specialized challengers. For New Entrants and Emerging Players: Establish a beachhead in prescriptive analytics for mid-market manufacturing, where reinforcement learning automation remains undersupplied relative to predictive forecasting saturation. Target Indian enterprises with hybrid orchestration tools bridging RBI-mandated on-premises data lakes with elastic public inference. Lead with consumption-based pricing to bypass incumbent seat-license lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward vertical-specific model libraries with embedded regulatory compliance, particularly in healthcare and financial services where certification depth creates durable differentiation. Long-term viability favors vendors controlling both training infrastructure and inference optimization layers. Watch hyperscaler custom silicon roadmaps as the inflection signal for independent vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Synapse and AWS SageMaker API consolidation reduces customer switching costs for enterprise data officers. |
| Acquisition of Specialist Firm | Vertical MLOps talent acquisition in Bangalore accelerates production pipeline deployment for Indian market penetration. |
| Strategic Partnership | EU AI Act certification partnerships with Frankfurt compliance consultants open German industrial manufacturing procurement. |
| Geographic Expansion | Mumbai hyperscaler node investment reduces latency for SEBI-regulated real-time fraud detection workloads. |
| Product Launch | Serverless query engine releases collapse seasonal demand spike costs for retail inventory velocity analytics. |
Research Approach
The analysis maps predictive, prescriptive, descriptive, and real-time analytics service types, each validated through chief data officers, cloud procurement leads, MLOps engineers, and healthcare IT compliance directors. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K hyperscaler disclosures, EU AI Act implementation guidance, and hospital GPO contract databases. Bottom-up triangulation across deployment model adoption curves and top-down cross-check against enterprise data modernization budget flows anchored volume estimates.
Assumptions held regulatory enforcement timelines and GPU supply allocation ratios fixed while varying healthcare predictive analytics penetration rates and hybrid cloud migration velocities across the projection horizon. Segmentation dimensions modeled include deployment architecture, service type complexity, end-use vertical compliance requirements, and regional data sovereignty patterns. CAGRs derived from elasticity-adjusted adoption curves incorporating HIPAA qualification cycle lengths and EU AI Act certification lag times.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT capital expenditure cycles or foundry capacity expansion timelines would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and hyperscaler pricing discipline. Material shifts in US export control scope or EU AI Act high-risk classification criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Patent Analytics Services Market
Analytics
Process Analytics Market
Analytics
HR Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Global Enterprise Data Visualization Platform Market
Analytics
France Contact Center Analytics Market
Analytics
Global Analytics Market
Analytics
Global Enterprise Performance Management Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
Europe Edge Analytics Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
North America Location Analytics Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Data Mining Tools Market