
 Global E-Commerce Analytics Software Market | 2026-2036
Global E-Commerce Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Commerce Analytics Software Market Foresight
India is rewriting competitive dynamics in e-commerce analytics as cloud infrastructure investment surges and digital payment penetration deepens. Adobe Analytics leverages its creative cloud ecosystem to anchor enterprise clients seeking unified customer journey mapping. Google Analytics sustains dominance through free-tier acquisition funnels that convert users into paid enterprise deployments. Shopify Analytics specializes in merchant-native analytics, embedding directly into checkout flows and inventory systems for online retailers.
E-commerce analytics software encompasses platforms that ingest, process, and visualize transactional, behavioral, and operational data from digital commerce environments, typically integrating APIs from payment gateways, inventory systems, and advertising networks to enable real-time decision-making. These systems serve the primary commercial purpose of converting raw clickstream and purchase data into actionable merchandising, marketing, and supply chain intelligence. Cloud-based deployment leads solution architecture as enterprises prioritize elastic compute for peak shopping events, while customer behavior analytics commands margin concentration due to its direct linkage to conversion rate optimization and lifetime value modeling. Marketing analytics represents the fastest-expanding solution type as attribution complexity multiplies across fragmented social commerce channels.
The EU AI Act and GDPR frame product development requirements for analytics vendors serving European online retailers, mandating algorithmic transparency and consent-based data processing that increase engineering overhead but create compliance-based switching costs. The US lacks federal privacy legislation equivalent to GDPR, though the FTC's Section 5 authority and emerging state laws in California and Virginia are fragmenting compliance landscapes for vendors operating across American jurisdictions. Stakeholders must monitor whether India's Digital Personal Data Protection Act enforcement compels localization investments that alter cost structures for cloud-native analytics providers.
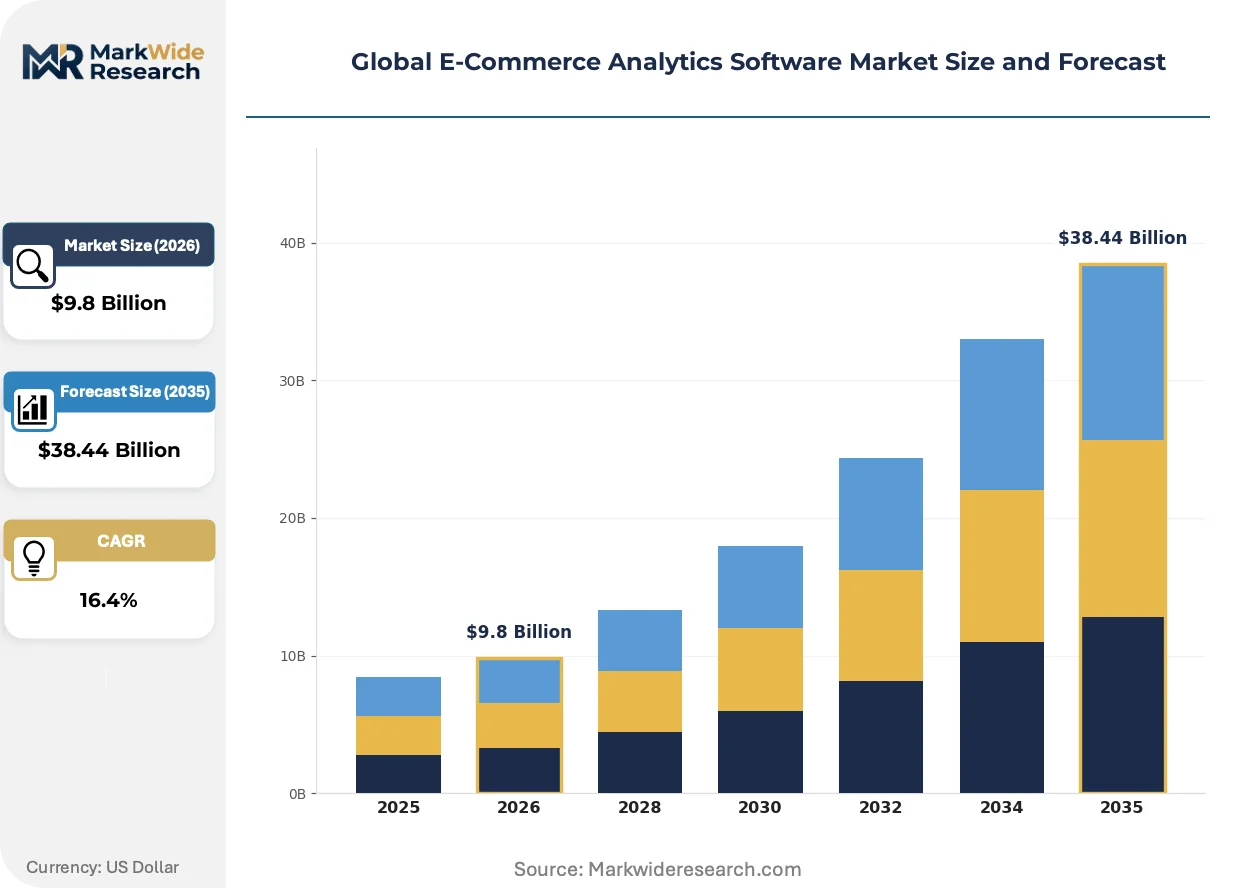
Market Dynamics
Privacy-preserving computation architectures are forcing a fundamental rebuild of e-commerce analytics infrastructure as retailers confront the collision between granular customer tracking and expanding data sovereignty mandates.
Growth Catalysts
- EU AI Act compliance frameworks:Algorithmic transparency requirements are accelerating vendor investment in explainable AI modules that European online retailers now specify in procurement criteria.
- Real-time inventory optimization:Elastic cloud compute enables peak-event surge processing that fashion and electronics merchants deploy during high-velocity shopping periods.
- India:Digital payment penetration and cloud infrastructure expansion are creating addressable merchant bases previously unreachable by enterprise analytics platforms.
Market Restraints
- Consent-based data architecture costs:GDPR-mandated granular consent management layers add engineering overhead that compresses margins for mid-tier analytics providers serving European markets.
- Cloud concentration risk:Hyperscaler dependency in compute and storage creates vendor lock-in exposure for retailers seeking multi-cloud resilience.
- Cross-channel attribution complexity:Fragmented social commerce touchpoints degrade model accuracy, forcing expensive data fusion investments without guaranteed precision gains.
Strategic Opportunities
- Germany:Mittelstand retailers remain underpenetrated by enterprise-grade behavioral analytics, creating whitespace for modular, compliance-native platforms.
- Federated learning convergence:Privacy-preserving machine learning combined with edge computing enables analytics deployment without raw data centralization.
- Embedded finance integration:Buy-now-pay-later data streams offer new behavioral signals that analytics platforms can monetize through lender partnerships.
Industry Challenges
- Differential privacy engineering scarcity:Talent capable of implementing mathematically rigorous anonymization remains concentrated among academic and hyperscaler research labs.
- Legacy ERP integration friction:On-premise inventory and order management systems resist API-native connectivity, extending implementation timelines for unified analytics deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Commerce Analytics Software Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, PaaS Solution Type: Customer Behavior Analytics, Sales Performance Analytics, Inventory Optimization, Marketing Analytics, Website Traffic Analytics Use Case: Personalization, Fraud Detection, Pricing Optimization, Demand Forecasting, Customer Segmentation End User: Online Retailers, Marketplaces, Logistics Providers, Digital Marketers, Payment Gateways |
| Companies Covered | Google Analytics, Adobe Analytics, Salesforce Commerce Cloud, Shopify Analytics, Stackline, Glassbox, Improvado, Glew, Fullstory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Commerce Analytics Software Market Shifts & Advancements
First-party data strategies are displacing third-party cookie dependency as the organizing principle for customer intelligence, redirecting vendor roadmaps toward consent-native collection architectures.
Differential privacy implementations are collapsing the historical trade-off between data utility and individual protection. Retailers in Germany and France are adopting these techniques to retain cohort-level insights while satisfying CNIL and BfDI audit standards. The structural consequence is collapsing the addressable market gap between privacy-compliant and precision-optimized analytics tiers.
The EU AI Act's risk-based classification system is forcing algorithmic documentation requirements that reshape product development cycles. High-risk systems—those determining credit eligibility or dynamic pricing—now require conformity assessments that extend time-to-market by six to twelve months. Vendors are responding by segmenting product lines into regulated and non-regulated feature bundles.
Merchant procurement of analytics is consolidating around outcome-based pricing models that tie vendor compensation to documented conversion lifts or customer lifetime value improvements. This displaces traditional seat-based or event-volume licensing in mid-market segments. The shift is most visible in the United States, where retail CFOs increasingly mandate ROI guarantees in analytics vendor negotiations.
Global E-Commerce Analytics Software Market Segmentation
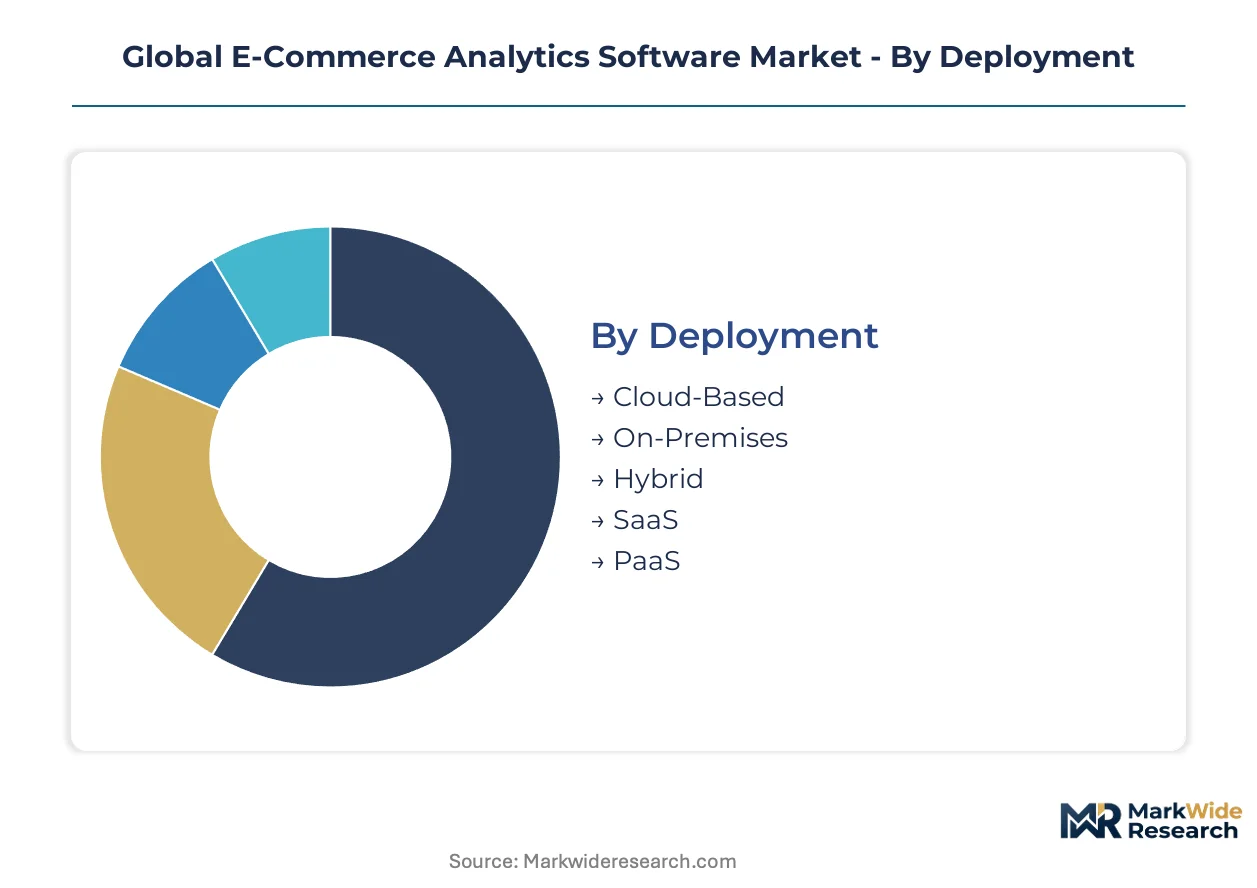
E-commerce analytics software segments reflect divergent technical requirements across deployment architectures, analytical functions, and operational use cases. Procurement patterns vary sharply between cloud-native merchants seeking elastic scalability and legacy retailers maintaining on-premise data sovereignty. Understanding these segment boundaries enables vendors to align product roadmaps with buyer willingness-to-pay and implementation constraints.
Deployment:
Cost tier determines infrastructure commitment depth, with capital expenditure tolerance varying dramatically by merchant scale and regulatory exposure.
- Cloud-Based:Elastic compute architectures process peak-event transaction surges without permanent infrastructure overprovisioning. Fashion and electronics merchants in the United States and Germany deploy these solutions during high-velocity shopping periods when transaction volumes spike unpredictably.
- On-Premises:Localized data processing satisfies stringent data residency mandates from regulators such as Germany's BfDI and France's CNIL. German Mittelstand retailers favor this architecture to maintain direct custody of customer behavioral records under GDPR audit protocols.
- Hybrid:Split processing enables sensitive data localization while leveraging cloud burst capacity for computational intensity.
- SaaS:Subscription pricing lowers entry barriers for mid-market merchants without dedicated data engineering teams.
- PaaS:Developer-centric toolchains allow custom analytics pipeline construction atop managed infrastructure.
Cloud-Based deployment commands the established base. The steepest expansion runs through Hybrid configurations as retailers navigate between performance elasticity and compliance rigidity.
Solution Type:
Application focus separates platforms by which commercial decision they primarily inform—merchandising, marketing, or operations.
- Customer Behavior Analytics:Clickstream processing and session reconstruction identify abandonment patterns and conversion friction points. Online retailers across India's expanding digital commerce sector deploy these tools to optimize checkout flows against rising customer acquisition costs.
- Marketing Analytics:Multi-touch attribution models map fragmented social commerce journeys across Instagram, TikTok, and WhatsApp commerce touchpoints. Digital marketers in the United States face acute pressure to quantify return on ad spend as platform privacy changes degrade traditional tracking precision.
- Sales Performance Analytics:Revenue decomposition by product, channel, and promotional mechanic supports merchandising decisions.
- Inventory Optimization:Demand signal integration across warehouses prevents stockouts and markdown erosion.
- Website Traffic Analytics:Visitor volume and source analysis informs acquisition strategy and technical performance monitoring.
Customer Behavior Analytics anchors current revenue concentration. Marketing Analytics is climbing the fastest as attribution complexity multiplies across emerging social commerce channels.
Use Case:
Volume intensity varies by use case, with real-time personalization requiring substantially higher event processing throughput than periodic demand forecasting.
- Personalization:Real-time recommendation engines ingest behavioral signals to dynamically adjust product rankings, content modules, and promotional offers. Online retailers in fashion verticals deploy these systems to recover margin from returns-heavy categories through improved size and style matching.
- Fraud Detection:Anomaly detection models flag transaction patterns indicative of payment fraud, account takeover, or promotional abuse. Payment gateways across India integrate these capabilities to manage chargeback exposure as digital payment penetration deepens.
- Pricing Optimization:Dynamic price elasticity modeling responds to competitive moves and demand shifts.
- Demand Forecasting:Time-series prediction supports procurement and inventory positioning decisions.
- Customer Segmentation:Cohort clustering enables differentiated marketing treatment and lifetime value estimation.
Personalization commands the established base. Fraud Detection is gaining share fastest as real-time payment volumes expand and regulatory liability frameworks tighten.
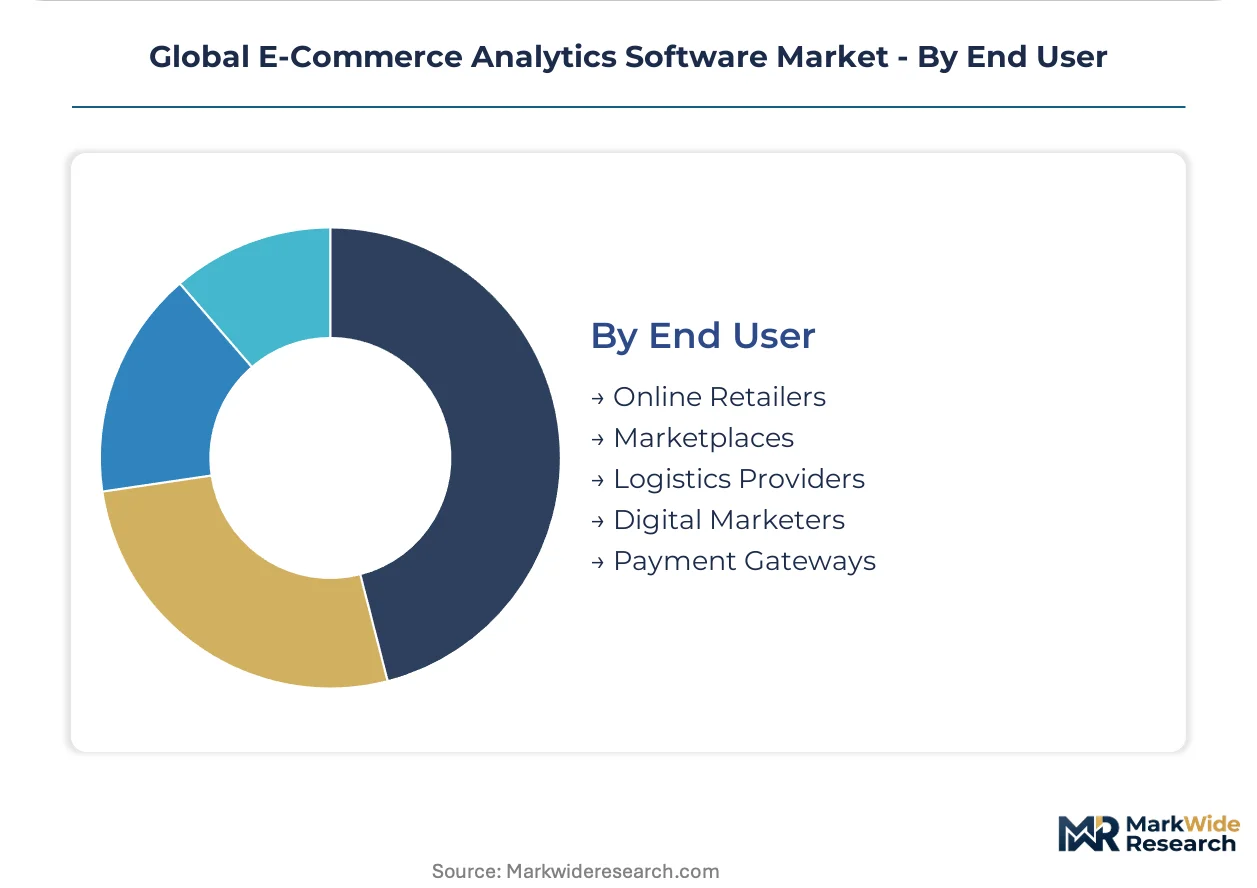
End User:
Customer type dictates integration complexity, with marketplaces requiring multi-tenant architectures that pure retailers do not.
- Online Retailers:Direct-to-consumer merchants require unified visibility across marketing, merchandising, and fulfillment operations. These buyers in Germany and the United States increasingly mandate outcome-based pricing tied to documented conversion improvements.
- Marketplaces:Platform operators serving third-party sellers need seller-facing analytics dashboards and commission optimization tools. India's marketplace ecosystem generates concentrated demand for multi-tenant behavioral analytics as seller bases scale rapidly.
- Logistics Providers:Delivery network operators optimize routing and capacity against e-commerce shipment patterns.
- Digital Marketers:Agency and in-house marketing teams prioritize cross-channel attribution and audience intelligence.
- Payment Gateways:Transaction processors analyze authorization patterns and merchant risk profiles.
Online Retailers command the established base. Marketplaces represent the steepest expansion trajectory as platform commerce models proliferate across emerging digital economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable systems linking Mumbai to Singapore and Frankfurt anchor India's emergence as a data processing hub for cross-border e-commerce analytics workloads.
United States
Hyperscaler cloud regions in Northern Virginia and Oregon process transaction volumes from major online retailers. The FTC's Section 5 enforcement actions against deceptive data practices are reshaping vendor compliance investments. Seattle's enterprise software cluster hosts multiple analytics platforms serving fashion and electronics merchants with real-time personalization engines.
Germany
Mittelstand retailers in Baden-Württemberg and Bavaria are expanding procurement of modular analytics platforms. The BfDI's GDPR audit protocols mandate localized data processing for customer behavioral records. Frankfurt's financial technology corridor is driving demand for fraud detection analytics integrated with payment infrastructure.
India
Digital payment penetration through UPI is generating petabyte-scale transaction datasets for behavioral modeling. The Digital Personal Data Protection Act is compelling cloud-native providers to evaluate localization investments. Bangalore's SaaS ecosystem is incubating merchant-native analytics platforms targeting marketplace sellers.
United Kingdom
London-based luxury retailers are deploying customer journey analytics to optimize omnichannel conversion paths. The Information Commissioner's Office enforcement of consent requirements is elevating procurement criteria for privacy-preserving architectures. Manchester's e-commerce logistics cluster is driving inventory optimization analytics adoption among fulfillment operators.
Japan
Tokyo's department store chains are integrating real-time personalization systems for mobile commerce applications. METI's data free flow with trust initiatives are shaping cross-border analytics governance frameworks. Osaka's manufacturing supply base is extending analytics deployment from B2B procurement into direct-to-consumer channels.
Global E-Commerce Analytics Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with modular APIs. The vendor landscape organizes around three structural tiers: hyperscale cloud providers with bundled analytics, independent software vendors with vertical specialization, and embedded commerce platform natives. Consolidation pressure is intensifying as outcome-based pricing models compress margins for mid-tier players. Strategic moves concentrate on M&A for consent-management capabilities and partnerships with payment networks for transaction data access.
Within the embedded commerce tier, Shopify Analytics exemplifies merchant-native platform integration, while Google Analytics occupies the acquisition-funnel position for free-to-paid conversion. Adobe Analytics represents the creative-cloud-anchored enterprise archetype, bundling customer journey mapping with content production workflows. These three patterns illustrate how distribution channel control shapes competitive positioning across deployment models.
| Leading Market Players |
|---|
| Google Analytics |
| Adobe Analytics |
| Salesforce Commerce Cloud |
| Shopify Analytics |
| Stackline |
| Glassbox |
| Improvado |
| Glew |
| Fullstory |
| Others |
Supply & Pricing Matrix
Hyperscaler cloud regions in the United States and Western Europe anchor compute infrastructure pricing, concentrating margin capture among AWS, Azure, and Google Cloud while compressing margins for independent software vendors dependent on third-party hosting. This upstream concentration forces mid-tier analytics providers into outcome-based pricing models that tie vendor compensation to documented conversion lifts, transferring performance risk downstream to sellers with weaker bargaining positions.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure across European deployments, mandating consent-native architectures and algorithmic transparency modules that add engineering overhead. Three-tier pricing structure across premium, standard, and economy levels separates enterprise clients with dedicated compliance teams from mid-market merchants using shared infrastructure. Price differentiation rests on certification level—ISO 27001 and SOC 2 Type II tiers command 40-60% premiums—and customization depth for legacy ERP integration. Cost compression in the standard tier is intensifying because hyperscalers are bundling baseline analytics into cloud contracts. Mid-market online retailers in India exhibit highest price sensitivity, while German Mittelstand retailers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Upstream feedstock for e-commerce analytics software draws from three concentrated inputs: cloud compute capacity concentrated in the United States, Ireland, and Singapore; specialized semiconductor hardware for AI inference anchored in Taiwan and South Korea; and differential privacy engineering talent clustered in academic and hyperscaler research labs across Switzerland and the United States. Raw material dependencies include GPU accelerators, high-bandwidth memory modules, and cryptographic processing units for privacy-preserving computation. Single-source vulnerability runs through NVIDIA's dominance in training-grade GPUs, creating procurement bottlenecks for vendors building real-time personalization engines. Distribution runs through direct enterprise sales for large merchants, hyperscaler marketplaces for cloud-native deployments, and embedded platform integration for merchant-native solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global e-commerce analytics software is exiting a capital discipline phase as digital payment penetration and cloud infrastructure expansion in India trigger reinvestment cycles. Recovery durability depends on sustained merchant procurement of outcome-based contracts that validate ROI before scale commitments.
For Market Incumbents: Insulate core enterprise relationships by embedding consent-management capabilities acquired through targeted M&A, neutralizing the threat from modular compliance-native challengers in Germany. Deepen vertical integration into edge computing infrastructure to reduce hyperscaler dependency and capture margin currently flowing to cloud providers. Prioritize certification investment in ISO 27701 privacy information management to maintain procurement eligibility under tightening EU AI Act enforcement.
For New Entrants and Emerging Players: Build out federated learning architectures that enable analytics deployment without raw data centralization, targeting the whitespace in German Mittelstand retail where legacy ERP integration friction has slowed incumbent penetration. Focus initial commercial traction on marketplace sellers in India, the most penetrable segment given rapid seller base expansion and underdeveloped native analytics. Pursue partnership-led go-to-market with payment networks to access transaction data streams that strengthen behavioral signal quality.
For Investors and Strategic Acquirers: Capital is best deployed toward privacy-preserving computation specialists with differential privacy engineering depth and established CNIL or BfDI audit relationships, positioned for 5-10 year structural demand as data sovereignty mandates expand beyond Europe. Long-term viability favors vendors with hybrid deployment flexibility spanning cloud elasticity and on-premise localization. Monitor enforcement patterns under India's Digital Personal Data Protection Act as the critical inflection signal for localization investment requirements that would reshape cost structures for cloud-native providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Consent-Management Specialist | GDPR and EU AI Act audit readiness secures procurement eligibility with German Mittelstand retailers. |
| Payment Network Data Partnership | Buy-now-pay-later transaction streams unlock behavioral signals for lender-analytics platform monetization. |
| Federated Learning Platform Launch | Privacy-preserving machine learning enables CNIL-compliant analytics without raw data centralization. |
| Edge Computing Infrastructure Investment | Localized processing capacity reduces hyperscaler dependency and latency for real-time personalization. |
| ISO 27701 Certification Program | Privacy information management certification meets escalating enterprise procurement criteria under EU AI Act. |
Research Methodology
Desk research of SEC filings from hyperscaler cloud providers, venture financing disclosures from analytics startups, and regulatory guidance documents from the European Commission preceded structured interviews with CTOs at online retailers, data protection officers at German Mittelstand companies, and integration specialists at systems integrators. Secondary validation drew from EU AI Act implementation guidance, GDPR enforcement actions by CNIL and BfDI, and cloud infrastructure capex disclosures. Bottom-up merchant spend estimates were triangulated against top-down software market sizing.
Assumptions held fixed across the modeling period include sustained enforcement of GDPR and EU AI Act compliance requirements, continued hyperscaler cloud market concentration, and stable digital payment penetration growth trajectories in India. Segmentation dimensions modeled encompass deployment architecture, solution type, and end-user category, with regional adoption patterns capturing divergent regulatory exposure. CAGRs were derived from trend extrapolation adjusted for policy-driven inflection points. Industry-specific forecast inputs included merchant payment volume growth and cloud infrastructure expansion timelines.
Practitioners should monitor enforcement patterns under India's Digital Personal Data Protection Act and differential privacy standardization efforts at ISO for early signals of forecast revision. Cross-checking against hyperscaler cloud revenue disclosures and merchant software spend surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Sweden ICT Market
Analytics
China Contact Center Analytics Market
Analytics
Identity Analytics Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Global Healthcare Cloud Based Analytics Market
Analytics
Marketing Analytics Market
Analytics
Embedded Analytics Market
Analytics
Practice Analytics Market
Analytics
United Kingdom Business Intelligence Market
Analytics
Multi-Touch Attribution Market
Analytics
Workforce Analytics Market
Analytics
Global Systems of Insight Market
Analytics
Supply Chain Analytics Market
Analytics
Global Data Prep Market
Analytics
US Video Analytics Market