
 Application Metrics and Monitoring Tools Market | 2026-2036
Application Metrics and Monitoring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Application Metrics and Monitoring Tools Market Outlook
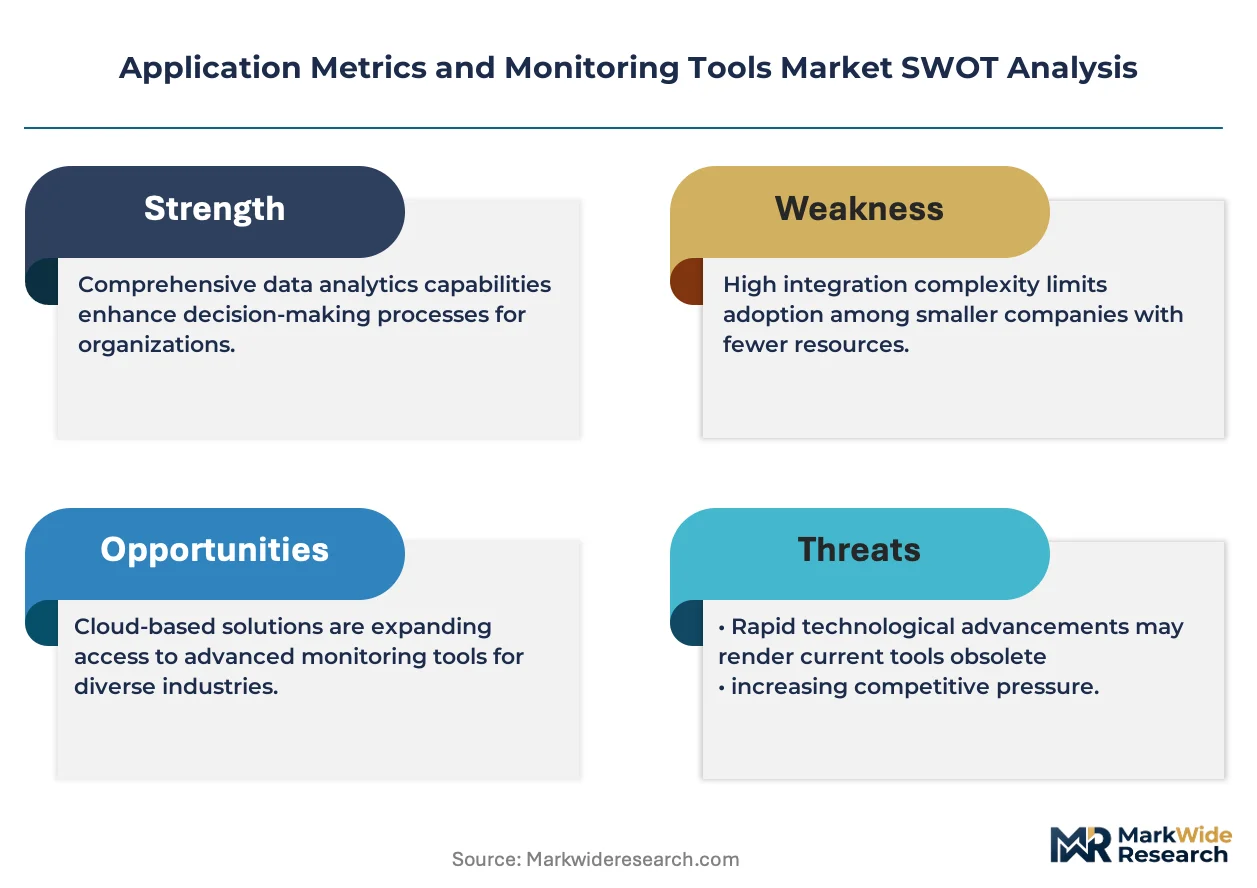
Subscription-based financing and usage-metered leasing is tilting competitive dynamics toward vendors with elastic infrastructure economics. Datadog, Inc. leverages its cloud-native architecture to capture expanding workloads without proportional cost scaling. Dynatrace, Inc. anchors its position through AI-driven causal analytics that reduce mean-time-to-resolution for enterprise clients. Microsoft Azure Monitor competes by bundling observability into existing enterprise agreements, creating captive demand channels across hybrid estates.
Application metrics and monitoring tools constitute software platforms that ingest distributed telemetry—traces, logs, metrics, and events—at millisecond granularity to detect latency anomalies, resource saturation, and dependency failures across microservice architectures. Their primary commercial purpose is to sustain digital service reliability for revenue-critical applications where downtime carries direct financial penalty. Cloud Monitoring and APM currently occupy the highest-margin tiers of the product landscape, as these categories command premium pricing for real-time stream processing and automated root-cause analysis. Hybrid Cloud deployment models are gaining structural share as regulated industries retreat from pure public-cloud strategies, while On-Premises solutions retain durable positions in sovereign data environments with strict residency mandates.
FCC guidelines on communications infrastructure resilience and EU GDPR data-processing requirements are elevating compliance-grade observability from optional capability to procurement prerequisite. HIPAA obligations in US healthcare deployments and BIS cybersecurity frameworks in India are similarly tightening audit-trail standards for application telemetry. Stakeholders must weigh whether to build compliant instrumentation stacks in-house or absorb vendor-managed certifications that accelerate market access.
Market Dynamics
Cloud-native telemetry architectures are fragmenting procurement authority between infrastructure teams and application developers, creating dual-track purchasing patterns that favor modular, API-first observability platforms over monolithic suites.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making systems in financial services require continuous model performance monitoring, expanding addressable demand for real-time inference telemetry.
- Manufacturing-IT convergence:Germany's industrial software corridor drives granular application tracing requirements as operational technology networks merge with enterprise IT stacks.
- OpenTelemetry standardization:Vendor-neutral instrumentation protocols reduce switching costs and accelerate multi-cloud deployment patterns across enterprise technology estates.
Market Restraints
- Telemetry data storage costs:Petabyte-scale log retention for HIPAA-compliant healthcare deployments strains operational budgets and compresses vendor margins.
- Cloud hyperscaler bundling:Microsoft Azure Monitor and AWS CloudWatch create captive demand channels that restrict independent vendor access to enterprise accounts.
- Sovereign data residency requirements:India's BIS cybersecurity frameworks and GDPR localization rules fragment infrastructure economics across jurisdictional boundaries.
Strategic Opportunities
- Edge computing telemetry:Distributed IoT deployments in smart manufacturing create greenfield demand for lightweight, low-latency monitoring agents.
- Carbon-aware observability:EU Green Deal reporting requirements position energy-efficiency analytics as a compliance-adjacent product extension.
- AI-driven causal analysis:Automated root-cause identification reduces mean-time-to-resolution and supports premium pricing for enterprise service level agreements.
Industry Challenges
- Observability engineer scarcity:Specialized skills in distributed tracing and SRE practices command compensation premiums that inflate implementation costs.
- Legacy mainframe integration:Financial institutions struggle to unify telemetry from COBOL-era systems with containerized microservice architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Metrics and Monitoring Tools Market |
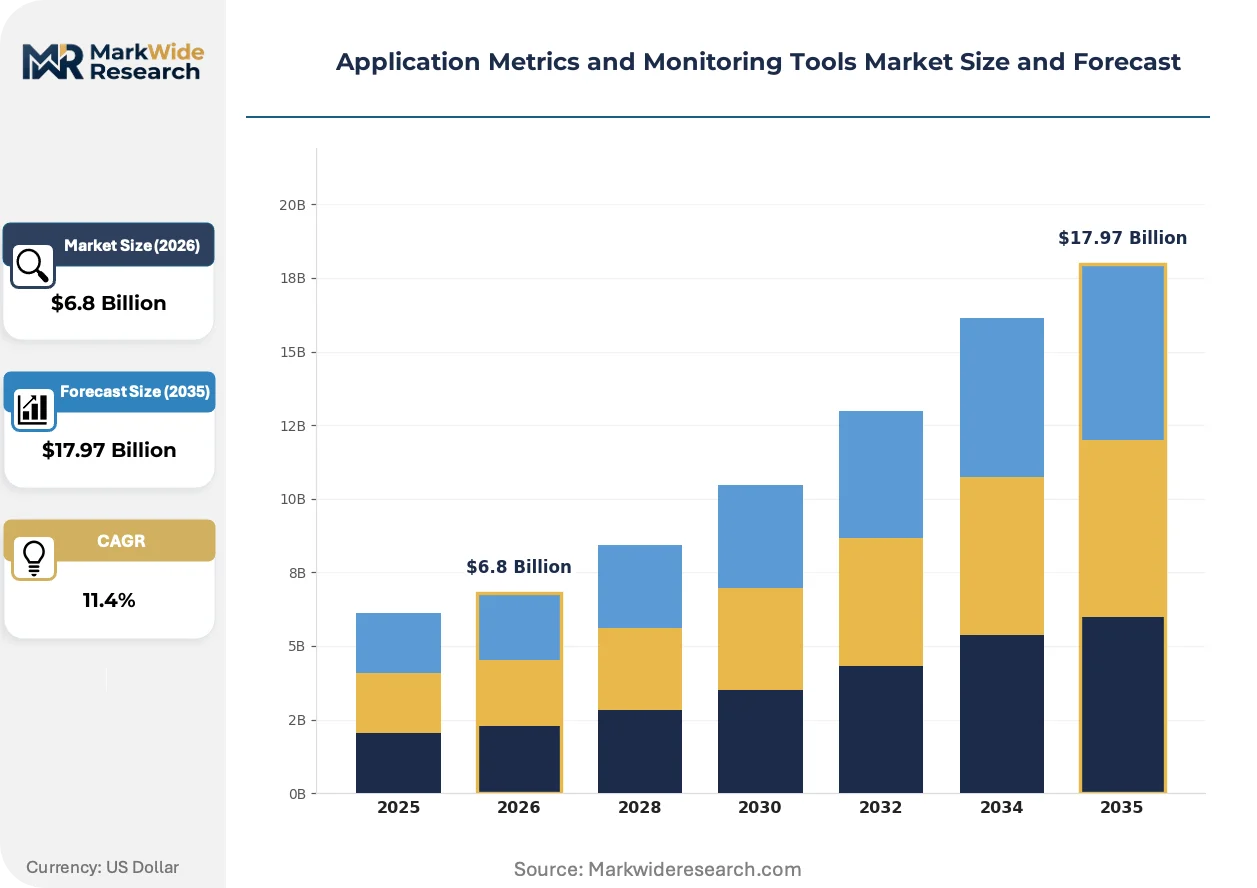
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
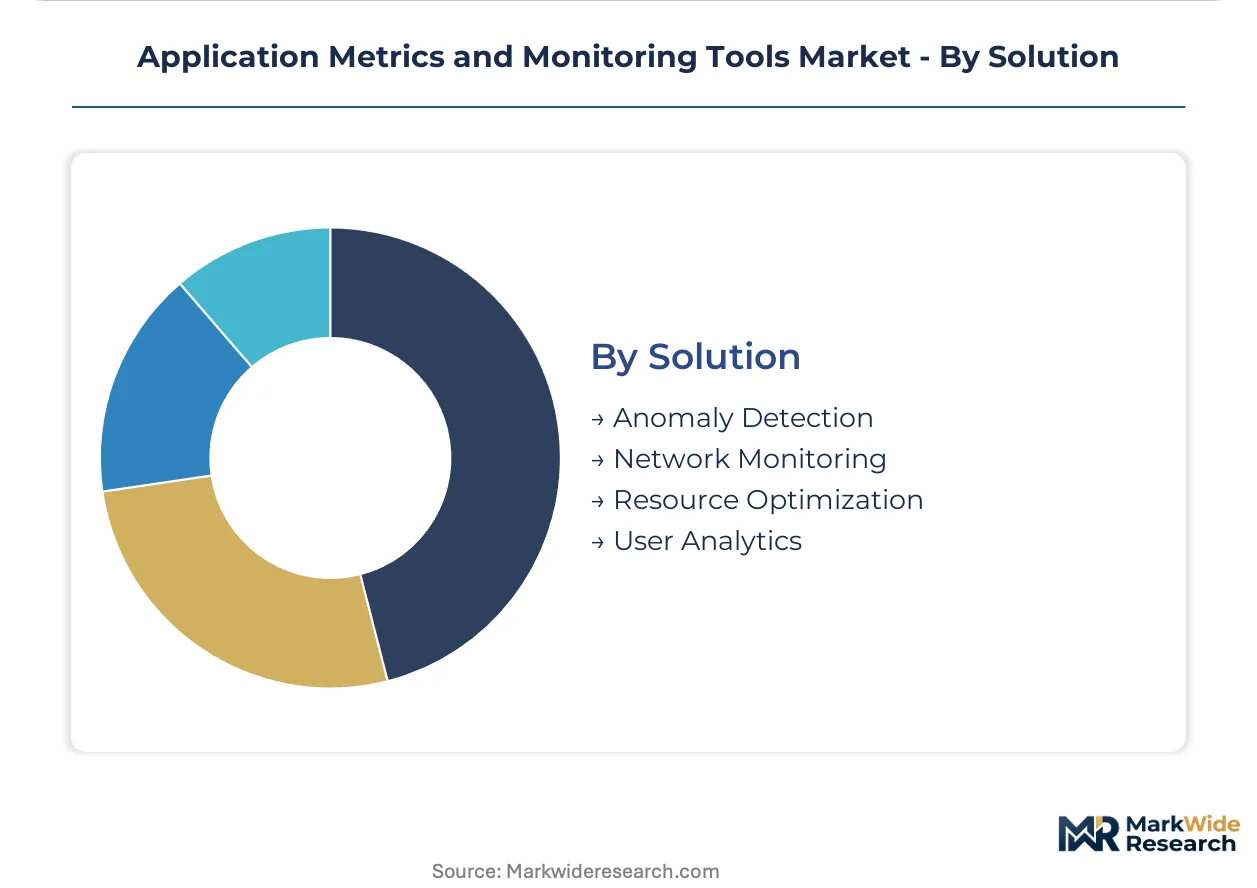
| Segmentation | Product Type: Log Management, Performance Monitoring, Cloud Monitoring, APM End User: IT Services, Financial Institutions, E-Commerce, Telecommunications Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Solution: Anomaly Detection, Network Monitoring, Resource Optimization, User Analytics |
| Companies Covered | Datadog, Inc., New Relic, Inc., Dynatrace, Inc., Splunk Inc., AppDynamics, Google Cloud Operations, Microsoft Azure Monitor, Amazon CloudWatch, Elastic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Metrics and Monitoring Tools Market Strategic Shifts
Observability platforms are absorbing adjacent capabilities—security analytics, cost optimization, carbon tracking—to escape commoditization in core metrics ingestion. This capability expansion redefines competitive boundaries and buyer evaluation criteria.
OpenTelemetry is hybridizing proprietary agent architectures by establishing a common instrumentation layer across cloud providers. Financial services firms in Frankfurt and Singapore deploy vendor-neutral collectors to avoid lock-in. This standardization compresses differentiation timelines for agent-based monitoring suites and forces vendors to compete on analytics rather than data capture.
GDPR Article 32 security-processing requirements are elevating audit-grade telemetry from optional feature to procurement prerequisite. Healthcare and banking procurement teams now mandate cryptographically verifiable log integrity before contract execution. European deployments face the tightest compliance timelines as supervisory authorities finalize technical implementation guidance.
Consumption-based pricing models are displacing perpetual licenses as buyers demand elasticity aligned with workload volatility. SaaS-native vendors capture this shift through usage-metered contracts while legacy incumbents struggle to restructure revenue recognition. Germany's Mittelstand manufacturing sector exhibits the fastest adoption of metered observability spending.
Application Metrics and Monitoring Tools Market Segmentation
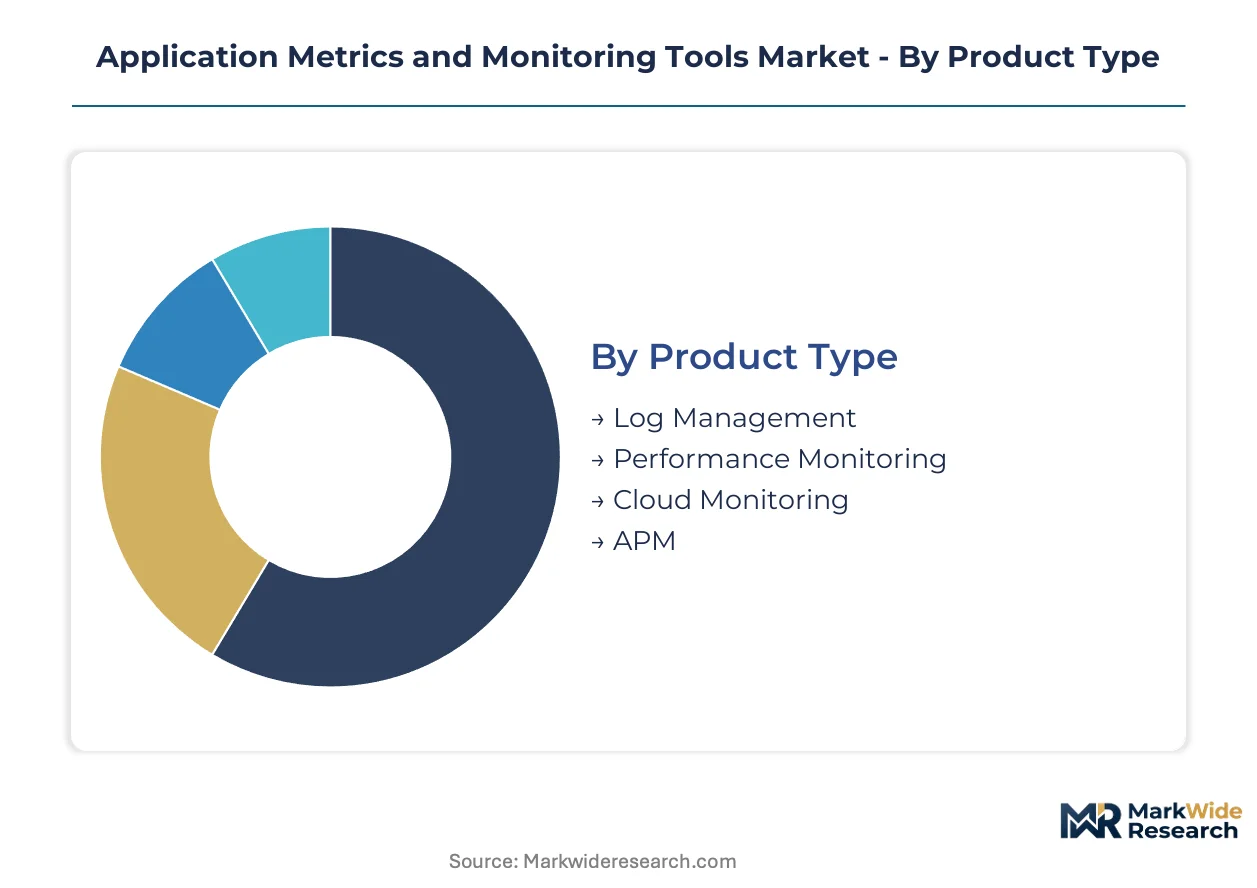
Segmentation in the Application Metrics and Monitoring Tools Market reveals how procurement authority fragments across infrastructure teams, application developers, and compliance officers. Buyers evaluate telemetry platforms through divergent lenses—cost predictability, real-time granularity, or audit-grade data residency—creating distinct competitive battlegrounds for vendors.
Product Type:
After-sales service intensity varies sharply across product categories, with Cloud Monitoring and APM demanding continuous algorithm tuning and escalation support while Log Management operates closer to commodity infrastructure.
- Cloud Monitoring:Real-time ingestion engines process distributed telemetry across multi-cloud estates with millisecond latency SLAs. Financial institutions in Frankfurt and Singapore deploy these platforms for revenue-critical payment infrastructure where downtime carries direct financial penalty.
- APM:Automated root-cause analysis engines trace dependencies across microservice architectures to compress mean-time-to-resolution. Manufacturing-IT convergence in Germany's industrial software corridor drives acute demand for granular transaction tracing as operational technology networks merge with enterprise IT.
- Log Management:Petabyte-scale retention systems with cryptographically verifiable integrity for HIPAA and GDPR audit trails.
- Performance Monitoring:Synthetic testing and real-user measurement for web application experience optimization.
By volume, Log Management leads due to universal infrastructure instrumentation requirements. By growth pace, Cloud Monitoring is ahead as regulated industries retreat from pure public-cloud strategies toward hybrid telemetry architectures.
End User:
Cost tier stratification separates enterprise buyers with dedicated observability engineering teams from mid-market adopters purchasing through bundled cloud contracts.
- Financial Institutions:Compliance-grade telemetry mandates under EU AI Act and GDPR Article 32 drive procurement of cryptographically verifiable log integrity. Automated decision-making systems require continuous model performance monitoring, expanding addressable demand for real-time inference telemetry in Frankfurt and Singapore trading hubs.
- IT Services:Multi-tenant observability platforms with tenant-isolated data pipelines and white-label analytics interfaces. Managed service providers across India's technology corridors absorb vendor-managed certifications to accelerate market access for healthcare and banking clients.
- Telecommunications:FCC resilience guidelines and 5G network slicing telemetry for service assurance.
- E-Commerce:Peak-load elasticity requirements and cart-abandonment tracing for revenue optimization.
By volume, IT Services leads through multi-tenant aggregation. By growth pace, Financial Institutions is expanding most quickly under regulatory compulsion.
Deployment Model:
Application concentration determines infrastructure economics, with sovereign data environments commanding premium pricing for jurisdictional compliance.
- Hybrid Cloud:Split telemetry pipelines route sensitive audit trails to private infrastructure while streaming performance metrics to public cloud analytics engines. India's BIS cybersecurity frameworks and GDPR localization rules fragment deployment patterns across jurisdictional boundaries, favoring architectures that maintain data residency flexibility.
- On-Premises:Air-gapped observability stacks for classified government and defense workloads with strict network segmentation.
- Public Cloud:Native integrations with AWS CloudWatch and Microsoft Azure Monitor creating captive demand channels.
- Private Cloud:Dedicated tenant environments for healthcare HIPAA deployments with single-tenant isolation requirements.
By volume, Public Cloud leads through hyperscaler bundling. By growth pace, Hybrid Cloud is climbing the fastest as regulated industries retreat from pure public-cloud strategies.
Solution:
Margin tier differentiation separates premium AI-driven causal analytics from commoditized threshold-based alerting.
- Anomaly Detection:Machine learning models baseline normal system behavior to flag deviation patterns without predefined thresholds. EU AI Act compliance mandates for automated decision-making systems in financial services require continuous model performance monitoring, expanding addressable demand for real-time inference telemetry.
- User Analytics:Session reconstruction and journey mapping for digital experience optimization in e-commerce conversion funnels.
- Network Monitoring:Flow analysis and packet inspection for telecommunications infrastructure resilience under FCC guidelines.
- Resource Optimization:Carbon-aware workload scheduling aligning compute placement with renewable energy availability for EU Green Deal reporting.
By volume, Network Monitoring leads through telecommunications infrastructure scale. By growth pace, Anomaly Detection is gaining share fastest as AI-driven causal analysis commands premium pricing for enterprise service level agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Application metrics and monitoring tools flow disproportionately from US-headquartered vendors toward European and Asian financial centers, creating persistent trade surpluses in software services that regulatory fragmentation now complicates.
United States
Financial institutions in New York and Chicago drive demand for real-time payment infrastructure telemetry under SEC oversight. HIPAA obligations compress margins for healthcare deployments requiring petabyte-scale log retention. Silicon Valley cloud-native vendors anchor supply chains serving domestic hyperscaler ecosystems.
Germany
Manufacturing-IT convergence in Baden-Württemberg and Bavaria generates granular application tracing requirements as operational technology networks merge with enterprise IT. EU AI Act compliance mandates from Frankfurt supervisory authorities elevate audit-grade telemetry to procurement prerequisite. Industrial software corridors around Stuttgart and Munich concentrate deployment expertise.
United Kingdom
London trading hubs require continuous model performance monitoring for automated decision-making systems under FCA guidelines. GDPR Article 32 security-processing requirements drive cryptographically verifiable log integrity mandates. The City of London's fintech density creates concentrated demand for hybrid cloud observability architectures.
India
BIS cybersecurity frameworks fragment infrastructure economics across jurisdictional boundaries, favoring sovereign data residency solutions. Bangalore and Hyderabad technology corridors absorb vendor-managed certifications to accelerate healthcare and banking market access. IT services multi-tenancy concentrates procurement authority among managed service providers.
Singapore
Monetary Authority of Singapore guidelines on financial infrastructure resilience elevate compliance-grade observability for trading systems. The city-state's position as Asia-Pacific wealth management hub concentrates demand for real-time inference telemetry. Hybrid deployment patterns route sensitive audit trails to private infrastructure while streaming performance metrics to public cloud analytics.
Application Metrics and Monitoring Tools Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the telemetry pipeline. The vendor base organizes around three archetypes: cloud-native SaaS vendors with elastic infrastructure economics, legacy incumbents restructuring toward consumption-based pricing, and hyperscaler bundlers leveraging captive enterprise agreements. Consolidation pressure intensifies as M&A activity absorbs point-solution vendors into broader observability suites, while strategic partnerships between telemetry platforms and consulting firms accelerate enterprise deployment velocity.
Within the cloud-native tier, Datadog, Inc. and Dynatrace, Inc. occupy positions exemplifying elastic architecture advantages and AI-driven causal analytics respectively. Microsoft Azure Monitor represents hyperscaler bundling dynamics that create captive demand channels across hybrid estates. These three anchors illustrate how competitive positioning fragments between independent SaaS economics and ecosystem-integrated distribution.
| Leading Market Players |
|---|
| Datadog, Inc. |
| New Relic, Inc. |
| Dynatrace, Inc. |
| Splunk Inc. |
| AppDynamics |
| Google Cloud Operations |
| Microsoft Azure Monitor |
| Amazon CloudWatch |
| Elastic |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in US West Coast hyperscaler data centers is compressing infrastructure economics and forcing observability vendors toward usage-metered contracts that align revenue recognition with actual workload consumption. This utilization signal reshapes both supplier consolidation patterns and buyer negotiation leverage across enterprise procurement cycles.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium AI-driven analytics, standard threshold-based alerting, and economy log retention tiers. Price differentiation rests on certification grade—GDPR Article 32 audit trails command substantial premiums over standard HIPAA-compliant configurations—and volume scale, with petabyte-scale deployments securing metered discounts. Pricing pressure stems from hyperscaler bundling, as Microsoft Azure Monitor and AWS CloudWatch embed observability into existing enterprise agreements. Mid-market manufacturing segments exhibit highest price sensitivity, while financial institutions in Frankfurt and Singapore demonstrate lowest elasticity due to regulatory compulsion.
Supply Chain Analysis
Upstream semiconductor feedstock concentration in Taiwan, South Korea, and the United States shapes telemetry infrastructure availability. Specialized AI accelerators and high-bandwidth memory modules constitute critical component dependencies, with supply chain risk centering on single-source vulnerability for advanced inference chips. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with managed service providers in India's technology corridors absorbing vendor-managed certifications to accelerate healthcare and banking market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of observability engineers proficient in distributed tracing and SRE practices is constraining deployment velocity and inflating implementation costs for enterprise buyers. This capability gap creates asymmetric advantage for vendors with embedded automation and low-code configuration tools.
For Market Incumbents: Harden defensive positioning through backward integration into OpenTelemetry collector development, reducing dependency on third-party instrumentation. Acquire boutique consulting firms specializing in legacy mainframe telemetry unification to capture financial services modernization budgets. Capacity addition in Germany's industrial software corridor addresses manufacturing-IT convergence demand while preempting regional challenger emergence. For New Entrants and Emerging Players: Build out edge computing telemetry capabilities for smart manufacturing deployments in Baden-Württemberg, where incumbent coverage remains thin. Target carbon-aware observability extensions for EU Green Deal compliance reporting, leveraging energy-efficiency analytics as a differentiated entry wedge. Channel partnerships with Indian managed service providers accelerate healthcare and banking market access without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-native vendors with consumption-based pricing models and elastic infrastructure economics. Long-term viability favors platforms absorbing adjacent capabilities—security analytics, cost optimization, carbon tracking—to escape core metrics commoditization. Acquisition target archetype: point-solution vendors with OpenTelemetry-native architectures and established presence in sovereign data environments. The signal to watch is hyperscaler marketplace traction, indicating ecosystem-integrated distribution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| OpenTelemetry-Native Platform Development | Vendor-neutral instrumentation reduces switching costs and accelerates multi-cloud deployment patterns across Frankfurt and Singapore financial centers. |
| AI-Driven Causal Analytics Acquisition | Automated root-cause identification commands premium pricing for enterprise service level agreements in manufacturing-IT convergence scenarios. |
| Edge Computing Telemetry Expansion | Lightweight monitoring agents capture greenfield demand from distributed IoT deployments in Germany's industrial software corridor. |
| Carbon-Aware Observability Launch | EU Green Deal reporting requirements position energy-efficiency analytics as compliance-adjacent product extension with pricing power. |
| Hyperscaler Marketplace Integration | Native AWS and Azure listings create captive demand channels that restrict independent vendor access to enterprise accounts. |
Study Parameters
Cross-validation between primary interviews with platform engineers, IT procurement officers, SRE team leads, and compliance officers and secondary sources including SEC filings, hyperscaler capex disclosures, and EU regulatory implementation guidance anchors the qualitative findings. Bottom-up telemetry platform deployment estimates triangulate against top-down enterprise software spending analyses across the projection horizon.
Calibration against historical adoption curves for cloud-native architectures informs the analytical framework. Segmentation dimensions modeled encompass deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted revenue recognition patterns and workload volatility assumptions, with OpenTelemetry standardization velocity and EU AI Act compliance timelines as industry-specific forecast inputs.
Stress conditions across hyperscaler bundling intensity, sovereign data residency fragmentation, and observability engineer wage inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and standardization adoption curves. Cross-checking against external benchmarks including enterprise SaaS spending surveys and cloud infrastructure utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
India Contact Center Analytics Market
Analytics
Mobile Analytics Market
Analytics
Legal Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Iraq ICT Market
Analytics
Greece ICT Market
Analytics
Big Data Analytics Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
Global Data Analysis Software Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Capacity Management Analytics Market
Analytics
BI and Analytics Market
Analytics
Contact Center Analytics Market