
 France Contact Center Analytics Market | 2026-2036
France Contact Center Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
France Contact Center Analytics Market Insights
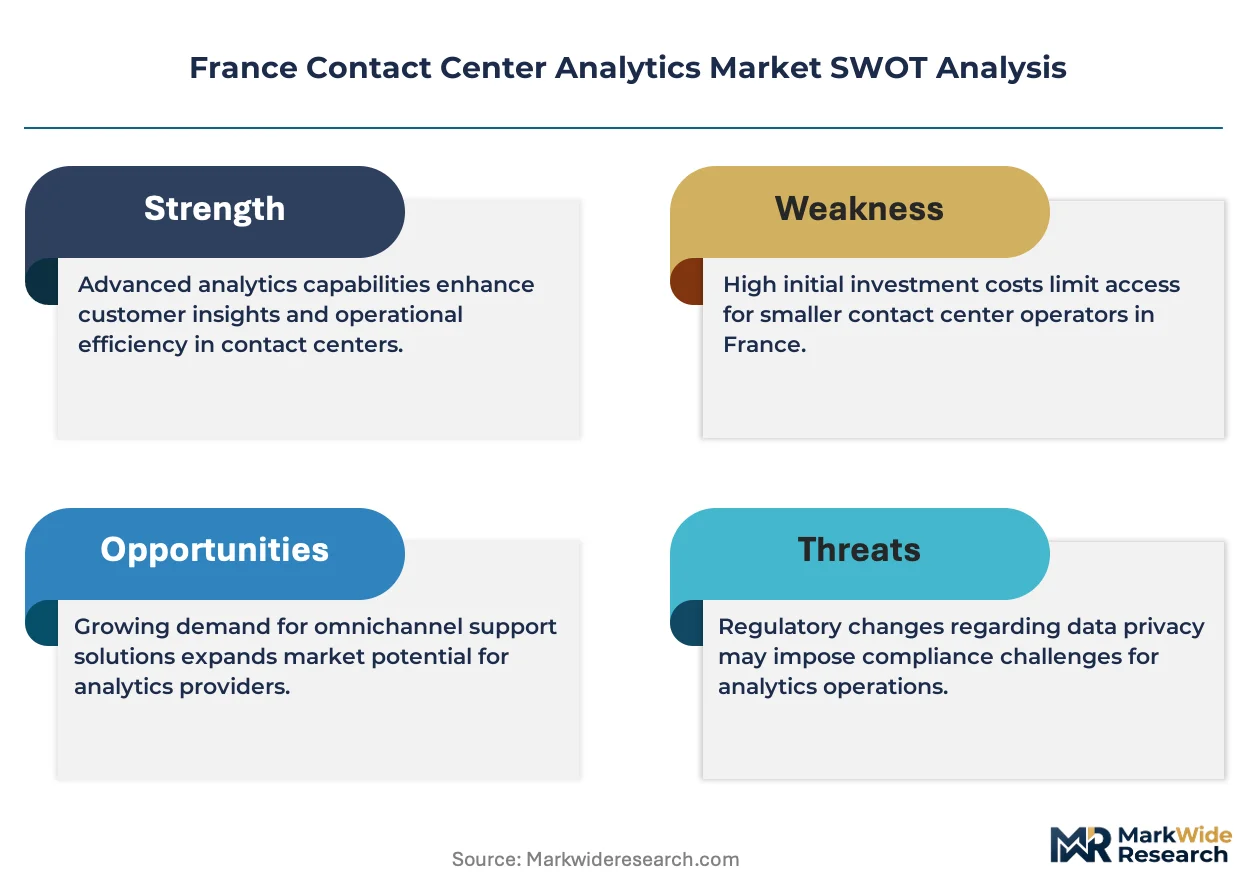
GDPR enforcement is pivoting the France contact center analytics sector toward consent-aware architecture and data lineage tooling. NICE Ltd anchors its position through workforce optimization platforms that sustain compliance with French data residency rules. Genesys International Corporation competes via cloud-native routing that integrates analytics across hybrid estates. SAP SE differentiates through embedded CRM analytics that leverage existing enterprise footprints in Lyon and Marseille banking hubs.
France contact center analytics encompasses software systems that capture, process, and interpret voice, text, and operational data from customer interactions, typically processing audio streams at 8-16 kHz sampling rates and applying natural language processing to transcribe and classify sentiment in under 200 milliseconds for real-time agent guidance. The primary commercial purpose is to reduce average handle time, improve first-contact resolution, and surface regulatory risks during live conversations. Speech analytics occupies the largest technology segment due to persistent voice-channel dominance in French service industries, while predictive analytics grows fastest as insurers deploy churn models trained on interaction metadata. Cloud deployment leads in new implementations, though hybrid configurations retain significant share among Île-de-France financial institutions with legacy on-premises telephony investments.
CNIL guidelines on automated decision-making and the EU AI Act's risk-classification framework shape product roadmaps for algorithmic transparency in French customer service environments. The country's national data protection regulator enforces strict purpose-limitation rules that constrain how interaction recordings train machine learning models. Stakeholders must monitor forthcoming EU-level algorithmic accountability standards that will determine whether emotion-detection features require explicit opt-in mechanisms in French consumer contracts.
Market Dynamics
The France contact center analytics market pivots on CNIL's strict interpretation of GDPR Article 6 and Article 22, which mandates granular consent documentation for every automated processing of customer interaction data. French financial institutions now embed compliance checkpoints directly into real-time analytics pipelines, transforming regulatory adherence from a back-office function into a competitive architecture.
Growth Catalysts
- GDPR Article 22 enforcement:The CNIL's algorithmic decision-making guidelines compel insurers to deploy explainable AI layers atop predictive churn models, expanding analytics software procurement.
- Speech analytics adoption:French banks process 8-16 kHz audio streams to extract sentiment and risk indicators, satisfying both customer experience targets and conduct supervision mandates from the ACPR.
- Cloud migration in Île-de-France:Paris-based financial services firms consolidate telephony estates onto cloud-native platforms, generating demand for hybrid monitoring solutions that bridge legacy PBX and modern APIs.
Market Restraints
- Data residency requirements:The EU Data Act and French sovereignty rules restrict cross-border processing of interaction recordings, complicating multi-tenant SaaS architectures.
- Technical debt in legacy telephony:On-premises Avaya and Cisco installations in Lyon and Marseille banking hubs resist API-based analytics integration without expensive middleware.
- Skill scarcity in computational linguistics:The domestic talent pool for French-language NLP model tuning remains thin relative to English-language capabilities.
Strategic Opportunities
- EU AI Act risk classification:France's early transposition of emotion-detection prohibitions creates first-mover advantage for vendors offering transparent, non-manipulative interaction scoring.
- Provence-Alpes-Côte d'Azur outsourcing expansion:Marseille's emerging multilingual hub status attracts English and Arabic customer service operations, requiring analytics localization.
- Real-time agent guidance convergence:Integration of speech analytics with workforce management platforms opens white space for unified compliance-performance dashboards.
Industry Challenges
- Consent revocation complexity:CNIL-mandated granular opt-out mechanisms fragment training datasets, degrading machine learning model accuracy for sentiment classification.
- Hybrid estate integration:Synchronizing metadata between cloud contact center platforms and on-premises CRM systems in established banking IT stacks demands expensive custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Contact Center Analytics Market |
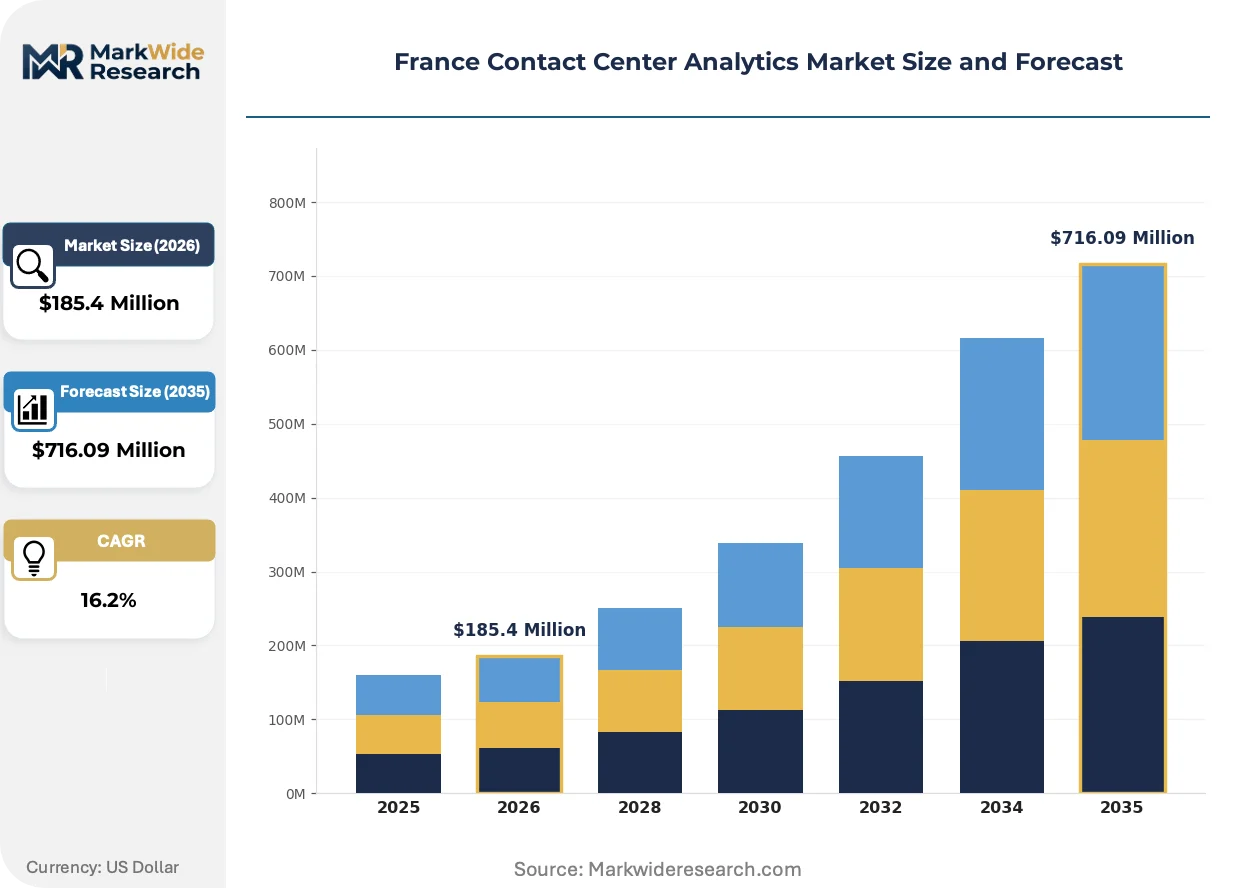
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $716.09 Million |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Speech Analytics, Text Analytics, Predictive Analytics, Workforce Optimization Deployment: Cloud, On-Premises, Hybrid, Multi-Cloud End User: BFSI, Retail, Healthcare, Telecommunications Solution: Reporting Tools, Real-Time Monitoring, Customer Feedback, Quality Management |
| Companies Covered | Oracle Corp, 8x8 Inc, NICE Ltd, CallMiner, Five9 Inc, Genesys International Corporation, SAP SE, Stratifyd, Cisco Systems Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Contact Center Analytics Market Trends and Innovations
Natural language processing architectures are compressing transcription latency below 200 milliseconds, enabling live agent guidance that was technically impossible three years ago. French vendors now compete on explainability metrics rather than raw accuracy, reflecting CNIL's interpretability requirements.
Transformer-based speech models are automating real-time entity extraction and sentiment scoring during live conversations. Major insurers in Paris and Lyon deploy these systems to flag regulatory risk phrases before agents conclude calls. The technology is automating compliance documentation that previously required post-call manual review, compressing quality assurance cycles from days to seconds.
The EU AI Act's prohibition on emotion recognition in workplace and educational settings is reshaping product roadmaps for French customer service environments. Vendors now emphasize behavioral pattern detection over affective state inference to avoid high-risk system classification. Banking procurement teams in Île-de-France prioritize solutions with built-in algorithmic impact assessments, anticipating delegated act requirements.
Subscription pricing for analytics modules is displacing perpetual license models among mid-market French insurers. Procurement teams now demand consumption-based billing tied to interaction volumes rather than seat counts. This shift is most visible in Occitanie and Nouvelle-Aquitaine, where regional mutual insurers lack capital for upfront enterprise software investments.
France Contact Center Analytics Market Segmentation
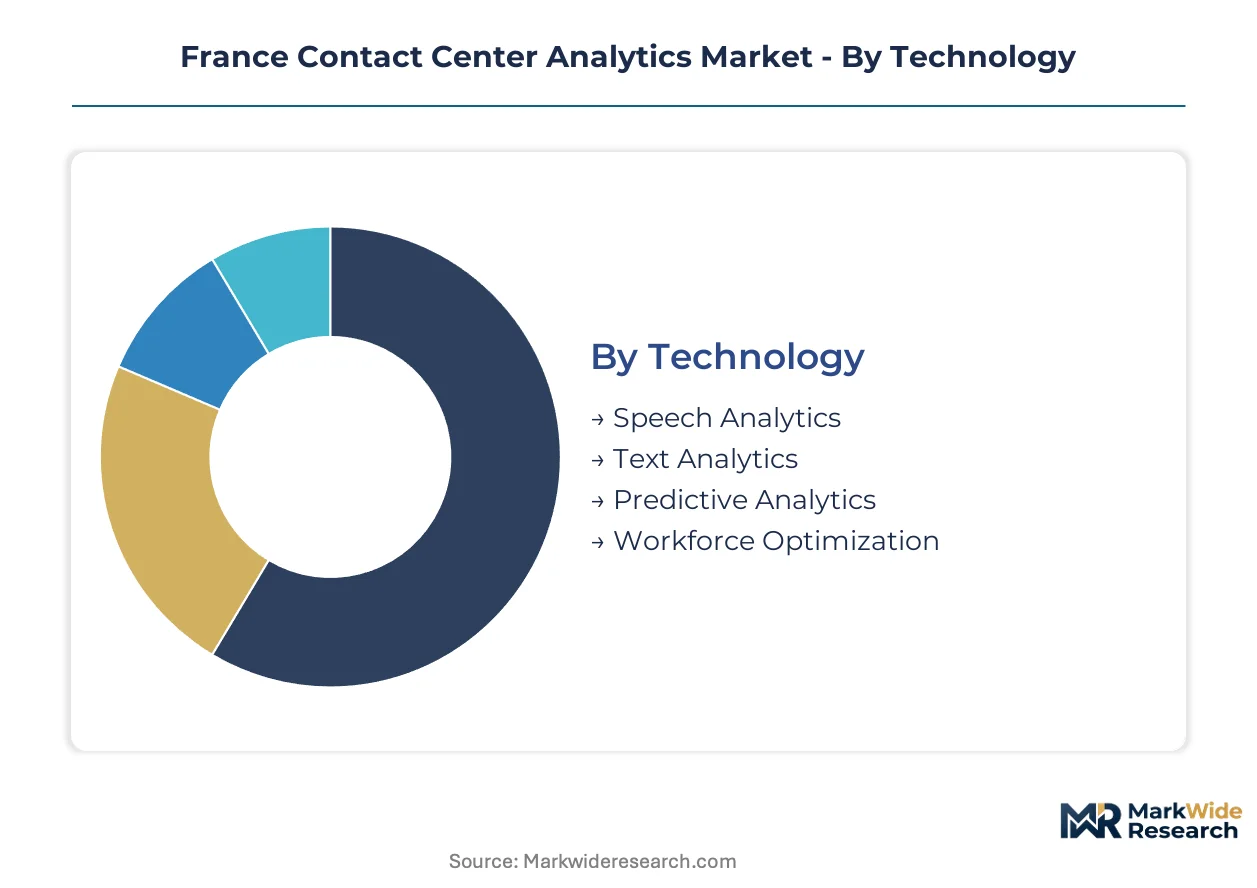
Segmentation in the France contact center analytics market reveals how compliance architecture, cloud migration patterns, and vertical-specific use cases reshape procurement priorities across French enterprises. Understanding these divides exposes where vendors must localize features for CNIL consent workflows versus where standardized platforms suffice.
Technology:
Upgrade cycles in French contact centers now center on replacing legacy quality monitoring with AI-native stacks that embed GDPR compliance by design.
- Speech Analytics:Processes 8-16 kHz audio streams to extract sentiment, entity recognition, and risk indicators in under 200 milliseconds. French banks in Paris and Lyon deploy these systems to satisfy ACPR conduct supervision mandates while compressing quality assurance cycles. Demand concentrates among insurers retrofitting post-call review pipelines with real-time guidance layers.
- Predictive Analytics:Churn models and next-best-action engines trained on interaction metadata. The segment climbs fastest as mutual insurers in Occitanie deploy cloud-native forecasting to offset thin IT capital reserves.
- Text Analytics:NLP pipelines for chat, email, and social media classification. Regional banks in Nouvelle-Aquitaine adopt these for asynchronous channel monitoring.
- Workforce Optimization:Scheduling and performance management modules integrated with analytics feeds. Established BFSI players in Marseille layer this atop existing WFM investments.
Speech analytics sits at the top of the volume ranking, with predictive analytics climbing the fastest.
Deployment:
Cost tier differentiation separates capital-constrained regional insurers from Paris-based institutions with legacy telephony sunk costs.
- Cloud:Native SaaS architectures with API-first analytics ingestion. New implementations in Île-de-France financial services favor this model for rapid scaling without data center investment.
- Hybrid:Bridges cloud contact center platforms with on-premises CRM and telephony estates. Lyon and Marseille banking hubs demand this configuration to preserve Avaya and Cisco PBX investments while adding real-time monitoring.
- On-Premises:Fully captive infrastructure for sovereign data control. Declining share but persists among defense-adjacent contractors with security clearance requirements.
- Multi-Cloud:Analytics workloads distributed across two or more hyperscaler environments. Emerging pattern among multinational French insurers mitigating vendor lock-in.
Cloud deployment leads new procurement volumes, with hybrid configurations expanding most quickly among established financial institutions.
End User:
Application intensity varies sharply by sector regulatory exposure and customer interaction frequency.
- BFSI:Banking and insurance dominates absolute spend. CNIL consent documentation requirements and ACPR supervision mandates compel granular analytics pipelines with embedded explainability layers.
- Telecommunications:High interaction volumes drive demand for automated quality management at scale. Orange and SFR procurement teams prioritize real-time sentiment classification for retention campaigns.
- Healthcare:Patient service centers deploy analytics for appointment optimization and complaint triage. GDPR health data provisions constrain model training more severely than in other sectors.
- Retail:E-commerce and omnichannel service operations adopt text analytics for chat-heavy customer journeys. Seasonal volume spikes favor consumption-based pricing models.
BFSI commands the largest technology budget allocation, with telecommunications gaining share fastest on pure interaction volume growth.
Solution:
Customer type segmentation separates enterprise buyers seeking unified platforms from mid-market purchasers assembling best-of-breed modules.
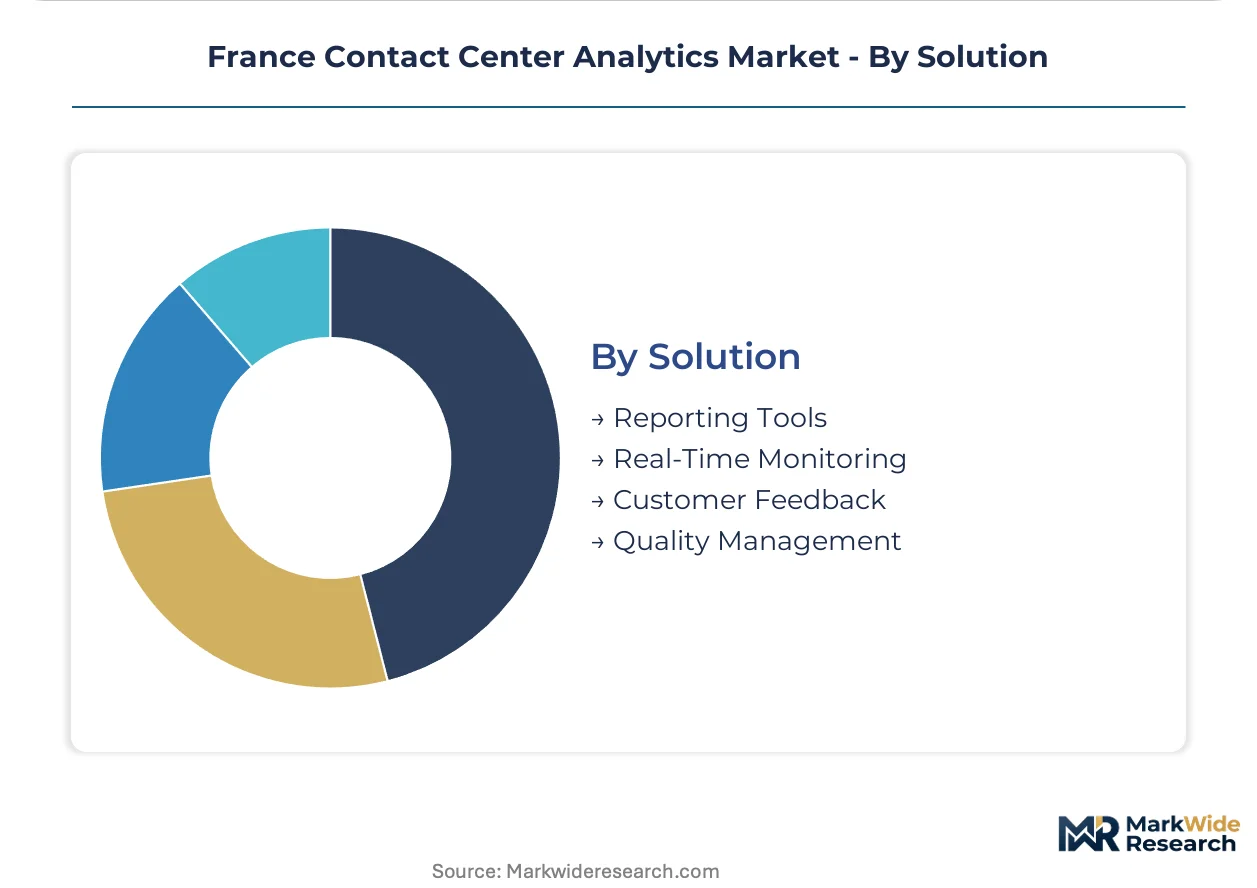
- Real-Time Monitoring:Live agent guidance systems with sub-200ms transcription latency. Major French insurers deploy these to flag regulatory risk phrases during active conversations, automating compliance documentation that previously required post-call manual review.
- Quality Management:Evaluation forms, calibration workflows, and coaching modules. Traditional backbone of contact center operations now integrating with AI scoring to reduce evaluator headcount.
- Reporting Tools:Dashboard and visualization layers for operational KPIs. Standardized offerings with limited differentiation; procurement favors embedded analytics within larger platforms.
- Customer Feedback:Post-interaction survey and voice-of-customer aggregation. Regional mutual insurers in Provence-Alpes-Côte d'Azur adopt these to compensate for thinner competitive intelligence resources.
Real-time monitoring leads solution category investment, with quality management expanding most rapidly as legacy evaluation systems reach replacement age.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris concentrates France's contact center analytics talent pool, with engineering and data science graduates from École Polytechnique and Télécom Paris feeding vendor R&D labs and enterprise implementation teams across Île-de-France.
Île-de-France
Paris-based financial institutions drive demand for real-time monitoring solutions as cloud migration accelerates among legacy banking estates. CNIL's strict GDPR Article 22 interpretation compels insurers to deploy explainable AI layers for automated decision-making documentation. La Défense and Paris city center host the densest concentration of vendor professional services teams supporting enterprise deployments.
Auvergne-Rhône-Alpes
Lyon's banking hub sustains hybrid deployment demand as institutions preserve Avaya and Cisco PBX investments while adding API-based analytics. The ACPR's conduct supervision mandates push regional insurers toward speech analytics for risk phrase detection. Grenoble's tech ecosystem contributes NLP engineering talent for French-language model tuning.
Provence-Alpes-Côte d'Azur
Marseille's emerging multilingual hub status attracts English and Arabic customer service operations requiring localized analytics. Regional mutual insurers adopt consumption-based pricing models to offset thin IT capital reserves. The port city's outsourcing expansion creates demand for workforce optimization platforms bridging legacy and cloud estates.
Occitanie
Mutual insurers in Toulouse and Montpellier deploy predictive analytics for churn modeling trained on interaction metadata. GDPR health data provisions constrain model training more severely than in other sectors. The region's agricultural cooperative banking networks favor modular procurement over unified platform investments.
Nouvelle-Aquitaine
Regional banks adopt text analytics for asynchronous channel monitoring across chat and email customer journeys. Bordeaux's wine trade and tourism sectors generate seasonal volume spikes favoring elastic cloud deployment. The area's smaller institutional scale drives preference for SaaS architectures over captive infrastructure investment.
France Contact Center Analytics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the France contact center analytics market. Enterprise software vendors leverage existing CRM footprints to embed analytics modules, while standalone speech analytics vendors compete on transcription latency and French-language model accuracy. The vendor base separates into three strategic archetypes: cloud-native platform providers, legacy workforce optimization incumbents, and AI-native analytics specialists. Competitive moves center on API ecosystem expansion and vertical-specific compliance certification rather than price-led displacement.
Within the legacy workforce optimization tier, NICE Ltd and Genesys International Corporation exemplify vendors with entrenched French banking relationships. SAP SE occupies a position among diversified enterprise software providers embedding analytics within broader CRM estates. Cloud-native specialists including Five9 Inc and 8x8 Inc represent the API-first architecture gaining share among mid-market insurers. These named entities anchor competitive dynamics without dominating absolute market position, as procurement decisions increasingly hinge on CNIL compliance certification and hybrid integration capability rather than brand recognition alone.
| Leading Market Players |
|---|
| Oracle Corp |
| 8x8 Inc |
| NICE Ltd |
| CallMiner |
| Five9 Inc |
| Genesys International Corporation |
| SAP SE |
| Stratifyd |
| Cisco Systems Inc |
| Others |
Pricing and Supply Chain Analysis
CNIL-mandated granular consent documentation requirements are forcing French financial institutions to restructure procurement contracts toward modular SaaS consumption, compelling vendors to unbundle enterprise suites and compress implementation timelines to capture constrained IT budgets.
Pricing Analysis
Bundled platform licensing versus unbundled per-module subscriptions splits the France contact center analytics market into two pricing archetypes. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and CNIL compliance certification depth. Pricing pressure stems from regional mutual insurers in Occitanie and Nouvelle-Aquitaine demanding consumption-based billing tied to interaction volumes rather than seat counts. Mid-market BFSI players exhibit highest price sensitivity, while Paris-based systemic banks prioritize compliance assurance over cost optimization.
Supply Chain Analysis
Reverse logistics for cloud infrastructure refurbishment and hardware lifecycle management flows through Dublin, Amsterdam, and Frankfurt hyperscaler hubs serving French deployments. Software supply chains draw from Ireland's EU data residency infrastructure, India's NLP engineering talent pools, and Germany's enterprise telephony manufacturing. Single-source vulnerability concentrates in French-language speech model training datasets, where domestic computational linguistics expertise remains thin. Distribution runs through systems integrators in La Défense and Lyon, with direct vendor relationships dominating enterprise accounts above five hundred seats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in France contact center analytics rests on SaaS consumption models displacing perpetual licenses, capturing recurring revenue while reducing customer acquisition costs through embedded compliance features that accelerate procurement cycles.
For Market Incumbents: Hedge against cloud-native displacement by embedding explainable AI documentation layers directly into real-time monitoring pipelines, addressing CNIL's algorithmic transparency mandates before competitors achieve certification. Fortify hybrid integration capabilities to preserve installed-base relationships with Lyon and Marseille banking hubs resisting full cloud migration. Prioritize API ecosystem expansion over feature proliferation to capture mid-market insurers assembling best-of-breed stacks. For New Entrants and Emerging Players: Launch via vertical-specific compliance certification rather than horizontal platform breadth, targeting Occitanie mutual insurers underserved by legacy workforce optimization vendors. Penetrate the Provence-Alpes-Côte d'Azur multilingual hub expansion as Marseille attracts English and Arabic customer service operations requiring localized analytics. Anchor go-to-market strategy around consumption-based pricing that aligns with thin IT capital reserves at regional institutions. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native analytics specialists possessing French-language model accuracy advantages and pre-built CNIL compliance workflows. Long-term viability favors vendors bridging hybrid estate complexity rather than pure cloud plays, as Île-de-France financial institutions preserve decade-long telephony investments. Monitor EU AI Act delegated act releases on emotion-detection prohibitions as inflection indicator for product roadmap obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| CNIL Compliance Certification Investment | Pre-built GDPR Article 22 documentation layers accelerate procurement with ACPR-supervised institutions. |
| Hybrid Integration Platform Development | API bridges between cloud analytics and Avaya Cisco PBX estates capture Lyon Marseille banking demand. |
| French-Language NLP Model Acquisition | Computational linguistics talent scarcity makes proprietary training data a defendable moat. |
| Consumption-Based Pricing Transition | Interaction-volume billing aligns vendor revenue with Occitanie mutual insurer cash flow constraints. |
| Real-Time Agent Guidance Convergence | Unified compliance-performance dashboards open white space between workforce management and analytics vendors. |
Research Methodology
Multiple input streams — executive interviews with vendor product managers, procurement discussions with BFSI IT directors, and validation sessions with CNIL compliance officers — were reconciled against secondary sources including ACPR supervision reports, CNIL algorithmic decision-making guidelines, and hyperscaler regional infrastructure disclosures. Bottom-up sizing from individual vendor deployments across Paris Lyon Marseille banking hubs was triangulated with top-down demand estimates derived from French insurance sector IT spending patterns.
Data-stream reconciliation anchored the forecast framework across technology deployment and end-use segmentation dimensions, modeling cloud hybrid and on-premises pathways alongside BFSI telecommunications and healthcare vertical adoption curves. Speech analytics transcription latency benchmarks and predictive analytics model deployment rates served as industry-specific forecast inputs, with CAGRs derived from trend extrapolation against regulatory milestone timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or CNIL consent revocation mechanism redesign. Practitioners should monitor delegated act releases on high-risk system classification and ACPR conduct supervision guidance updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Assortment Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
Global Sales Performance Management Market
Analytics
Brazil Big Data Analytics Market
Analytics
Europe Network and Location Analytics Market
Analytics
BI and Analytics Market
Analytics
Italy Geospatial Analytics Market
Analytics
Video Analytics Market
Analytics
Global Network Analytics Market
Analytics
Global Systems of Insight Market
Analytics
Audio and Video Analytics Software Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Global Operational Analytics Market
Analytics
Active Data Warehousing Market
Analytics
Global Industrial Analytics Market
Analytics
Weather Data Services Market