
 Plant Design Software Market | 2026-2036
Plant Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Design Software Market Insights
The EU Green Deal is restructuring capital allocation across European process industries, compelling operators to validate plant layouts against lifecycle carbon budgets before breaking ground. Bentley Systems leverages its OpenPlant portfolio to anchor digital twin workflows for water and energy infrastructure clients. AVEVA Group competes through deep specialization in cloud-native engineering data management for hydrocarbon processing. Hexagon PPM dominates the heavy fabrication segment with interoperable CAD and asset information platforms that sustain multi-contractor project execution.
Plant design software encompasses engineering applications that generate, validate, and manage spatial layouts, piping networks, and equipment configurations for industrial facilities, typically operating with millimeter-grade coordinate precision and clash-detection algorithms. These systems serve primarily to compress front-end engineering design cycles and eliminate field rework through virtual commissioning. Cloud-based deployment is capturing the fastest expansion as owner-operators demand remote collaboration across distributed engineering teams, while on-premises installations retain dominance in defense and classified energy projects where data sovereignty overrides accessibility. Fully integrated systems command the deepest margin pools by binding design data to procurement and maintenance workflows, though modular systems are gaining traction among mid-sized engineering firms seeking staged capability investment.
The EPA enforces Risk Management Program requirements that mandate digital documentation of process safety information, directly elevating software fidelity standards for US chemical and petrochemical designers. REACH compliance through ECHA obliges European manufacturers to embed substance tracking into plant design databases from the conceptual phase. ISO 15926 data exchange standards shape interoperability expectations that determine vendor qualification for international energy projects. Stakeholders must weigh cloud migration timelines against the contractual liability exposure of hosting proprietary process designs on third-party infrastructure.
Market Dynamics
Cloud-native engineering platforms are compressing front-end design cycles by enabling real-time clash detection and multi-contractor coordination, forcing incumbent vendors to rearchitect legacy architectures or cede share to SaaS-native competitors.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:Facility operators across Germany and the Netherlands must validate plant layouts against lifecycle carbon budgets before construction permits issue, mandating digital twin-enabled design validation.
- Intelligent 3D modeling adoption:Oil and gas engineering firms deploy these platforms to eliminate field rework and accelerate project handover timelines.
- ISO 15926 data exchange standards:Interoperability mandates for international energy projects elevate software fidelity requirements, disqualifying non-compliant vendors from major capital contracts.
Market Restraints
- Specialized engineering talent scarcity:Millimeter-grade coordinate precision and clash-detection algorithm expertise concentrates in Germany, the US, and Japan, constraining vendor expansion.
- On-premises infrastructure lock-in:Defense and classified energy projects in the US and France demand data sovereignty, fragmenting vendor R&D across deployment architectures.
- Legacy system integration complexity:Brownfield modernization projects in European chemical conglomerates require costly middleware development to bridge 1990s-era CAD databases with modern platforms.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Greenfield capacity buildout creates first-mover advantage for vendors offering modular, staged-capability plant design systems to mid-sized engineering firms.
- Digital twin convergence with asset maintenance:Binding design data to procurement and maintenance workflows opens recurring revenue streams beyond perpetual licenses.
- EPA Risk Management Program digitization mandates:US chemical and petrochemical designers must upgrade software fidelity to document process safety information, creating compliance-driven replacement cycles.
Industry Challenges
- Cloud migration liability exposure:Owner-operators face contractual risk when hosting proprietary process designs on third-party infrastructure, slowing SaaS transition timelines.
- REACH substance tracking embedding:European manufacturers must reconfigure plant design databases from conceptual phase to trace hazardous materials, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Design Software Market |
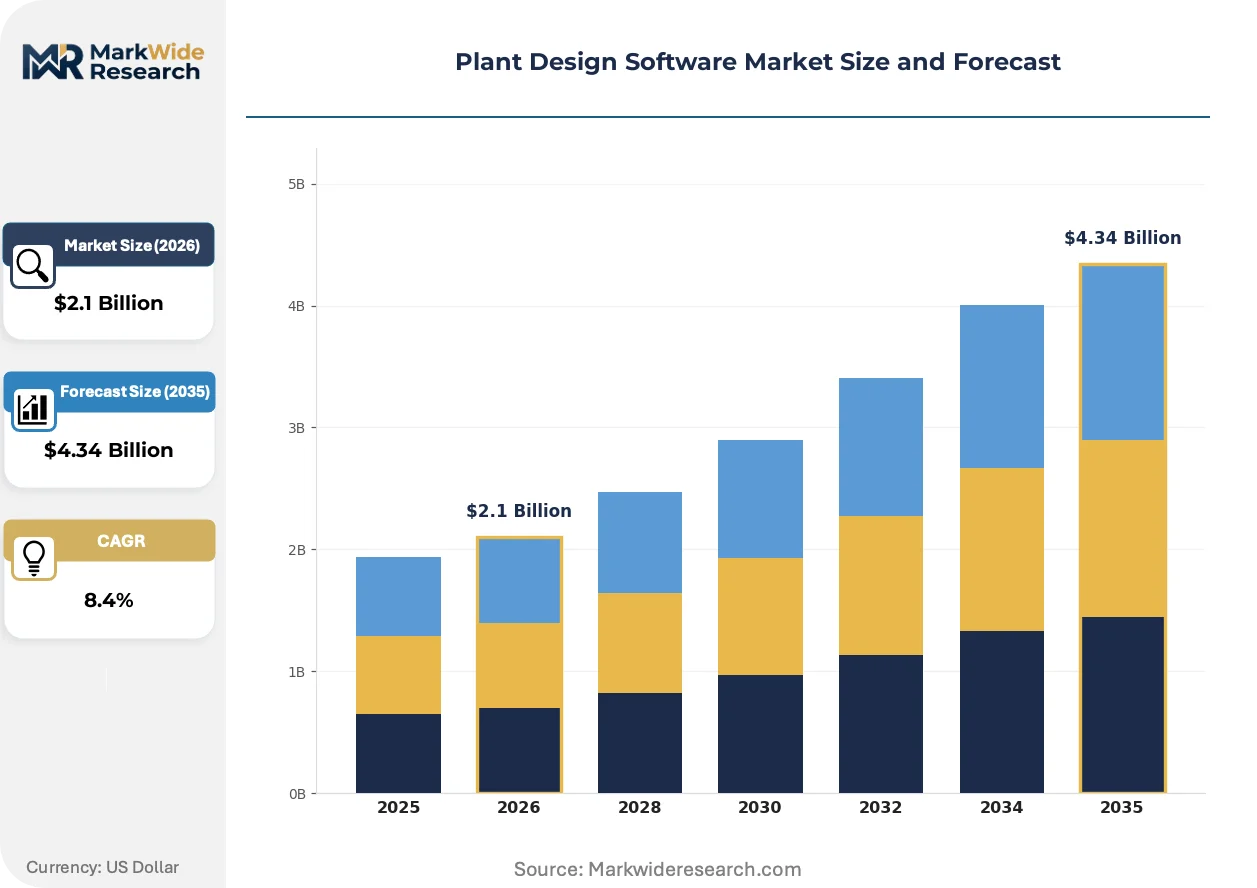
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, CAD Software, BIM Tools, Simulation Software Deployment: On-Premises, Cloud-Based, Hybrid, Desktop End User: Engineering Firms, Construction Companies, Manufacturing Plants, Architects Integration Level: Standalone Solutions, API Integration, Fully Integrated Systems, Modular Systems |
| Companies Covered | Bentley Systems, AVEVA Group, Hexagon PPM, Autodesk, Siemens, Dassault Systèmes, Intergraph, CADWorx, Kubotek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Design Software Market Trends and Innovations
Generative design algorithms and real-time rendering engines are redefining competitive differentiation, compressing the gap between conceptual layout and constructible documentation while enabling non-specialist stakeholder review.
AI-assisted piping route optimization is integrating physics-based simulation with reinforcement learning to auto-generate clash-free layouts. Mid-sized engineering firms in Germany and South Korea adopt these tools to compete for lump-sum EPC contracts previously reserved for larger competitors. The technology is integrating procurement data feeds to auto-size equipment specifications against real-time vendor catalogs, collapsing the traditional design-procurement handoff delay.
EPA enforcement of digital process safety documentation tightens liability standards for US chemical facility designers. The regulation mandates searchable, version-controlled hazard analysis records linked to spatial equipment coordinates. Petrochemical operators in Texas and Louisiana accelerate software replacement cycles to avoid consent decree exposure, prioritizing platforms with built-in audit trails and electronic signature workflows.
Subscription pricing models displace perpetual licenses as owner-operators demand consumption-aligned cost structures. Engineering procurement officers in the Middle East and Southeast Asia negotiate seat-based SaaS contracts with burst capacity for peak project phases. This shift concentrates vendor attention on annual recurring revenue metrics and customer success functions, rewarding platforms with superior onboarding and training architectures over those with deeper legacy feature sets.
Plant Design Software Market Segmentation
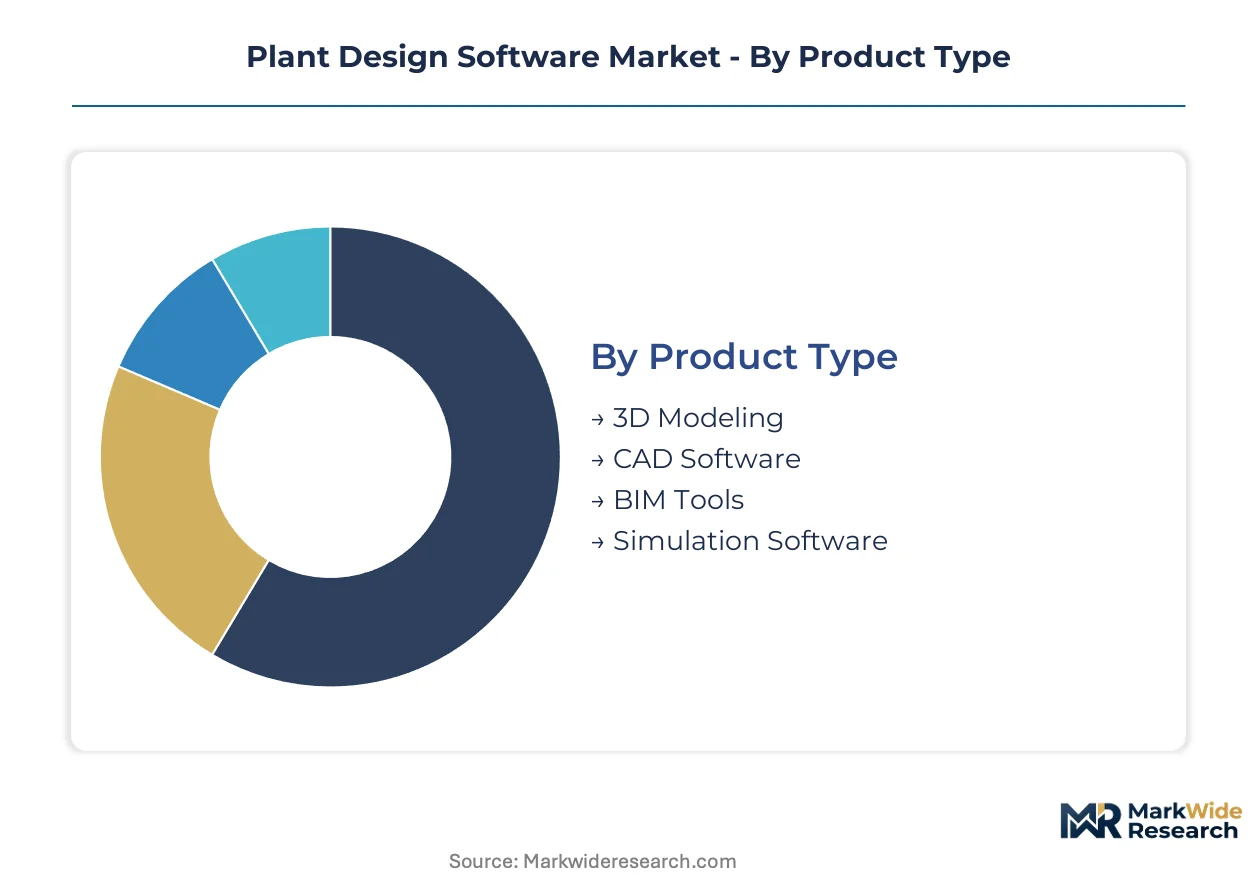
Plant design software segmentation reveals how vendor R&D investment splits across deployment architectures, integration depths, and user workflows. Engineering procurement officers select capabilities based on project scale, data sovereignty requirements, and brownfield integration complexity.
Product Type:
Supply concentration in 3D modeling and BIM tools pulls licensing revenue toward platforms with clash-detection algorithms and millimeter-grade coordinate precision.
- 3D Modeling:Intelligent spatial layout engines generate equipment configurations and piping networks with real-time rendering. Oil and gas engineering firms in Texas and Louisiana deploy these platforms to compress front-end engineering cycles and eliminate field rework. Demand concentrates where EPA Risk Management Program mandates enforce digital process safety documentation.
- BIM Tools:Building information modeling platforms bind architectural, structural, and MEP systems into unified digital representations. German chemical conglomerates and automotive OEMs modernizing brownfield sites prioritize BIM-enabled digital twins for lifecycle carbon budget validation under EU Green Deal benchmarks.
- CAD Software:Drafting and documentation systems remain foundational for 2D schematic generation and regulatory submission packages.
- Simulation Software:Physics-based process modeling validates thermal, fluid, and stress performance before construction permits issue.
Today's leader: 3D Modeling. Tomorrow's challenger: BIM Tools.
Deployment:
Cost tier differentiation separates perpetual-license on-premises installations from consumption-aligned SaaS contracts with burst capacity provisions.
- Cloud-Based:Remote collaboration platforms enable real-time multi-contractor coordination across distributed engineering teams. Owner-operators in the Middle East and Southeast Asia negotiate seat-based contracts with elastic scaling for peak project phases, though contractual liability exposure slows adoption for proprietary process designs.
- On-Premises:Local infrastructure retains dominance where data sovereignty overrides accessibility. US defense and French classified energy projects mandate air-gapped installations, fragmenting vendor R&D across architectures.
- Hybrid:Split deployments keep sensitive design data on-premises while leveraging cloud rendering and collaboration for non-critical workflows.
- Desktop:Single-workstation licenses persist among small engineering consultancies with intermittent project volumes.
Cloud-Based platforms are climbing the fastest as subscription pricing displaces perpetual licenses. On-Premises retains defensive moats in regulated sectors.
End User:
Application-specific requirements drive feature prioritization, with engineering firms demanding clash detection and construction companies prioritizing 4D sequencing.
- Engineering Firms:EPC contractors and specialty designers require ISO 15926-compliant data exchange for international energy project qualification. Mid-sized German and South Korean firms adopt AI-assisted piping optimization to compete for lump-sum contracts previously reserved for larger competitors.
- Construction Companies:Field execution teams leverage 4D simulation and virtual commissioning to compress handover timelines and reduce rework costs.
- Manufacturing Plants:Owner-operators bind design data to procurement and maintenance workflows, opening recurring revenue streams beyond initial licenses.
- Architects:Spatial design professionals integrate plant layouts with facility aesthetics and occupant flow requirements.
Engineering Firms command the deepest engagement. Manufacturing Plants represent the stickiest long-term accounts through maintenance integration.
Integration Level:
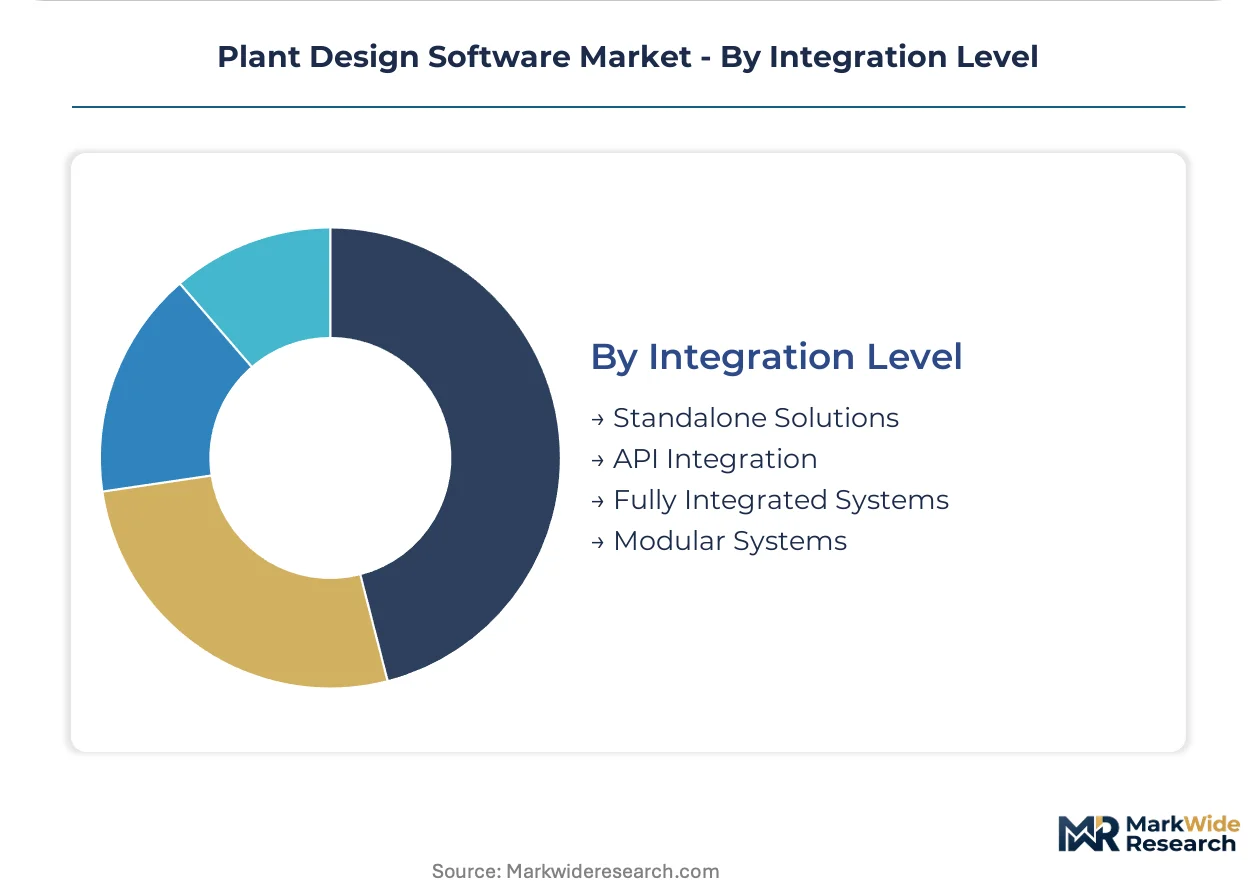
Margin pools concentrate in fully integrated systems that bridge design, procurement, and asset maintenance, though modular architectures win among staged-capability buyers.
- Fully Integrated Systems:End-to-end platforms connect spatial design to vendor catalogs, electronic procurement, and computerized maintenance management. These systems capture premium pricing by collapsing the traditional design-procurement handoff delay.
- Modular Systems:Staged-capability architectures allow mid-sized engineering firms to invest incrementally. India's PLI scheme for specialty chemicals creates first-mover advantage for vendors offering expandable plant design systems to greenfield capacity buildouts.
- API Integration:Middleware connectivity bridges legacy 1990s-era CAD databases with modern platforms for brownfield modernization projects.
- Standalone Solutions:Point applications serve discrete functions without external data exchange requirements.
Fully Integrated Systems dominate margin capture. Modular Systems are gaining share fastest among capital-constrained mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millimeter-grade coordinate precision and clash-detection algorithm expertise concentrates in Germany, the United States, and Japan, anchoring regional demand clusters for plant design software deployment.
Germany
Chemical conglomerates and automotive OEMs drive brownfield modernization with digital twin-enabled systems. The EU Green Deal's industrial emissions benchmarks force facility operators to validate plant layouts against lifecycle carbon budgets before construction permits issue. Engineering teams in Ludwigshafen and Wolfsburg deploy intelligent 3D modeling platforms to compress project timelines.
United States
Oil and gas engineering firms in Texas and Louisiana accelerate adoption of cloud-native platforms for multi-contractor coordination. EPA Risk Management Program enforcement mandates searchable, version-controlled hazard analysis records linked to spatial equipment coordinates. Petrochemical operators prioritize platforms with built-in audit trails to avoid consent decree exposure.
China
State-owned energy enterprises and specialty chemical producers expand greenfield capacity under dual carbon goals. National emissions intensity targets compel facility designers to embed carbon tracking into conceptual phase databases. Engineering procurement officers in Shanghai and Ningbo negotiate seat-based SaaS contracts with elastic scaling provisions.
India
Mid-sized engineering firms compete for lump-sum EPC contracts using modular, staged-capability plant design systems. The PLI scheme for specialty chemicals creates first-mover advantage for vendors serving greenfield capacity buildouts. Project clusters in Gujarat and Maharashtra modernize process layouts with API-integrated middleware bridging legacy CAD databases.
Japan
Heavy fabrication contractors and precision equipment manufacturers demand ISO 15926-compliant data exchange for international energy project qualification. METI industrial digitization programs elevate software fidelity standards for domestic facility designers. Engineering teams in Osaka and Nagoya adopt AI-assisted piping route optimization to auto-generate clash-free layouts.
Plant Design Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as perpetual-license vendors face pressure from SaaS-native entrants. The vendor base splits between established platforms with deep legacy feature sets and newer architectures optimized for remote collaboration. Three archetypes dominate: integrated suite providers binding design to procurement workflows, modular specialists serving staged-capability buyers, and cloud-native challengers capturing subscription revenue. Incumbents defend position through strategic partnerships with industrial automation vendors, while SaaS competitors pursue geographic expansion into underpenetrated engineering procurement markets.
Within the integrated suite tier, Bentley Systems, AVEVA Group, and Hexagon PPM occupy positions representing distinct specialization vectors. Bentley Systems anchors digital twin workflows for water and energy infrastructure clients through its OpenPlant portfolio. AVEVA Group exemplifies deep specialization in cloud-native engineering data management for hydrocarbon processing. Hexagon PPM represents heavy fabrication segment dominance with interoperable CAD and asset information platforms sustaining multi-contractor project execution.
| Leading Market Players |
|---|
| Bentley Systems |
| AVEVA Group |
| Hexagon PPM |
| Autodesk |
| Siemens |
| Dassault Systèmes |
| Intergraph |
| CADWorx |
| Kubotek |
| Others |
Pricing and Supply Chain Analysis
Cloud-native deployment premiums against perpetual-license holdouts create a sharp bifurcation in vendor pricing power, with SaaS architectures commanding recurring revenue multiples while on-premises installations defend margin through data sovereignty premiums in US defense and French classified energy projects.
Pricing Analysis
Bundled subscription tiers displace unbundled perpetual licenses as owner-operators in the Middle East and Southeast Asia negotiate seat-based SaaS contracts with burst capacity for peak project phases. Price differentiation rests on integration depth—fully integrated systems capturing premium pricing by collapsing design-procurement handoffs, while modular systems compete on staged-capability investment thresholds. Pricing pressure stems from mid-sized engineering firms in India and South Korea demanding consumption-aligned cost structures. Construction companies show highest price sensitivity; owner-operators binding design to maintenance workflows demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with German engineering talent clusters, where millimeter-grade coordinate precision and clash-detection algorithm expertise concentrates in Ludwigshafen and Wolfsburg. Software development draws from Germany, the United States, and Japan for core platform engineering; India and South Korea feed implementation and customization layers. Raw material dependencies include cloud infrastructure from hyperscalers, specialized GPU hardware for real-time rendering, and legacy CAD database middleware for brownfield integration. Tariff exposure runs through semiconductor components in AI-assisted piping optimization modules. Distribution runs through direct enterprise sales with certified implementation partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
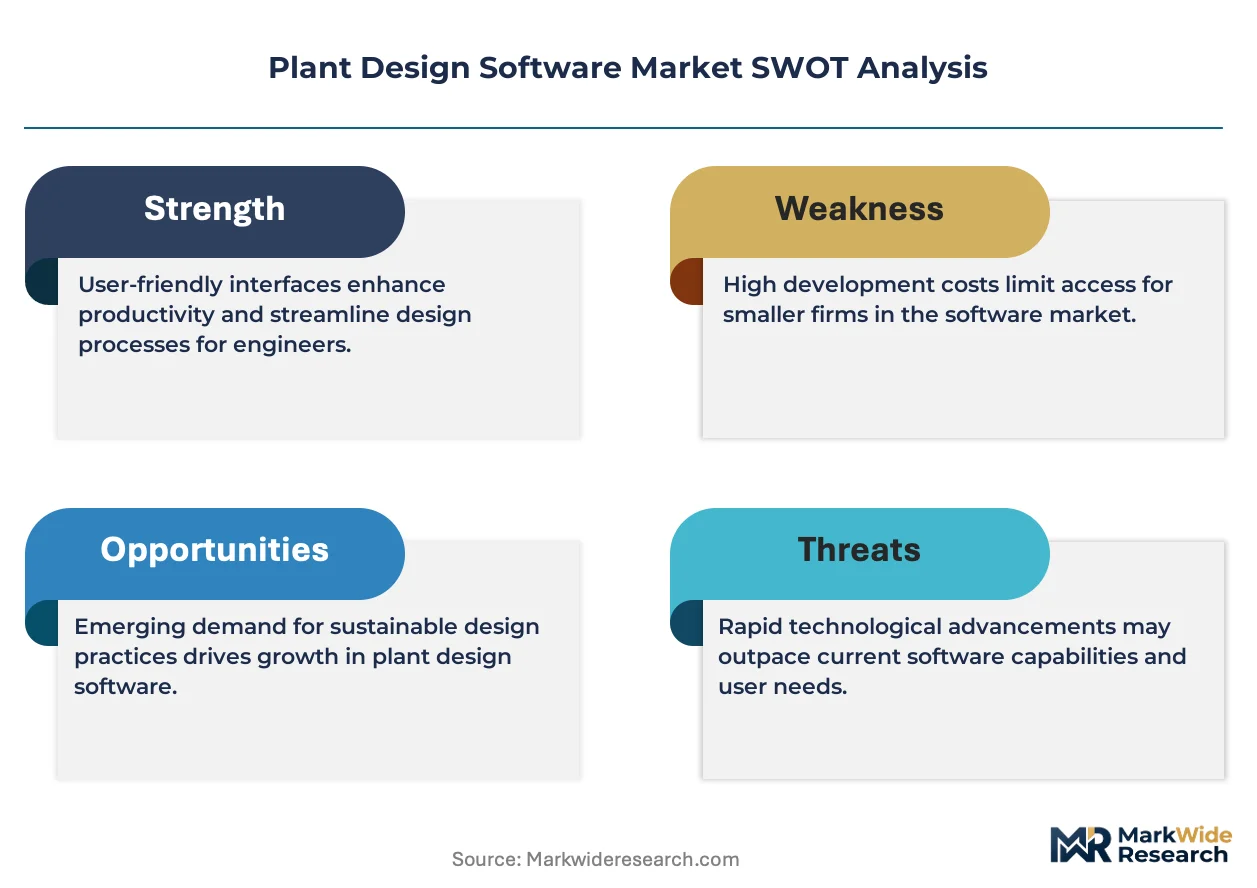
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and the Netherlands exceed India's PLI scheme subsidy offsets, creating margin capture opportunities for vendors with modular architectures.
For Market Incumbents: Acquire AI-assisted piping optimization specialists to neutralize SaaS-native challengers compressing front-end design cycles. Defend position by deepening backward integration into cloud rendering infrastructure, reducing hyperscaler dependency. Prioritize certification investment for ISO 15926 data exchange standards to disqualify non-compliant vendors from international energy contracts. For New Entrants and Emerging Players: Regional system integrators in India's Gujarat and Maharashtra clusters offer the fastest channel to lump-sum EPC contract access. White-space targets include mid-sized engineering firms seeking staged-capability plant design systems for greenfield specialty chemicals capacity. Underpenetrated segments span cloud-native platforms for US petrochemical operators facing EPA Risk Management Program digitization mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where SaaS-native architectures threaten legacy perpetual-license vendors with stranded R&D in on-premises infrastructure. Long-term viability favors platforms binding design data to procurement and maintenance workflows, capturing recurring revenue beyond initial licenses. Acquisition target archetype: modular specialists with API integration capabilities for brownfield modernization. Signal to watch: EPA enforcement intensity accelerating software replacement cycles in Texas and Louisiana.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables real-time multi-contractor coordination for distributed engineering teams in Middle East projects. |
| Digital Twin Integration | Binds spatial design to lifecycle carbon budget validation for EU Green Deal compliance in German chemical facilities. |
| AI-Assisted Piping Optimization | Auto-generates clash-free layouts using reinforcement learning for South Korean mid-sized EPC competitors. |
| API Middleware Development | Bridges 1990s-era CAD databases with modern platforms for European brownfield modernization contracts. |
| Subscription Pricing Transition | Aligns vendor revenue to annual recurring metrics with customer success functions for Southeast Asian buyers. |
Research Methodology
Direct dialogue with plant engineering directors, EPC procurement officers, software integration specialists, and regulatory compliance leads anchored qualitative findings, cross-referenced against secondary sources including EPA enforcement databases, ECHA REACH substance tracking filings, ISO standards documentation, and customs trade data for engineering software imports. Bottom-up and top-down triangulation validated market sizing across deployment architectures.
Bottom-up segment-level modeling across deployment mode, integration depth, end-user vertical, and regional adoption pattern informed value projections across the analysis window. Top-down macro validation incorporated capital expenditure patterns from oil and gas engineering firms and chemical conglomerates. CAGRs derived from slope analysis of technology substitution curves and regulatory compliance-driven replacement cycles, with cloud adoption elasticity and brownfield integration complexity as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement intensity, EU Green Deal benchmark revisions, and hyperscaler pricing for cloud infrastructure. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Sales Enablement Platform Market
Software & Services
Machine Translation Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Product Analytics Software Market
Software & Services
Sales Dialer Software Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Global Directory Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
India Software Services Export Market
Software & Services
Dental Practice Management Software Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Global Data Quality Software Market