
 Europe Edge Analytics Market | 2026-2036
Europe Edge Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Edge Analytics Market Insights
Channel partnerships between industrial automation distributors and cloud providers is tilting toward embedded analytics bundles. Microsoft leverages its Azure IoT Edge stack to anchor factory-floor deployments across German automotive suppliers. Dell Technologies sustains hardware dominance through ruggedized edge servers purpose-built for European industrial environments. Cisco Systems competes on networking-integrated analytics, controlling the data pipeline from sensor to inference engine.
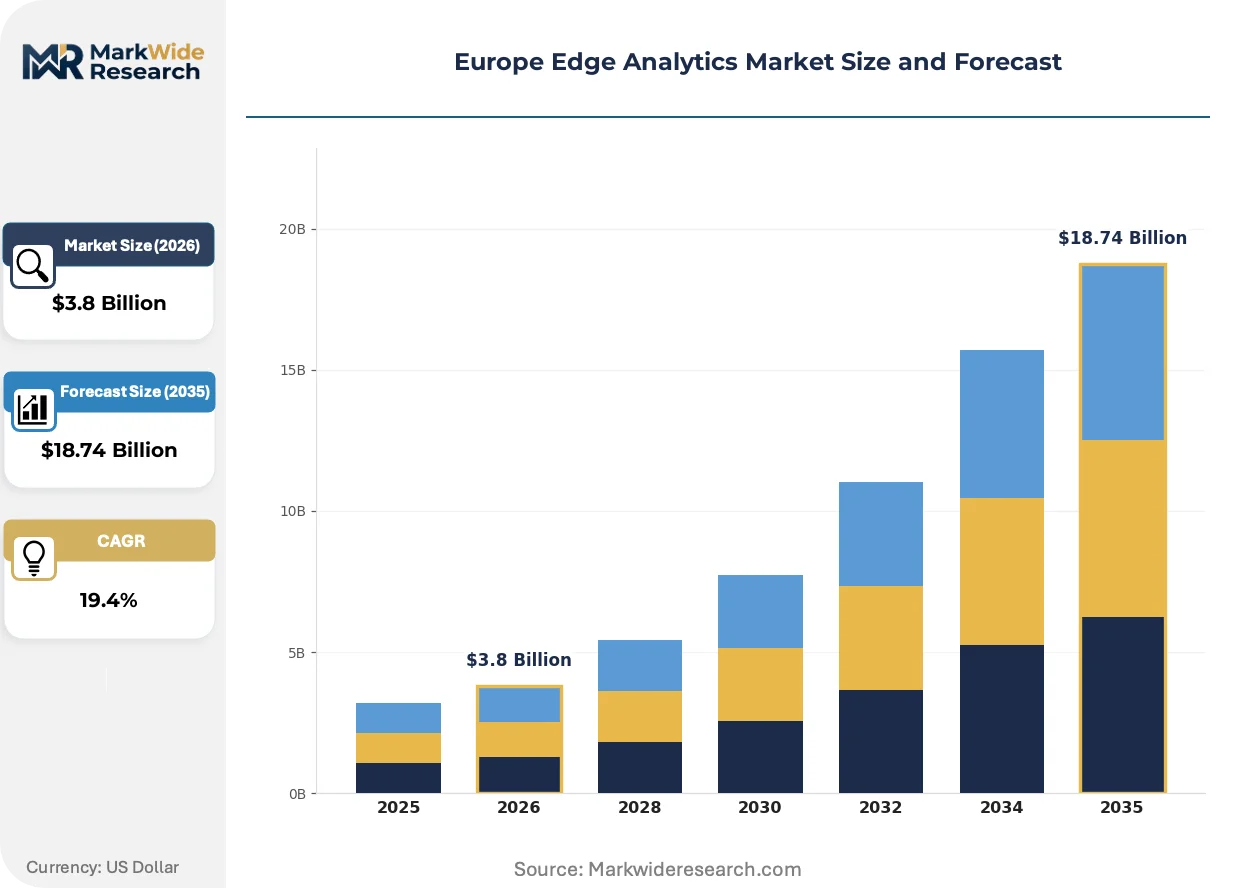
Europe Edge Analytics encompasses real-time data processing, pattern recognition, and automated inference executed on distributed compute nodes physically proximate to data sources, typically operating with sub-50 millisecond latency thresholds and local storage buffers to ensure continuity during network interruptions. The technology serves industrial and commercial users by enabling immediate operational decisions without cloud round-trip delays. Software solutions lead revenue contribution as enterprises prioritize analytics engines over commodity hardware, while IoT technology segments expand fastest as sensor proliferation outpaces standalone AI deployments. Manufacturing end users concentrate margin pools around predictive maintenance and quality assurance use cases.
The EU AI Act, GDPR, and CE marking frameworks collectively shape product development roadmaps, requiring algorithmic transparency and data minimization in edge deployments while mandating safety certifications for hardware sold across member states. EMA guidelines for pharmaceutical manufacturing and the EU Green Deal's energy efficiency mandates further steer adoption toward regulated, low-power edge systems. Stakeholders must weigh compliance investment against latency advantages as regulatory fragmentation between member states intensifies procurement complexity.
Market Dynamics
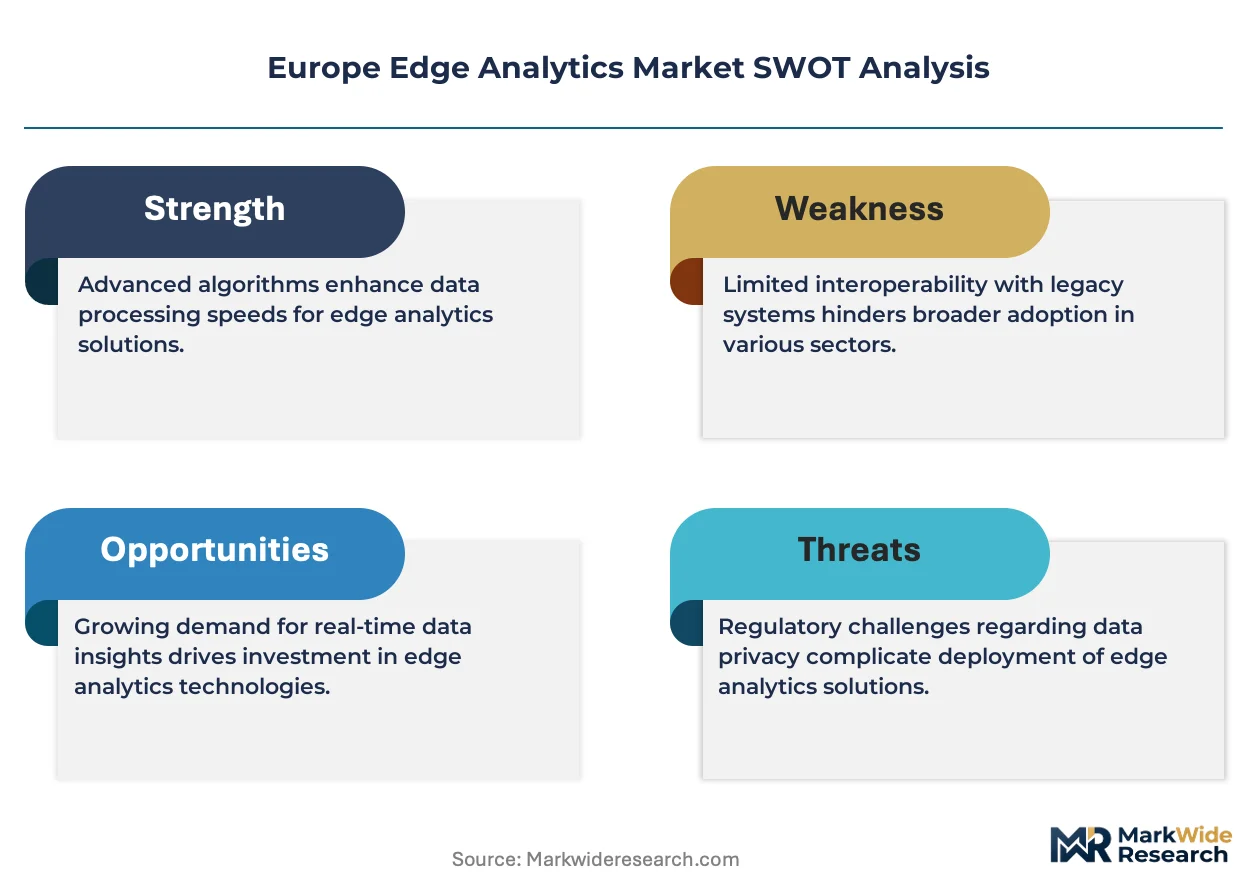
The EU AI Act is forcing algorithmic transparency mandates onto edge deployments, compelling vendors to rearchitect inference engines for auditability while manufacturers absorb compliance costs into procurement budgets.
Growth Catalysts
- Industrial IoT sensor proliferation:Manufacturing floors in Germany's automotive corridors are embedding vibration and thermal sensors at machine level, generating demand for localized pattern recognition without cloud latency.
- EU Green Deal energy mandates:Industrial facilities face binding efficiency targets that edge analytics addresses through real-time power consumption optimization and predictive load balancing.
- CE marking harmonization:Unified hardware certification across member states reduces vendor requalification burdens, accelerating cross-border deployment of ruggedized edge servers.
Market Restraints
- Specialized silicon supply concentration:Advanced inference accelerators depend on fabrication capacity concentrated in East Asian foundries, exposing European integrators to allocation volatility and extended lead times.
- GDPR data minimization friction:The regulation's strict purpose limitation clauses complicate training data retention at the edge, forcing costly on-device anonymization pipelines.
- Legacy brownfield integration:Decades-old SCADA protocols in French and Italian industrial plants resist seamless API connectivity, requiring expensive protocol gateway layers.
Strategic Opportunities
- Spain's underpenetrated industrial base:Automotive component suppliers near Barcelona and Valencia lag German peers in predictive maintenance adoption, creating whitespace for first-mover analytics vendors.
- Pharmaceutical cold chain monitoring:EMA guidelines for temperature-sensitive biologics distribution mandate continuous environmental tracking, opening demand for validated edge nodes in logistics networks.
- 5G private network convergence:Integration of ultra-reliable low-latency radio with edge compute enables new quality assurance use cases in precision manufacturing that standalone Wi-Fi cannot support.
Industry Challenges
- Embedded systems talent scarcity:The intersection of hardware engineering, machine learning optimization, and industrial protocol expertise remains shallow across European labor markets, inflating project timelines.
- Multi-jurisdiction compliance stacking:Vendors must simultaneously satisfy GDPR, EU AI Act risk classifications, and national cyber certification schemes, fragmenting product roadmaps.
- Inference model drift management:Continuous accuracy degradation in deployed edge models demands retraining infrastructure that many industrial buyers lack operational maturity to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Edge Analytics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Platform Deployment: On-Premises, Cloud, Hybrid, Managed End User: Retail, Manufacturing, Healthcare, Transportation Technology: Machine Learning, IoT, Artificial Intelligence, Data Processing |
| Companies Covered | Microsoft, Amazon Web Services, Dell Technologies, IBM, Cisco Systems, Intel Corporation, NVIDIA Corporation, Qualcomm Technologies, ADLINK Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Edge Analytics Market Trends and Innovations
Software-defined architectures are displacing fixed-function hardware across European industrial sites, compressing deployment cycles and enabling remote reconfiguration of analytics pipelines without physical intervention.
Containerized inference runtimes are virtualizing model execution environments across heterogeneous edge hardware, from ARM-based industrial gateways to x86 rack servers. German automotive suppliers adopt these abstraction layers fastest, consolidating multiple quality inspection workloads onto shared compute pools. This virtualization is compressing vendor lock-in and accelerating workload migration between hardware generations.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk automated decision systems, including certain predictive maintenance and quality control deployments. Industrial software vendors must now embed logging and explainability modules into edge analytics stacks. German and French manufacturing corridors are experiencing the steepest compliance investment curves as they host the densest concentrations of affected use cases.
Buyer organizations are consolidating vendor relationships around integrated platform providers rather than assembling point solutions. Industrial automation distributors in the Lyon-Grenoble corridor now bundle edge hardware, analytics software, and managed connectivity into single procurement contracts. This consolidation is most pronounced among mid-cap French manufacturers lacking internal integration capabilities.
Europe Edge Analytics Market Segmentation
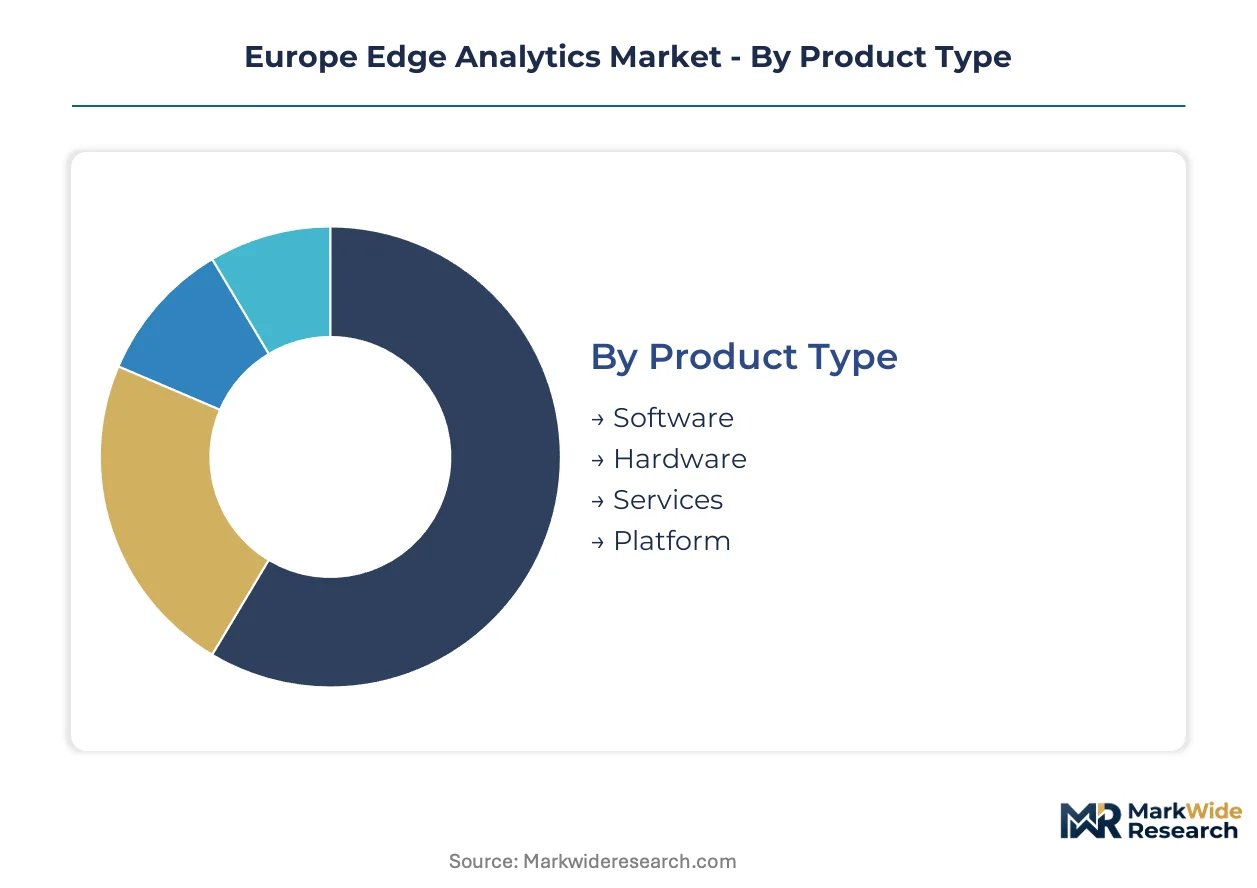
Edge analytics segmentation reveals distinct procurement patterns across European industrial buyers. Software and platform investments dominate capital allocation as enterprises prioritize inference capabilities over commodity infrastructure. Technology choices increasingly hinge on regulatory compliance requirements under the EU AI Act and GDPR frameworks.
Product Type:
Mature hardware categories coexist with rapidly evolving software stacks as buyers rebalance spending toward analytics engines.
- Software:Analytics engines and inference runtimes process sensor streams locally without cloud round-trip delays. German automotive suppliers in Stuttgart and Munich corridors prioritize these solutions for sub-50 millisecond quality inspection loops. The EU AI Act's algorithmic transparency mandates are forcing explainability modules into every deployment.
- Platform:Integrated stacks combining runtime environments, model management, and device orchestration compress procurement complexity for mid-cap manufacturers. French smart factory clusters near Lyon favor bundled platforms over point solutions to compensate for shallow internal integration capabilities.
- Hardware:Ruggedized edge servers and industrial gateways provide physical compute infrastructure for factory-floor deployments.
- Services:Implementation, training, and managed support offerings address talent scarcity in embedded systems engineering across European labor markets.
Software handles the majority of throughput; Platform is expanding most quickly as vendor consolidation accelerates.
Deployment:
Cost tier differentiation separates enterprise buyers with capital reserves from mid-market adopters seeking operational expenditure flexibility.
- On-Premises:Dedicated infrastructure within facility boundaries satisfies GDPR data residency requirements and eliminates network dependency for critical control loops. German pharmaceutical manufacturers deploying EMA-compliant cold chain monitoring insist on fully captive edge nodes.
- Hybrid:Split architectures process latency-sensitive inference locally while aggregating training data and model updates through cloud pipelines. French automotive component suppliers near Grenoble adopt this pattern to balance real-time quality control with centralized model refinement.
- Cloud:Fully managed edge runtimes hosted by hyperscale providers reduce capital barriers for smaller industrial buyers.
- Managed:Outsourced operations and maintenance contracts address skill gaps in model drift management and firmware updates.
On-Premises retains the largest installed base; Hybrid is gaining share fastest as manufacturers seek regulatory shelter without sacrificing cloud agility.
End User:
Application intensity varies dramatically across verticals, with predictive maintenance and quality assurance concentrating margin pools in discrete manufacturing.
- Manufacturing:Predictive maintenance of industrial equipment and real-time quality inspection drive the deepest edge analytics penetration. German automotive corridors embed vibration and thermal sensors at machine level, generating localized pattern recognition demand that resists cloud latency.
- Healthcare:Continuous patient monitoring and medical device inference require validated edge nodes with FDA-equivalent certification pathways. EMA guidelines for pharmaceutical manufacturing steer adoption toward regulated, low-power systems in logistics networks handling temperature-sensitive biologics.
- Retail:Inventory tracking and customer behavior analytics at store level generate demand for compact, fanless edge gateways.
- Transportation:Fleet telematics and autonomous vehicle perception processing push compute to roadside infrastructure and vehicle-embedded systems.
Manufacturing commands the dominant revenue position; Healthcare is climbing the fastest as regulatory validation frameworks mature.
Technology:
Supply concentration in advanced silicon shapes competitive dynamics as inference accelerators face allocation volatility from East Asian foundries.
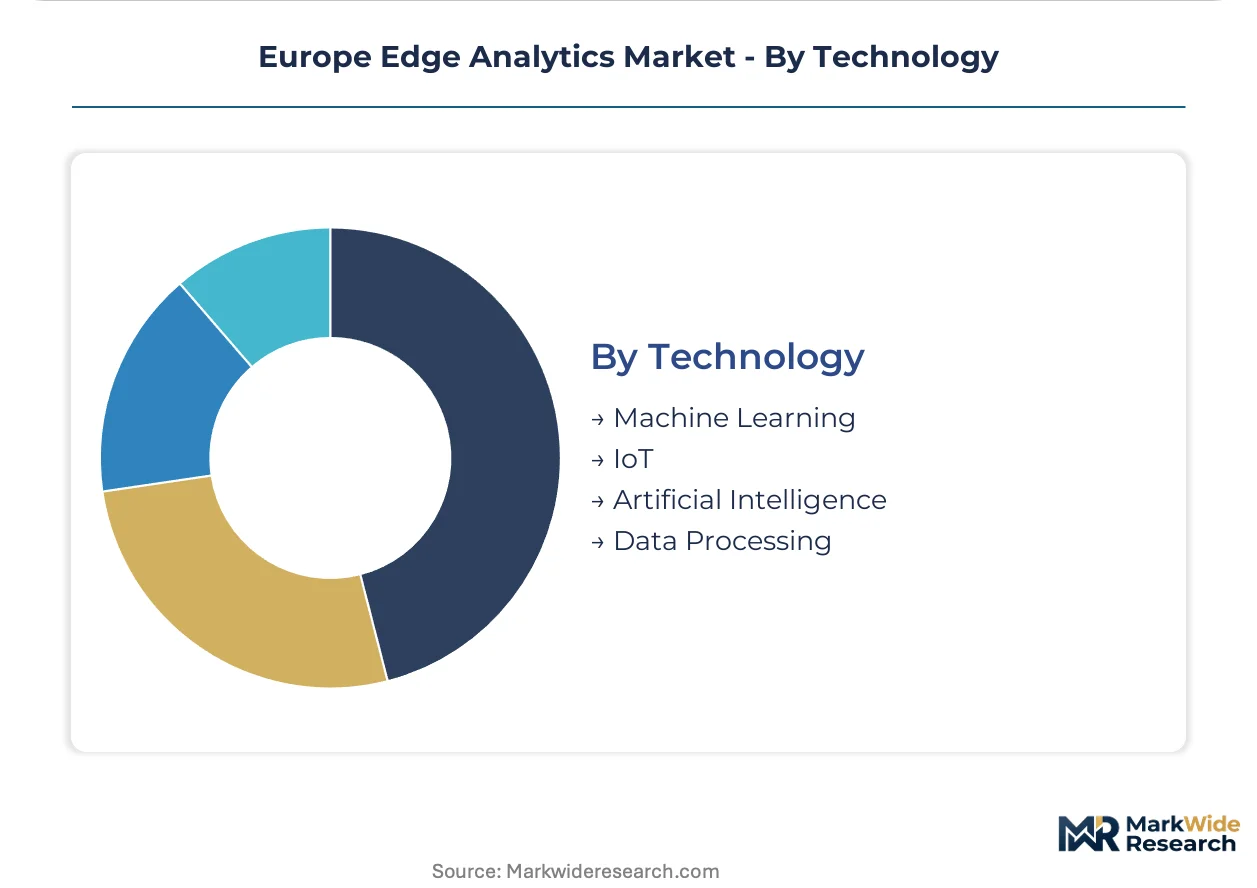
- Machine Learning:Supervised and unsupervised models deployed at the edge enable anomaly detection and classification without continuous cloud connectivity. Containerized inference runtimes virtualize execution across heterogeneous hardware from ARM-based gateways to x86 rack servers.
- IoT:Sensor proliferation outpaces standalone AI deployments as vibration, thermal, and acoustic monitoring endpoints multiply across factory floors. The EU Green Deal's energy efficiency mandates accelerate real-time power consumption optimization through distributed sensor networks.
- Artificial Intelligence:Deep learning inference and neural network execution at the edge demands specialized accelerators with stringent thermal and power constraints.
- Data Processing:Stream processing and event correlation engines filter noise and aggregate signals before actionable alerts trigger operational responses.
Machine Learning anchors current deployments; IoT is the fastest mover on share as sensor density compounds data generation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor and its digital twin infrastructure anchor Europe's edge analytics deployment density, connecting industrial clusters from Rotterdam through the Ruhr Valley to Milan with low-latency fiber and 5G private networks that enable real-time inference at manufacturing nodes.
Germany
Automotive suppliers in Stuttgart and Munich corridors embed vibration and thermal sensors at machine level, generating localized pattern recognition demand. The EU AI Act's risk-based classification system imposes documentation requirements on predictive maintenance deployments. The Ruhr Valley's steel and chemicals complexes are retrofitting brownfield SCADA systems with edge gateways for emissions monitoring under EU Green Deal mandates.
France
Smart factory clusters near Lyon and Grenoble concentrate demand for bundled analytics platforms that compensate for shallow internal integration capabilities. ANSM guidelines for pharmaceutical manufacturing steer adoption toward validated edge nodes in temperature-sensitive biologics distribution. The Île-de-France region hosts hyperscale cloud regions that anchor hybrid deployment architectures for latency-sensitive inference.
United Kingdom
Financial services firms in London deploy edge analytics for real-time fraud detection at payment terminals, satisfying FCA operational resilience requirements. The Midlands manufacturing belt is adopting containerized inference runtimes across automotive component plants. Cambridge's technology cluster is spawning specialized vendors in low-power edge AI for industrial IoT applications.
Italy
Luxury goods manufacturers in Milan and Florence utilize edge analytics for quality inspection of leather and textile finishes, preserving artisanal production methods while automating defect detection. CE marking harmonization reduces vendor requalification burdens for ruggedized servers deployed across Emilia-Romagna's packaging machinery sector. The Port of Trieste's digital infrastructure supports cold chain monitoring for pharmaceutical exports to Central Europe.
Netherlands
Rotterdam's port complex anchors Europe's densest deployment of edge nodes for container logistics and predictive maintenance of cargo handling equipment. The country's national cyber certification scheme intersects with GDPR data minimization requirements, complicating training data retention for computer vision models. Eindhoven's high-tech systems cluster supplies specialized silicon for inference accelerators deployed across German automotive plants.
Europe Edge Analytics Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers that bundle hardware, software, and managed connectivity into single procurement contracts. Three strategic archetypes dominate: hyperscale cloud providers extending infrastructure to the edge, industrial automation distributors embedding analytics into existing relationships, and specialized hardware vendors supplying ruggedized compute for factory-floor environments. Competitive moves center on strategic partnerships between cloud stacks and industrial distributors, plus portfolio diversification into regulated verticals requiring certified edge systems.
Within the hyperscale tier, Microsoft and Amazon Web Services anchor cloud-to-edge continuum strategies, exemplifying the platform archetype that French mid-cap manufacturers increasingly favor for bundled procurement. Dell Technologies and Cisco Systems occupy positions in the infrastructure tier, with Dell representing hardware-centric ruggedization for industrial environments and Cisco exemplifying networking-integrated analytics that controls data pipelines from sensor to inference engine. These three companies collectively illustrate the vendor consolidation pattern accelerating across European manufacturing corridors.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| Dell Technologies |
| IBM |
| Cisco Systems |
| Intel Corporation |
| NVIDIA Corporation |
| Qualcomm Technologies |
| ADLINK Technology |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Taiwanese foundry capacity for advanced inference accelerators compresses margin structures across hardware tiers while amplifying procurement lead-time spreads between volume buyers and mid-cap integrators. This concentration dynamic forces European vendors to absorb allocation volatility into pricing tiers or sacrifice market position.
Pricing Analysis
Volume-discount tiering structures separate enterprise-scale automotive suppliers in Stuttgart from mid-cap French manufacturers near Lyon, with the former extracting 40-60% unit economics advantages through multi-year platform commitments. Certification grade under EU AI Act risk classifications and after-sales service bundling constitute the primary differentiation levers. Cost compression in standard-tier hardware is intensifying because East Asian foundry allocation constraints force European integrators to premium-price guaranteed delivery slots. Mid-cap manufacturers lacking internal integration capabilities exhibit highest price sensitivity, while German automotive OEMs prioritize latency guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Jabil, and Flex holding dominant capacity for ruggedized edge server assembly, with backend testing and firmware loading distributed across Czech Republic and Poland facilities. Advanced silicon draws from Taiwan and South Korea foundries, while passive components and industrial-grade storage modules source from China and Japan. Single-source vulnerability in 7nm and below inference accelerators exposes European vendors to allocation rationing during capacity crunches. Distribution runs through industrial automation distributors in the Lyon-Grenoble corridor and German automotive supply integrators, with direct OEM relationships gaining share among large-scale deployers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance fragmentation creates vendor consolidation opportunities as mid-cap manufacturers abandon point-solution assembly in favor of bundled platform procurement.
For Market Incumbents: Entrench platform dominance by embedding explainability modules and audit logging into base-tier offerings before regulatory deadlines harden procurement criteria. Acquire specialized compliance engineering teams in France and Germany to capture ANSM and KBA certification pathways. Channel control through exclusive distributor relationships in underpenetrated Spanish corridors represents the critical defensive lever against hyperscale cloud encroachment. For New Entrants and Emerging Players: Spain's automotive component belt near Barcelona offers whitespace entry points where predictive maintenance penetration lags German benchmarks by 3-5 years. Target pharmaceutical cold chain monitoring as the fastest-closing vertical, where EMA guidelines mandate validated edge nodes but incumbent platform vendors lack temperature-specific sensor integration depth. Pursue managed service wraparound as the primary go-to-market angle, compensating for shallow buyer technical capabilities. For Investors and Strategic Acquirers: Industrial IoT gateway specialists with captive pharmaceutical validation capabilities represent the optimal acquisition archetype, combining regulatory moats with sensor fusion expertise. Long-term viability hinges on EU Green Deal energy efficiency mandate acceleration and 5G private network deployment curves. Monitor CE marking harmonization implementation delays as the critical inflection signal—regulatory fragmentation extension would compress mid-tier vendor margins and trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Integration | EU AI Act explainability modules embedded in base platforms capture mid-cap manufacturers before procurement deadlines. |
| Geographic Manufacturing Footprint | Czech Republic and Poland assembly facilities reduce lead times for German automotive corridor deployments. |
| Strategic Partnership | Industrial automation distributors in Lyon-Grenoble bundle hardware, software, and connectivity into single contracts. |
| Acquisition of Specialist Firm | Pharmaceutical validation engineering teams capture EMA-compliant cold chain monitoring demand in logistics networks. |
| Platform Integration | Containerized inference runtimes virtualize across heterogeneous hardware from ARM gateways to x86 rack servers. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, industrial automation procurement leads, and OEM platform integration specialists anchored the qualitative base. Primary interviews combined with secondary validation through SEC filings of listed industrial technology vendors, hyperscaler capex disclosures, EU regulatory filings under AI Act and GDPR frameworks, and customs data on edge hardware imports. Bottom-up deployment sizing across German automotive corridors, French smart factory clusters, and Spanish industrial zones triangulated against top-down market aggregation.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning deployment model, organization size tier, vertical application intensity, and regional regulatory cluster. CAGRs derived from deployment velocity curves weighted by compliance investment cycles and foundry capacity allocation assumptions. Model inputs incorporated sensor density growth rates in manufacturing floors, 5G private network rollout timelines, and EU Green Deal energy mandate enforcement trajectories.
Practitioners should monitor foundry capacity allocation announcements, EU AI Act implementing act publication schedules, and CE marking harmonization enforcement variance for early signals of forecast revision. Assumptions reflect current regulatory trajectories and silicon supply configurations. Quarterly review of inference accelerator lead times, pharmaceutical validation backlog durations, and mid-cap manufacturer platform consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
ASEAN Geospatial Analytics Market
Analytics
Investigative Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Europe Operational Intelligence Market
Analytics
SME Big Data Market
Analytics
Global Marketing Attribution Software Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Business Intelligence (BI) Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Sweden ICT Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Process Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market