
 Asia-Pacific Crowd Analytics Market | 2026-2036
Asia-Pacific Crowd Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Crowd Analytics Market Insights
Subscription-based SaaS licensing is reconfiguring capital requirements for crowd analytics vendors, lowering barriers for mid-tier municipal buyers across Southeast Asia. NEC Corporation leverages its long-standing government relationships to dominate large-scale public safety deployments. IBM Corporation sustains competitive positioning through hybrid cloud architectures that address data sovereignty constraints. Cisco Systems, Inc. specializes in edge-computing hardware that processes video feeds locally before cloud transmission.
Crowd analytics encompasses software and hardware systems that apply computer vision, sensor fusion, and predictive algorithms to measure pedestrian density, flow patterns, and behavioral anomalies in physical spaces. These systems typically process video streams at 15-30 frames per second through GPU-accelerated edge nodes, generating real-time occupancy counts and dwell-time metrics for operational decision-making. Software solutions currently capture the largest revenue share as municipalities prioritize algorithmic platforms over dedicated sensor hardware. Cloud-based deployment is expanding fastest among retail chains seeking centralized management across multi-site portfolios, though on-premises installations retain strong preference in China's public sector due to cybersecurity protocols.
Japan's METI guides industrial standards for AI-enabled surveillance systems, while China's SAMR enforces algorithmic transparency requirements for public-space analytics vendors. India's TRAI mandates data localization for video analytics processing citizen movement patterns, directly influencing vendor infrastructure placement decisions. Australia's TGA-equivalent privacy frameworks and South Korea's MFDS-aligned biometric regulations add compliance layers for cross-border platform providers. Stakeholders must weigh sovereign data requirements against the cost of fragmented regional infrastructure builds.
Market Dynamics
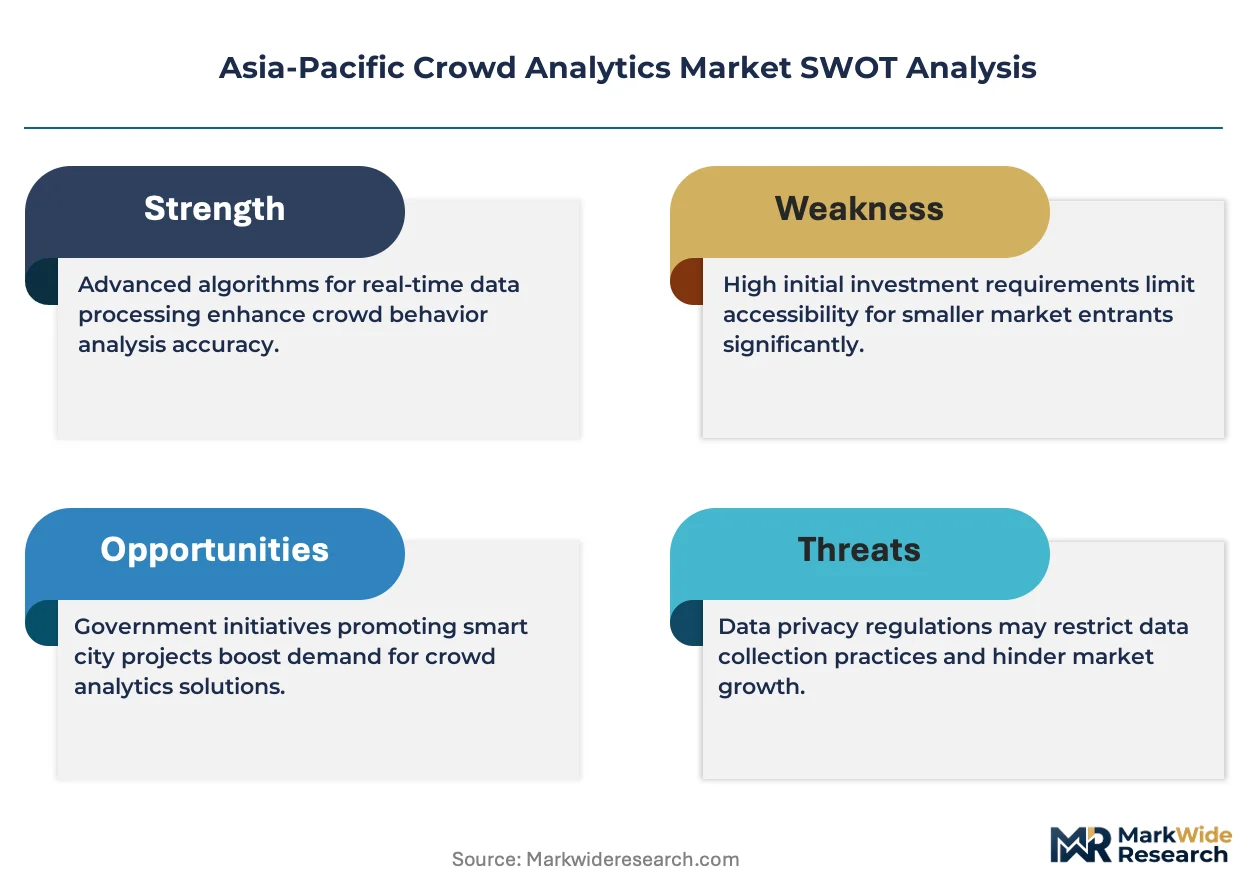
Data-localization mandates across India, China, and Australia are fragmenting vendor infrastructure requirements and reshaping competitive entry costs for crowd analytics platforms.
Growth Catalysts
- Smart city mandates:India's Ministry of Housing and Urban Affairs accelerates pedestrian-flow optimization procurement across 100+ designated urban corridors.
- TRAI localization rules:India's telecom regulator mandates domestic processing of citizen movement data, creating captive demand for local infrastructure deployment.
- Edge AI silicon:GPU-accelerated processing nodes at 15-30 frames per second enable real-time anomaly detection without cloud dependency.
Market Restraints
- GB standards compliance:China's mandatory national standards for public-safety video analytics impose certification timelines exceeding 18 months for foreign vendors.
- Sensor hardware concentration:Specialized thermal and LiDAR sensor supply concentrates among Japanese and South Korean component suppliers.
- Algorithmic transparency requirements:China's SAMR mandates explainable AI documentation for public-space deployment, raising R&D overhead.
Strategic Opportunities
- Vietnam urbanization:Secondary city smart infrastructure programs remain underpenetrated by established analytics vendors.
- SaaS licensing expansion:Subscription models lower capital barriers for mid-tier municipal buyers across Southeast Asian markets.
- 5G-IoT convergence:Ultra-reliable low-latency communication enables sensor fusion between video, WiFi probe, and Bluetooth beacon data streams.
Industry Challenges
- Computer vision talent scarcity:Shortage of GPU kernel optimization specialists delays edge-node deployment timelines.
- Legacy analog integration:Existing CCTV infrastructure in older Japanese railway stations requires costly encoder retrofits for analytics compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Crowd Analytics Market |
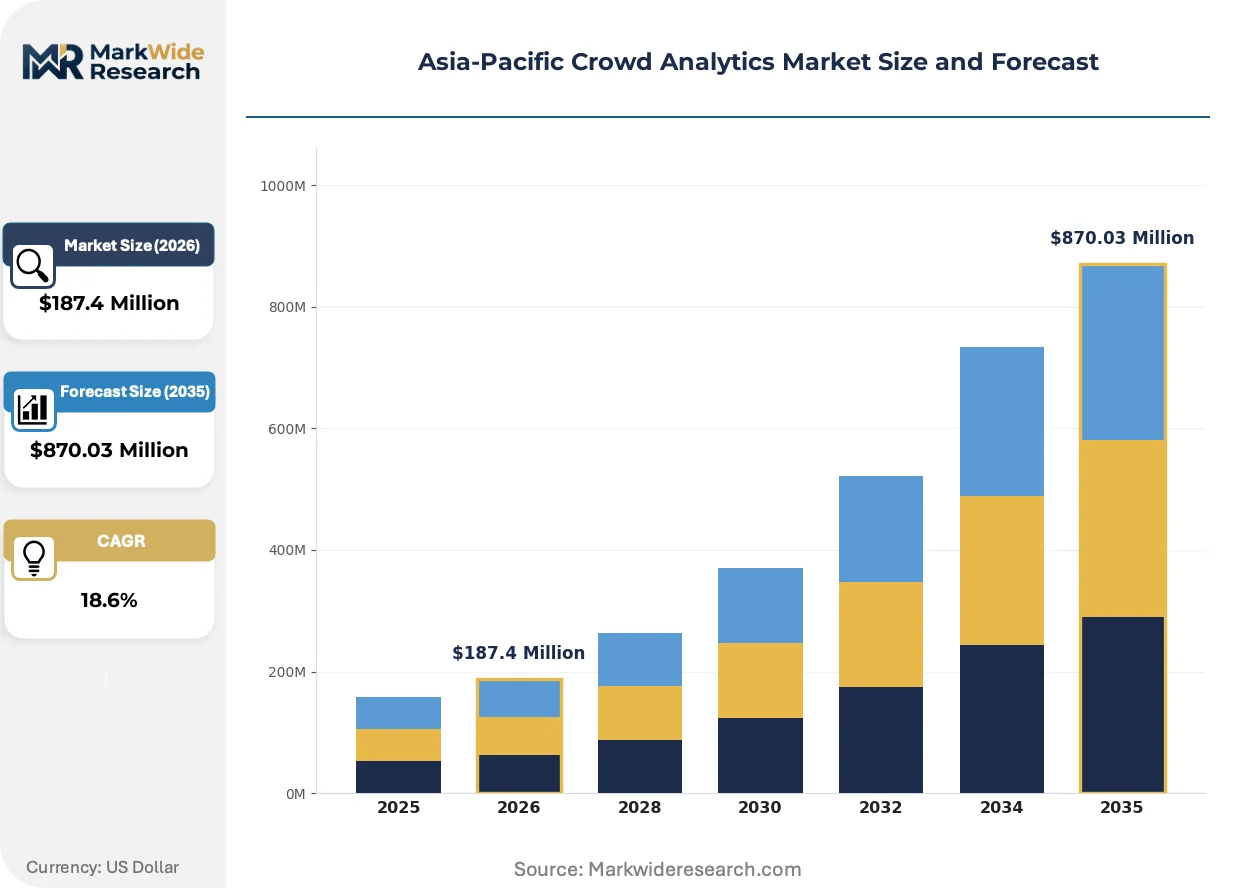
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Integration End User: Retail, Transportation, Sports, Entertainment Deployment: On-Premises, Cloud-Based, Hybrid, Managed Application: Traffic Management, Event Monitoring, Audience Engagement, Operational Efficiency |
| Companies Covered | Savannah Simulations AG, IBM Corporation, Nokia Corporation, Intel Corporation, Hewlett Packard Enterprise Development LP, NEC Corporation, Sightcorp, Cisco Systems, Inc., Amazon Web Services, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Crowd Analytics Market Trends and Innovations
Deployment architectures are bifurcating between sovereign-cloud compliance and edge-native processing, forcing vendors to maintain parallel technology stacks across the region.
Edge computing is hybridizing with centralized analytics platforms. GPU-accelerated nodes process video feeds locally for sub-100-millisecond latency, then transmit aggregated metadata to municipal data centers. Singapore's integrated resort complexes and Japan's railway-operated stations deploy these architectures for real-time occupancy management. This topology is hybridizing vendor business models, compressing pure-cloud revenue streams while expanding hardware-software bundled offerings.
Australia's privacy frameworks aligned with TGA-equivalent biometric regulations now require explicit consent mechanisms for facial recognition in retail analytics. This policy shift fragments software development roadmaps, forcing vendors to maintain separate algorithm versions for markets with divergent consent requirements. Retail chains operating across Australia and Southeast Asia face the steepest compliance multiplication.
Buyer contracting patterns are consolidating around performance-based service level agreements. Municipal procurement offices in India and Singapore now tie vendor payments to accuracy benchmarks for crowd density estimation, displacing traditional per-camera licensing. This reconfiguration concentrates vendor selection among platforms with proven training datasets for Asian demographic and environmental conditions.
Asia-Pacific Crowd Analytics Market Segmentation
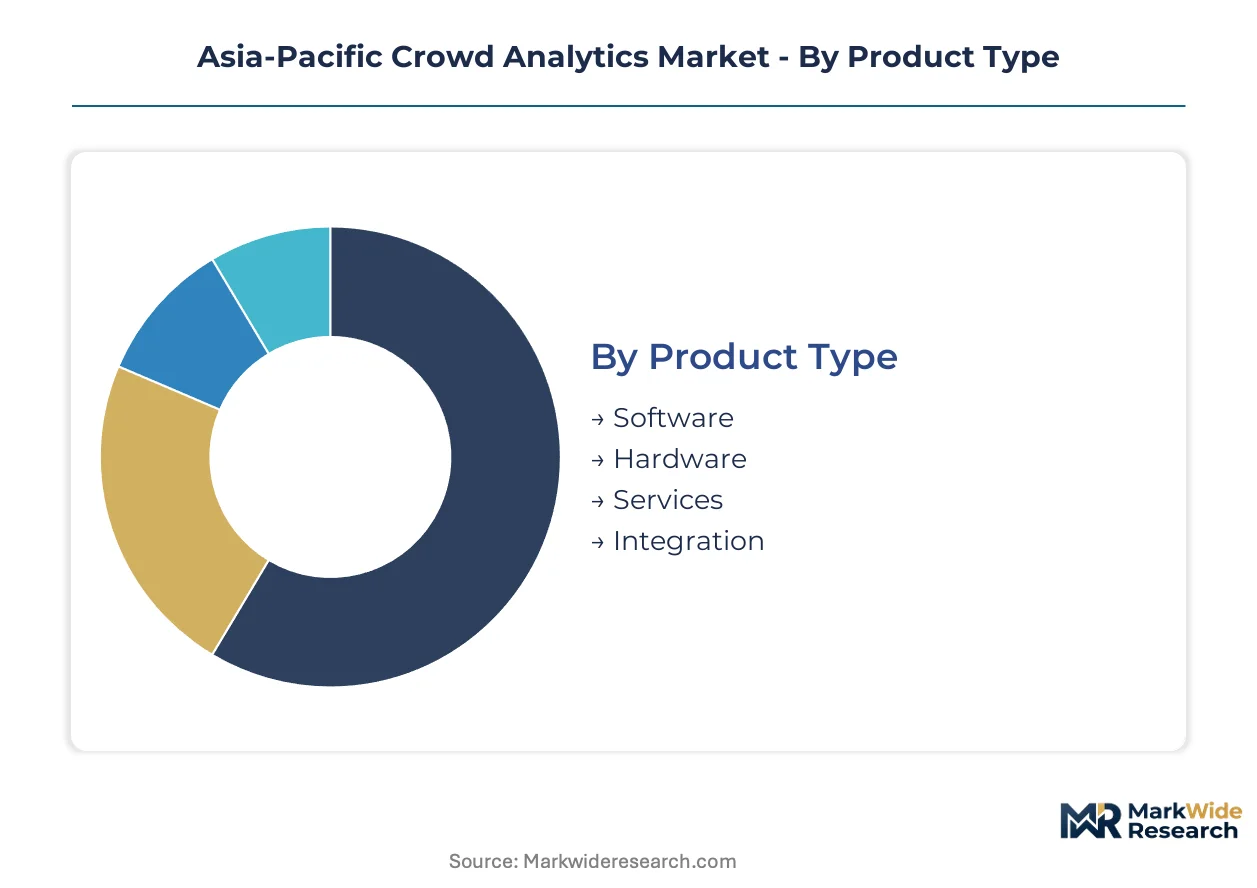
Crowd analytics procurement patterns diverge sharply across product architectures, end-use environments, and deployment topologies. Vendors must align capability roadmaps with the distinct refresh cycles and compliance burdens that characterize each segment category.
Product Type:
Software solutions turn over fastest as algorithmic platforms iterate quarterly, while hardware and integration services lock in for multi-year infrastructure cycles.
- Software:Algorithmic platforms process video streams through GPU-accelerated inference engines, generating real-time occupancy metrics and dwell-time analytics. Singapore's integrated resort complexes and Japan's railway-operated stations prioritize these solutions for pedestrian-flow optimization, driven by municipal procurement offices tying vendor payments to crowd density estimation accuracy benchmarks.
- Hardware:Edge-computing nodes and sensor arrays capture video feeds at 15-30 frames per second for local processing before cloud transmission. Demand concentrates in China's public sector, where GB standards for public-safety video analytics and SAMR algorithmic transparency requirements mandate on-premise infrastructure with documented explainable AI capabilities.
- Services:Consulting and managed analytics support model training, calibration, and compliance documentation for municipal buyers.
- Integration:System integration services retrofit legacy CCTV infrastructure in older Japanese railway stations with encoder upgrades for analytics compatibility.
Software dominates installed base. Hardware is where expansion concentrates.
End User:
Transportation and retail applications operate on compressed deployment timelines, while sports and entertainment venues plan around episodic capital cycles.
- Retail:Cloud-based deployment expands fastest among retail chains seeking centralized management across multi-site portfolios, though Australia's TGA-equivalent privacy frameworks now require explicit consent mechanisms for facial recognition analytics.
- Transportation:Pedestrian-flow optimization systems process commuter density across Japan's railway-operated stations and India's 100+ designated smart city urban corridors, with TRAI data-localization guidelines mandating domestic processing infrastructure.
- Sports:Venue operators deploy crowd analytics for safety perimeter management and concession queue optimization during major events.
- Entertainment:Integrated resort complexes in Singapore combine video analytics with WiFi probe and Bluetooth beacon sensor fusion for guest movement pattern analysis.
Transportation commands the largest procurement volumes. Retail is climbing the fastest.
Deployment:
Cloud-based solutions refresh continuously through SaaS licensing, whereas on-premises installations persist through sovereign data compliance mandates.
- On-Premises:Installations retain strong preference in China's public sector due to cybersecurity protocols and SAMR enforcement of algorithmic transparency documentation for public-space deployment.
- Cloud-Based:Subscription-based SaaS licensing lowers capital barriers for mid-tier municipal buyers across Southeast Asian markets, with centralized management appealing to retail chains operating multi-site portfolios.
- Hybrid:GPU-accelerated nodes process video feeds locally for sub-100-millisecond latency, then transmit aggregated metadata to municipal data centers, compressing pure-cloud revenue streams while expanding hardware-software bundled offerings.
- Managed:Fully outsourced analytics operations appeal to buyers lacking in-house computer vision talent for GPU kernel optimization and edge-node deployment.
On-Premises anchors public sector procurement. Hybrid is gaining share fastest.
Application:
Traffic management and event monitoring deploy on emergency procurement cycles, while audience engagement and operational efficiency follow annual budget rhythms.
- Traffic Management:Real-time pedestrian and vehicle flow optimization across Indian urban corridors and Japanese railway stations, with India's Ministry of Housing and Urban Affairs accelerating procurement through smart city mandates.
- Event Monitoring:Safety anomaly detection for crowd crush prevention and perimeter breach alerts, with Singapore's integrated resort complexes deploying these capabilities for real-time occupancy management.
- Audience Engagement:Dwell-time analytics and demographic profiling for retail and entertainment venues, fragmented by Australia's explicit consent requirements versus Southeast Asian markets.
- Operational Efficiency:Staff allocation optimization and queue management for transportation hubs and large-format retail, tied to performance-based service level agreements.
Traffic Management holds the deepest installed base. Event Monitoring is where vendor competition intensifies most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Housing and Urban Affairs accelerates pedestrian-flow optimization procurement through smart city mandates across 100+ designated urban corridors. TRAI data-localization guidelines mandate domestic processing infrastructure for citizen movement data. Japan's METI guides industrial standards for AI-enabled surveillance systems.
India
Smart city deployments across Mumbai, Delhi-NCR, and Bangalore drive demand for real-time crowd density systems. TRAI mandates data localization for video analytics processing citizen movement patterns, forcing vendors to build domestic cloud infrastructure. The Ministry of Housing and Urban Affairs channels funding toward pedestrian-flow optimization in 100+ designated smart city urban corridors.
China
GB standards for public-safety video analytics impose certification timelines exceeding 18 months for foreign vendors entering the market. SAMR enforces algorithmic transparency requirements and explainable AI documentation for public-space deployment. Beijing and Shanghai anchor procurement for edge-computing nodes that process video feeds locally before limited cloud transmission.
Japan
Railway-operated stations in Tokyo, Osaka, and Nagoya deploy GPU-accelerated processing nodes for commuter density management. METI guides industrial standards for AI-enabled surveillance systems, shaping vendor compliance roadmaps. NEC Corporation leverages long-standing government relationships to dominate large-scale public safety deployments across Kanto and Kansai metropolitan zones.
Singapore
Integrated resort complexes combine video analytics with WiFi probe and Bluetooth beacon sensor fusion for guest movement pattern analysis. The city-state's procurement offices tie vendor payments to accuracy benchmarks for crowd density estimation. Marina Bay and Sentosa clusters concentrate demand for hybrid deployment architectures processing feeds locally at sub-100-millisecond latency.
Australia
TGA-equivalent privacy frameworks require explicit consent mechanisms for facial recognition in retail analytics applications. Sydney and Melbourne retail chains face compliance multiplication when operating across Australian and Southeast Asian markets. Procurement patterns consolidate around performance-based service level agreements displacing traditional per-camera licensing structures.
Asia-Pacific Crowd Analytics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment topology segments. The vendor base organizes around three strategic archetypes: government-contracting incumbents with established compliance relationships, cloud-native platforms addressing data sovereignty constraints, and edge-hardware specialists processing video feeds locally. M&A activity concentrates on acquiring computer vision talent for GPU kernel optimization. Strategic partnerships between municipal systems integrators and algorithmic platform vendors reshape procurement access.
Within the government-contracting tier, NEC Corporation and IBM Corporation exemplify divergent approaches to sovereign-cloud compliance. NEC leverages long-standing relationships with Japanese and Indian public sector buyers, while IBM sustains positioning through hybrid cloud architectures. Cisco Systems, Inc. anchors the edge-hardware specialist archetype, specializing in computing nodes that process video feeds locally. Amazon Web Services, Inc. and Nokia Corporation occupy positions on the cloud-platform vector, with the former addressing retail chain demand for centralized multi-site management and the latter targeting 5G-IoT convergence opportunities. Hewlett Packard Enterprise Development LP and Intel Corporation represent infrastructure-layer suppliers enabling GPU-accelerated inference engines. Savannah Simulations AG and Sightcorp exemplify algorithmic specialists competing on training dataset quality for Asian demographic conditions.
| Leading Market Players |
|---|
| Savannah Simulations AG |
| IBM Corporation |
| Nokia Corporation |
| Intel Corporation |
| Hewlett Packard Enterprise Development LP |
| NEC Corporation |
| Sightcorp |
| Cisco Systems, Inc. |
| Amazon Web Services, Inc. |
| Others |
Pricing and Supply Chain Analysis
Japanese and South Korean component suppliers dominate specialized thermal and LiDAR sensor production, anchoring margin capture upstream while downstream vendors compete on algorithmic differentiation and compliance bundling.
Pricing Analysis
Certification level creates the primary spread between deployment tiers, with GB standards-compliant platforms in China commanding premiums over uncertified alternatives. Subscription-based SaaS licensing dominates software revenue, compressing upfront capital requirements for mid-tier municipal buyers. Price differentiation rests on algorithmic accuracy benchmarks and data-sovereignty infrastructure placement. Margins are tightening in hardware-software bundled offerings as GPU-accelerated edge nodes commoditize.
Supply Chain Analysis
Contract manufacturers in Taiwan and mainland China hold capacity for GPU-accelerated inference engines and edge-computing nodes. Supply draws from Japanese thermal sensor foundries, South Korean LiDAR component specialists, and Chinese PCB assembly clusters. Single-source vulnerability concentrates in advanced GPU silicon. Distribution runs through municipal systems integrators and direct vendor relationships with railway operators and resort complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data-localization mandates across India, China, and Australia are fragmenting infrastructure requirements, creating a high-growth disruption where compliance architecture becomes the primary competitive differentiator.
For Market Incumbents: Build regulatory moats through pre-certified edge-hardware bundles that satisfy TRAI localization and SAMR algorithmic transparency requirements simultaneously. Deepen relationships with Japanese railway operators and Singapore's integrated resort complexes to lock out cloud-native challengers. Invest in GPU kernel optimization talent pools to defend deployment timeline advantages against emerging platform vendors. For New Entrants and Emerging Players: Pursue Vietnam's secondary city smart infrastructure programs, where established analytics vendors remain underpenetrated and procurement offices lack technical evaluation capacity. Target Australia's retail analytics segment with explicit-consent-compliant facial recognition platforms that incumbent vendors must retrofit. Lead with hybrid deployment architectures that bridge municipal data sovereignty concerns with SaaS pricing flexibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed computer vision specialists possessing training datasets for Asian demographic conditions. The five-to-ten year viability window favors platforms with proven accuracy benchmarks tied to performance-based service level agreements. Monitor procurement pattern shifts in India's 100+ designated smart city urban corridors as the primary inflection indicator for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | GB standards and SAMR compliance timelines exceeding 18 months create barriers for foreign competitors. |
| GPU-Accelerated Edge Node Development | Sub-100-millisecond latency requirements in Singapore's Marina Bay clusters drive hardware differentiation. |
| Strategic Partnership with Municipal Integrators | Access to India's Ministry of Housing and Urban Affairs procurement channels accelerates smart city deployments. |
| Acquisition of Computer Vision Talent | Scarcity of GPU kernel optimization specialists delays edge-node deployment timelines for competitors. |
| Hybrid Cloud-Edge Architecture Launch | TRAI data-localization mandates and China's cybersecurity protocols fragment pure-cloud revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, railway operations directors, integrated resort technology managers, and edge-hardware engineering leads; and secondary validation against TRAI localization guidelines, METI industrial standards, SAMR algorithmic transparency requirements, and hyperscaler capex disclosures for AI infrastructure. Bottom-up triangulation across deployment topology segments was cross-checked with top-down market sizing.
Forecast inputs considered product type turnover cycles, end-user procurement patterns across transportation and retail verticals, and deployment topology shifts from on-premises to hybrid architectures. Segmentation dimensions modeled include software-hardware-services mix, end-use environment, deployment model, and application type. CAGRs were derived from iterative reconciliation of vendor revenue trajectories and buyer budget expansion rates across the projection horizon. Edge AI silicon availability and 5G-IoT convergence timelines served as technology-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in municipal infrastructure budgets, cross-border data flow restrictions, or GPU supply availability would shift the trajectory. Quarterly review of smart city procurement announcements, certification timeline changes, and edge-hardware shipment indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Event Stream Processing Market
Analytics
Latin America Location Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
United Kingdom Business Intelligence Market
Analytics
Global Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
Behavior Analytics Market
Analytics
Mobile Business Intelligence Market
Analytics
Dark Analytics Market
Analytics
Data Analysis Tools Market
Analytics
Mobile App Attribution Tool Market
Analytics
Global Marketing Attribution Software Market
Analytics
UK Video Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Online Analytical Processing Market
Analytics
Drone Analytics Software Market