
 Autonomous Polishing Machine Market | 2026-2036
Autonomous Polishing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Polishing Machine Market Insights
Buyer concentration among tier-one automotive suppliers is repositioning procurement leverage toward integrated automation platforms. Rösler Oberflächentechnik GmbH leverages its surface-engineering heritage to anchor robotic finishing lines in European manufacturing clusters. Fastems competes through flexible manufacturing system integration that extends autonomous polishing into unmanned night shifts. Acme Manufacturing dominates North American aerospace polishing with specialized multi-axis robotic cells.
An autonomous polishing machine is a self-directed material-finishing system that employs force-controlled end-effectors, vision-guided path planning, and real-time surface-quality feedback to achieve specified roughness parameters without direct human intervention. These systems execute precision finishing on turbine blades, stamped body panels, and semiconductor wafer edges where manual consistency proves unattainable. Robotic configurations lead current deployments due to their reach and payload flexibility across automotive and aerospace work envelopes. AI-Controlled technology is capturing the fastest expansion as machine-learning-based surface-defect recognition reduces rework rates and enables adaptive parameter adjustment during polishing cycles.
The EU Machinery Directive and CE marking framework mandate protective stops and collaborative speed limits that shape robot arm selection and guarding architecture. Germany's KBA and France's labor inspectorate enforce workplace safety protocols that accelerate demand for certified autonomous systems with documented risk assessments. China's SAMR issues GB standards for industrial robot safety that condition market access for imported polishing platforms. Stakeholders must monitor evolving certification requirements across multiple jurisdictions to avoid deployment delays and retrofit liabilities.
Market Dynamics
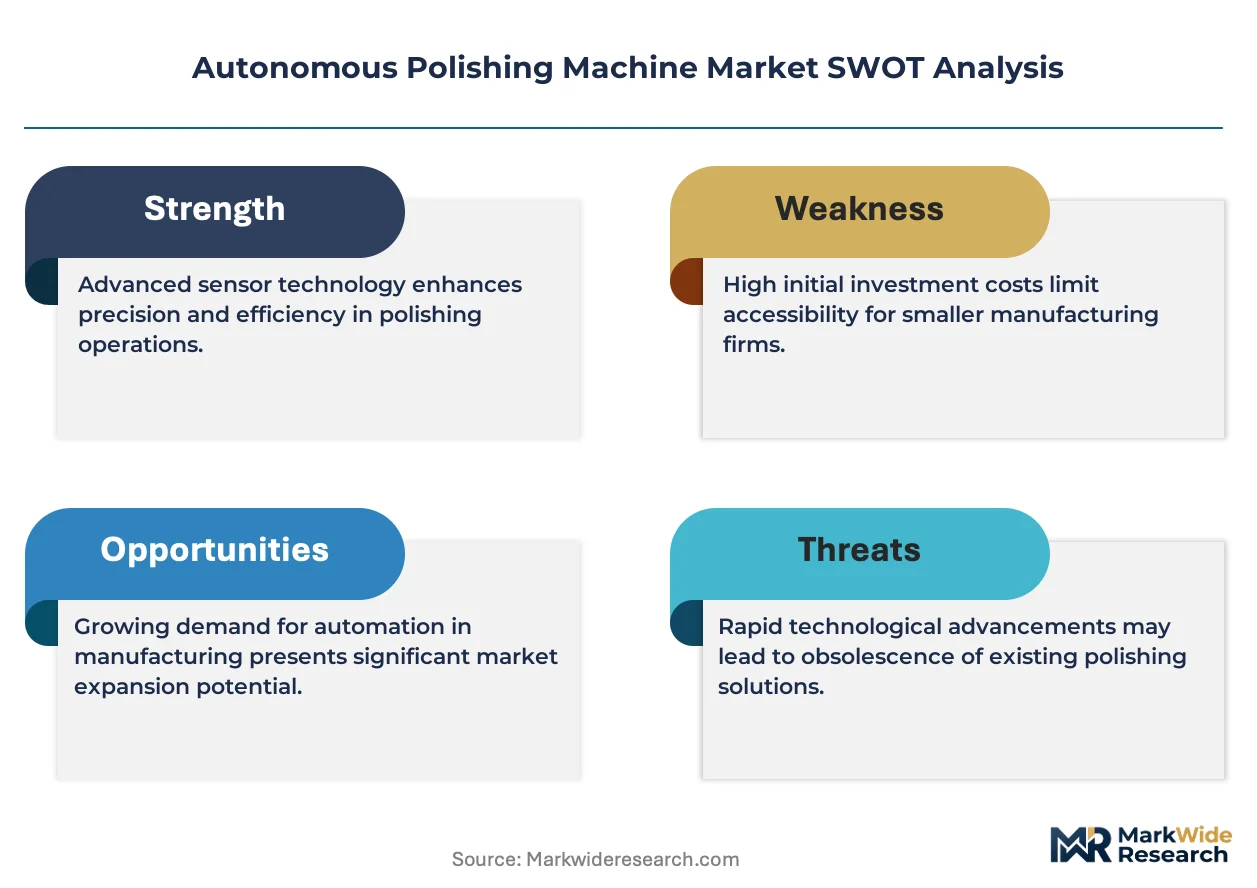
Tier-one automotive suppliers are consolidating procurement around integrated automation platforms, forcing polishing equipment vendors to bundle force-control software, vision systems, and predictive maintenance modules into single-source contracts rather than standalone hardware sales.
Growth Catalysts
- EU Machinery Directive compliance mandates:Protective stop requirements and collaborative speed limits under CE marking standards are accelerating replacement cycles for legacy non-certified polishing cells in European manufacturing facilities.
- Turbine blade finishing demand:Aerospace OEMs are deploying robotic polishing for nickel-based superalloy airfoils where manual consistency fails to meet surface roughness specifications for thermal barrier coating adhesion.
- Semiconductor wafer edge processing:Silicon carbide substrate manufacturers are adopting autonomous edge-polishing systems to eliminate micro-cracks that propagate during high-temperature epitaxy processes.
Market Restraints
- Force sensor input cost volatility:High-precision six-axis force/torque sensors utilizing semiconductor strain gauges face supply concentration among Japanese component suppliers, creating margin pressure for system integrators.
- Technical limitation in reflective surface path planning:Specular surfaces on polished aluminum automotive panels generate optical noise that degrades structured-light vision accuracy, requiring redundant tactile verification.
- Substitution threat from additive manufacturing:Metal 3D printing with near-net-shape surface finish is reducing post-processing polishing requirements for low-volume aerospace bracket production.
Strategic Opportunities
- Underpenetrated medical implant finishing:Orthopedic manufacturers in Switzerland and Ireland remain dependent on manual polishing for cobalt-chromium knee joints, creating white space for certified autonomous systems with FDA 21 CFR Part 820 documentation.
- Technology convergence of AI vision and haptic feedback:Machine-learning defect classification combined with real-time force modulation enables adaptive parameter adjustment without engineering intervention between part changeovers.
- India PLI scheme for automotive components:Production-linked incentive thresholds for advanced automotive technology parts are subsidizing capital equipment procurement for supplier parks in Tamil Nadu and Gujarat.
Industry Challenges
- Multi-physics simulation talent scarcity:Polishing process modeling requires coupled knowledge of abrasive mechanics, thermal dynamics, and robot kinematics that resides in fragmented academic programs rather than vendor training centers.
- CE marking certification timeline compression:Third-party notified body queues for machinery safety validation are extending deployment schedules by four to eight months for European automotive supplier contracts with fixed SOP dates.
- Legacy PLC integration complexity:Brownfield installations require protocol translation between modern ROS-based polishing controllers and decades-old proprietary shop floor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Polishing Machine Market |
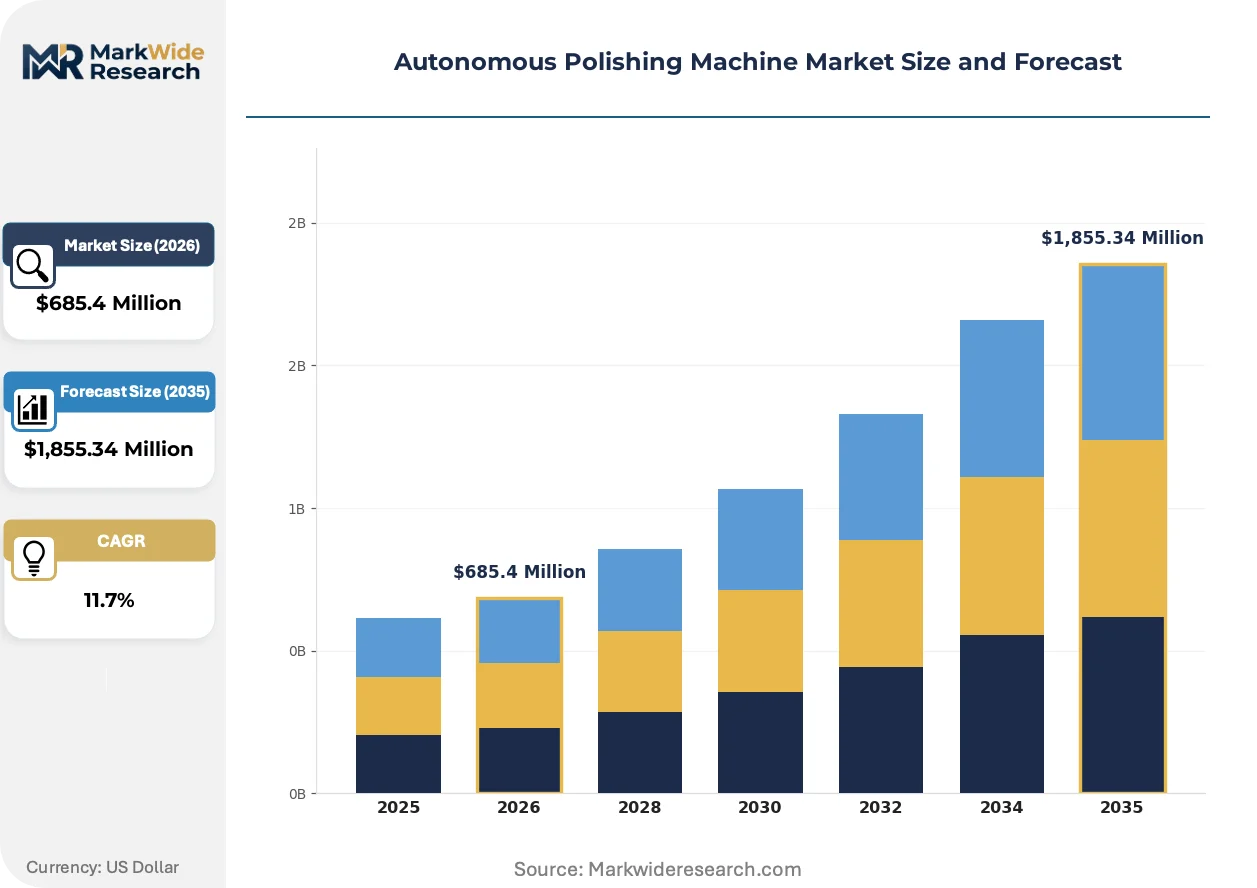
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Robotic, Desktop, Industrial Technology: AI-Controlled, Laser, Ultrasonic, Magnetic End User: Aerospace, Automotive Parts, Electronics Manufacturing, Metalwork Application: Surface Finishing, Polishing, Deburring, Cleaning |
| Companies Covered | Rösler Oberflächentechnik GmbH, Walther Trowal GmbH, OTEC Präzisionsfinish GmbH, LXD Robotics, Acme Manufacturing, Fastems, AV?R, Logen Robot, DANBACH ROBOT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Polishing Machine Market Trends and Innovations
Digital twin technology is compressing commissioning timelines for polishing cells by enabling virtual force-profile validation before physical installation. Three developments are restructuring competitive positioning.
Adaptive polishing algorithms utilizing reinforcement learning are automating parameter selection for heterogeneous surface conditions. Automotive stamping plants in Germany are deploying these systems for body panel finishing where manual teach-pendant programming consumed excessive engineering hours. The technology is automating the transition from fixed-cycle to condition-responsive polishing, reducing rework rates and enabling unmanned night-shift operation.
China's SAMR enforcement of updated GB standards for collaborative robot safety is mandating functional safety certifications that exceed prior self-declaration requirements. Industrial robot importers must now submit third-party test reports for protective stop response times and force-limiting performance. Polish and Czech automotive suppliers sourcing Chinese robot arms are experiencing procurement delays as certification documentation backlogs accumulate at notified bodies.
After-sales service unbundling is disrupting traditional equipment vendor revenue models. Tier-one suppliers are separating hardware procurement from software maintenance contracts, engaging specialized predictive analytics firms for spindle vibration monitoring and abrasive consumption forecasting. This pattern is most visible in North American aerospace manufacturing clusters where capital equipment and operational technology budgets report through different procurement hierarchies.
Autonomous Polishing Machine Market Segmentation
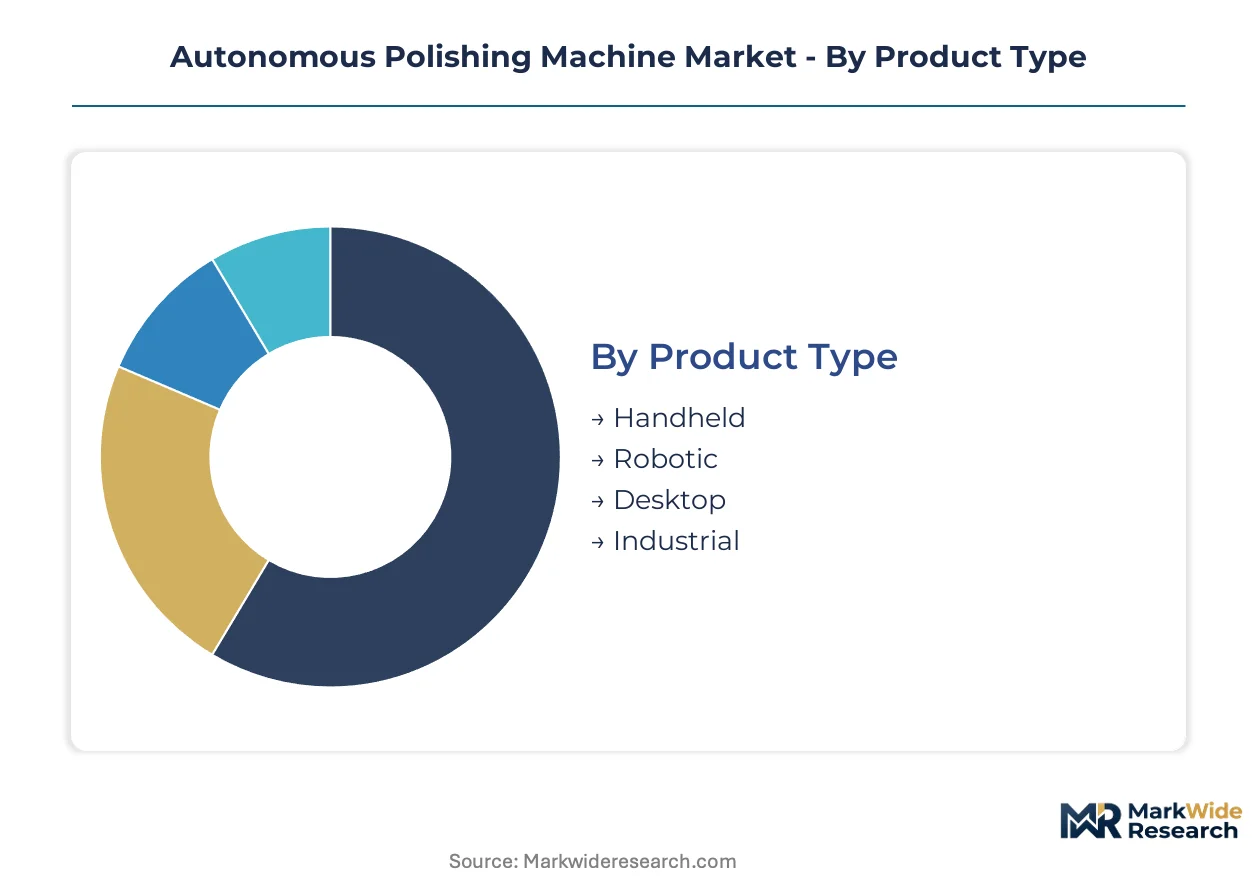
Autonomous polishing machines fragment across hardware configurations, control architectures, and industrial workflows. Each segmentation axis reveals distinct procurement patterns and technical requirements that shape vendor positioning and customer switching costs.
Product Type:
Standardization decreases as payload and reach increase, with handheld units offering maximum flexibility and industrial systems requiring extensive integration engineering.
- Robotic:Articulated arm configurations with force-controlled end-effectors dominate automotive body panel and aerospace turbine blade finishing. German automotive supplier parks in Baden-Württemberg and Bavaria anchor current installed capacity for six-axis polishing cells.
- Industrial:Gantry-mounted or Cartesian systems handle large work envelopes for wind turbine components and marine propellers. These installations concentrate in shipbuilding clusters along Poland's Baltic coast and heavy fabrication yards.
- Handheld:Portable units with haptic feedback serve repair operations and low-volume custom metalwork shops.
- Desktop:Compact systems target dental implant laboratories and jewelry manufacturing for precision micro-finishing.
Most installed capacity flows through Robotic configurations. Expansion is steepest in Industrial systems for renewable energy component manufacturing.
Technology:
Control sophistication determines price positioning, with rule-based automation at the base and adaptive learning systems commanding premium positioning.
- AI-Controlled:Machine vision classifies surface defects in real time while reinforcement learning optimizes force and speed parameters mid-cycle. Semiconductor wafer edge processing in Hsinchu and Dresden fabs drives fastest adoption for defect reduction.
- Laser:Directed energy polishing achieves sub-micron finishes on optical molds and medical implants without abrasive contact. Swiss orthopedic manufacturers in Valais deploy these systems for cobalt-chromium knee joint finishing.
- Ultrasonic:High-frequency vibration assists abrasive action for complex internal geometries in additive-manufactured parts.
- Magnetic:Magnetorheological fluid finishing enables conformal polishing of freeform surfaces in mold and die production.
AI-Controlled systems capture the fastest-growing trajectory as surface-defect recognition reduces engineering intervention between part changeovers.
End User:
Certification requirements and surface-finish specifications create tiered entry barriers across manufacturing verticals.
- Automotive Parts:Stamping plants and powertrain component suppliers deploy robotic cells for body panel and crankshaft finishing. Tier-one supplier consolidation around integrated automation platforms concentrates demand in Germany, Japan, and Michigan.
- Aerospace:Nickel-based superalloy turbine blades and structural brackets require documented surface roughness for thermal barrier coating adhesion. OEM qualification protocols in Toulouse, Hamburg, and Seattle extend sales cycles.
- Electronics Manufacturing:Silicon carbide substrate and advanced packaging facilities adopt edge-polishing systems to eliminate micro-cracks.
- Metalwork:Job shops and general fabrication serve construction equipment and agricultural machinery with lower specification requirements.
Procurement volume concentrates in Automotive Parts. Technology investment intensity peaks in Aerospace due to qualification overhead.
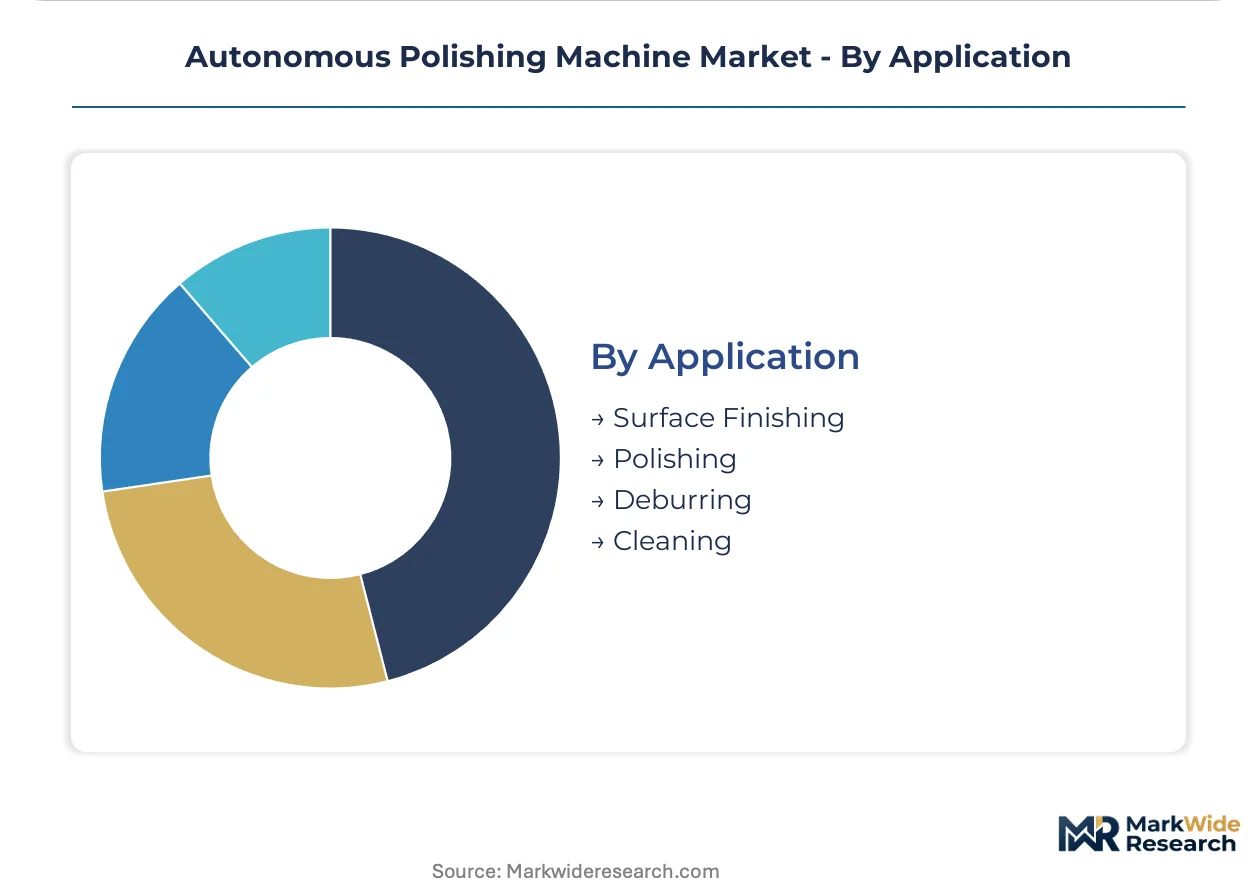
Application:
Process sequence positioning determines system architecture, with upstream roughing operations tolerating higher material removal variance than final finishing stages.
- Surface Finishing:Final-stage operations achieve specified roughness parameters for coating adhesion, sealing performance, or aesthetic requirements. Automotive OEM paint shops in Stuttgart and Wolfsburg mandate consistent surface preparation.
- Polishing:Intermediate and final abrasive operations improve gloss and tactile properties on visible consumer surfaces.
- Deburring:Edge-breaking and flash removal from castings, stampings, and machined components precedes finishing operations.
- Cleaning:Pre-process and post-process surface preparation removes contaminants and residual abrasive media.
System complexity concentrates in Surface Finishing. Operational technology integration spending runs highest in Deburring for unmanned production line continuity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier density contrasts with China's semiconductor fabrication expansion, while the United States anchors aerospace turbine blade demand. Regulatory frameworks and industrial clustering patterns create divergent procurement timelines across these manufacturing centers.
Germany
Baden-Württemberg and Bavaria host dense networks of tier-one automotive suppliers deploying robotic polishing cells for body panel consistency. The KBA enforces workplace safety protocols that accelerate certified autonomous system procurement with documented risk assessments. Stuttgart's stamping plants mandate surface preparation standards that drive technology investment intensity.
China
Silicon carbide substrate manufacturers in Hsinchu-adjacent fabrication zones adopt autonomous edge-polishing systems for epitaxy process reliability. SAMR's updated GB standards for collaborative robot safety mandate third-party functional safety certifications beyond prior self-declaration. Supplier parks in the Yangtze River Delta experience procurement delays as certification documentation backlogs accumulate.
United States
Aerospace OEMs in Seattle and Hartford deploy robotic polishing for nickel-based superalloy turbine blades requiring thermal barrier coating adhesion. FAA qualification protocols extend sales cycles for surface-finishing equipment vendors. Michigan's powertrain component suppliers consolidate procurement around integrated automation platforms with predictive maintenance modules.
Japan
Semiconductor wafer edge processing facilities in Kyushu and Chubu adopt AI-controlled systems for defect reduction during high-temperature processes. METI industrial robot safety guidelines condition market access for imported polishing platforms. Nagoya's automotive stamping plants represent concentrated demand for force-controlled end-effector technology.
Switzerland
Orthopedic manufacturers in Valais remain dependent on manual polishing for cobalt-chromium knee joints, creating white space for certified autonomous systems. Swissmedic and FDA 21 CFR Part 820 documentation requirements shape vendor selection criteria. Geneva's precision-engineering clusters drive laser polishing adoption for sub-micron medical implant finishes.
Autonomous Polishing Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware configuration and control architecture segments. The vendor base stratifies into three tiers: integrated automation platform providers, surface-engineering heritage specialists, and regional fabrication equipment suppliers. Strategic moves concentrate on bundling force-control software with vision systems and predictive maintenance modules into single-source contracts. Geographic expansion through distributor networks and technology licensing agreements for AI vision modules dominate competitive activity.
Among German surface-engineering specialists, Rösler Oberflächentechnik GmbH and OTEC Präzisionsfinish GmbH occupy positions anchored in European manufacturing clusters, while Fastems exemplifies the flexible manufacturing system integration archetype extending autonomous polishing into unmanned production schedules. Acme Manufacturing represents the North American aerospace-focused configuration, with LXD Robotics and DANBACH ROBOT sitting within the Asian robotics supplier tier serving semiconductor and automotive fabrication zones.
| Leading Market Players |
|---|
| Rösler Oberflächentechnik GmbH |
| Walther Trowal GmbH |
| OTEC Präzisionsfinish GmbH |
| LXD Robotics |
| Acme Manufacturing |
| Fastems |
| AV?R |
| Logen Robot |
| DANBACH ROBOT |
| Others |
Pricing and Supply Chain Analysis
Captive production of force-control software and vision systems by integrated automation platform vendors anchors both supply security and pricing power in this market. Tier-one automotive suppliers in Germany and Japan bundle hardware procurement with predictive maintenance contracts, compressing margins for standalone equipment vendors while rewarding vertically integrated providers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for robotic polishing cells as domestic manufacturers achieve functional safety certifications under SAMR's updated GB standards. Three-tier pricing structure across premium, standard, and economy levels separates AI-controlled adaptive systems from rule-based automation and refurbished legacy installations. Pricing pressure stems from Japanese component suppliers' concentration in six-axis force/torque sensors. Job shops and metalwork fabricators exhibit highest price sensitivity; aerospace OEMs prioritize qualification documentation over unit cost.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg and Bavaria are accelerating supplier investment in unmanned night-shift capable systems. Component sourcing draws from Japan for precision force sensors, Germany for machine vision modules, and China for collaborative robot arms. Single-source vulnerability concentrates in semiconductor strain gauge suppliers. Distribution runs through direct OEM relationships for tier-one automotive and aerospace accounts, with regional distributors serving job shop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as surface-finish specifications tighten across automotive, aerospace, and semiconductor verticals, forcing replacement cycles for non-compliant legacy equipment.
For Market Incumbents: Hedge against additive manufacturing substitution by deepening software moats—bundle force-control algorithms with predictive maintenance modules into multi-year service contracts. Acquire specialized vision-system developers to close capability gaps in reflective surface path planning before Chinese competitors achieve CE marking parity.
For New Entrants and Emerging Players: Launch via technology licensing agreements for AI vision modules rather than capital-intensive hardware manufacturing. Target medical implant finishing in Switzerland and Ireland where FDA 21 CFR Part 820 documentation requirements deter established automation vendors. Prioritize orthopedic knee joint applications over saturated automotive body panel segments.
For Investors and Strategic Acquirers: Roll-up economics work for surface-engineering heritage specialists because tier-one supplier consolidation favors single-source automation platforms with documented risk assessments. Five-to-ten year viability hinges on regulatory certification depth rather than hardware cost position. Monitor CE marking certification queue lengths at notified bodies as inflection indicator for European deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Vision Module Acquisition | Machine-learning defect classification accelerates adaptive parameter adjustment without engineering intervention between part changeovers. |
| CE Marking Certification Investment | Third-party functional safety validation unlocks European automotive supplier contracts with fixed SOP dates. |
| Medical Implant Specialization | FDA 21 CFR Part 820 documentation capabilities open orthopedic manufacturing in Switzerland and Ireland. |
| Predictive Maintenance Service Unbundling | Spindle vibration monitoring and abrasive consumption forecasting separate hardware from recurring revenue streams. |
| India PLI Scheme Localization | Production-linked incentive thresholds subsidize capital equipment procurement for Tamil Nadu and Gujarat supplier parks. |
Research Methodology
Direct dialogue with plant engineers at tier-one automotive suppliers, aftermarket service heads at surface-engineering specialists, OEM procurement teams in aerospace manufacturing clusters, and robotics integration specialists anchored qualitative findings. Secondary validation drew from KBA workplace safety enforcement records, SAMR GB standard update notifications, FAA qualification protocol documentation, and semiconductor fabrication equipment trade data. Bottom-up installation counts triangulated against top-down automation spending estimates.
Segment-level projections across robotic, industrial, handheld, and desktop configurations combined with AI-controlled, laser, ultrasonic, and magnetic technology tiers informed value estimates over the projection horizon. Automotive parts, aerospace, electronics manufacturing, and metalwork end-use splits modeled separately. CAGRs derived from replacement cycle analysis of non-certified legacy polishing cells and greenfield adoption curves in semiconductor wafer edge processing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended CE marking certification timelines or accelerated additive manufacturing penetration in aerospace brackets. Material deviation in force sensor supply concentration or collaborative robot safety regulatory enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Sweden Robotic Lawn Mower Market