
 Global Analytics Market | 2026-2036
Global Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Analytics Market Analysis
Platform licensing revenue is rewriting margin distribution across the analytics value chain. Microsoft Corporation leverages its Azure cloud infrastructure to anchor enterprise deployments across multiple verticals. SAP SE sustains dominance in operational analytics through deep ERP integration and industry-specific modules. IBM Corporation competes in the predictive analytics segment with Watson-powered tools targeting healthcare and financial risk applications.
Analytics encompasses the systematic computational analysis of data through statistical algorithms, machine learning models, and query-based processing to extract actionable intelligence from structured and unstructured datasets. The discipline relies on distributed computing frameworks, in-memory processing architectures, and SQL-plus-NoSQL hybrid engines to handle petabyte-scale throughput with sub-second latency for real-time decisioning. Cloud-based deployment leads solution type distribution as enterprises abandon capital-intensive on-premise data centers for elastic consumption models. Predictive analytics represents the fastest-expanding solution category as manufacturing and BFSI end users deploy forecasting tools for supply chain optimization and credit risk scoring. Customer analytics applications command premium pricing within the marketing analytics subset due to high attribution accuracy requirements and cross-channel identity resolution complexity.
The US FDA governs analytics deployment in pharmaceutical clinical trials through 21 CFR Part 11 validation requirements, while the EU AI Act imposes conformity assessments on high-risk algorithmic systems used in credit scoring and insurance pricing. China's SAMR enforces algorithmic recommendation transparency rules that affect consumer analytics platforms operating in that jurisdiction. Stakeholders must monitor divergence between EU risk-based AI governance and US sectoral agency guidance when architecting multinational analytics deployments.
Market Dynamics
Cloud migration mandates under GDPR and the EU AI Act are forcing enterprises to re-architect analytics infrastructure around elastic consumption models, compressing traditional on-premise deployment timelines.
Growth Catalysts
- EU AI Act Conformity Assessments:High-risk algorithmic systems in credit scoring and insurance pricing face mandatory compliance deadlines, creating immediate procurement pull for validated analytics platforms.
- Healthcare Outcome Optimization:Providers deploy patient flow analytics and clinical decision support systems to reduce readmission penalties and optimize resource allocation.
- In-Memory Processing Architectures:Sub-second latency requirements for real-time decisioning drive replacement of disk-based query engines with distributed RAM clusters.
Market Restraints
- Specialized Talent Scarcity:Shortage of MLOps engineers and data governance specialists extends implementation timelines and inflates professional services costs.
- Cross-Border Data Localization:China's SAMR algorithmic transparency rules and EU GDPR data residency requirements fragment cloud architecture strategies.
- Legacy System Entrenchment:Decades-old ERP investments in manufacturing and BFSI verticals resist API-based integration with modern analytics stacks.
Strategic Opportunities
- Saudi Arabia's Digital Transformation:MOHAP health data interoperability mandates and SFDA regulatory modernization create greenfield deployment opportunities.
- Edge Analytics Convergence:Manufacturing and logistics operators combine 5G connectivity with lightweight inference engines for shop-floor decision autonomy.
- CSRD Sustainability Reporting:EU corporate sustainability disclosure requirements mandate granular emissions tracking, expanding ESG analytics module demand.
Industry Challenges
- 21 CFR Part 11 Validation:Pharmaceutical analytics deployments require extensive documentation and audit trails, extending sales cycles.
- Interoperability Standard Fragmentation:Competing health data exchange protocols complicate multi-vendor analytics environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Analytics Market |
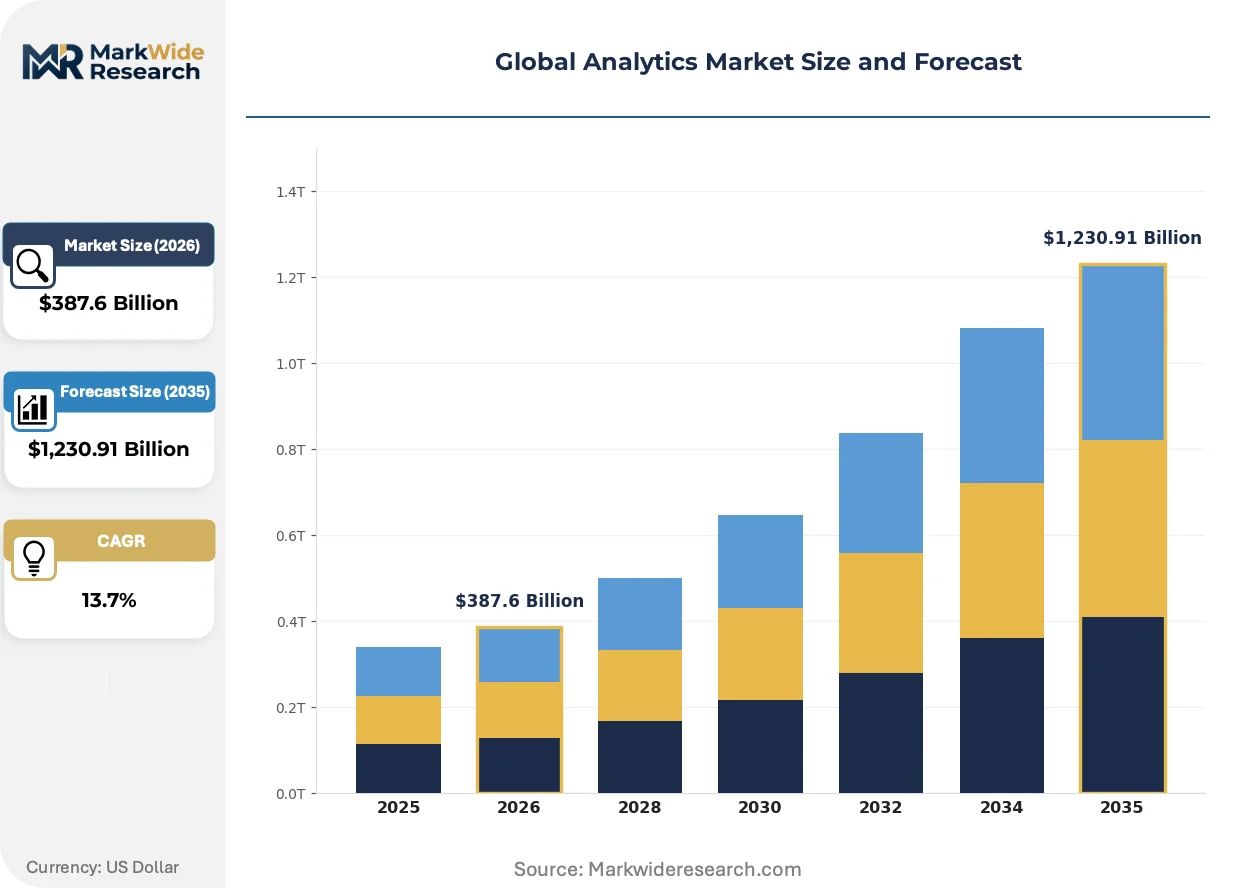
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,230.91 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Solution Type: Data Visualization, Predictive Analytics, Descriptive Analytics, Real-Time Analytics End User: Healthcare, Retail, Manufacturing, BFSI Application: Customer Analytics, Operational Analytics, Marketing Analytics, Risk Management |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Amazon Web Services, SAS Institute Inc., Alphabet Inc., Tableau Software, Databricks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Analytics Market Emerging Trajectories
Real-time inference capabilities are compressing decision windows across operational and strategic use cases, while regulatory fragmentation forces architectural flexibility.
SQL-plus-NoSQL hybrid query engines are migrating from batch-oriented data warehouses to streaming-first architectures. Financial services clusters in New York deploy these engines for intraday risk recalculation. The technology is migrating from historical aggregation toward continuous pattern detection, collapsing the latency gap between data ingestion and actionable output.
REACH substance restriction protocols and RoHS hazardous material limits affect hardware procurement for on-premise analytics appliances. Equipment manufacturers reformulate circuit board compositions and cooling system chemistries. EU-based deployments face the steepest compliance cost adjustments, with some operators accelerating full-cloud abandonment of physical infrastructure.
Consumption-based licensing is replacing perpetual software agreements across enterprise procurement functions. Technology corridors in California and financial services buyers in London lead this transition. Japan's METI guidelines on software asset depreciation accelerate the shift in Asia-Pacific manufacturing headquarters.
Global Analytics Market Segmentation
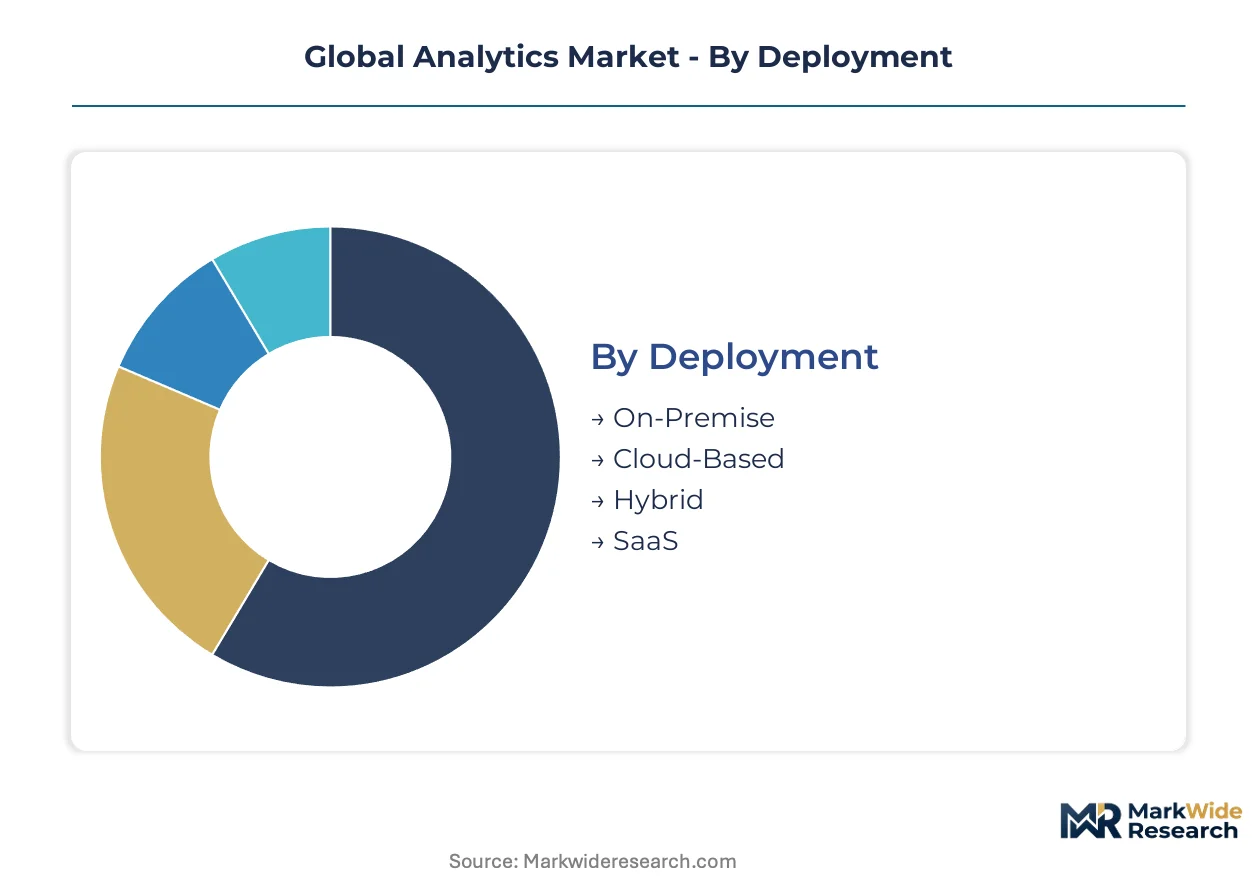
Deployment architecture determines procurement economics and compliance posture for analytics infrastructure. Solution type selection reflects latency requirements and decision-velocity demands across operational contexts.
Deployment:
Cost tier differentiation separates capital-intensive ownership from elastic consumption models.
- Cloud-Based:Elastic compute and storage resources provisioned through hyperscaler infrastructure eliminate data center capital expenditure. Financial services clusters in New York and technology corridors in California concentrate procurement, driven by GDPR data residency mandates and EU AI Act conformity deadlines.
- SaaS:Pre-configured analytics modules delivered through browser interfaces compress implementation timelines from quarters to weeks. Healthcare providers in the United States prioritize this tier for patient outcome analytics, constrained by HIPAA audit requirements and specialized MLOps talent scarcity.
- On-Premise:Dedicated hardware installations within enterprise-controlled facilities.
- Hybrid:Workload-splitting architectures combining local processing with cloud burst capacity.
Cloud-Based commands the established base. The steepest expansion runs through SaaS.
Solution Type:
Application focus distinguishes retrospective aggregation from forward-looking inference capabilities.
- Predictive Analytics:Machine learning models trained on historical patterns generate probability-weighted forecasts for credit scoring and supply chain disruption. Manufacturing and BFSI end users in Germany and Japan deploy these tools for inventory optimization and risk recalculation.
- Real-Time Analytics:Streaming data pipelines with sub-second latency enable immediate operational response. Logistics operators in the Netherlands combine 5G edge connectivity with lightweight inference engines for warehouse automation and fleet routing decisions.
- Data Visualization:Interactive dashboards translating query outputs into graphical representations.
- Descriptive Analytics:Historical aggregation and pattern reporting from structured datasets.
Descriptive Analytics commands the established base. Predictive Analytics gains share fastest.
End User:
Customer type segmentation maps regulatory exposure and data sovereignty requirements.
- BFSI:Risk scoring, fraud detection, and algorithmic trading systems subject to SEC, FERC, and EU AI Act oversight. New York and London financial clusters drive premium procurement for validated platforms.
- Healthcare:Clinical decision support and patient flow optimization facing FDA 21 CFR Part 11 and EMA validation requirements.
- Manufacturing:Shop-floor quality control and predictive maintenance deployments.
- Retail:Cross-channel customer analytics and demand forecasting applications.
BFSI commands the established base. Healthcare climbs the fastest.
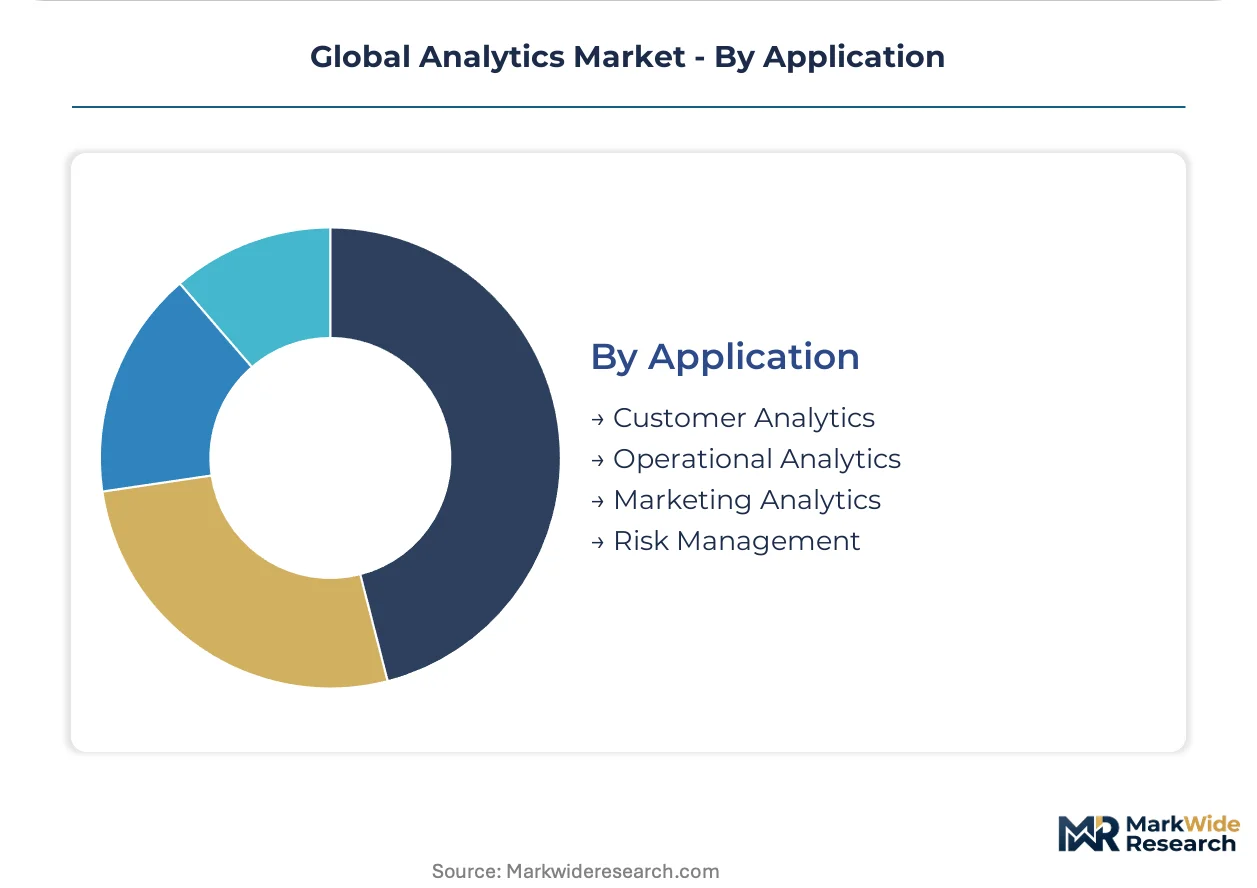
Application:
Functional use case determines integration complexity and attribution accuracy requirements.
- Customer Analytics:Identity resolution across touchpoints and attribution modeling for marketing spend optimization. Premium pricing reflects cross-channel data fusion complexity and GDPR consent management overhead.
- Risk Management:Credit scoring, insurance pricing, and operational risk quantification subject to EU AI Act high-risk system classifications and conformity assessments.
- Operational Analytics:Process efficiency and resource allocation optimization.
- Marketing Analytics:Campaign performance measurement and audience segmentation.
Operational Analytics commands the established base. Risk Management shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler infrastructure investments concentrate in the United States, Germany, and China, with regulatory divergence across GDPR, EU AI Act, and SAMR jurisdictions reshaping data residency architectures. Enterprise procurement clusters in financial services and healthcare verticals drive national-level demand differentiation.
United States
Financial services clusters in New York and technology corridors in California anchor cloud-based analytics procurement. The FDA governs pharmaceutical deployments through 21 CFR Part 11 validation requirements. Healthcare providers in Boston and Minneapolis deploy patient outcome optimization systems under HIPAA audit frameworks.
Germany
Manufacturing headquarters in Stuttgart and Munich drive predictive analytics adoption for supply chain optimization. The EU AI Act imposes conformity assessments on credit scoring and insurance pricing algorithms. Industrial operators in the Ruhr region combine operational analytics with CSRD sustainability reporting modules.
China
Consumer analytics platforms face SAMR algorithmic recommendation transparency rules affecting personalization engines. Technology corridors in Shenzhen and Beijing concentrate domestic cloud infrastructure investment. State-backed financial institutions in Shanghai deploy risk scoring systems under central bank guidance.
United Kingdom
Financial services buyers in London lead consumption-based licensing transitions away from perpetual agreements. The Financial Conduct Authority oversees algorithmic trading system deployments. Healthcare analytics procurement in Manchester and Birmingham concentrates on NHS interoperability mandates.
Japan
Manufacturing headquarters in Tokyo and Osaka accelerate predictive maintenance analytics under METI software asset depreciation guidelines. Automotive suppliers in Nagoya deploy real-time quality control systems. BFSI operators in the Kanto region prioritize validated platforms for credit risk applications.
Global Analytics Market Vendor Landscape
Cloud-native specialists and legacy ERP-integrated incumbents split the market along deployment architecture lines. Consolidation pressure intensifies as platform licensing revenue concentrates margin capture with infrastructure owners. Three archetypes dominate: hyperscaler-anchored suites, operational analytics specialists with deep system integration, and vertical-specific predictive tools. Competitive moves center on API-based ecosystem expansion and consumption model transitions.
Within the hyperscaler-anchored tier, Microsoft Corporation and Amazon Web Services exemplify infrastructure-led platform strategies. SAP SE occupies a position among ERP-integrated operational analytics providers. IBM Corporation represents the predictive analytics specialist archetype targeting regulated verticals. Each anchors distinct procurement evaluation criteria across enterprise buyers.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Amazon Web Services |
| SAS Institute Inc. |
| Alphabet Inc. |
| Tableau Software |
| Databricks Inc. |
| Others |
Supply Flow & Price Mechanics
Cross-border data localization mandates under GDPR and China's SAMR rules determine both pricing tier spreads and supply chain shape for analytics infrastructure procurement. Enterprises face compliance-driven cost premiums for validated platforms while cloud hyperscalers re-architect regional data residency architectures to capture margin.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for high-risk algorithmic systems in credit scoring and insurance pricing, mandating conformity assessment overhead that stratifies offerings across premium validated, standard compliant, and economy unvalidated tiers. Certification level and vertical integration depth drive price differentiation, with FDA 21 CFR Part 11 validation for pharmaceutical deployments commanding the steepest premiums. Cost compression in the economy tier intensifies because hyperscaler infrastructure commoditization erodes margins for undifferentiated compute. Healthcare providers exhibit the highest price sensitivity due to constrained capital budgets, while BFSI operators in New York and London demonstrate the lowest sensitivity given regulatory penalty exposure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for on-premise analytics hardware procurement, particularly affecting GPU-accelerated inference appliances and specialized memory modules. Manufacturing concentrates in Taiwan, South Korea, and the United States for advanced semiconductors, while China anchors mid-tier server assembly. Component dependencies span high-bandwidth memory dies, custom ASICs, and liquid cooling systems. Distribution runs through hyperscaler direct procurement channels for cloud-based deployments, with systems integrators and value-added resellers handling on-premise enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Analytics Market sits in early-cycle expansion as EU AI Act conformity deadlines force immediate procurement pull for validated platforms across credit scoring and insurance pricing. Cloud migration mandates are compressing traditional deployment timelines while creating greenfield infrastructure demand.
For Market Incumbents: Insulate platform revenue by deepening ERP integration moats in manufacturing and BFSI verticals where decades-old system entrenchment resists API-based replacement. Prioritize certification investment for EU AI Act high-risk system classifications to capture conformity assessment premiums before compliance deadlines harden procurement criteria. Defend against cloud-native specialists by anchoring consumption-based licensing transitions through existing enterprise relationships.
For New Entrants and Emerging Players: Mid-market healthcare providers in Saudi Arabia and the United Arab Emirates represent the most penetrable entry point, given MOHAP health data interoperability mandates and SFDA regulatory modernization creating greenfield deployment opportunities. Edge analytics convergence in manufacturing and logistics offers secondary white-space, combining 5G connectivity with lightweight inference engines for shop-floor autonomy. A vertical-specific go-to-market angle targeting CSRD sustainability reporting modules for EU industrial operators bypasses incumbent ERP lock-in.
For Investors and Strategic Acquirers: EU AI Act implementation timelines reshape the acquisition landscape, favoring targets with existing conformity assessment infrastructure and validated healthcare or BFSI deployments. Long-term viability hinges on consumption model transition completion and API-based ecosystem expansion rather than perpetual license maintenance. The signal to watch is hyperscaler partnership depth, as infrastructure anchoring determines platform distribution economics across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and AWS hyperscaler anchoring determines enterprise distribution economics for analytics suites. |
| Regulatory Certification | FDA 21 CFR Part 11 and EU AI Act validation opens pharmaceutical and high-risk BFSI procurement channels. |
| Vertical Specialization | Healthcare outcome optimization and CSRD sustainability modules command premium pricing through compliance integration. |
| Consumption Model Transition | Elastic licensing replaces perpetual agreements, concentrating recurring revenue with infrastructure owners. |
| Edge Analytics Development | 5G-connected lightweight inference engines enable manufacturing shop-floor decision autonomy outside cloud dependency. |
Methodological Framework
Desk research of hyperscaler infrastructure investment disclosures, regulatory filing databases, and enterprise software procurement records preceded structured interviews with CTOs, IT procurement officers, platform engineers, and healthcare informatics directors. Primary fieldwork combined with secondary validation across SEC filings, EU regulatory guidance documents, and cloud service provider capex disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Fixed assumptions held regulatory implementation timelines and hyperscaler regional expansion plans constant across the projection horizon, while varying enterprise cloud migration velocity and MLOps talent availability scenarios. Segmentation dimensions modeled deployment architecture, solution type, end-user vertical, and application functional use case alongside regional adoption pattern differentiation. CAGRs derived from historical trajectory analysis and penetration curve benchmarking against comparable software infrastructure markets, with inputs from healthcare digital transformation spend and BFSI risk technology budgets.
Practitioners should monitor EU AI Act enforcement consistency and SAMR algorithmic transparency rule expansion for early signals of compliance cost inflation or procurement delay. Forecasts reflect assumptions about regulatory divergence persistence and cloud infrastructure commoditization pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Enterprise Drone Analytics Software Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Embedded Analytics Market
Analytics
CSP Network Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
HR Analytics Market
Analytics
Speech and Voice Analytics Market
Analytics
Global Network Analytics Market
Analytics
Europe Supply Chain Analytics Market
Analytics
Israel ICT Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Social Business Intelligence Market
Analytics
Operational Intelligence Market
Analytics
TV Analytics Solutions Market