
 Patent Analytics Services Market | 2026-2036
Patent Analytics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Patent Analytics Services Market Outlook
The patent analytics services market is repositioning around a widening capability gap between premium AI-native platforms and commoditized bibliographic search tools. Clarivate leverages its Derwent Innovation heritage and Web of Science integration to sustain pricing power at the high end. LexisNexis anchors its position through proprietary patent linkage databases and regulatory intelligence overlays. Questel competes on geographic coverage, operating pan-European filing analytics that dominate EPO opposition workflows.
Patent analytics services encompass the systematic extraction, visualization, and strategic interpretation of patent documents, claims mappings, and prosecution histories using machine-classified technology taxonomies and citation network algorithms. These services enable R&D prioritization, competitive monitoring, and litigation risk quantification across technology-intensive industries. Search services and monitoring services lead current revenue composition, though valuation services are expanding fastest as private equity and corporate M&A teams require defensible patent-backed due diligence. Cloud-based delivery models now capture the dominant share of new deployments, while hybrid architectures persist in sectors with stringent data residency requirements.
The USPTO's patent quality initiatives and the EU's Unitary Patent System reshape demand for prior-art depth and territorial claim construction. ISO 9001-certified analytics providers gain procurement preference from Fortune 500 legal departments. China's NMPA patent linkage regulations and Japan's METI intellectual property strategy reviews add jurisdictional complexity that specialized vendors must navigate. Stakeholders should monitor how generative AI transforms claim-charting productivity and whether regulatory bodies mandate algorithmic transparency in automated invalidity assessments.
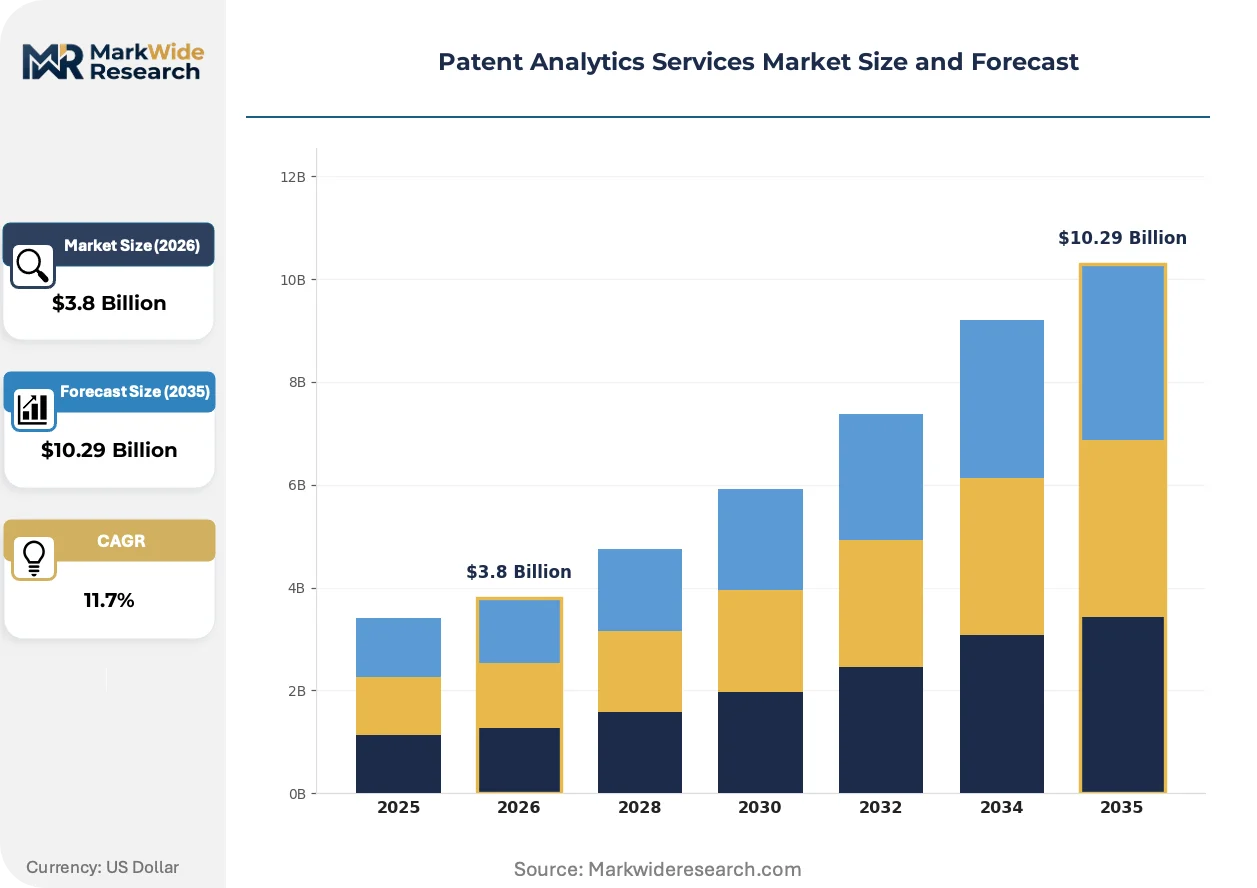
Market Dynamics
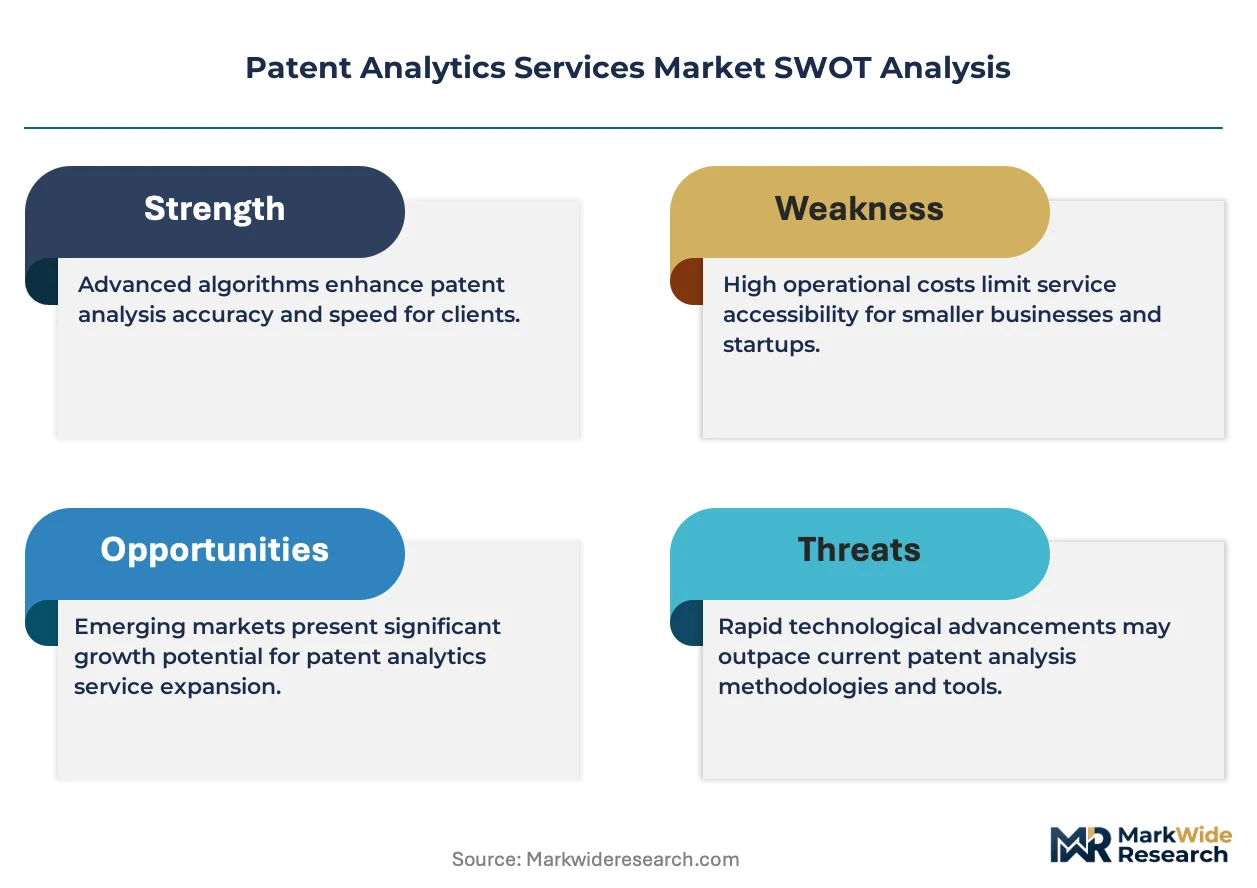
Generative AI is compressing claim-charting timelines from weeks to hours, forcing incumbent platforms to retrain models on proprietary prosecution histories or surrender pricing power to API-first entrants.
Growth Catalysts
- EU Unitary Patent System:The streamlined territorial coverage is amplifying demand for pan-European freedom-to-operate studies as filers consolidate portfolio strategies around single-unit enforcement.
- Pharmaceutical patent linkage:China's NMPA regulations now tie generic approvals to originator patent status, requiring litigation-risk analytics for biosimilar entrants mapping exclusivity cliffs.
- Private equity due diligence:Buyout firms now mandate patent-backed valuation for technology targets, expanding analytics scope from legal departments to transaction advisory workflows.
Market Restraints
- Data residency mandates:Germany's BSI certification requirements and China's data localization rules fragment cloud architectures, forcing redundant infrastructure spend.
- Training data scarcity:Machine learning models for claim construction require annotated prosecution histories that remain locked behind USPTO PAIR access tiers and national paywalls.
- Substitution by open-source tools:Free patent databases from EPO and USPTO satisfy basic monitoring needs for cost-conscious SME filers, capping price elasticity at the low end.
Strategic Opportunities
- India's PLI scheme:Domestic manufacturing incentives for semiconductors and pharmaceuticals are generating first-time patent filing volumes that lack local analytics capacity.
- Standard-essential patent pools:5G and Wi-Fi 7 licensing consortia require automated essentiality assessment tools that remain underdeveloped for telecommunications hardware.
- Climate technology taxonomies:The EU Green Deal's patent classification for clean tech is creating demand for carbon-accounting-linked IP strategy services that cross-reference emission disclosures.
Industry Challenges
- Prompt engineering talent scarcity:Firms struggle to hire analysts who combine patent prosecution expertise with large language model fine-tuning for invalidity search automation.
- ISO 9001 certification timelines:Analytics providers face 12-18 month quality management audits to qualify for Fortune 500 legal department vendor lists, delaying revenue recognition.
- Legacy system integration:Corporate IP management databases from the 2000s lack API connectivity, forcing manual data extraction for AI-native analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patent Analytics Services Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Search Services, Monitoring Services, Valuation Services, Litigation Support Technology: Artificial Intelligence, Machine Learning, Natural Language Processing, Data Mining End User: Law Firms, Corporations, Research Institutions, Government Agencies Delivery Model: On-Premises, Cloud-Based, Hybrid, Subscription-Based |
| Companies Covered | Clarivate, LexisNexis, Questel, PatSnap, Innography, IFI Claims Patent Services, Anaqua, Derwent Innovation, Gridlogics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patent Analytics Services Market Strategic Shifts
Natural language processing architectures trained on patent-specific syntax are displacing Boolean search as the primary retrieval mechanism, compressing prior-art identification cycles and reshaping analyst staffing models.
Transformer-based claim decomposition is expanding into pharmaceutical freedom-to-operate workflows, where Roche and Novartis deployment teams now generate automated infringement risk matrices for antibody sequences. The technology compresses biologics patent landscaping from six-week engagements to 72-hour deliverables, enabling real-time portfolio adjustments during clinical trial enrollment.
The EU AI Act's transparency requirements for high-risk AI systems are mandating algorithmic audit trails for automated invalidity assessments used in EPO opposition proceedings. German analytics providers now embed explainability layers into citation network algorithms to satisfy Munich-based patent attorney procurement standards. This regulatory overlay is segmenting vendor capabilities between auditable enterprise platforms and opaque productivity tools.
Corporate legal departments are consolidating spend around integrated intelligence suites that merge patent analytics with regulatory monitoring and litigation docket tracking. Pharmaceutical buyers now reject standalone search subscriptions in favor of unified dashboards spanning FDA Orange Book updates, PTAB petition filings, and NMPA approval timelines. This bundling preference is visible most acutely among US-based biotech firms with parallel EU and China filing strategies.
Patent Analytics Services Market Segmentation
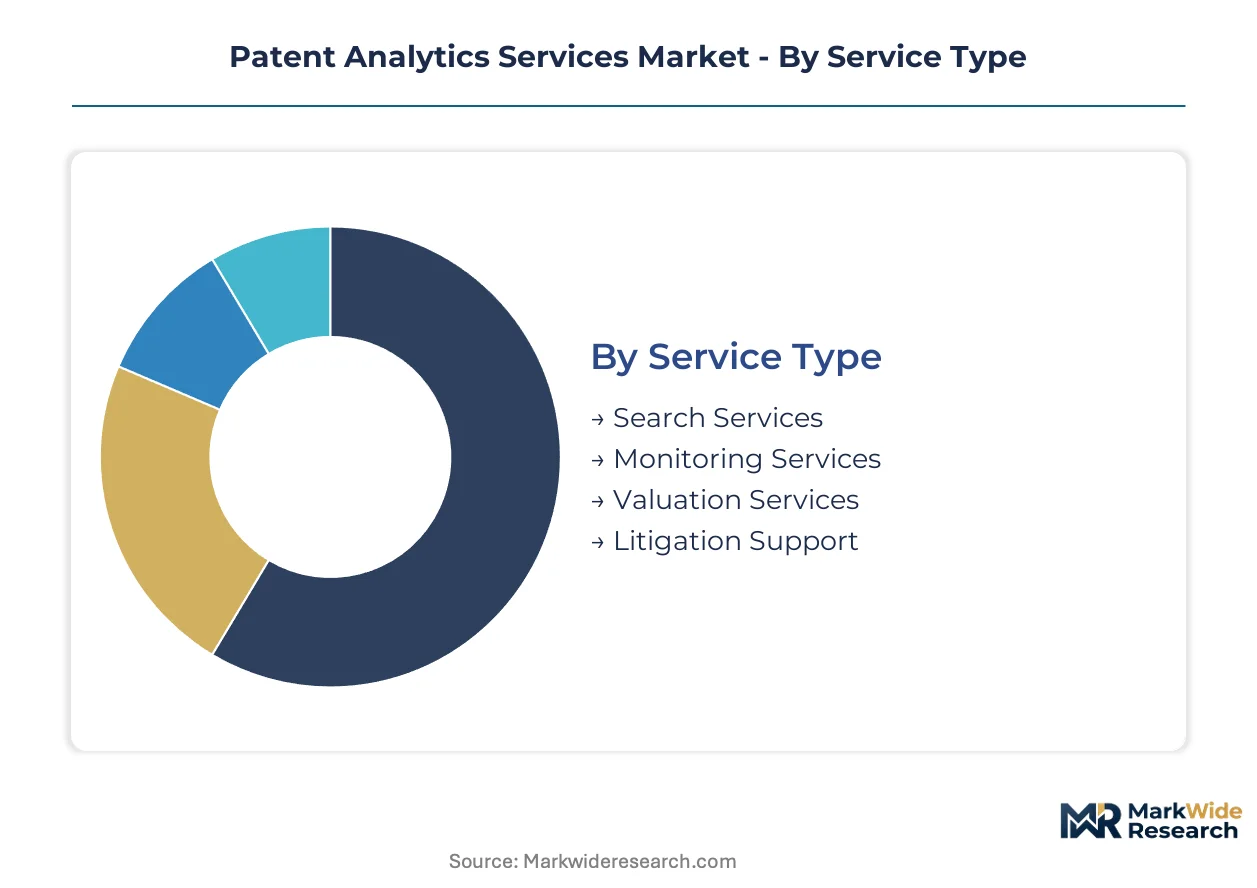
Patent analytics buyers segment sharply by technical sophistication and procurement authority. Law firms prioritize prosecution workflow integration while corporate R&D groups demand predictive portfolio intelligence.
Service Type:
Buyers differentiate primarily by engagement duration and analytical depth required for decision-making.
- Search Services:Systematic prior-art retrieval using Boolean and semantic query architectures. Pharmaceutical companies in Germany deploy these for EPO opposition preparation, compressing manual examiner review cycles.
- Monitoring Services:Continuous surveillance of competitor filings, claim amendments, and legal status changes. US biotech firms rely on automated alerts to track biosimilar entrants mapping exclusivity cliffs.
- Valuation Services:Patent-backed due diligence for M&A and licensing transactions.
- Litigation Support:Claim-charting and infringement analysis for district court and ITC proceedings.
Search Services leads volumes today; Valuation Services is gaining share fastest.
Technology:
Technology selection tracks data infrastructure maturity and in-house AI capabilities.
- Artificial Intelligence:Transformer architectures trained on prosecution histories automate claim construction analysis. Japanese METI-funded consortia deploy these for semiconductor prior-art mapping.
- Natural Language Processing:Patent-specific syntax parsing enables semantic claim decomposition. Roche deployment teams generate antibody sequence risk matrices in 72-hour cycles.
- Machine Learning:Citation network algorithms for technology landscape clustering.
- Data Mining:Structured extraction from USPTO PAIR and EPO registers.
Natural Language Processing dominates enterprise procurement; Artificial Intelligence shows steepest expansion trajectory.
End User:
End-user segmentation reflects organizational patent asset intensity and litigation exposure.
- Law Firms:Full-service practices and boutiques handling EPO oppositions and USPTO PTAB proceedings. Munich-based attorneys specify ISO 9001-certified providers for Fortune 500 clients.
- Corporations:Technology and pharmaceutical companies with parallel filing strategies across US, EU, and China. These buyers reject standalone tools for unified regulatory intelligence dashboards.
- Research Institutions:Universities and national labs commercializing federally funded inventions.
- Government Agencies:Patent offices and competition authorities conducting landscape studies.
Corporations lead volumes today; Research Institutions are climbing the fastest.
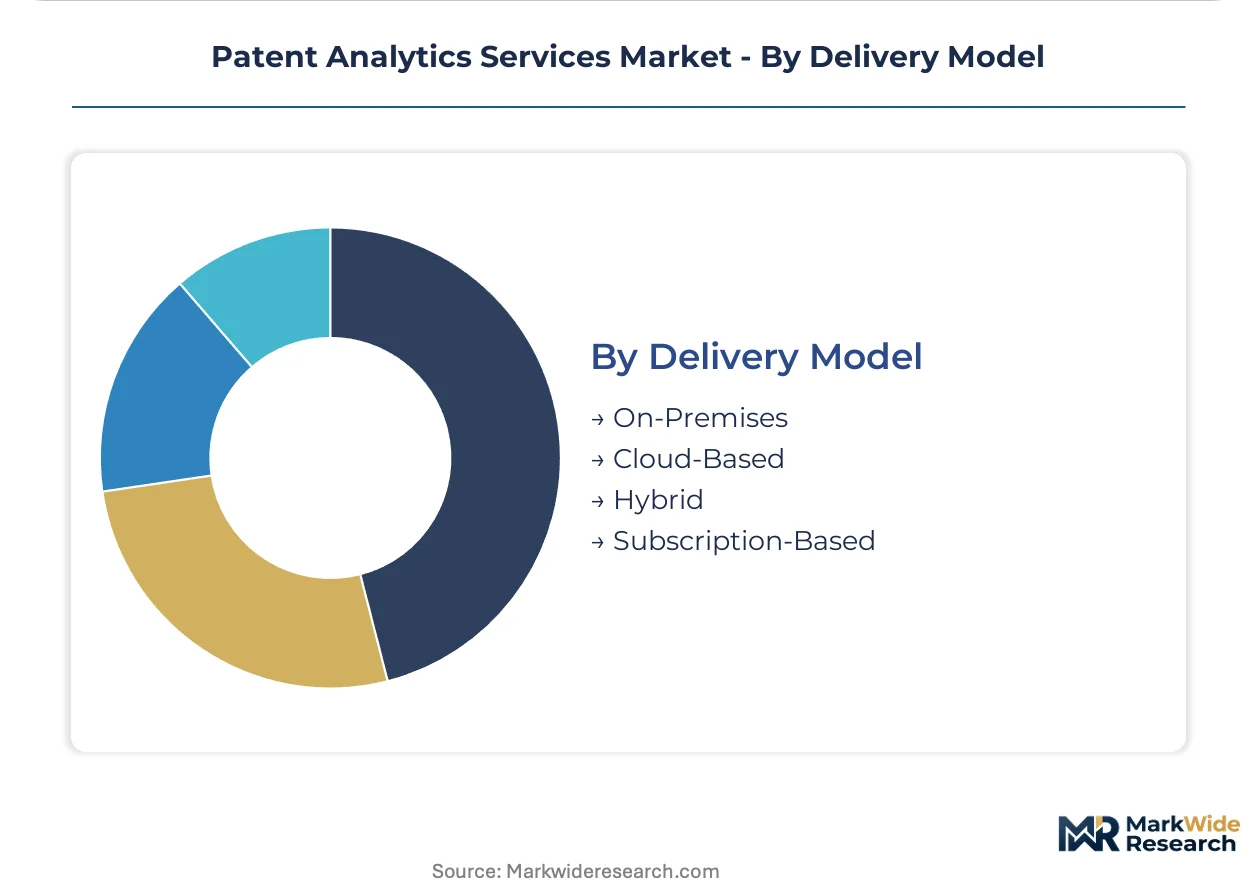
Delivery Model:
Delivery architecture hinges on data residency mandates and legacy system constraints.
- Cloud-Based:API-first platforms with elastic compute for large-scale citation analysis. New deployments concentrate here despite Germany's BSI certification requirements forcing redundant infrastructure.
- Hybrid:Sensitive prosecution histories remain on-premises while search indexes reside in cloud. China's data localization rules fragment architectures for multinational filers.
- On-Premises:Air-gapped installations for defense contractors and national security-sensitive R&D.
- Subscription-Based:Seat-license models for corporate legal departments with predictable search volumes.
Cloud-Based leads volumes today; Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates European patent analytics procurement around Munich's EPO headquarters, while the United States drives North American demand through PTAB litigation volumes and FDA regulatory intelligence needs.
United States
USPTO PTAB proceedings and biosimilar litigation generate sustained demand for claim-charting automation. The FDA's Orange Book patent linkage requirements compel pharmaceutical firms to integrate regulatory monitoring with invalidity search workflows. Boston and San Francisco biotech clusters deploy real-time portfolio dashboards during clinical trial enrollment.
Germany
EPO opposition filings and Unitary Patent System consolidation anchor European analytics procurement. BSI certification requirements for data residency fragment cloud architectures, forcing redundant infrastructure investments. Munich-based patent attorneys specify ISO 9001-certified providers for Fortune 500 prosecution engagements.
China
NMPA patent linkage regulations tie generic approvals to originator exclusivity status, requiring litigation-risk mapping for biosimilar entrants. MIIT semiconductor incentives under the dual carbon goals generate first-time filing volumes lacking local analytics capacity. Shanghai and Beijing R&D clusters import automated claim construction tools from established vendors.
Japan
METI intellectual property strategy reviews and semiconductor prior-art mapping programs fund domestic AI-native platform development. JIS standards compliance creates procurement friction for foreign cloud-based providers. Tokyo and Osaka corporate legal departments consolidate spend around unified regulatory intelligence suites.
India
PLI scheme incentives for pharmaceuticals and semiconductors generate patent filing volumes without corresponding local analytics infrastructure. CDSCO regulatory pathways for complex generics intensify competitive intelligence requirements. Bangalore and Hyderabad manufacturing clusters rely on imported search services for freedom-to-operate studies.
Patent Analytics Services Market Competitive Environment
Top-tier vendors anchor premium AI-native platforms, while mid-tier providers compete on geographic coverage and specialized regulatory overlays. The market stratifies between integrated intelligence suites and standalone search tools. Three archetypes dominate: heritage data aggregators with citation network depth, API-first entrants compressing claim-charting timelines, and regional specialists navigating jurisdictional compliance. Incumbents defend positioning through proprietary prosecution history training data, while challengers exploit generative AI productivity gains.
Within the heritage aggregator tier, Clarivate and LexisNexis exemplify vendors leveraging Derwent Innovation lineage and Web of Science integration to sustain enterprise pricing power. Questel occupies a position as the pan-European filing analytics specialist dominating EPO opposition workflows. These three represent the capability gap between premium platforms and commoditized bibliographic tools.
| Leading Market Players |
|---|
| Clarivate |
| LexisNexis |
| Questel |
| PatSnap |
| Innography |
| IFI Claims Patent Services |
| Anaqua |
| Derwent Innovation |
| Gridlogics |
| Others |
Value Chain & Pricing Dynamics
Corporate legal department consolidation around unified intelligence dashboards is compressing vendor margins and forcing platform providers to absorb cloud infrastructure redundancy costs for BSI-certified German deployments.
Pricing Analysis
Capacity additions in India's analytics services sector are reshaping price floors for mid-tier search and monitoring engagements. The dominant pricing model is tiered subscription SaaS, with premium tiers anchored by ISO 9001 certification and proprietary prosecution history databases. Price differentiation rests on certification grade and geographic data residency compliance. Pricing pressure stems from open-source EPO and USPTO tools capping elasticity at the SME tier. Fortune 500 legal departments show lowest price sensitivity; research institutions and emerging market filers exhibit highest.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from pharmaceutical and semiconductor R&D clusters. Geographic supply concentrates in the United States, Germany, and China, with specialized annotation labor pools in India and Southeast Asia. Raw material dependencies include proprietary prosecution history datasets, cloud compute infrastructure, and patent examiner annotation services. Supply chain risk centers on single-source vulnerability for USPTO PAIR access tiers and national paywall restrictions. Distribution runs through API-first platforms and legacy system integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patent analytics services market functions as a stable compounder, with regulatory complexity across FDA, EPO, and NMPA jurisdictions ensuring persistent demand for specialized intelligence workflows.
For Market Incumbents: Cement positioning by acquiring proprietary prosecution history training data locked behind USPTO PAIR tiers, and by embedding explainability layers that satisfy EU AI Act transparency mandates for EPO opposition proceedings. API-first entrants exploiting generative AI productivity gains represent the primary threat; defensive investment in ISO 9001 certification timelines and Munich-based attorney procurement relationships provides channel control.
For New Entrants and Emerging Players: Boutique law firms specializing in EPO oppositions present the most penetrable channel partner type for automated claim-charting tools. White-space targets include India's PLI scheme beneficiaries lacking local analytics capacity, and climate technology taxonomies requiring carbon-accounting-linked IP strategy. A regulatory intelligence overlay bundling patent search with FDA Orange Book and NMPA approval tracking offers differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native platforms possessing annotated prosecution history datasets and established EPO opposition workflows. Long-term viability favors vendors integrating regulatory intelligence across US, EU, and China filing strategies. The acquisition target archetype is regional specialists with jurisdictional compliance expertise and Fortune 500 legal department procurement relationships. Watch for generative AI transparency mandates from the EU AI Act as an inflection indicator for explainability-layer investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Prosecution History Database Acquisition | Secures proprietary training data for transformer-based claim construction models beyond USPTO PAIR access tiers. |
| EU AI Act Explainability Layer Development | Embeds algorithmic audit trails into citation network algorithms to satisfy Munich patent attorney procurement standards. |
| Regulatory Intelligence Suite Integration | Merges patent analytics with FDA Orange Book updates and NMPA approval timelines for unified pharmaceutical dashboards. |
| India PLI Scheme Market Entry | Captures first-time patent filing volumes from semiconductor and pharmaceutical manufacturing incentives lacking local analytics capacity. |
| Climate Technology Taxonomy Development | Cross-references EU Green Deal patent classifications with emission disclosures for carbon-accounting-linked IP strategy services. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with patent analytics platform executives, corporate IP counsel at pharmaceutical and semiconductor firms, Munich-based EPO opposition attorneys, and private equity due diligence specialists. Secondary validation draws from USPTO PTAB filing databases, EPO opposition registers, FDA Orange Book updates, NMPA patent linkage regulations, and SEC filings from publicly traded analytics providers. Bottom-up service-type demand modeling and top-down market sizing triangulate volume and value estimates.
Granularity-level modeling disaggregates revenue across search services, monitoring services, valuation services, and litigation support, with technology segmentation spanning artificial intelligence, natural language processing, machine learning, and data mining. End-user segmentation distinguishes law firms, corporations, research institutions, and government agencies. Delivery model architecture separates cloud-based, hybrid, and on-premises deployments. CAGRs derive from fitted growth curves benchmarked against historical patent filing volumes, regulatory expansion timelines, and AI adoption S-curves across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to generative AI regulatory mandates, open-source tool substitution rates, and data localization rule fragmentation. Forecasts reflect documented assumptions around USPTO patent quality initiative timelines, EU Unitary Patent System adoption velocity, and NMPA patent linkage enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Geospatial Imagery Analytics Market
Analytics
Online Analytical Processing Market
Analytics
UK Geospatial Analytics Market
Analytics
Global Web Analytics Software Market
Analytics
AI Performance Marketing Market
Analytics
Load (ETL) Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Statistical Analytics Market
Analytics
Attribution Software Market
Analytics
Big Data in Automotive Market
Analytics
Global AI Video Analytics Market
Analytics
Product Analytics Market
Analytics
Contact Center Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Mobile App Attribution Tool Market
Analytics
IoT Analytics Market