
 North America Location Analytics Market | 2026-2036
North America Location Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Location Analytics Market Outlook
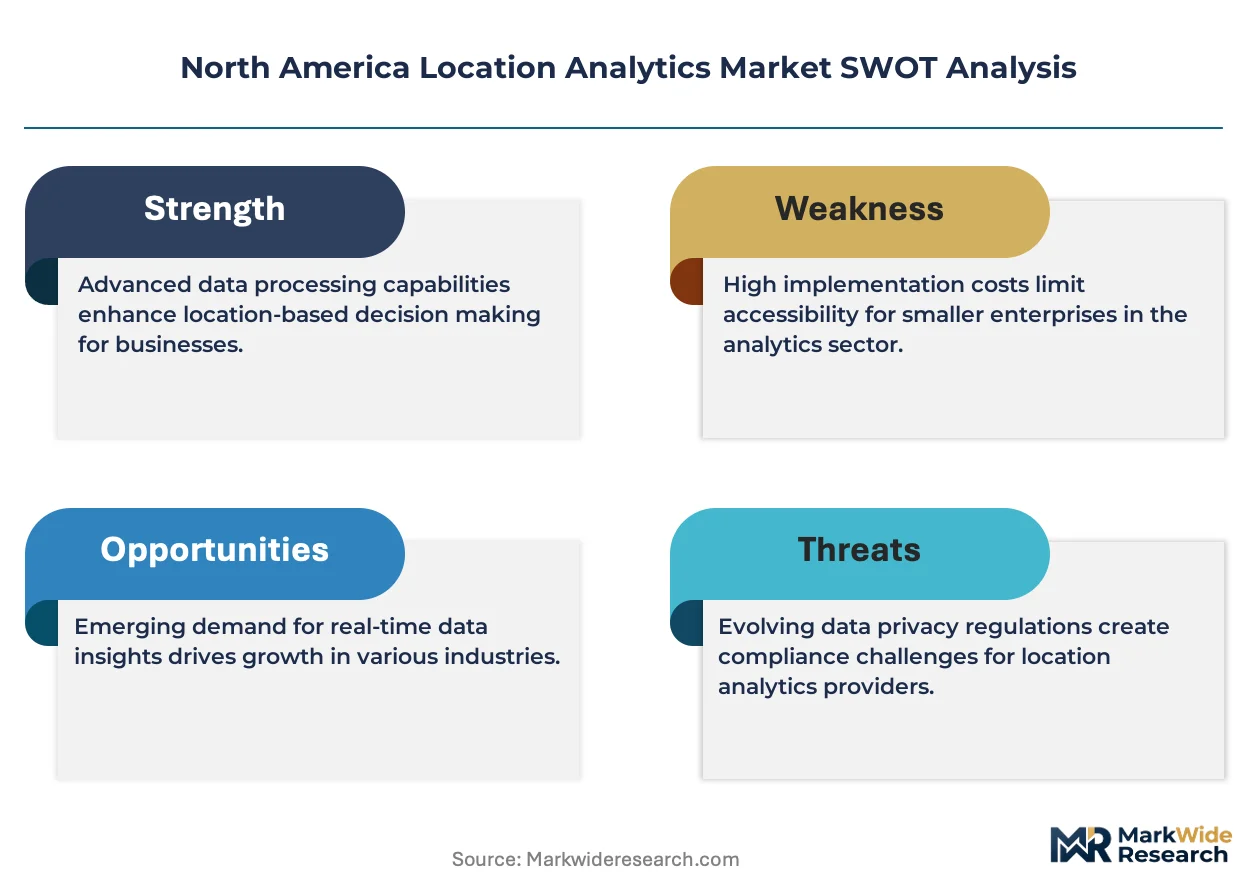
The North America location analytics market is pivoting on a widening split between premium geospatial platforms with real-time edge processing and commodity mapping dashboards sold through channel partners. Esri Inc. dominates the premium tier with deep vertical integration into government and utility GIS workflows. Google LLC competes through cloud-native location APIs that anchor developer ecosystems across retail and logistics. Microsoft Corporation extends its position by embedding spatial analytics within Azure and enterprise productivity stacks.
Location analytics encompasses the extraction, visualization, and predictive modeling of georeferenced data to support operational and strategic decisions, typically processing coordinate streams, polygon boundaries, and temporal movement patterns at sub-meter precision for fleet routing, site selection, and risk assessment. Software solutions lead revenue contribution due to recurring license structures and embedded AI capabilities, while cloud solutions represent the fastest expansion vector as public cloud deployments reduce infrastructure barriers for mid-market adopters. Services retain margin concentration in complex implementations for healthcare network optimization and transportation corridor planning where specialized consulting commands pricing power.
The FCC governs geolocation privacy under wireless carrier regulations, while state frameworks including California's Consumer Privacy Act shape how location data may be collected, retained, and monetized across commercial applications. HIPAA constrains healthcare deployments by mandating de-identification protocols for patient movement analytics, creating compliance costs that favor established vendors with certified data governance architectures. Stakeholders must monitor evolving state patchworks and federal preemption debates to determine whether centralized compliance investment or jurisdiction-specific product variants offer superior risk-adjusted returns.
Market Dynamics
The North America location analytics market pivots on real-time edge processing capabilities displacing batch-mode geospatial workflows, compressing decision latency from hours to seconds for fleet operators and emergency response networks.
Growth Catalysts
- California Consumer Privacy Act (CCPA) amendments:Stricter geolocation consent requirements are forcing enterprises to upgrade data governance stacks, creating replacement demand for certified analytics platforms.
- Smart city infrastructure:Texas and New York metro corridors are deploying sensor-dense urban operating systems that feed continuous coordinate streams into municipal analytics layers.
- Computer vision fusion:Retail chains are layering visual footfall sensors atop Wi-Fi positioning to correlate physical movement with demographic inference at sub-aisle granularity.
Market Restraints
- Cloud egress cost volatility:Mid-market adopters face unpredictable data transfer charges when streaming high-frequency GPS telemetry across multi-cloud architectures.
- FCC geolocation privacy enforcement:Wireless carrier consent frameworks create compliance friction for cross-carrier mobility datasets, fragmenting addressable data pools.
- Vector database specialization:Spatial query acceleration requires niche engineering talent concentrated in San Francisco and Seattle hiring markets, inflating implementation timelines.
Strategic Opportunities
- Canadian healthcare networks:Ontario and Quebec hospital systems remain underpenetrated for patient flow optimization, offering first-mover positioning before provincial procurement standardization.
- IRA clean energy corridors:Federal tax credits for grid modernization are mandating geospatial asset tracking across renewable generation and transmission investments.
- 5G network slicing:Telcos are offering guaranteed-latency location services as a premium API tier, enabling new revenue-sharing models with logistics platforms.
Industry Challenges
- HIPAA de-identification engineering:Healthcare deployments require specialized protocols for scrubbing temporal-spatial patient trails, extending implementation cycles by 4-6 months.
- Legacy GIS integration:Government agencies maintain decades-old Esri ArcMap workflows that resist API-native migration without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Location Analytics Market |
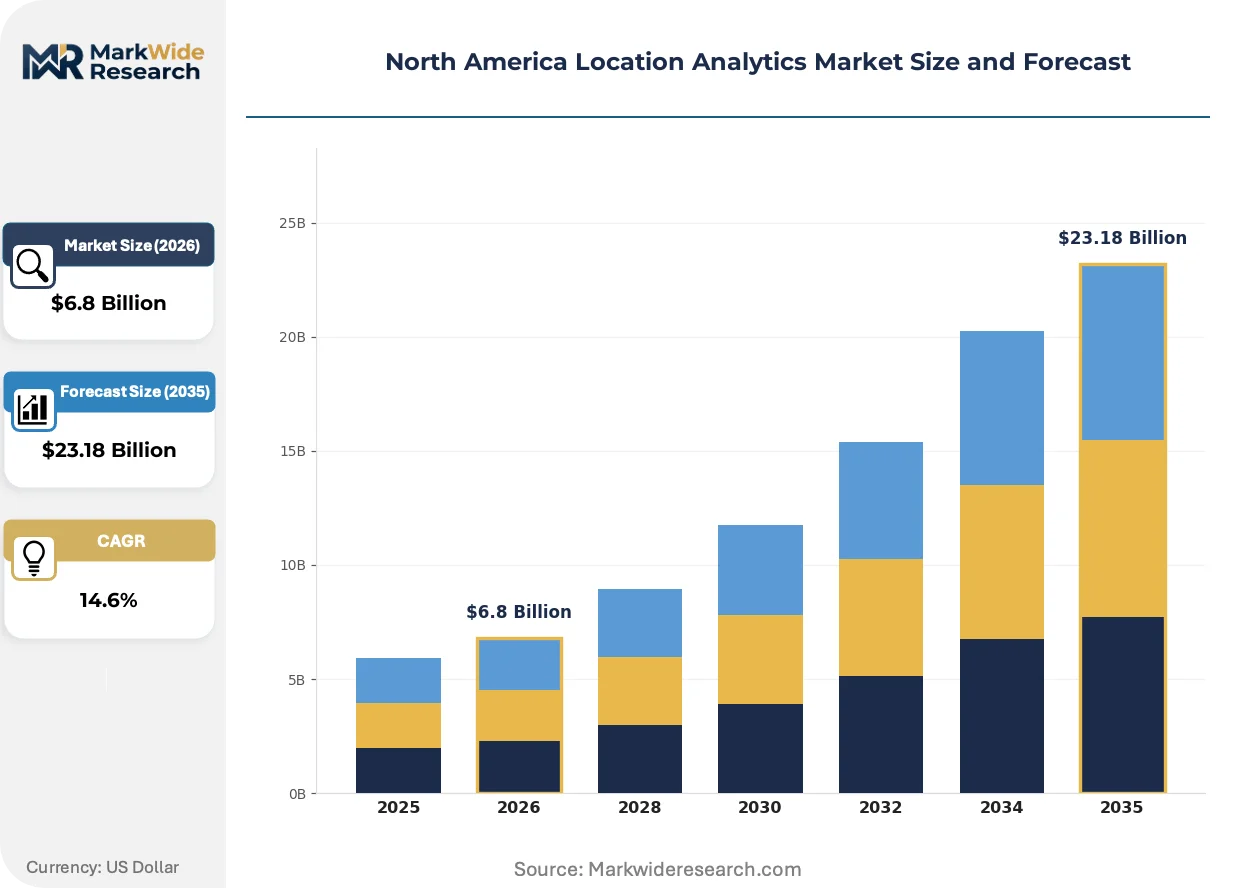
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Cloud Solutions, On-Premise Solutions End User: Retail, Healthcare, Transportation, Manufacturing Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Application: Traffic Management, Asset Tracking, Market Analysis, Risk Management |
| Companies Covered | Esri Inc., Google LLC, Microsoft Corporation, IBM Corporation, Cisco Systems Inc., HERE Technologies, TomTom N.V., Hexagon AB, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Location Analytics Market Strategic Shifts
Edge-native spatial processing is compressing the latency window for location intelligence, enabling predictive routing and risk scoring that batch systems cannot match. This shift reconfigures vendor competitive position around real-time architecture rather than historical data depth.
Digital twin platforms are absorbing building information modeling (BIM) and IoT sensor feeds into unified spatial operating environments. Facility managers in Texas and California commercial real estate portfolios are deploying these systems for occupancy-driven HVAC and security orchestration. The technology is absorbing capital previously allocated to standalone energy management and access control systems, consolidating vendor relationships.
FCC geolocation privacy rulemakings are tightening consent requirements for commercial use of carrier-derived location signals. Wireless providers must now obtain explicit opt-in for secondary data monetization, shrinking the supply of anonymized mobility datasets available to retail and advertising platforms. California and New York state attorneys general are layering additional enforcement mechanisms, pushing vendors toward first-party sensor deployments.
Subscription pricing for geospatial APIs is displacing perpetual license models across mid-market logistics and field service segments. Buyers in the Great Lakes manufacturing corridor are consolidating vendor relationships around usage-based contracts that align costs with seasonal shipment volatility. This procurement evolution favors cloud-native platforms with granular metering over traditional enterprise GIS deployments requiring upfront capital commitment.
North America Location Analytics Market Segmentation
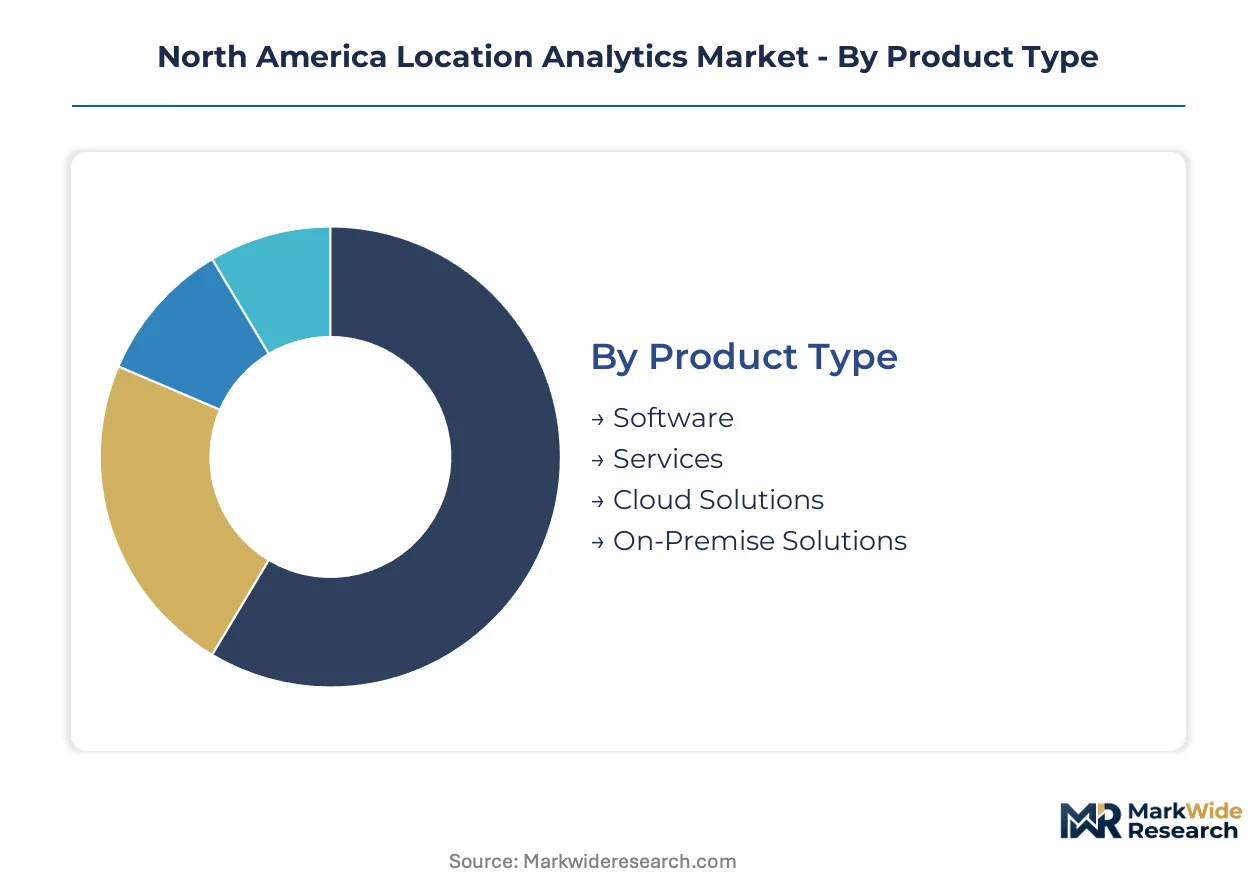
Location analytics buyers in North America face a configuration matrix spanning embedded versus standalone deployments, cloud-native versus legacy infrastructure, and sector-specific compliance requirements. Segmentation choices directly determine integration costs, data governance burdens, and the velocity of insight generation across operational workflows.
Product Type:
Software platforms anchor recurring revenue through embedded AI capabilities, while services and cloud architectures diverge sharply in margin structure and customer acquisition economics.
- Software:Recurring license structures dominate revenue contribution, with embedded machine learning modules for predictive routing and site selection commanding premium positioning. Texas and California logistics corridors drive concentration, as fleet operators demand sub-meter precision for last-mile optimization under tightening delivery windows.
- Services:Complex implementations for healthcare network optimization and transportation corridor planning retain margin concentration, where specialized consulting around HIPAA de-identification protocols extends implementation cycles but sustains pricing power. Ontario hospital systems represent underpenetrated demand ahead of provincial procurement standardization.
- Cloud Solutions:Public cloud deployments reduce infrastructure barriers for mid-market adopters across the Great Lakes manufacturing belt.
- On-Premise Solutions:Government agencies and regulated utilities favor captive infrastructure for sensitive geospatial asset data.
Software leads volumes today; cloud solutions are gaining share fastest.
End User:
Sector-specific compliance architectures and sensor density requirements create divergent procurement patterns across verticals.
- Retail:Wi-Fi positioning layered with computer vision footfall sensors enables sub-aisle demographic correlation. California and New York metro chains face CCPA-driven governance upgrades that displace legacy dashboard vendors.
- Healthcare:Patient flow optimization requires temporal-spatial de-identification engineering that extends sales cycles but creates vendor stickiness through certified data architectures.
- Transportation:Real-time edge processing compresses fleet routing decisions from batch-mode hours to seconds.
- Manufacturing:Asset tracking across renewable generation investments accelerates under IRA tax credit mandates for grid modernization.
Retail commands the largest addressable spend; healthcare exhibits the steepest expansion trajectory.
Deployment:
Infrastructure placement determines latency boundaries, egress cost exposure, and regulatory jurisdiction for data residency.
- Public Cloud:Usage-based contracts align costs with seasonal shipment volatility, consolidating vendor relationships around granular metering. Mid-market logistics buyers in the Great Lakes corridor favor this procurement evolution over upfront capital commitment.
- Private Cloud:Municipal analytics layers in Texas and New York smart city deployments require sovereign infrastructure for continuous sensor feeds.
- Hybrid Cloud:Edge-native spatial processing with cloud-based model training splits workloads across latency-sensitive and compute-intensive functions.
- On-Premise:Legacy Esri ArcMap workflows in federal agencies resist API-native migration without costly middleware development.
Public cloud dominates new procurement; hybrid architectures are climbing the fastest.
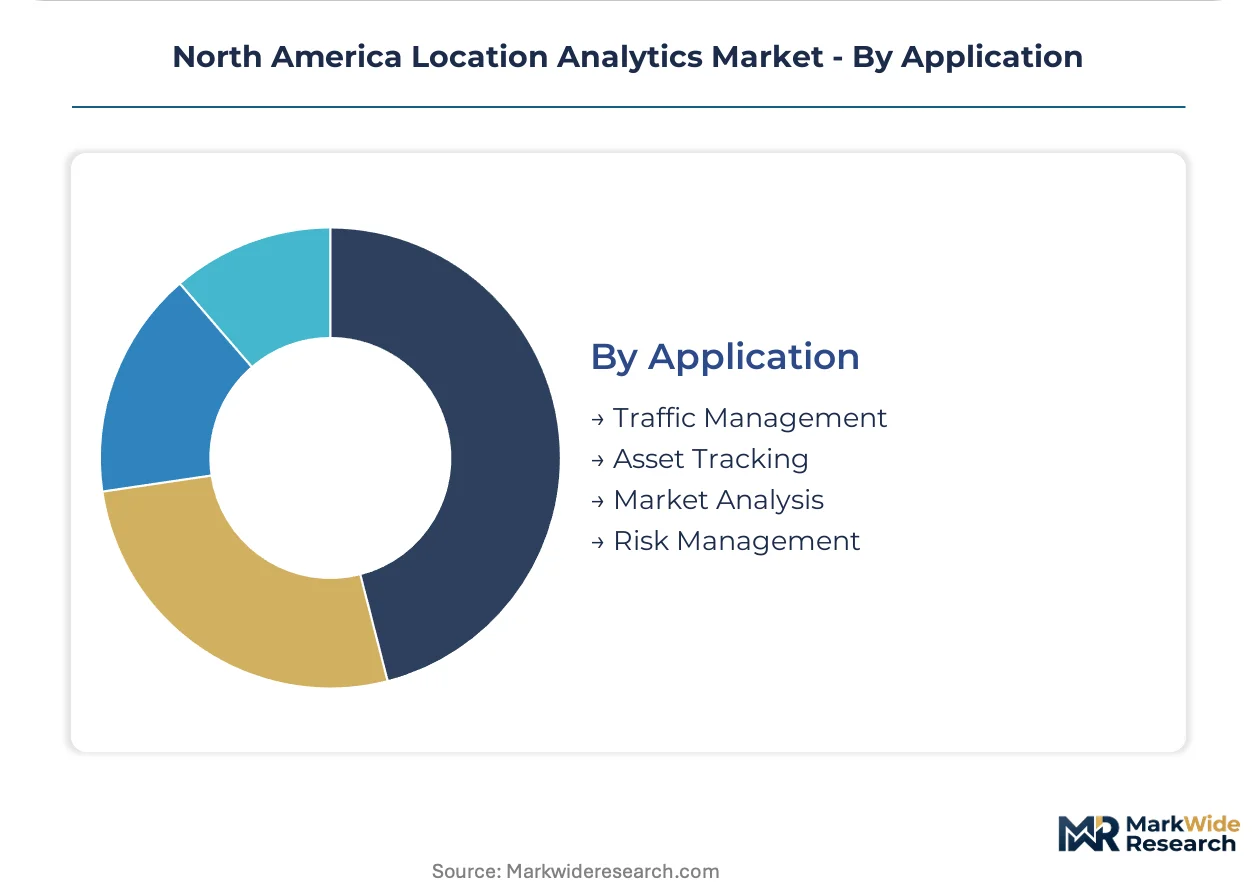
Application:
Use case maturity varies from operational optimization to strategic risk quantification, with divergent data freshness requirements.
- Traffic Management:Municipal operating systems in Texas and California metro corridors ingest continuous coordinate streams for congestion prediction and signal optimization.
- Asset Tracking:Geospatial monitoring of renewable generation and transmission investments is mandated under federal grid modernization incentives.
- Market Analysis:Retail chains correlate physical movement patterns with demographic inference for network expansion decisions.
- Risk Management:Insurance and logistics platforms score geographic exposure using predictive spatial models.
Asset tracking leads current deployment value; traffic management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spatial data engineering talent clusters in California's Bay Area and Seattle's tech corridor anchor North American innovation capacity, while regulatory divergence between federal and state frameworks shapes vendor compliance architecture across sub-regions.
United States
Texas and California metro corridors concentrate logistics density and smart city infrastructure investment, driving demand for real-time edge processing platforms. FCC geolocation privacy enforcement under wireless carrier regulations fragments cross-carrier mobility datasets. Austin and Dallas-Fort Worth anchor municipal analytics deployments for traffic signal optimization and emergency response networks.
Canada
Ontario and Quebec hospital systems present underpenetrated demand for patient flow optimization ahead of provincial procurement standardization. Health Canada and provincial privacy commissioners enforce PIPEDA-aligned consent frameworks for commercial location data use. Toronto's financial district and Vancouver's port logistics cluster drive enterprise adoption of cloud-native geospatial APIs.
Mexico
Manufacturing corridors in Nuevo León and the Bajío Region accelerate asset tracking adoption for automotive and electronics supply chains serving US markets. Federal telecommunications reform under IFT jurisdiction shapes carrier-derived location data availability. Mexico City Metro anchors municipal traffic management investments integrating sensor-dense urban operating systems.
North America Location Analytics Market Competitive Environment
Top-tier vendors anchor the premium geospatial platform tier, while mid-market cloud-native providers compete through developer ecosystem penetration and usage-based pricing models. The vendor base stratifies across three functional archetypes: legacy GIS incumbents with deep government vertical integration, hyperscale cloud platforms embedding spatial analytics within productivity stacks, and specialized mapping API providers serving logistics and retail segments. Dominant competitive moves include strategic partnerships between telcos and analytics platforms for 5G network-sliced location services, and portfolio diversification into digital twin platforms absorbing BIM and IoT sensor feeds.
Within the premium enterprise tier, Esri Inc. and Microsoft Corporation exemplify divergent architectural approaches to spatial data infrastructure. Esri Inc. occupies a position representing deep vertical integration into government and utility GIS workflows resistant to API-native migration. Microsoft Corporation anchors cloud-native embedding of spatial analytics within Azure and enterprise productivity stacks. Google LLC sits within the developer-centric API tier, competing through location services that anchor retail and logistics application ecosystems.
| Leading Market Players |
|---|
| Esri Inc. |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| Cisco Systems Inc. |
| HERE Technologies |
| TomTom N.V. |
| Hexagon AB |
| SAP SE |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up GIS specialists concentrate ownership of mid-market spatial analytics platforms across Texas and California, compressing pricing discipline through portfolio-standardized subscription tiers while channeling implementation services through captive consulting arms.
Pricing Analysis
Bundled platform-and-service contracts dominate enterprise procurement, while unbundled API access wins mid-market logistics buyers. Three-tier pricing structure across premium, standard, and economy levels separates Esri's government-integrated suites from cloud-native alternatives and open-source tooling. Price differentiation hinges on real-time processing latency guarantees and HIPAA certification status. Pricing pressure stems from cloud egress cost volatility eroding margins on high-frequency telemetry streams. Mid-market field service operators exhibit acute price sensitivity; federal agencies demonstrate lowest sensitivity due to procurement rigidity.
Supply Chain Analysis
Reverse-logistics flows for spatial hardware—GPS receivers, edge servers, and sensor arrays—remain underdeveloped, with refurbishment concentrated in Mexico's Tijuana electronics corridor and Texas border assembly zones. Core component supply draws from Taiwan for semiconductors, China for lithium-ion cells powering mobile field units, and Germany for precision optics in surveying equipment. Single-source vulnerability concentrates in GPU accelerators for real-time inference. Distribution runs through hyperscaler marketplaces and specialized GIS value-added resellers serving government verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in healthcare and smart city verticals where real-time edge processing commands premium positioning against batch-mode alternatives.
For Market Incumbents: Deploy certification investment as the primary lever. Esri and Microsoft should deepen HIPAA-compliant architecture penetration to lock out cloud-native challengers in hospital network procurement. Consolidate channel control through exclusive partnerships with 5G carriers offering network-sliced location services. The threat of API-native platforms displacing legacy ArcMap workflows demands preemptive middleware development subsidies. For New Entrants and Emerging Players: Mid-market Canadian healthcare networks represent the most penetrable buyer archetype ahead of Ontario and Quebec provincial standardization. Ontario hospital systems currently lack certified patient flow optimization vendors. Target municipal analytics layers in secondary Texas metros—San Antonio, Houston—where smart city investment lags Dallas-Fort Worth. Lead with usage-based pricing aligned to seasonal occupancy volatility rather than perpetual licensing. For Investors and Strategic Acquirers: Valuations sit cheapest among edge-native spatial processing startups with demonstrated sub-second latency architectures but limited vertical certification. Long-term viability favors vendors with healthcare compliance moats over pure-play logistics API providers. Acquisition targets should demonstrate certified data governance stacks and recurring revenue concentration above project-based consulting. Monitor FCC geolocation privacy rulemakings for signals of carrier data supply contraction that would elevate first-party sensor platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Esri's ArcGIS Online embedding within Microsoft Teams accelerates government workflow adoption. |
| Strategic Partnership | 5G carrier alliances for network-sliced location services create guaranteed-latency API tiers. |
| Acquisition of Specialist Firm | Digital twin platform purchases absorb BIM and IoT sensor feed integration capabilities. |
| Geographic Expansion | Ontario and Quebec hospital systems offer first-mover positioning before procurement standardization. |
| Product Launch | Edge-native spatial processing modules compress decision latency from hours to seconds for fleet operators. |
Study Parameters
Multiple input streams — structured executive interviews, regulatory filing analysis, and cloud infrastructure spend disclosures — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged GIS platform engineers, municipal IT procurement officers, hospital biomedical informatics directors, and logistics fleet technology managers. Secondary validation drew from FCC rulemaking dockets, state attorney general enforcement actions, hyperscaler capex reports, and health system RFP databases. Bottom-up deployment counts across Texas, California, and New York metro corridors were cross-checked against top-down software licensing revenue estimates.
Historical growth trajectories were cross-referenced against panel input from platform vendors and systems integrators. The analytical framework modeled deployment mode, end-user vertical, and integration complexity across the projection horizon. CAGRs were derived from segment-specific adoption curves weighted by compliance burden and infrastructure investment cycles. Forecast inputs incorporated 5G network rollout timelines, IRA clean energy corridor geospatial mandates, and evolving state privacy enforcement patterns.
Underlying measurement precision varies by segment; software licensing and cloud subscription revenue carry tighter precision than professional services estimates. Forecasts reflect assumptions around carrier data availability, edge hardware cost curves, and healthcare procurement standardization schedules. Practitioners should monitor FCC geolocation consent rulemakings, California CCPA amendment enforcement, and Ontario hospital system RFP releases for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Predictive Analytics Market
Analytics
Analytics Sandbox Market
Analytics
Italy ICT Market
Analytics
Patent Analytics Services Market
Analytics
United States Geospatial Analytics Market
Analytics
Identity Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
APAC Operational Intelligence Market
Analytics
Patent Analytics Market
Analytics
Iraq ICT Market
Analytics
Europe Crowd Analytics Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
Europe Data Monetization Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Europe Operational Intelligence Market
Analytics
Brazil Geospatial Analytics Market