
 US Predictive Analytics Market | 2026-2036
US Predictive Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
US Predictive Analytics Market Insights
The capability gap between cloud-native platforms and legacy on-premises stacks is unwinding competitive dynamics across the sector. IBM Corporation leverages its Watson portfolio to anchor enterprise-grade deployments in regulated industries. Microsoft Corporation competes through Azure's integrated AI infrastructure, sustaining momentum among mid-market adopters. Amazon Web Services dominates cloud-based delivery, extending predictive compute capacity through specialized instance families.
Predictive analytics encompasses statistical modeling, machine learning algorithms, and data mining techniques applied to historical datasets to forecast future outcomes with quantified confidence intervals. Organizations deploy these systems to optimize inventory positioning, anticipate equipment failures, and segment customer churn risk with automated retraining pipelines. Machine learning deployments capture the fastest expansion as neural architectures displace traditional regression in fraud detection and predictive maintenance workloads. Cloud-based delivery models concentrate margin pools at the infrastructure layer, while on-premises installations retain traction among financial services firms with stringent data residency requirements.
The FDA scrutinizes predictive algorithms in clinical decision support, while the SEC mandates model risk management for investment advisory applications, and HIPAA governs patient data flows training healthcare forecasting tools. These overlapping compliance obligations elevate procurement standards and extend sales cycles for non-compliant vendors. Stakeholders must weigh interoperability investments against the accelerating pace of algorithmic audit requirements.
Market Dynamics
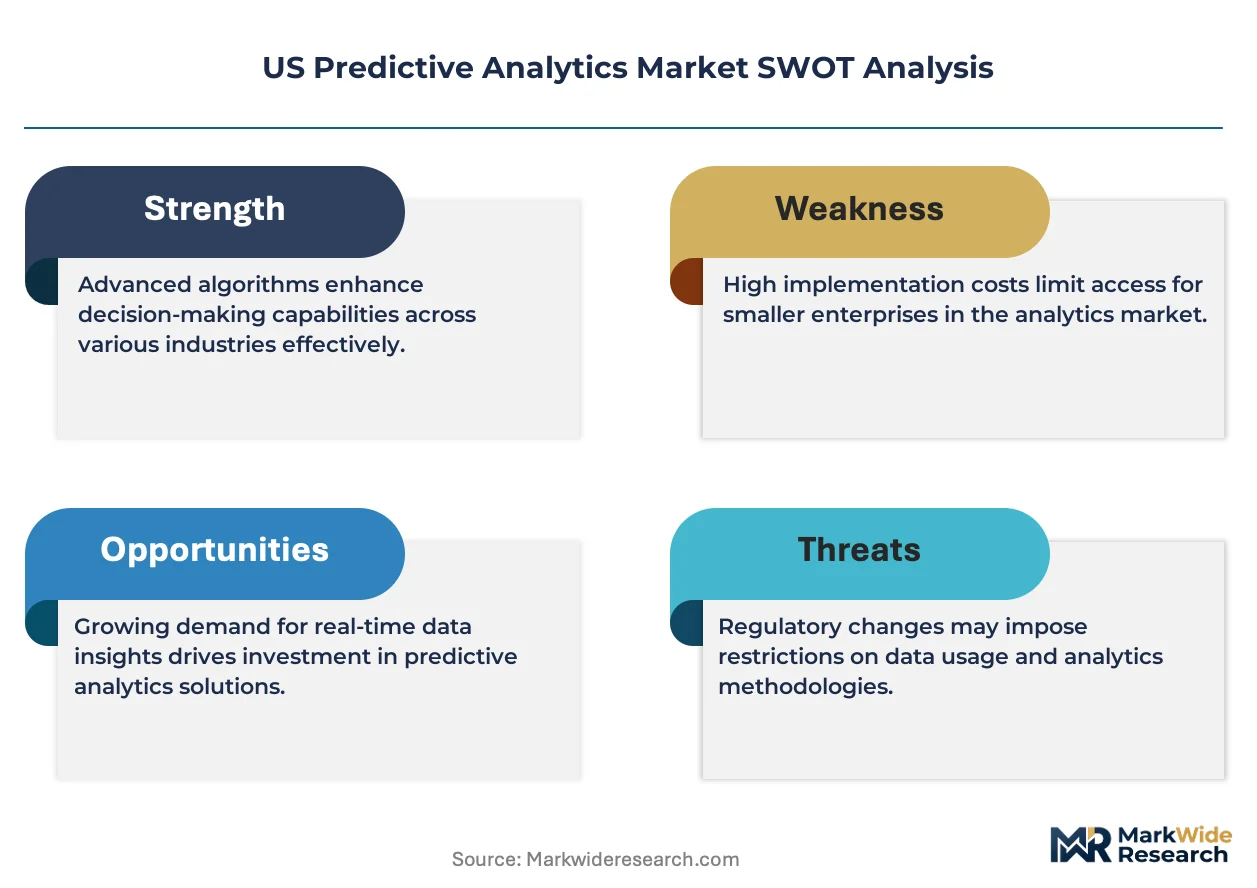
The FDA's evolving guidance on AI-enabled medical devices is compressing vendor compliance timelines while healthcare providers accelerate procurement of patient readmission forecasting tools, creating a bifurcation between compliant and non-compliant solution providers.
Growth Catalysts
- HIPAA-compliant cloud infrastructure:Healthcare systems in California and New York are migrating predictive workloads to FedRAMP-authorized platforms, eliminating on-premises data center overhead while maintaining patient privacy safeguards.
- Machine learning operations (MLOps) automation:Financial services firms deploy continuous model retraining pipelines for real-time fraud detection, reducing false-positive rates and operational review costs.
- Silicon Valley talent concentration:The San Francisco Bay Area's dense cluster of data engineering specialists enables rapid prototyping of neural architectures for predictive maintenance applications.
Market Restraints
- GPU compute cost volatility:Specialized training instances for large language model fine-tuning experience price swings tied to semiconductor foundry capacity constraints in Taiwan.
- Data residency requirements:New York State financial regulations mandate on-premises model hosting for certain investment advisory algorithms, blocking cloud-native deployment options.
- Model interpretability limitations:Deep learning architectures for clinical decision support lack transparent decision pathways, triggering FDA scrutiny and extended premarket review cycles.
Strategic Opportunities
- Texas healthcare expansion:Houston's medical center corridor shows underpenetrated demand for surgical outcome prediction tools among independent hospital networks.
- SEC model risk management mandates:Investment advisory firms face compliance deadlines requiring automated model monitoring, creating pull-through demand for governance platforms.
- Federated learning architectures:Convergence of edge computing and differential privacy techniques enables multi-institutional training without centralizing sensitive patient records.
Industry Challenges
- MLOps engineering scarcity:Production-grade pipeline construction requires rare combinations of software engineering and statistical validation expertise, elongating implementation timelines.
- Legacy EHR integration friction:Electronic health record systems from dominant vendors resist standardized API connectivity, forcing costly custom middleware development for data extraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Predictive Analytics Market |
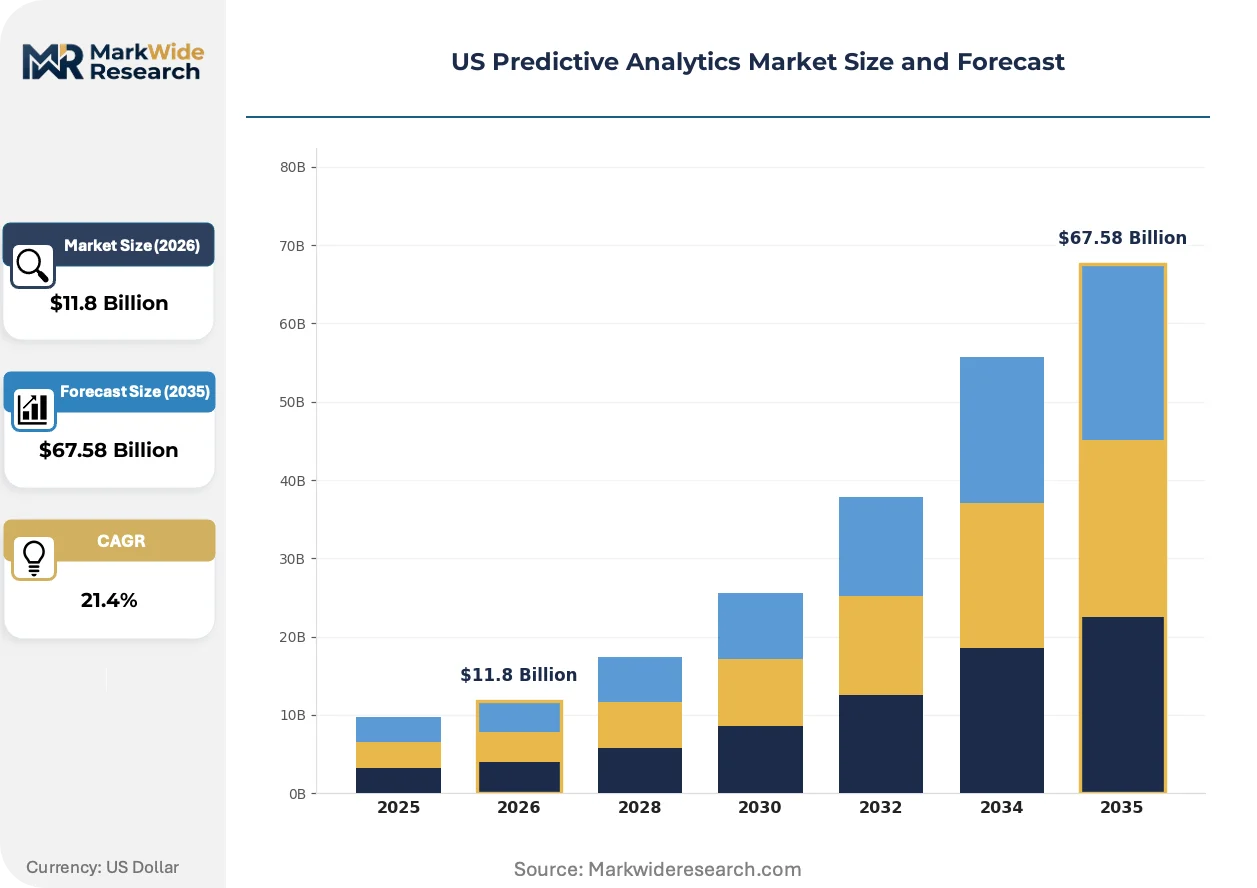
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $67.58 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Data Mining, Statistical Analysis, Natural Language Processing Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud End User: Retail, Healthcare, Manufacturing, Financial Services Application: Fraud Detection, Customer Relationship Management, Predictive Maintenance, Risk Management |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., Salesforce, Inc., Google LLC, Amazon Web Services, Alteryx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Predictive Analytics Market Trends and Innovations
Neural architecture search and automated feature engineering are compressing model development cycles, while regulatory pressure on algorithmic transparency forces vendors to rebuild core platforms around explainable methods rather than black-box accuracy optimization.
Transformer-based time series forecasting is fragmenting the traditional statistical modeling landscape. Healthcare systems in Massachusetts and Pennsylvania deploy these architectures for sepsis prediction and length-of-stay estimation. The technology is fragmenting vendor competitive positions, as incumbent platforms built on ARIMA and regression ensembles face replacement pressure from cloud-native challengers offering pre-trained foundation models.
The FDA's 2021 guidance on clinical decision support software continues tightening enforcement scope for predictive algorithms influencing diagnostic or treatment decisions. Device manufacturers must now submit prospective validation studies demonstrating real-world performance across diverse patient populations. High-risk cardiology and radiology applications face the steepest compliance burden, with several vendors withdrawing non-interpretable models from the 510(k) pathway entirely.
Buyers in the financial services vertical now require model cards and bias audit documentation as standard procurement deliverables, displacing traditional vendor scorecards focused on accuracy metrics alone. Chicago-based commodity trading firms and Boston asset managers lead this shift, embedding algorithmic governance requirements into RFP templates. The practice is spreading to healthcare procurement teams in Minnesota and North Carolina, who replicate financial sector diligence frameworks for clinical AI vendor selection.
US Predictive Analytics Market Segmentation
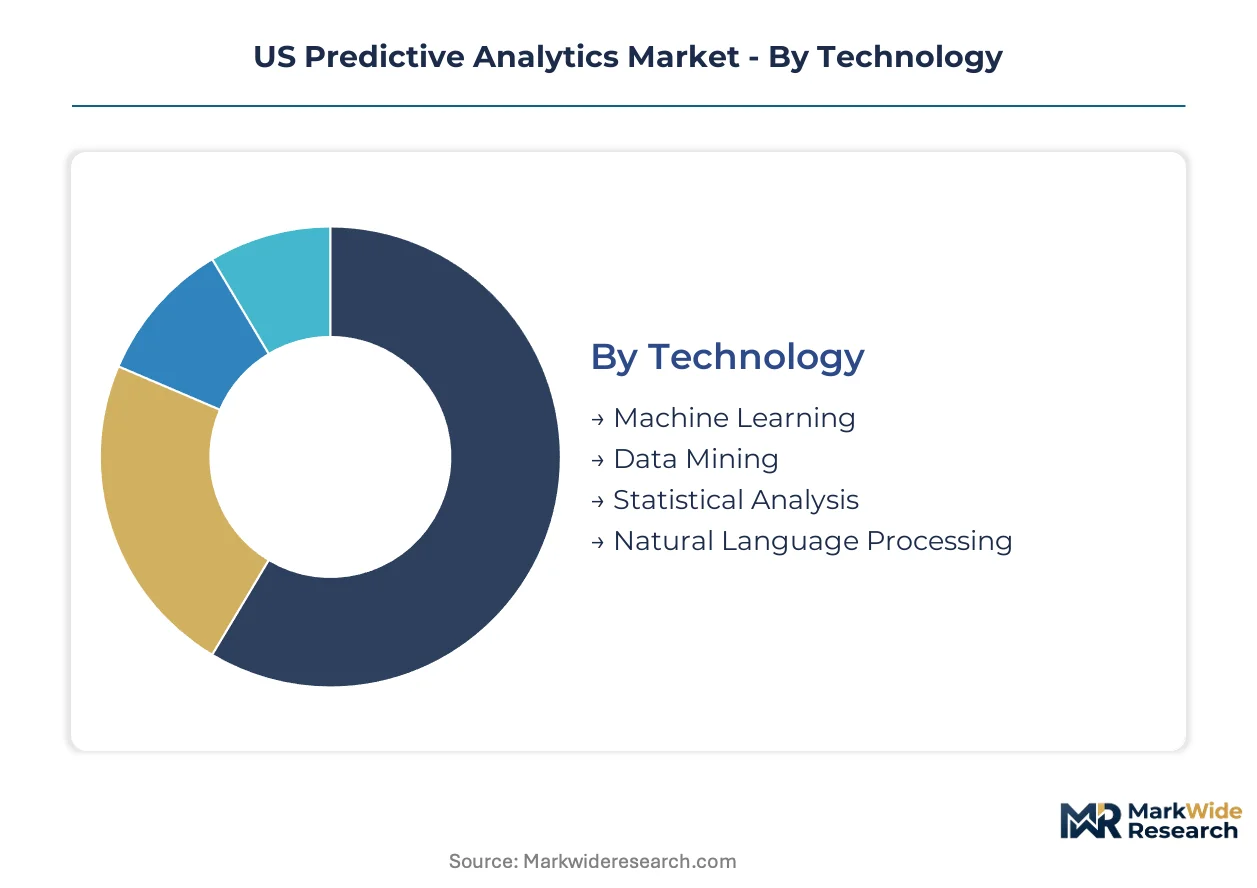
Technology choices determine infrastructure spend and talent requirements across the US predictive analytics landscape. Deployment models shape data residency compliance and operational flexibility for regulated industries. End-user verticals and application areas concentrate demand in distinct geographic clusters with specialized procurement criteria.
Technology:
Margin pools concentrate at the infrastructure layer for compute-intensive neural architectures, while licensing revenue flows to specialized statistical software vendors serving legacy enterprise accounts.
- Machine Learning:Neural architectures and ensemble methods process unstructured data for clinical decision support and algorithmic trading. Demand concentrates among Massachusetts healthcare systems deploying sepsis prediction models, constrained by FDA validation timelines for black-box algorithms.
- Data Mining:Pattern recognition algorithms extract actionable signals from transactional datasets in retail and financial services. Texas-based energy trading firms and California e-commerce platforms drive procurement of real-time basket analysis tools.
- Statistical Analysis:Traditional regression and time-series methods retain traction among insurance actuaries and epidemiological researchers requiring transparent, auditable methodologies.
- Natural Language Processing:Transformer-based models automate clinical documentation and regulatory filing extraction, with adoption concentrated among New York health systems and Washington DC government contractors.
Machine Learning holds installed capacity. Natural Language Processing is rotating up the share rankings.
Deployment:
Cloud-native delivery captures volume growth among mid-market adopters, while on-premises installations command premium pricing from financial services firms with strict data sovereignty requirements.
- Cloud-Based:Scalable compute instances enable rapid model training without capital expenditure. Healthcare systems in California migrate patient forecasting workloads to FedRAMP-authorized platforms, eliminating data center overhead while maintaining HIPAA safeguards.
- On-Premises:Dedicated hardware installations satisfy New York State financial regulations mandating localized model hosting for certain investment advisory algorithms.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud burst capacity for training workloads, common among Chicago commodity trading firms.
- Multi-Cloud:Redundant deployments across competing hyperscalers mitigate vendor lock-in and availability risk for mission-critical fraud detection pipelines.
Cloud-Based dominates new contract value. Hybrid architectures are climbing the fastest among regulated verticals.
End User:
Healthcare and financial services verticals generate the highest per-seat licensing revenue, while manufacturing adoption concentrates in predictive maintenance applications with measurable downtime reduction.
- Retail:Inventory optimization and demand forecasting tools reduce carrying costs for omnichannel operators. Pennsylvania and Ohio distribution hubs deploy these systems for seasonal workforce planning.
- Healthcare:Patient readmission prediction and length-of-stay estimation tools face FDA scrutiny. Houston's medical center corridor shows underpenetrated demand among independent hospital networks.
- Manufacturing:Equipment failure prediction minimizes unplanned downtime in automotive and aerospace supply chains. Detroit-area plants and Seattle-area aerospace clusters lead capital deployment.
- Financial Services:Real-time fraud detection and algorithmic risk management require continuous model retraining. Boston asset managers and Chicago trading firms mandate model cards and bias audits in procurement.
Financial Services holds installed capacity. Healthcare is gaining share fastest as FDA compliance roadmaps mature.
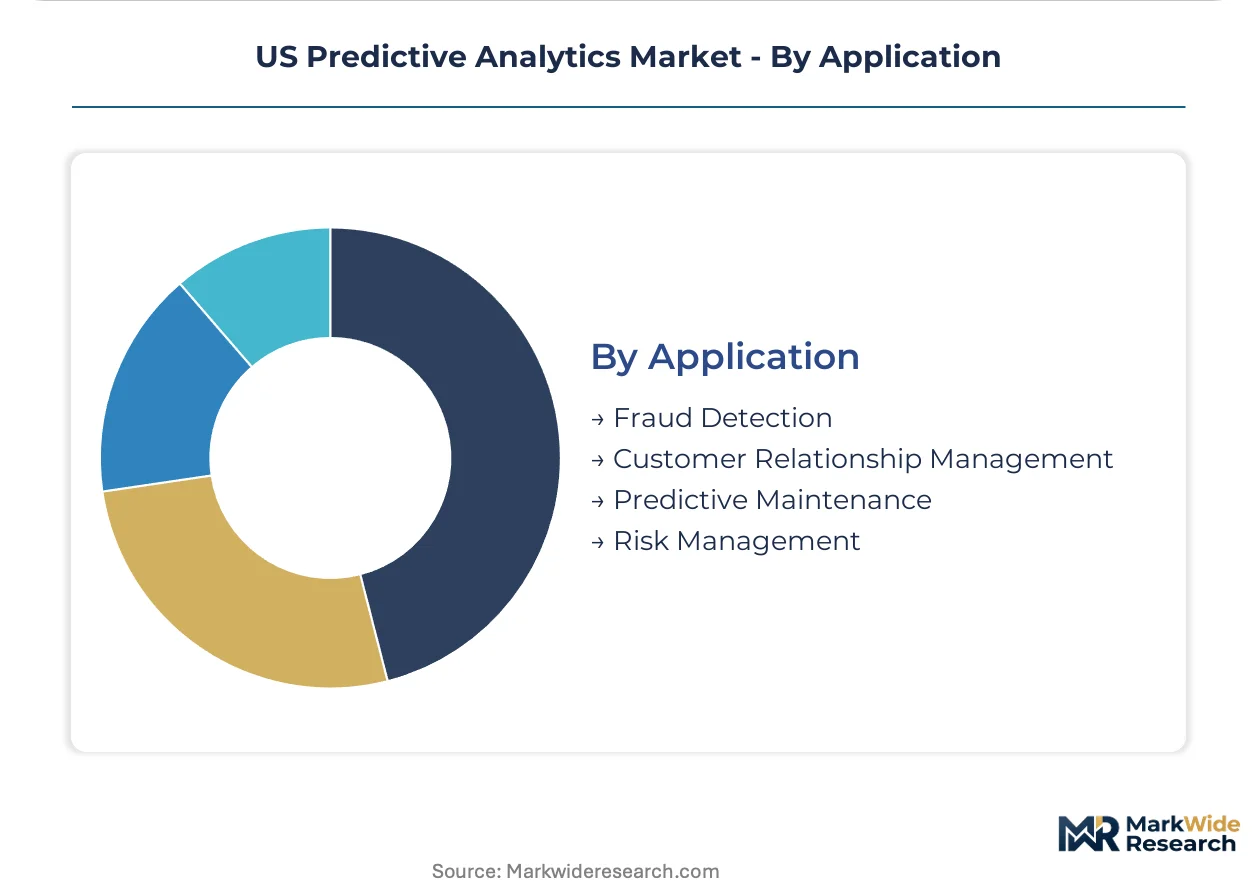
Application:
Fraud detection commands the highest real-time infrastructure spend, while predictive maintenance applications demonstrate the clearest ROI documentation for capital approval committees.
- Fraud Detection:Transaction monitoring systems deploy ensemble models to flag anomalous patterns in payment flows. Financial services firms in New York and Chicago reduce false-positive rates through MLOps automation.
- Customer Relationship Management:Churn prediction and lifetime value scoring optimize marketing spend. Retailers in California and Florida segment high-value accounts for retention campaigns.
- Predictive Maintenance:Sensor data analysis forecasts equipment degradation before functional failure. Manufacturing facilities in Michigan and South Carolina deploy these tools for critical production line assets.
- Risk Management:Credit default prediction and portfolio stress testing satisfy SEC model risk management mandates. Investment advisory firms face compliance deadlines requiring automated monitoring infrastructure.
Fraud Detection holds installed capacity. Predictive Maintenance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in California and New York demonstrate the lowest price elasticity for enterprise-grade predictive analytics, while mid-market manufacturing adopters in the Midwest and Southeast negotiate aggressively on per-seat licensing costs.
California
Silicon Valley technology firms and San Francisco-based healthcare systems drive demand for cloud-native machine learning platforms with FedRAMP authorization. The state's Office of Health Information Integrity enforces data breach notification standards that accelerate migration to HIPAA-compliant infrastructure. Los Angeles medical centers deploy patient readmission forecasting tools, though FDA validation timelines for black-box algorithms constrain deployment velocity.
New York
Manhattan investment advisory firms and Buffalo-based insurance carriers procure real-time fraud detection systems with continuous model retraining capabilities. New York State Department of Financial Services regulations mandate on-premises model hosting for certain algorithmic trading applications, blocking pure-cloud deployment options. The Hudson Valley corridor hosts specialized consultancies serving SEC model risk management compliance deadlines.
Texas
Houston's Texas Medical Center corridor generates underpenetrated demand for surgical outcome prediction tools among independent hospital networks. The Texas Department of State Health Services coordinates with federal agencies on health data interoperability standards that shape vendor procurement specifications. Dallas-Fort Worth financial services firms deploy customer churn prediction models for retail banking portfolios.
Massachusetts
Boston-area asset managers and Cambridge biotech firms lead adoption of transformer-based time series forecasting for portfolio stress testing and clinical trial optimization. The Massachusetts Executive Office of Health and Human Services promotes statewide health information exchange protocols that influence predictive data pipeline architecture. Worcester manufacturing clusters apply predictive maintenance algorithms to aerospace supply chain equipment.
Illinois
Chicago commodity trading firms and Loop-based insurance underwriters demand automated model monitoring infrastructure to satisfy evolving regulatory examination expectations. The Illinois Department of Financial and Professional Regulation scrutinizes algorithmic decision-making in consumer credit applications. Peoria agricultural equipment manufacturers pilot sensor-based failure prediction for seasonal harvest machinery.
US Predictive Analytics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US predictive analytics landscape. The vendor base separates into three tiers: hyperscale cloud platforms commanding infrastructure margins, specialized statistical software vendors serving legacy enterprise accounts, and vertical-specific challengers attacking niche compliance workflows. Dominant competitive moves include M&A activity targeting MLOps engineering talent and strategic partnerships bridging on-premises data residency requirements with cloud burst capacity.
Within the enterprise software tier, IBM Corporation and Microsoft Corporation occupy positions as archetypal platform consolidators, while Amazon Web Services anchors the infrastructure-centric segment. Oracle Corporation and SAP SE exemplify the legacy ERP-integrated approach to predictive capability deployment. These named entities represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| Salesforce, Inc. |
| Google LLC |
| Amazon Web Services |
| Alteryx |
| Others |
Pricing and Supply Chain Analysis
Ninety-day GPU allocation lead times for specialized training instances concentrate pricing power among hyperscale cloud providers while compressing margins for independent software vendors lacking captive infrastructure. This supply bottleneck feeds directly into subscription pricing tiers, with FedRAMP-authorized platforms commanding premium positioning against unaccredited alternatives.
Pricing Analysis
Managed service and extended support contracts drive lifetime value capture across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance certification depth and data residency guarantees. Cost compression in the economy tier intensifies because commodity compute instances face hyperscaler price competition. Mid-market healthcare systems in secondary metros exhibit highest price sensitivity, while Manhattan investment advisory firms accept premium positioning for on-premises sovereignty assurances.
Supply Chain Analysis
Strategic stockpiling of AI accelerators dominates procurement strategy as foundry capacity constraints in Taiwan trigger allocation rationing. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductors, while cloud infrastructure draws from domestic hyperscaler data center networks. Critical dependencies include NVIDIA H100/B200 accelerators, high-bandwidth memory modules, and specialized networking fabrics. Single-source vulnerability around TSMC advanced packaging creates chokepoint exposure. Distribution runs through direct hyperscaler marketplaces and certified systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now hinge on interoperability certification as buyers demand seamless EHR and ERP integration, shifting competitive advantage from algorithmic accuracy to ecosystem embeddedness.
For Market Incumbents: Secure MLOps engineering talent through acqui-hire transactions as pipeline construction expertise becomes the binding constraint on implementation velocity. Deepen backward integration into specialized compute infrastructure to reduce hyperscaler dependency and defend margin position against cloud-native challengers. The FDA's tightening 510(k) scrutiny for black-box clinical algorithms presents existential threat to non-compliant product lines. For New Entrants and Emerging Players: Lead with federated learning architectures targeting Houston's independent hospital networks, where surgical outcome prediction tools show minimal incumbent penetration. Texas healthcare expansion corridors offer lowest competitive density for compliant newcomers. Position around differential privacy guarantees and multi-institutional training capabilities that legacy platforms cannot replicate without architectural rebuild. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate AI divisions lacking vertical-specific compliance roadmaps, particularly those stranded between healthcare and financial services without clear FDA or SEC alignment. Long-term viability favors platforms with embedded governance tooling and automated audit documentation. Watch for FDA enforcement action velocity as inflection signal—accelerated 510(k) withdrawals would compress valuation multiples for non-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pursuit | Unlocks healthcare procurement pipelines requiring HIPAA-compliant cloud infrastructure. |
| MLOps Platform Acquisition | Addresses engineering scarcity constraining production pipeline delivery timelines. |
| EHR Integration Partnership | Reduces middleware friction dominating legacy system connectivity costs. |
| Model Card Standardization | Satisfies Boston and Chicago procurement teams mandating bias audit documentation. |
| On-Premises Sovereignty Offering | Captures New York State financial advisory demand blocked from cloud-native deployment. |
Research Methodology
Operator-level perspectives from healthcare CIOs, financial services model risk officers, cloud infrastructure procurement leads, and FDA regulatory consultants anchored the qualitative base. Secondary validation drew from SEC 10-K filings, FDA 510(k) submission databases, FedRAMP authorization manifests, and hyperscaler capex disclosures. Bottom-up sizing of deployment volumes triangulated against top-down IT spending benchmarks across the analysis window.
Sensitivity analysis tested forecast robustness across GPU cost volatility scenarios and regulatory enforcement intensity variations. Segmentation modeling spanned technology type, deployment architecture, end-user vertical, and geographic adoption cluster. CAGRs were derived from fitted growth curves against historical penetration rates, with neural architecture displacement timelines and compliance roadmap maturation serving as key demand-side inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA guidance stability or Taiwan semiconductor supply continuity would require recalibration. Forecasts reflect documented assumptions regarding MLOps talent pipeline expansion and HIPAA cloud migration velocity. Revision becomes warranted when FDA premarket review cycle duration crosses eighteen-month thresholds or when GPU allocation lead times extend beyond one hundred twenty days.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Operational Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Global Mobile BI Market
Analytics
APAC Retail Analytics Market
Analytics
Network Analytics Services Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Israel ICT Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Global Web Analytics Software Market
Analytics
Global Customer Experience Analytics Market
Analytics
Europe Location Data Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
Global System Monitoring Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Brazil Big Data Analytics Market