
 Global Enterprise Performance Management Market | 2026-2036
Global Enterprise Performance Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Performance Management Market Foresight
Direct enterprise sales channels is narrowing as cloud-native vendors displace traditional on-premises resellers. Oracle Corporation leverages its database-to-application stack to sustain integrated planning suites across large accounts. SAP SE anchors its position through S/4HANA-embedded performance tools that dominate European manufacturing installations. Workday Inc. competes aggressively in workforce planning segments where HR-ERP convergence creates switching costs.
Enterprise performance management comprises integrated software processes and methodologies that translate strategic objectives into operational plans, financial budgets, and measurable outcomes through real-time data consolidation, predictive modeling, and cross-functional dashboards. The discipline serves primarily to align departmental execution with corporate financial targets and regulatory disclosure requirements. Cloud-based deployment now leads solution offering growth as subscription economics reduce capital barriers for mid-market adopters, while financial planning, budgeting and forecasting commands the largest margin pool due to its centrality in CFO technology spending. Reporting and analytics is accelerating fastest as embedded AI capabilities expand self-service visualization beyond traditional finance users.
FDA 21 CFR Part 11 electronic record requirements, EU CSRD sustainability reporting standards, and SEC climate disclosure rules collectively expand audit-trail and scenario-modeling obligations that EPM platforms must satisfy. These frameworks shape product roadmaps by mandating immutable data lineage, automated consolidation controls, and multi-scenario stress testing as baseline capabilities. Stakeholders should monitor how generative AI integration alters the competitive boundary between standalone EPM suites and broader ERP planning modules.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from quarters to weeks, forcing incumbent vendors to restructure pricing models and partner ecosystems around subscription economics rather than perpetual license maintenance streams.
Growth Catalysts
- EU CSRD Mandates:Sustainability disclosure requirements are compelling European manufacturers to consolidate financial and non-financial reporting onto unified platforms with automated audit trails.
- Generative AI Integration:Natural language interfaces for variance analysis and scenario modeling are expanding user bases beyond trained finance specialists to operational managers.
- German Industrial Digitization:Government-backed Industrie 4.0 programs are accelerating advanced planning and scheduling tool procurement across automotive and machinery supply chains.
Market Restraints
- Data Migration Complexity:Decades of fragmented ERP implementations create schema incompatibilities that prolong cloud transition timelines and inflate professional services costs.
- Concentrated Cloud Infrastructure:Reliance on three hyperscalers for hosting concentrates operational risk and creates vendor lock-in concerns for regulated financial institutions.
- Skills Scarcity:Shortages of professionals combining financial planning expertise with Python and SQL proficiency constrain implementation velocity for mid-market enterprises.
Strategic Opportunities
- India Manufacturing Uptake:PLI scheme beneficiaries are modernizing planning infrastructure, creating first-mover advantage for vendors offering localized compliance templates.
- Extended Planning and Analysis:Convergence of financial forecasting with supply chain and workforce planning opens greenfield deployments outside traditional CFO technology budgets.
- Embedded AI Regulatory Tailwinds:EU AI Act risk classification requirements are driving demand for explainable forecasting models with documented algorithmic decision pathways.
Industry Challenges
- Multi-Cloud Integration Friction:Enterprises operating across AWS, Azure, and Google Cloud environments face data synchronization failures that corrupt consolidated reporting.
- ISO 27001 Certification Timelines:Protracted security audit cycles delay go-live dates for cloud deployments in banking and healthcare verticals with stringent data residency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Performance Management Market |
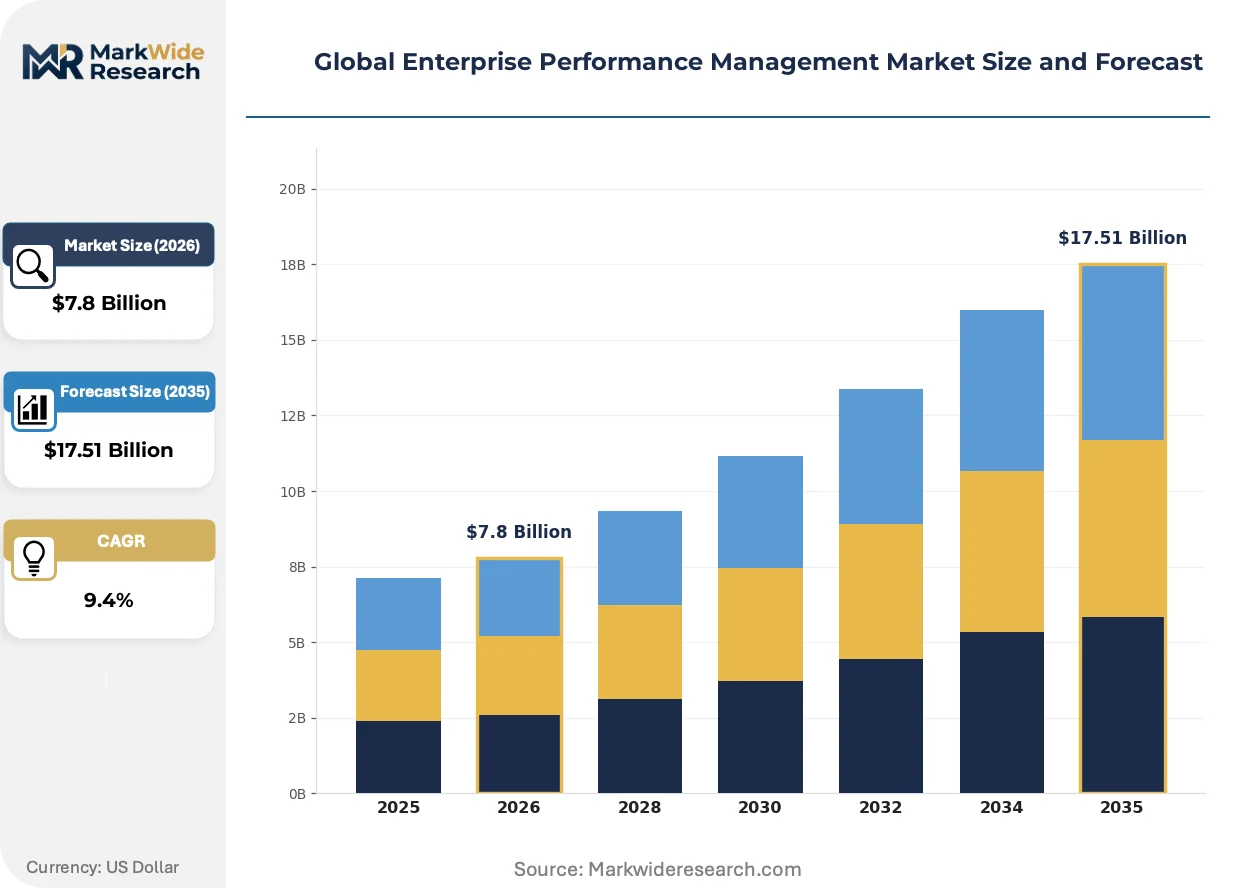
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Services Solution Offering: Financial Planning, Budgeting & Forecasting, Reporting & Analytics, Strategy Management, Profitability Modeling Application: Financial Consolidation, Workforce Planning, Sales Performance, Risk Management, Operational Performance End User Industry: Telecommunications, Manufacturing, Energy & Utilities, Government Agencies, Consumer Electronics |
| Companies Covered | Oracle Corporation, SAP SE, IBM Corporation, Anaplan Inc., OneStream Software LLC, Wolters Kluwer N.V., Workday Inc., SAS Institute Inc., Board International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Performance Management Market Shifts & Advancements
Embedded machine learning is shifting competitive advantage from historical reporting accuracy to predictive intervention timing, compressing the window between insight generation and operational response.
Agentic AI systems that autonomously execute variance investigations and re-forecasting workflows are rendering obsolete the manual spreadsheet reconciliation processes that still dominate monthly close cycles at mid-market enterprises. Finance teams at industrial manufacturers are piloting these capabilities most aggressively, driven by margin pressure to reduce planning cycle times from weeks to days. The structural consequence is a compression of competitive differentiation around speed-to-insight rather than breadth of functionality.
SEC climate disclosure rules are mandating scenario-stress testing capabilities that extend beyond traditional financial variables to incorporate carbon price trajectories and physical asset risk exposure. This regulatory pressure is forcing EPM vendors to integrate sustainability data models directly into core planning engines rather than treating ESG as a peripheral reporting module. Asset-heavy sectors including utilities and materials processing are experiencing the steepest compliance-driven procurement acceleration.
Subscription-based consumption models are displacing seat-based licensing as the dominant commercial structure, with buyers demanding usage-scaled pricing tied to monthly active planning sessions rather than total named users. This shift is most pronounced among professional services and technology firms with seasonal workforce fluctuations. Vendors responding with elastic pricing architectures are capturing disproportionate share in North American and UK mid-market segments where CFOs prioritize cost variability over fixed commitments.
Global Enterprise Performance Management Market Segmentation
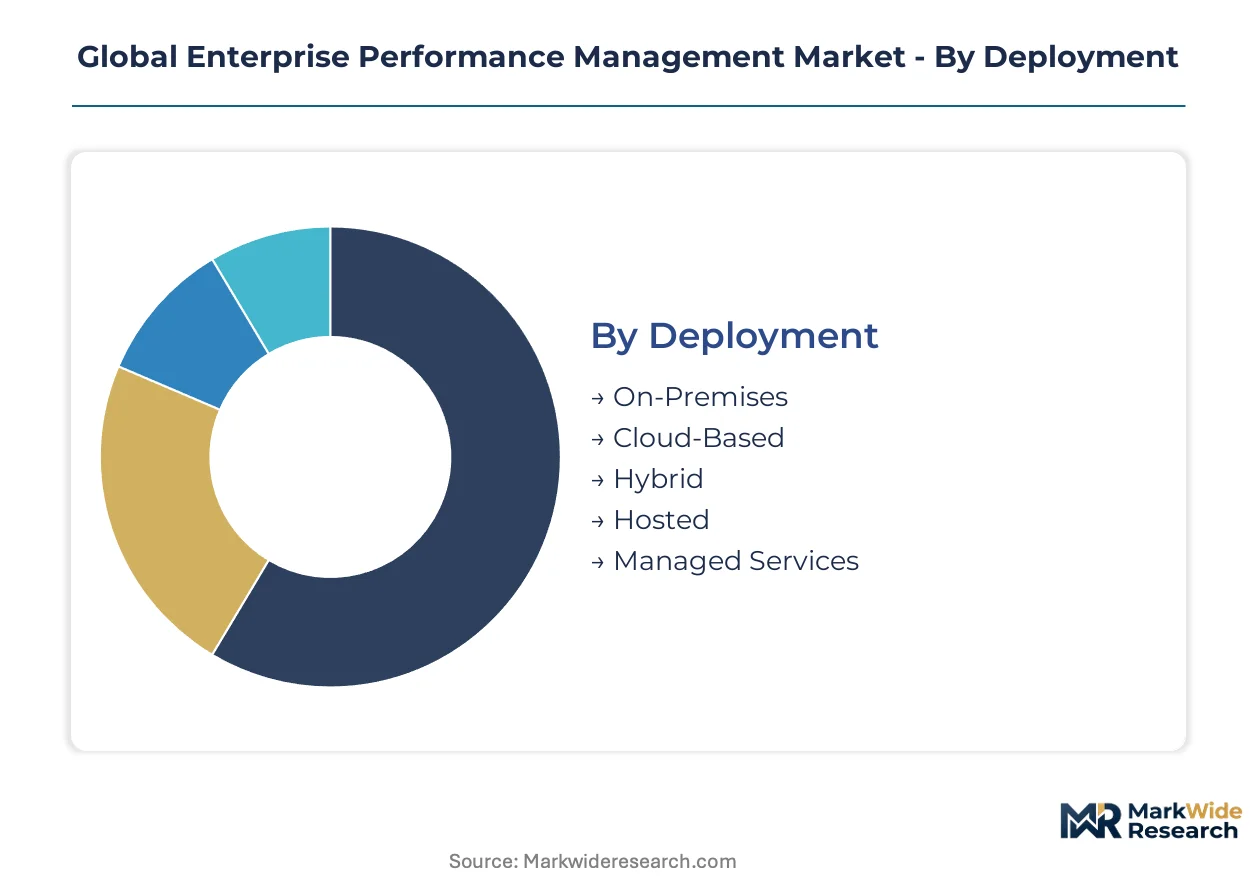
Enterprise Performance Management deployments diverge sharply by technical architecture and organizational readiness, with each configuration demanding distinct professional services intensity and ongoing vendor engagement. Segmentation reveals where cloud-native vendors displace legacy incumbents and which solution bundles command premium pricing.
Deployment:
After-sales service intensity varies dramatically across deployment modes, with on-premises installations requiring sustained technical support while cloud-native configurations shift burden to automated updates and remote monitoring.
- On-Premises:Legacy infrastructure installed within client data centers demands continuous hardware maintenance, security patching, and version upgrade management. German automotive manufacturers and Japanese industrial conglomerates sustain this model for air-gapped compliance environments where data sovereignty overrides cloud economics.
- Cloud-Based:Multi-tenant SaaS architectures eliminate infrastructure ownership while embedding automatic feature updates and elastic capacity scaling. Mid-market enterprises across the United States and United Kingdom prioritize this mode for CFO-mandated OpEx transformation and rapid deployment timelines.
- Hybrid:Split workloads maintain sensitive financial consolidation on-premises while pushing operational planning to cloud instances. Energy utilities in Texas and Alberta deploy this architecture to satisfy FERC data residency requirements without sacrificing workforce planning agility.
- Hosted:Single-tenant cloud deployments on dedicated virtual infrastructure address regulated financial institutions unwilling to accept multi-tenant risk exposure. Swiss private banks and Singaporean wealth managers dominate this segment.
- Managed Services:Outsourced platform administration transfers operational responsibility to vendor or third-party specialists. Australian superannuation funds and Canadian pension administrators leverage this mode to overcome internal skills scarcity.
By volume, Cloud-Based deployments lead. By growth pace, Managed Services is ahead.
Solution Offering:
Margin concentration follows CFO technology spending priorities, with financial planning modules capturing the largest share of enterprise software budgets while adjacent capabilities expand through cross-sell motions.
- Financial Planning, Budgeting & Forecasting:Core rolling forecast engines with driver-based modeling and scenario versioning represent the foundational EPM investment. Manufacturing enterprises in Germany and Mexico anchor demand through Industrie 4.0-linked capital allocation requirements.
- Reporting & Analytics:Self-service visualization platforms with embedded natural language querying accelerate beyond traditional finance users. Technology firms in Israel and Ireland deploy these tools for operational managers requiring real-time variance alerts without BI specialist intervention.
- Strategy Management:Balanced scorecard and OKR alignment modules connect operational metrics to executive compensation frameworks. Private equity-backed portfolio companies across the United States adopt these for holding-company reporting standardization.
- Profitability Modeling:Activity-based costing and customer-level contribution analysis tools dissect margin leakage across product lines. Telecommunications operators in Brazil and South Korea utilize these for tariff optimization and churn prediction.
Financial Planning, Budgeting & Forecasting commands the largest installed base. Reporting & Analytics is climbing the fastest.
Application:
Functional scope determines integration complexity and implementation duration, with workforce planning requiring HR system connectivity while risk management demands regulatory template libraries.
- Financial Consolidation:Multi-entity close automation with intercompany elimination and currency translation handles the most data-intensive EPM workloads. Japanese trading houses and Dutch multinational insurers anchor this segment through complex holding structures spanning dozens of jurisdictions.
- Workforce Planning:Headcount forecasting integrated with compensation benchmarking and skills inventory management. Professional services firms in the United Kingdom and India deploy these tools for project-based staffing optimization.
- Sales Performance:Territory quota allocation and commission calculation engines with predictive pipeline analytics. Medical device distributors across the United States and Germany utilize these for incentive alignment with regulatory compliance constraints.
- Risk Management:Scenario stress testing with automated control documentation for audit trail requirements. Banks in Singapore and Australia prioritize these capabilities for APRA and MAS prudential standards adherence.
- Operational Performance:Shop-floor KPI dashboards and OEE metrics bridging ERP production data with financial outcomes. Machinery OEMs in Italy and Taiwan anchor demand through servitization business models requiring outcome-based contract tracking.
Financial Consolidation retains the deepest penetration. Operational Performance is gaining share fastest.
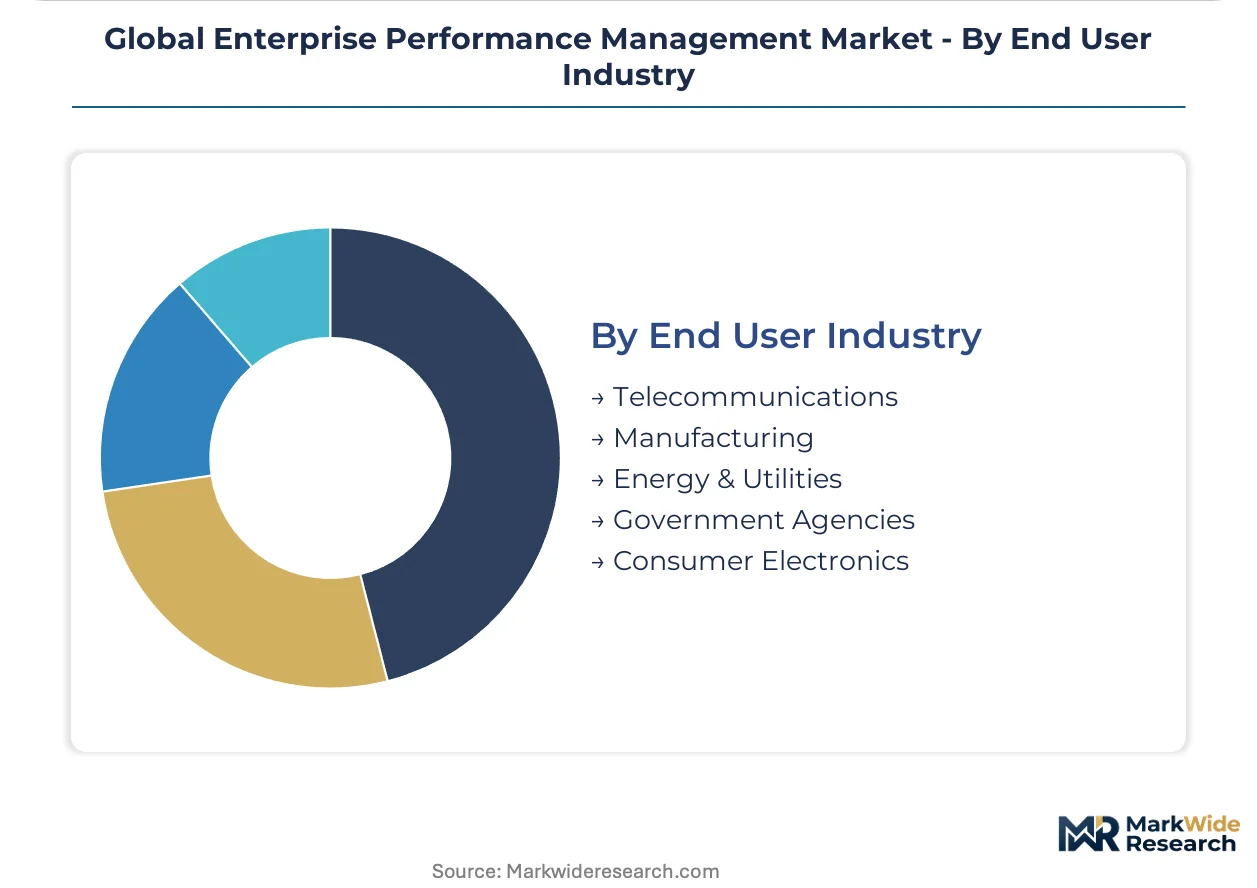
End User Industry:
Industry verticals impose distinct regulatory and operational constraints that shape module prioritization and deployment urgency.
- Manufacturing:Advanced planning and scheduling integration with MES systems dominates procurement criteria. German automotive suppliers and Mexican aerospace contractors drive adoption through customer-mandated digital thread requirements.
- Energy & Utilities:Asset-intensive capital project forecasting and regulatory rate-case modeling anchor EPM investments. Electric utilities in Texas and renewable developers in Denmark utilize these for IRA-linked investment tax credit optimization.
- Telecommunications:Subscriber lifetime value modeling and network capex allocation across 5G rollout timelines. Operators in South Korea and Brazil prioritize these for spectrum auction preparation and tariff rebalancing.
- Government Agencies:Program-level budgeting with grant compliance tracking and citizen service outcome measurement. Federal departments in Australia and provincial ministries in Canada anchor this segment.
- Consumer Electronics:Short-cycle product profitability analysis and channel inventory optimization. Smartphone and wearable manufacturers in China and Vietnam deploy these for quarterly SKU rationalization.
Manufacturing represents the largest vertical footprint. Energy & Utilities shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC climate disclosure rules anchor United States procurement patterns. CSRD mandates reshape European vendor selection. PLI scheme incentives accelerate Indian manufacturing digitization.
United States
Financial services and technology sectors drive cloud-native EPM adoption. SEC climate disclosure rules mandate scenario-stress testing capabilities that extend beyond traditional financial variables. New York-based asset managers and San Francisco technology firms pilot generative AI interfaces for variance analysis.
Germany
Automotive suppliers and machinery OEMs dominate advanced planning tool procurement. Industrie 4.0 government programs accelerate capital allocation software investments. Stuttgart industrial cluster and Munich manufacturing belt anchor demand for S/4HANA-embedded performance tools.
India
PLI scheme beneficiaries modernize planning infrastructure across electronics and pharmaceutical manufacturing. RBI prudential standards shape risk management module requirements for banking institutions. Maharashtra and Gujarat industrial corridors attract first-mover vendors offering localized compliance templates.
United Kingdom
Professional services firms prioritize workforce planning tools for project-based staffing optimization. FCA regulatory expectations drive audit-trail capabilities in financial consolidation modules. London consulting cluster and Manchester shared service centers anchor mid-market cloud deployments.
Singapore
Wealth managers and regional headquarters demand hosted single-tenant architectures for data residency compliance. MAS technology risk management guidelines shape vendor selection criteria. Marina Bay financial district anchors procurement for private banking EPM infrastructure.
Global Enterprise Performance Management Market Competitive Landscape
Database-to-application stack vendors and cloud-native specialists split the market between integrated suite dominance and agile deployment economics. Incumbent consolidation around perpetual license maintenance streams confronts subscription-model disruption. Strategic archetypes include full-stack platform providers, best-of-breed point solution vendors, and vertical-specialist configurators. Competitive moves concentrate on generative AI integration partnerships and multi-cloud certification acceleration.
Within the full-stack archetype, Oracle Corporation and SAP SE exemplify database-to-application integration strategies. Workday Inc. occupies a position within the cloud-native workforce planning tier. These three entities represent the dominant competitive anchors across large-account procurement and mid-market displacement dynamics.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Anaplan Inc. |
| OneStream Software LLC |
| Wolters Kluwer N.V. |
| Workday Inc. |
| SAS Institute Inc. |
| Board International SA |
| Others |
Supply & Pricing Matrix
Transatlantic fiber-optic cable routes connecting Frankfurt and New York carry the bulk of real-time financial data synchronization traffic, with latency-sensitive pricing for hosted EPM deployments rising when congestion hits these corridors. Supply concentration among three hyperscalers amplifies their pricing power over subscription tiers, while downstream buyers face widening spreads between standardized SaaS offerings and configured implementations.
Pricing Analysis
The customization-premium spread separates multi-tenant SaaS subscriptions from single-tenant hosted deployments by a factor of three to five in annual contract value. Subscription models dominate, with pricing differentiation driven by data residency certification tiers and integration complexity with legacy ERP systems. Pricing pressure stems from cloud-native entrants undercutting incumbent maintenance streams. Mid-market manufacturing enterprises exhibit the highest price sensitivity, while Swiss private banks and Singaporean wealth managers accept premium tiers for compliance-grade isolation.
Supply Chain Analysis
Upstream feedstock for EPM platforms centers on hyperscale compute capacity concentrated in the United States, Ireland, and Singapore, with secondary nodes in Germany and India expanding rapidly. Core dependencies include GPU clusters for AI-enabled forecasting, proprietary database licensing, and API integration frameworks. Single-source vulnerability around NVIDIA AI silicon creates procurement bottlenecks for vendors racing to embed generative capabilities. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings, with systems integrators capturing implementation services revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as regulatory divergence between EU CSRD mandates and SEC climate disclosure rules creates specialized compliance modules that generalist ERP vendors cannot address uniformly. Demand-side shift toward explainable AI auditing opens niches for algorithmic transparency specialists.
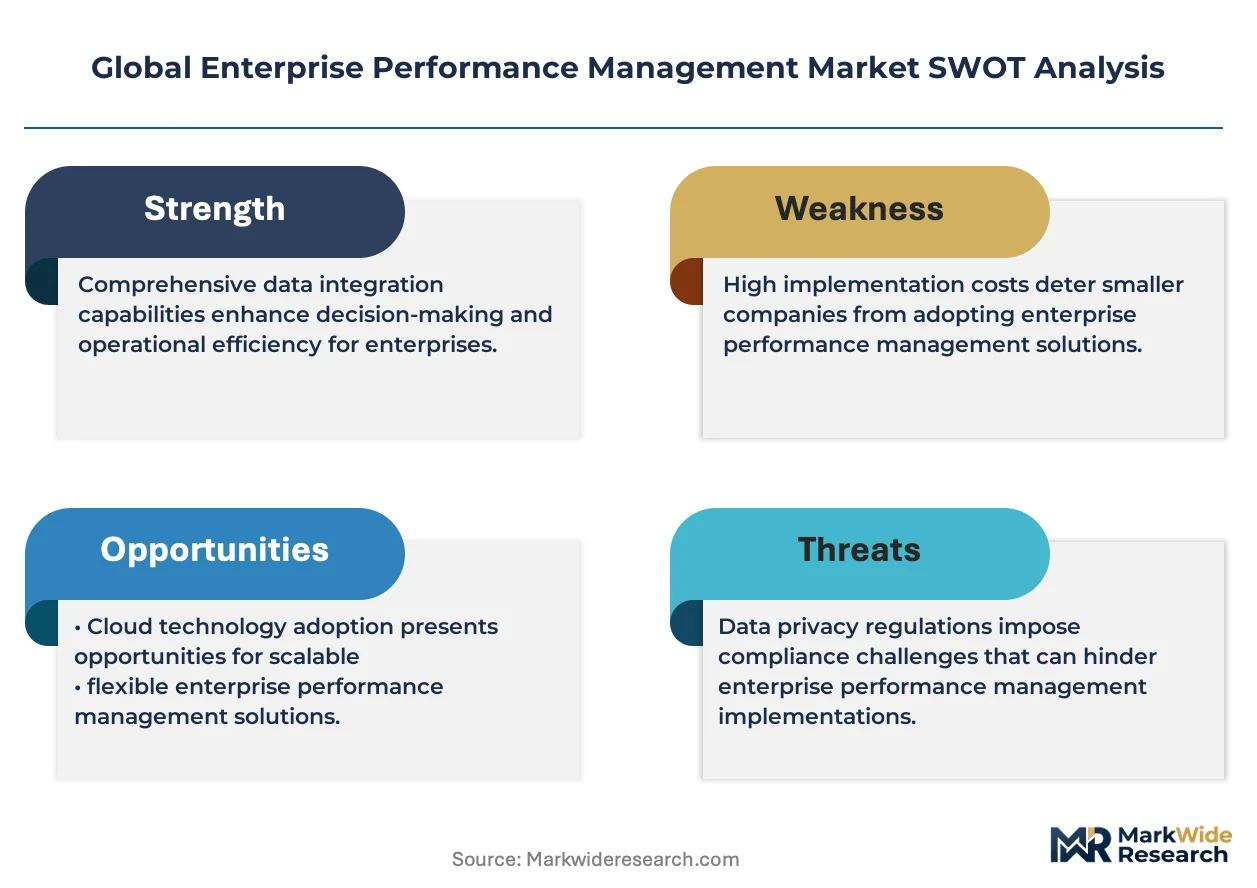
For Market Incumbents: Entrench position through embedded AI integration that locks in data gravity, while accelerating multi-cloud certification to neutralize hyperscaler lock-in threats. Prioritize ISO 27001 pre-certification for banking verticals to compress sales cycles. Defensive consolidation around S/4HANA and Oracle database-to-application stacks preserves enterprise accounts against cloud-native displacement.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme manufacturing corridors where localized compliance templates for electronics and pharmaceutical producers remain underserved. Target mid-market professional services firms in the United Kingdom with elastic consumption pricing tied to project-based staffing volatility. Go-to-market leverage through hyperscaler marketplace co-sell programs reduces customer acquisition costs versus direct field sales.
For Investors and Strategic Acquirers: Cloud-native workforce planning specialists with pre-built SAP and Workday connectors represent the most defensible acquisition archetype over a five-to-ten year window. These assets capture HR-ERP convergence budgets that standalone financial planning vendors cannot access. Monitor EU AI Act enforcement timelines as the inflection signal for explainable forecasting model demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Integration Partnership | Natural language interfaces for variance analysis expand user bases beyond finance specialists at German automotive suppliers. |
| Multi-Cloud Certification Acceleration | AWS-Azure-Google Cloud compatibility reduces data synchronization failures corrupting consolidated reporting for energy utilities. |
| Vertical Compliance Template Development | Pre-configured CSRD and SEC climate disclosure modules shorten implementation timelines for asset-heavy European manufacturers. |
| Elastic Consumption Model Deployment | Usage-scaled pricing tied to monthly active planning sessions captures UK professional services firms with seasonal workforce fluctuations. |
| Acquisition of Workforce Planning Specialist | HR-ERP convergence capabilities create switching costs that defend against cloud-native displacement in North American mid-market accounts. |
Research Methodology
The analysis maps cloud deployment modes, solution offerings, and end-user industry verticals, each validated through CFOs, IT procurement officers, platform engineers, and systems integration specialists. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and Gartner enterprise software expenditure surveys. Bottom-up deployment volume estimates triangulated against top-down CFO technology budget allocations across the analysis window.
Assumption sets held regulatory enforcement timelines and cloud infrastructure pricing curves fixed while varying enterprise digitization maturity and AI adoption velocity. Segmentation dimensions modeled include deployment architecture, organization size, vertical regulatory intensity, and regional compliance framework. CAGRs derived from logistic diffusion curves fitted to historical ERP replacement cycles and cloud migration patterns. Forecast inputs incorporated Industrie 4.0 program funding trajectories and PLI scheme beneficiary expansion schedules.
Stress conditions across hyperscaler concentration risk, data migration failure rates, and skills scarcity severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and cloud infrastructure cost trajectories. Cross-checking against Gartner and IDC enterprise software expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
India Contact Center Analytics Market
Analytics
Europe Predictive Analytics Market
Analytics
Spend Analytics Software Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Network Traffic Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Global Subscription Analytics Software Market
Analytics
Data Analytics Outsourcing Market
Analytics
Location Analytics Adoption Spending Market
Analytics
Global Healthcare Cloud Based Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Global Mobile BI Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Sales Intelligence Market
Analytics
Hadoop Big Data Analytics Solution Market