
 IT Operation Analytics (ITOA) Software Market | 2026-2036
IT Operation Analytics (ITOA) Software Market Size, Share, and Industry Trends Forecast 2026-2036
IT Operation Analytics (ITOA) Software Market Foresight
Mid-market enterprises with hybrid infrastructure footprints is redrawing the ITOA demand map, overtaking traditional large-enterprise buyers as the fastest-growing archetype. Splunk Inc. leverages its data-to-everything platform architecture to anchor high-velocity security and observability workloads. IBM Corporation sustains mainframe-to-cloud integration capabilities that dominate regulated industries with legacy debt. Dynatrace LLC differentiates through Davis AI causal analysis, positioning its automated root-cause engine against rules-based competitors.
IT Operation Analytics (ITOA) Software encompasses algorithmic platforms that ingest, correlate, and analyze telemetry streams from servers, networks, applications, and endpoints to detect anomalies, forecast failures, and automate remediation workflows. These systems process structured and unstructured operational data at sub-second latencies, typically employing machine learning models trained on historical incident patterns to reduce mean time to resolution in enterprise technology estates. Cloud-based deployment now leads solution architecture as organizations abandon capital-intensive on-premises data lakes for elastic consumption models, while application performance management commands the largest margin pool due to its direct linkage to revenue-impacting digital services. Infrastructure monitoring represents the most mature segment with entrenched vendor relationships, whereas compliance monitoring use cases are expanding fastest as regulators mandate continuous audit trails across distributed systems.
The EU AI Act classifies certain ITOA autonomous decision systems as high-risk, compelling providers to maintain human oversight and transparency documentation for algorithmic incident response. In the United States, SEC cybersecurity disclosure rules and NIST SP 800-53 controls are forcing publicly traded enterprises to deploy real-time analytics with immutable logging for audit readiness. Stakeholders must monitor how divergent transatlantic regulatory timelines for AI governance reshape vendor certification requirements and procurement criteria.
Market Dynamics
Hybrid cloud complexity is compressing enterprise tolerance for siloed monitoring tools, forcing consolidation onto unified telemetry platforms that correlate infrastructure, application, and security signals in real time.
Growth Catalysts
- EU AI Act compliance mandates:European data center operators must deploy continuous algorithmic audit trails for high-risk autonomous systems, expanding ITOA procurement in Germany, France, and the Netherlands.
- Financial services operational resilience:Basel III operational risk frameworks and SEC cybersecurity disclosure rules compel real-time incident logging across trading infrastructure and payment rails.
- Edge computing telemetry proliferation:Manufacturing and logistics networks generate petabyte-scale distributed data streams that exceed human analytical capacity, necessitating automated pattern recognition.
Market Restraints
- Specialized talent scarcity:Machine learning operations engineers and site reliability experts command premium compensation, constraining deployment velocity for mid-market enterprises.
- Data residency fragmentation:Divergent national data localization laws in China, Russia, and India force redundant infrastructure investment, elevating total cost of ownership.
- Legacy observability debt:Mainframe-centric financial institutions face decade-long migration timelines to cloud-native telemetry architectures, delaying platform consolidation.
Strategic Opportunities
- India's digital public infrastructure:The country's unified payments interface and health stack generate massive operational data volumes with limited incumbent analytics vendors.
- Sustainability-linked observability:CSRD and EU Green Deal carbon reporting requirements create demand for energy consumption analytics integrated with operational dashboards.
- Convergence of AIOps and security operations:Unified platforms that fuse threat intelligence with performance telemetry address CISO-CIO alignment pressures in regulated sectors.
Industry Challenges
- Multi-cloud integration complexity:Enterprises operating across AWS, Azure, and Google Cloud struggle with normalized data schemas and consistent alerting semantics.
- Algorithmic explainability requirements:Regulators and internal risk committees demand transparent reasoning chains for automated remediation actions, complicating black-box model deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Operation Analytics (ITOA) Software Market |
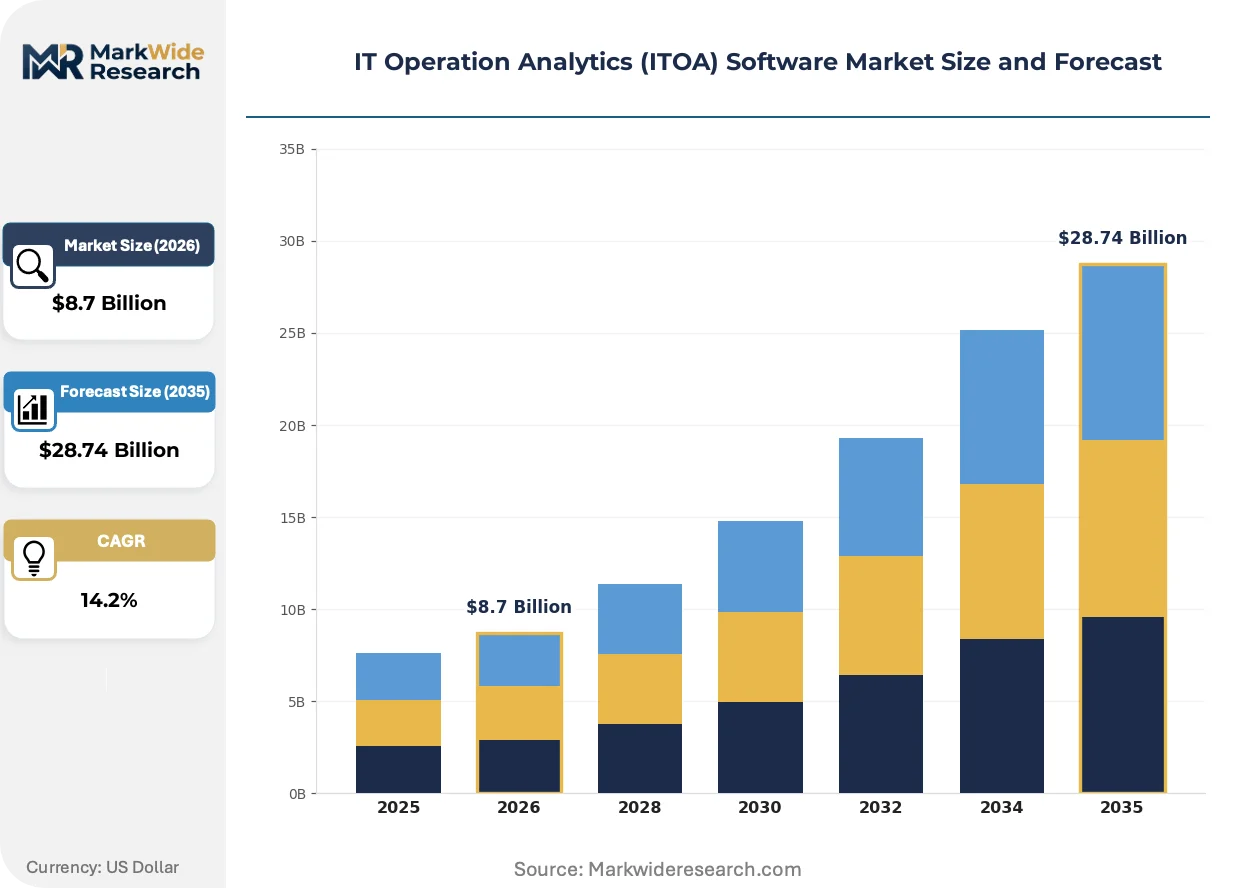
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Large Enterprises, SMEs, Government, Managed Service Providers Solution: Infrastructure Monitoring, Application Performance Management, IT Service Management, Network Analytics Use Case: Incident Management, Capacity Planning, Performance Optimization, Compliance Monitoring |
| Companies Covered | Splunk Inc., IBM Corporation, Microsoft Corporation, Oracle Corporation, BMC Software, Inc., Cisco Systems, Inc., Dynatrace LLC, ServiceNow, Inc., Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Operation Analytics (ITOA) Software Market Shifts & Advancements
OpenTelemetry standardization is dismantling proprietary agent lock-in, enabling portable instrumentation that follows workloads across cloud boundaries and on-premises estates.
Observability pipelines are decomposing monolithic data lake architectures into modular, stream-processing components. Mid-market SaaS providers adopt these lightweight telemetry routers to avoid capital-intensive storage commitments. This shift is compressing incumbent vendor maintenance revenue and elevating consumption-based pricing power for specialized stream analytics engines.
The EU AI Act's high-risk system classification is forcing transparency documentation for autonomous incident response workflows. German automotive manufacturers and French energy utilities now require algorithmic impact assessments before deploying self-healing infrastructure. This regulatory friction is privileging vendors with built-in explainability layers over opaque neural network alternatives.
Enterprise buyers are unbundling annual platform contracts into modular component procurement. Financial services firms in the United States now separately source log management, metric aggregation, and tracing visualization from best-of-breed specialists rather than accepting bundled suites. This disaggregation is most visible among hedge funds and regional banks with dedicated platform engineering teams.
IT Operation Analytics (ITOA) Software Market Segmentation
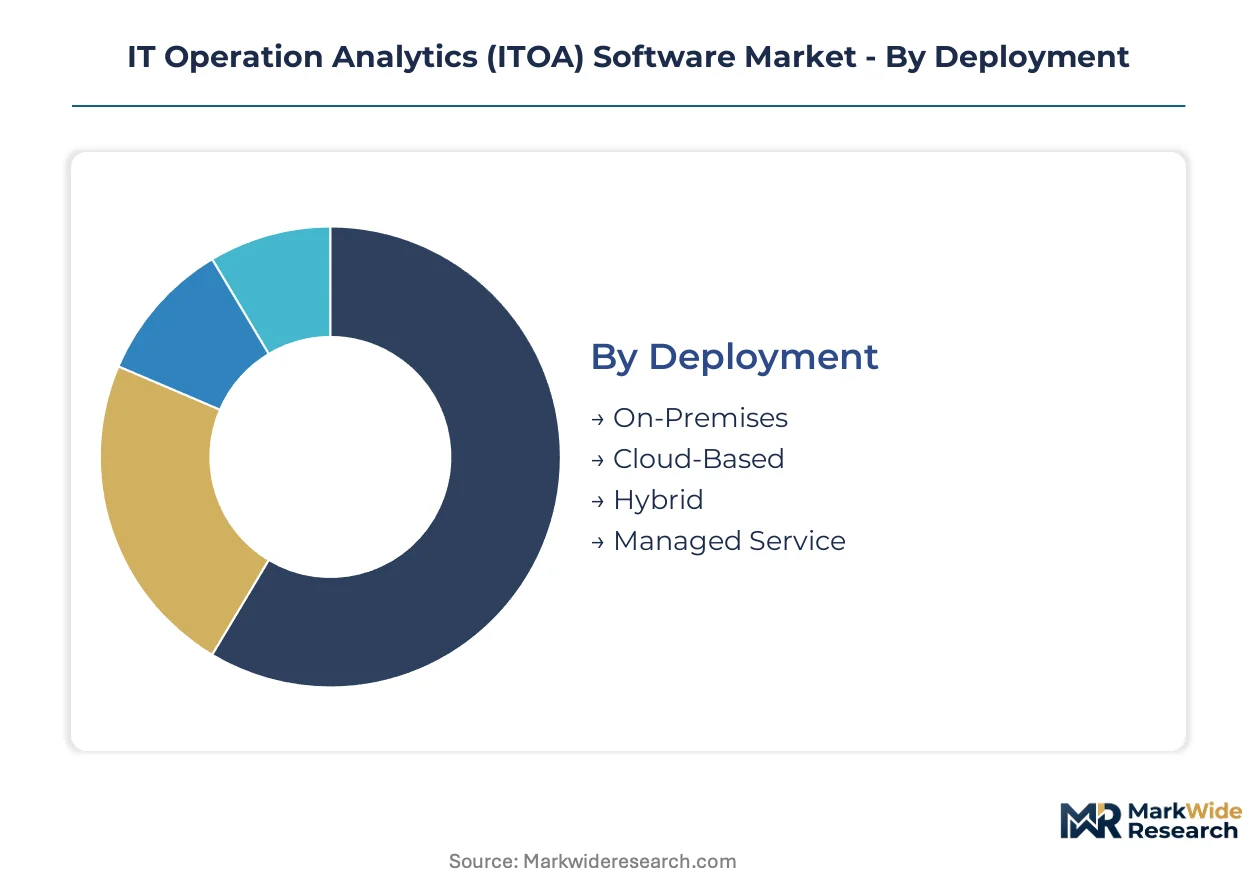
ITOA software procurement patterns diverge sharply across deployment architectures and organizational scale. Vendors must align pricing models, integration complexity, and compliance capabilities to distinct buyer archetypes rather than pursuing universal platform strategies.
Deployment:
Cloud-based solutions dominate export-oriented procurement from North American and European vendors, while on-premises deployments concentrate in domestic markets with strict data localization mandates.
- On-Premises:Organizations with sovereign data requirements operate dedicated telemetry infrastructure within facility boundaries. German automotive manufacturers and French defense contractors favor this model to satisfy national security classifications and EU data residency expectations.
- Cloud-Based:Elastic consumption models eliminate capital expenditure for storage and compute scaling. Mid-market enterprises across the United States, United Kingdom, and Netherlands adopt this architecture fastest due to limited internal platform engineering resources.
- Hybrid:Split deployments retain sensitive operational data on-premises while bursting analytics workloads to public cloud. Financial services firms in Singapore and Switzerland deploy this architecture to reconcile trading floor latency requirements with regulatory cloud guidance.
- Managed Service:Third-party operators assume full responsibility for telemetry ingestion, correlation, and dashboard delivery. Regional banks and municipal governments across Spain and Italy procure this option to circumvent specialized talent scarcity.
Cloud-based holds the largest share; momentum sits with Hybrid as regulated industries navigate sovereignty requirements.
End User:
Cost tier segmentation reveals divergent platform complexity thresholds and sales cycle durations across buyer categories.
- Large Enterprises:Multi-divisional technology estates demand unified telemetry platforms correlating mainframe, distributed, and containerized workloads. Fortune 500 manufacturers and telecommunications operators in the United States and Germany anchor this segment with seven-figure annual contracts.
- SMEs:Resource-constrained organizations prioritize SaaS-delivered observability with minimal configuration overhead. British fintech startups and Dutch logistics scale-ups drive fastest expansion here through consumption-based pricing acceptance.
- Government:Federal, state, and municipal agencies mandate FedRAMP, IL5, or equivalent security certifications. United States civilian agencies and United Kingdom National Health Service trusts represent concentrated procurement volumes.
- Managed Service Providers:Multi-tenant platform operators aggregate telemetry across hundreds of client environments. Indian IT services exporters and Polish outsourcing specialists are expanding most quickly in this category.
Large Enterprises retain dominant spend; SMEs are expanding most quickly as vendor pricing stratification penetrates mid-market buyers.
Solution:
Application maturity determines margin structure, with established categories defending maintenance revenue while emerging functions capture expansion budgets.
- Infrastructure Monitoring:Server, storage, and network telemetry collection represents the most mature functional category. Established relationships with United States federal agencies and German industrial conglomerates sustain incumbent vendor positions despite limited growth velocity.
- Application Performance Management:Real-time tracing of microservices and serverless functions commands premium pricing due to direct revenue linkage. E-commerce platforms and payment processors across the United Kingdom and Australia drive replacement cycles as legacy APM tools fail at cloud-native scale.
- IT Service Management:Integration of observability data with incident ticketing and change management workflows. Scandinavian public sector organizations and Canadian healthcare networks prioritize this capability for operational resilience certification.
- Network Analytics:Deep packet inspection and flow analysis for security and performance optimization. Telecommunications operators in Japan and South Korea deploy these tools to manage 5G core network complexity.
Infrastructure Monitoring holds the largest share; Application Performance Management shows the steepest expansion trajectory as digital revenue dependence intensifies.
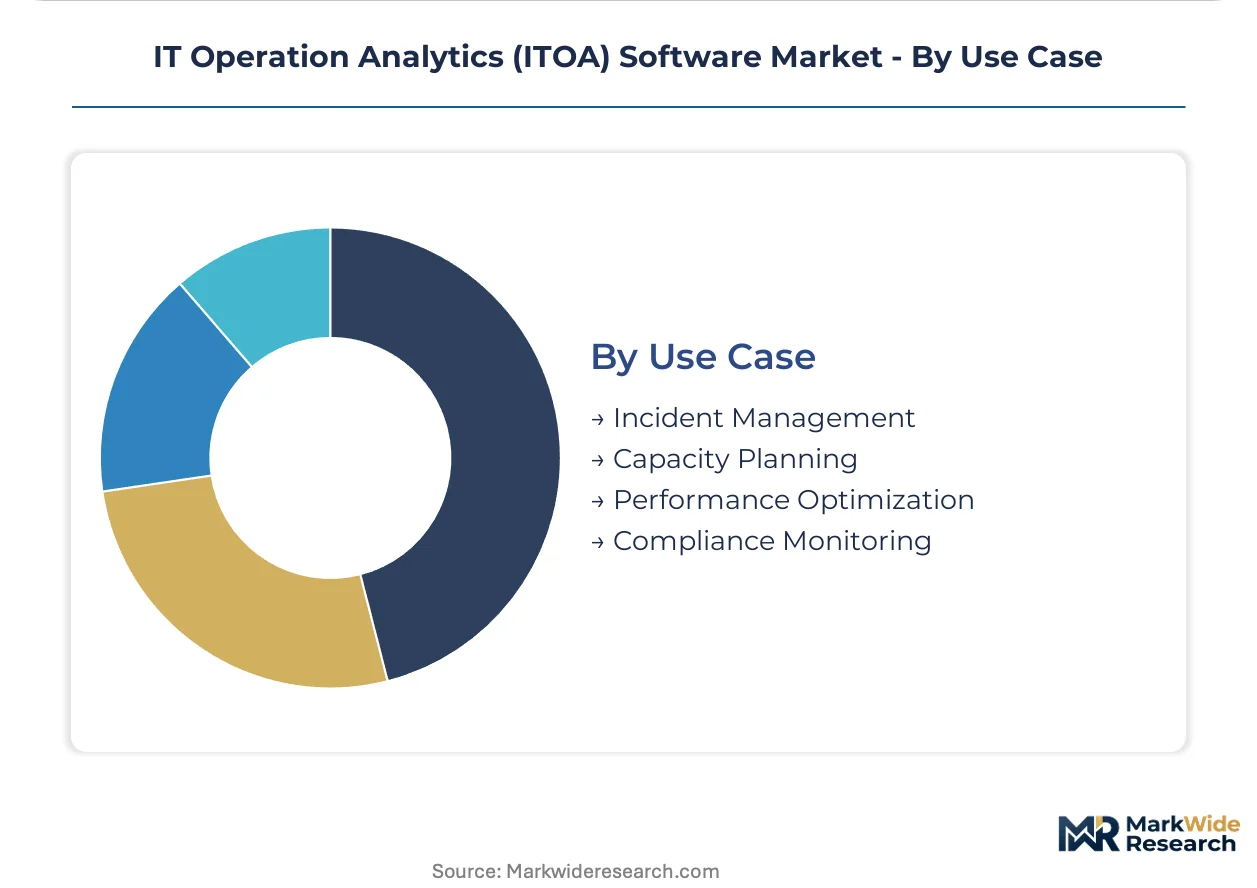
Use Case:
Customer type segmentation maps functional priorities to organizational maturity and regulatory exposure levels.
- Incident Management:Automated detection, correlation, and escalation of operational anomalies. United States securities exchanges and German energy grid operators mandate sub-minute mean time to detection for systemic risk mitigation.
- Capacity Planning:Predictive modeling of resource consumption to optimize infrastructure investment. Retailers across France and Italy deploy these capabilities to manage seasonal demand spikes without over-provisioning.
- Performance Optimization:Continuous tuning of application response times and infrastructure efficiency. Gaming platforms and streaming services in Sweden and Finland prioritize this use case for competitive user experience differentiation.
- Compliance Monitoring:Continuous audit trail generation and regulatory reporting automation. Financial institutions subject to SEC cybersecurity disclosure rules and EU AI Act documentation requirements are expanding procurement fastest here.
Incident Management holds the largest share; Compliance Monitoring gains share fastest as regulatory documentation mandates proliferate across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor headquarters and cloud infrastructure investment concentrate heavily in the United States, though deployment demand spans multiple regulatory jurisdictions with distinct compliance architectures.
United States
Federal cloud modernization mandates and SEC cybersecurity disclosure rules drive enterprise procurement of real-time operational intelligence platforms. NIST SP 800-53 controls require immutable logging for audit readiness among publicly traded firms. Financial services clusters in New York and Chicago anchor largest contract values for hybrid telemetry solutions.
Germany
Automotive manufacturers and industrial conglomerates demand sovereign data processing for operational telemetry. EU AI Act high-risk system classifications compel algorithmic impact assessments before autonomous incident response deployment. Munich and Stuttgart engineering hubs lead procurement for explainable AI monitoring layers.
United Kingdom
Financial services operational resilience regulations and Bank of England supervisory expectations accelerate platform consolidation. FCA guidelines on operational continuity push trading infrastructure toward sub-second anomaly detection. London fintech density generates mid-market SaaS observability growth fastest among European capitals.
India
Digital public infrastructure scale creates massive operational data volumes with limited incumbent analytics vendor presence. RBI guidelines on payment system oversight mandate continuous monitoring across unified payments interface rails. Bengaluru and Hyderabad IT services exporters expand multi-tenant platform operations for global client bases.
Japan
Telecommunications operators managing 5G core complexity drive network analytics procurement at premium pricing tiers. METI industrial data governance frameworks encourage domestic cloud adoption for manufacturing telemetry. Tokyo and Osaka financial centers balance legacy mainframe integration with cloud-native observability migration timelines.
IT Operation Analytics (ITOA) Software Market Competitive Landscape
Concentration sits with platform consolidators and specialized observability pure-plays rather than fragmented point-solution vendors. The vendor landscape organizes around three strategic archetypes: data-to-everything platform operators, mainframe-to-cloud integration specialists, and causal AI engine developers. M&A activity targets telemetry data ingestion capabilities, while strategic partnerships focus on OpenTelemetry standardization and multi-cloud normalization layers.
Within the platform consolidator tier, Splunk Inc. and IBM Corporation exemplify divergent architectural bets on unified data fabrics versus legacy infrastructure bridging. Dynatrace LLC occupies a position among causal AI specialists leveraging automated root-cause analysis against rules-based alternatives. These three anchors represent distinct competitive vectors: data platform breadth, regulated industry integration depth, and algorithmic explainability specialization.
| Leading Market Players |
|---|
| Splunk Inc. |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| BMC Software, Inc. |
| Cisco Systems, Inc. |
| Dynatrace LLC |
| ServiceNow, Inc. |
| Broadcom Inc. |
| Others |
Supply & Pricing Matrix
Elastic consumption models at hyperscale cloud providers compress unit economics for telemetry ingestion, concentrating pricing power among vendors with native multi-tenant architectures while forcing on-premises specialists toward managed service wrappers to defend margin floors.
Pricing Analysis
Volume-discount tiering structures separate enterprise consumption bands from mid-market SaaS tiers, with data ingestion rates and retention periods as the primary differentiation levers. Pricing stratifies across premium enterprise suites with FedRAMP certification, standard cloud-native offerings, and economy-tier observability pipelines for resource-constrained buyers. Cost compression in the economy tier is intensifying because OpenTelemetry standardization enables workload portability between vendors. Mid-market enterprises with hybrid footprints exhibit highest price sensitivity, while financial services firms with SEC disclosure mandates demonstrate lowest elasticity due to compliance-driven procurement.
Supply Chain Analysis
The United States anchors hyperscale cloud infrastructure for telemetry processing, while Ireland and Singapore concentrate regional data residency hubs for GDPR and APAC compliance requirements. Software supply chains draw from open-source instrumentation libraries, proprietary AI model training clusters, and third-party cloud compute reservations. Single-source vulnerability concentrates in foundational machine learning frameworks maintained by narrow contributor bases. Distribution runs through direct enterprise sales teams for large contracts and self-service marketplaces for developer-led adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITOA software demand tracks enterprise cloud migration cycles, with federal modernization mandates and EU regulatory deadlines sustaining procurement momentum through the current technology investment upswing.
For Market Incumbents: Fortify platform consolidation advantages by embedding explainable AI documentation layers that satisfy EU AI Act transparency requirements before competitors achieve certification. Deepen vertical integration into mainframe telemetry agents to capture legacy financial services migrations. Defend against OpenTelemetry-driven commoditization by investing in proprietary causal analysis engines that resist standardization. For New Entrants and Emerging Players: Differentiate on algorithmic explainability specialization for regulated European manufacturers and energy utilities facing high-risk system classifications. Target India's digital public infrastructure expansion, where unified payments interface oversight requirements outpace incumbent vendor presence. Pursue channel partnerships with managed service providers in Spain and Italy to circumvent direct sales capability gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors telemetry data ingestion specialists with OpenTelemetry-native architectures over legacy agent-dependent platforms. Long-term viability hinges on regulatory compliance automation capabilities as audit documentation mandates proliferate across jurisdictions. Acquisition targets should demonstrate embedded explainability frameworks and multi-cloud normalization layers. Watch hyperscaler observability bundling announcements as the critical inflection signal for standalone vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies security and observability telemetry to address CISO-CIO alignment pressures in Basel III-regulated banks. |
| Acquisition of Specialist Firm | Captures OpenTelemetry-native ingestion capabilities that resist hyperscaler bundling and sustain pricing autonomy. |
| Strategic Partnership | Links observability platforms with EU Green Deal carbon reporting tools for CSRD-mandated sustainability dashboards. |
| Product Launch | Introduces explainable AI incident response modules that satisfy German automotive manufacturer audit requirements. |
| Geographic Expansion | Establishes India data residency infrastructure to capture RBI-mandated payment system monitoring procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC cybersecurity disclosure filings, hyperscaler capex disclosures, EU regulatory impact assessments, and industry vertical procurement databases. Conversations with platform engineering directors, CISOs at financial services firms, IT procurement officers, and managed service provider executives informed demand-side validation. Supply-side perspectives derived from vendor product strategy leads and channel partner interviews. Bottom-up deployment model adoption rates triangulated against top-down enterprise IT spending forecasts across the analysis window.
Segmentation dimensions modeled include deployment architecture, organizational scale tier, solution functional category, and regional regulatory compliance intensity. CAGRs derived from elasticity-adjusted pricing trajectories and replacement cycle acceleration patterns in cloud-native versus legacy environments. Forecast inputs incorporated EU AI Act implementation timelines and SEC disclosure rule enforcement phases throughout the projection horizon.
Material uncertainties — regulatory timeline delays, hyperscaler bundling acceleration, and talent scarcity constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding OpenTelemetry standardization velocity and sovereign data residency law proliferation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
APAC Location Analytics Market
Analytics
Global System Monitoring Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Video Analytics Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Italy Geospatial Analytics Market
Analytics
Dark Analytics Market
Analytics
Automated Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Global People and HR Analytics Software Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Global Graph Analytics Market
Analytics
North America HR Analytics Market
Analytics
Mobile Analytics Market
Analytics
Predictive Analytics Market