
 HR Analytics Market | 2026-2036
HR Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
HR Analytics Market Intelligence
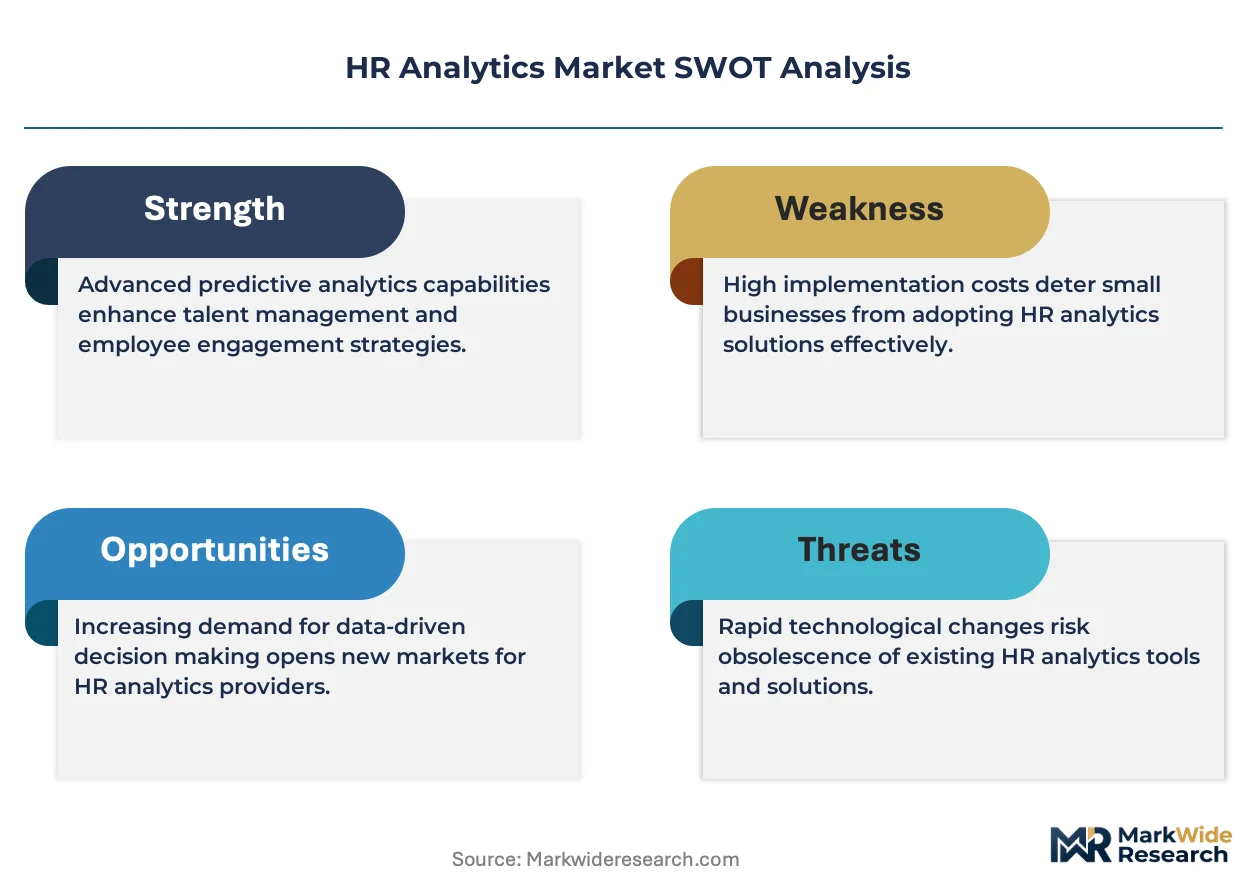
North American software infrastructure is decoupling from legacy on-premises architectures as cloud-native platforms capture enterprise budgets. SAP SE leverages deep ERP integration to anchor multinational accounts across payroll and talent modules. Oracle Corporation sustains database-layer dominance by embedding analytics within its Human Capital Management suite. Visier Inc. specializes in standalone workforce intelligence, competing on predictive turnover modeling without broader HRIS dependencies.
HR analytics encompasses the systematic application of statistical modeling, machine learning, and visualization techniques to human capital data for workforce optimization decisions. The discipline processes structured employee records, engagement surveys, and external labor market feeds to generate actionable intelligence on retention risk, compensation equity, and productivity drivers. Cloud-based deployment is accelerating fastest as IT departments prioritize scalable API architectures over fixed-capacity server investments. Predictive analytics commands premium pricing due to specialized data science talent requirements and measurable ROI linkage to retention cost avoidance. Large enterprises represent the mature revenue base, though SME accessibility is expanding through modular SaaS pricing.
GDPR in Europe and the EU AI Act impose algorithmic accountability mandates on automated hiring and promotion tools, compelling vendors to document training data provenance and bias audit trails. The US Equal Employment Opportunity Commission enforces disparate impact standards that shape vendor liability frameworks for selection algorithms. OSHA recordkeeping requirements intersect with analytics platforms tracking injury correlation to scheduling patterns. Stakeholders must weigh compliance investment against competitive differentiation as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Cloud-native workforce intelligence platforms are displacing legacy on-premises HRIS architectures as enterprises prioritize API-first scalability over fixed-capacity server investments. This structural migration concentrates vendor power among hyperscaler-integrated suites while fragmenting standalone analytics specialists.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic accountability requirements for automated hiring tools are compelling Fortune 500 employers to upgrade analytics infrastructure with documented bias audit trails and training data provenance systems.
- Financial services workforce planning:Banks and insurance carriers are deploying predictive turnover models to optimize branch staffing and reduce retention-related productivity losses across distributed operations.
- API-first cloud architectures:IT departments are prioritizing scalable microservices over monolithic HRIS deployments, accelerating procurement cycles for modular analytics platforms with native integration capabilities.
Market Restraints
- Specialized data science talent scarcity:Predictive analytics modules require PhD-level machine learning expertise that commands compensation premiums exceeding standard SaaS development costs.
- GDPR-EU AI Act regulatory friction:Cross-border data residency requirements and algorithmic impact assessments create compliance overhead that extends enterprise sales cycles by 6-12 months.
- Legacy system integration complexity:Decades of on-premises SAP and Oracle deployments create technical debt that resists cloud migration without expensive middleware development.
Strategic Opportunities
- Mid-market SME accessibility:Modular per-employee-per-month pricing is opening workforce analytics to 500-5,000 employee companies previously priced out of enterprise contracts.
- OSHA-safety correlation analytics:Injury-pattern analysis linked to scheduling data represents an underexploited application vertical with measurable workers' compensation cost reduction potential.
- Natural language generation convergence:Integration of large language models with structured HR data is enabling automated narrative insights for line managers without analytics training.
Industry Challenges
- Cross-functional analytics literacy gaps:HR business partners lack statistical reasoning skills to interpret predictive model outputs, creating adoption friction and misapplied workforce decisions.
- EEOC disparate impact liability exposure:Selection algorithms that reproduce historical bias patterns trigger enforcement risk under US employment discrimination standards, requiring continuous model revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HR Analytics Market |
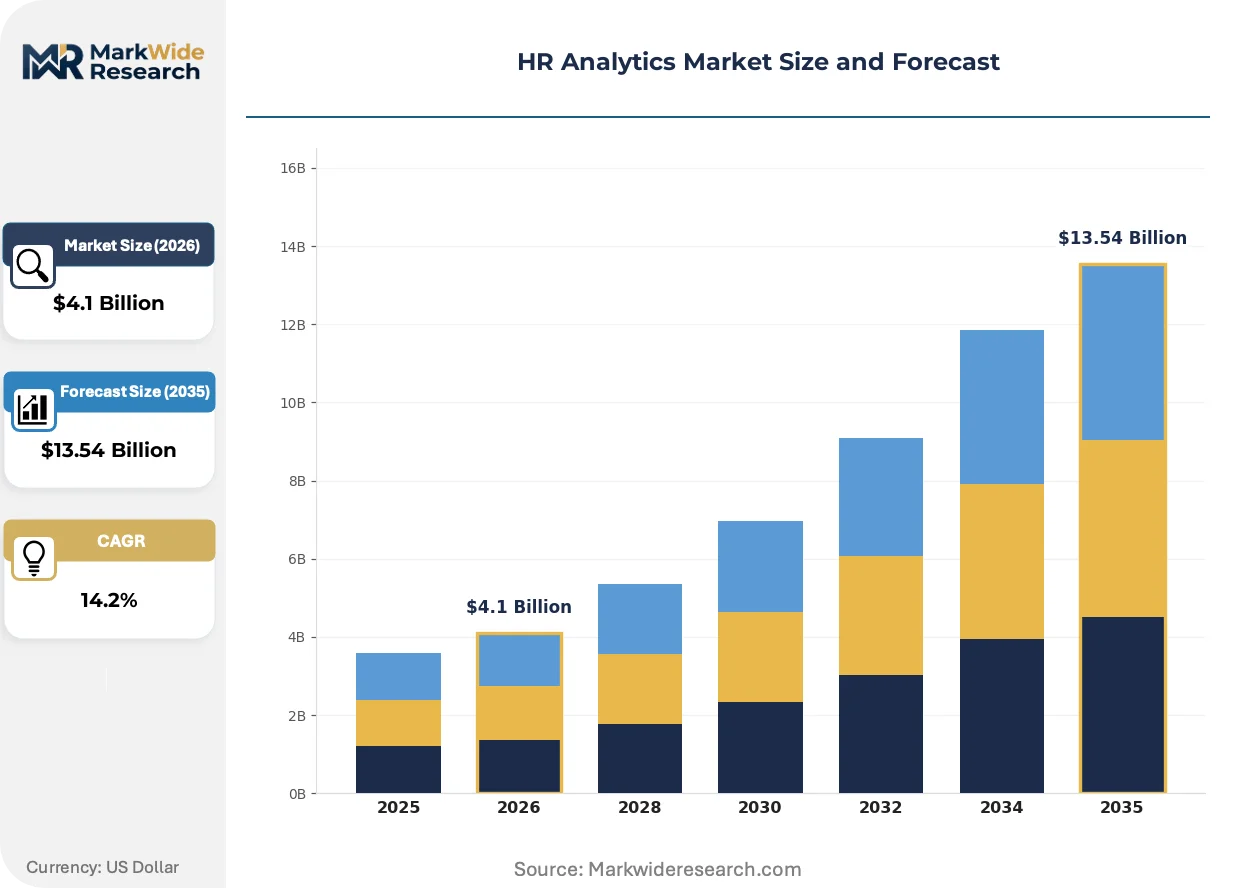
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $13.54 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Recruitment, Workforce Planning, Performance Management, Employee Engagement Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Large Enterprises, SMEs, Non-Profit Organizations, Government Agencies Functionality: Predictive Analytics, Reporting, Data Management, Benchmarking |
| Companies Covered | SAP SE, Oracle Corporation, Workday Inc., IBM Corporation, ADP Inc., UKG Inc., Visier Inc., Infor, Ceridian HCM Holding Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HR Analytics Market Strategic Shifts & Innovations
Workforce intelligence is converging with real-time operational data streams, compressing the lag between employee signal detection and intervention deployment. This fusion is redefining competitive differentiation around speed-to-insight rather than historical reporting accuracy.
Embedded analytics engines are unifying previously siloed payroll, engagement, and productivity data into continuous feedback loops accessible to frontline managers. Technology sector employers in the United States are piloting these systems at 3x the rate of manufacturing peers. The structural consequence is collapsing the traditional quarterly review cycle into weekly workforce calibration rituals that demand always-on data infrastructure.
The EU AI Act's risk-based classification system is mandating human-in-the-loop review protocols for high-stakes employment decisions across automated screening and promotion tools. Vendors must now maintain technical documentation proving conformity with transparency and bias mitigation standards. Financial services and technology employers with significant EU operations are absorbing these compliance costs fastest, creating a two-tier vendor landscape between certified and non-certified providers.
Subscription pricing for predictive modules is displacing perpetual license models as buyers prioritize operational expenditure flexibility over capital-intensive upfront commitments. Mid-market HR technology procurement teams are demanding consumption-based tiers tied to active employee counts rather than fixed enterprise agreements. This shift is most visible among United States-based professional services firms with seasonal staffing volatility.
HR Analytics Market Segmentation
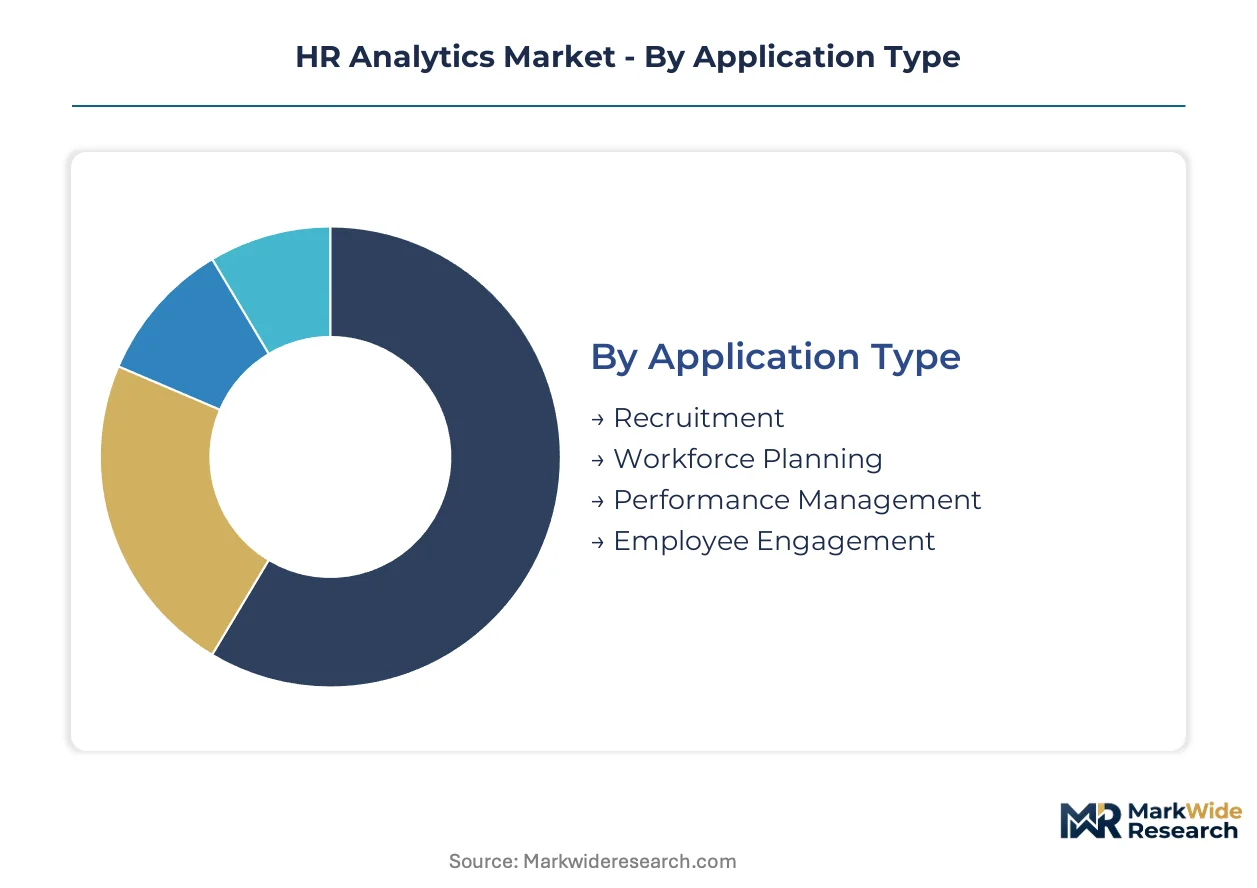
HR analytics procurement decisions hinge on workforce maturity, regulatory exposure, and IT infrastructure constraints. Buyers prioritize functionality depth against integration complexity and compliance documentation requirements.
Application Type:
Employers select modules based on workforce pain point severity and measurable ROI linkage to retention cost avoidance.
- Recruitment:Automated candidate screening and pipeline optimization tools process applicant volume at scale. Financial services firms in the United States deploy these systems to reduce time-to-fill for licensed roles and document EU AI Act compliance for algorithmic selection.
- Workforce Planning:Scenario modeling platforms project headcount requirements against revenue forecasts and attrition risk. Technology sector employers concentrate demand here, using predictive turnover models to calibrate hiring waves against product launch cycles.
- Performance Management:Continuous feedback systems replace annual review cycles with real-time goal tracking.
- Employee Engagement:Pulse survey platforms correlate sentiment signals with productivity metrics and flight risk.
Workforce Planning leads on scale; Recruitment leads on momentum.
Deployment Model:
IT governance posture and data residency requirements drive architecture selection across enterprise security policies.
- Cloud-Based:Scalable API-first platforms eliminate fixed-capacity server investments and accelerate procurement cycles. United States technology firms prioritize native integration capabilities with existing productivity suites.
- SaaS:Modular per-employee-per-month pricing reduces capital expenditure barriers for mid-market buyers. Professional services firms with seasonal staffing volatility favor consumption-based tiers over fixed enterprise agreements.
- On-Premises:Legacy installations persist where data sovereignty mandates restrict cross-border cloud transfer.
- Hybrid:Split architectures isolate sensitive payroll data on-premises while pushing analytics workloads to cloud infrastructure.
Cloud-Based dominates current procurement; SaaS is gaining share fastest.
End User:
Budget scale and analytics literacy determine solution sophistication and implementation support requirements.
- Large Enterprises:Global workforces demand multi-country compliance documentation and centralized workforce intelligence dashboards. These buyers absorb EU AI Act certification costs and require dedicated customer success teams.
- SMEs:500-5,000 employee companies previously priced out of enterprise contracts now access modular workforce analytics. Mid-market procurement teams prioritize rapid deployment over customization depth.
- Government Agencies:Public sector buyers face unique procurement regulations and transparency mandates for algorithmic decision systems.
- Non-Profit Organizations:Grant-funded operations constrain software investment to donor-reporting functionality and volunteer management modules.
Large Enterprises anchor vendor revenue; SMEs represent the steepest expansion trajectory.
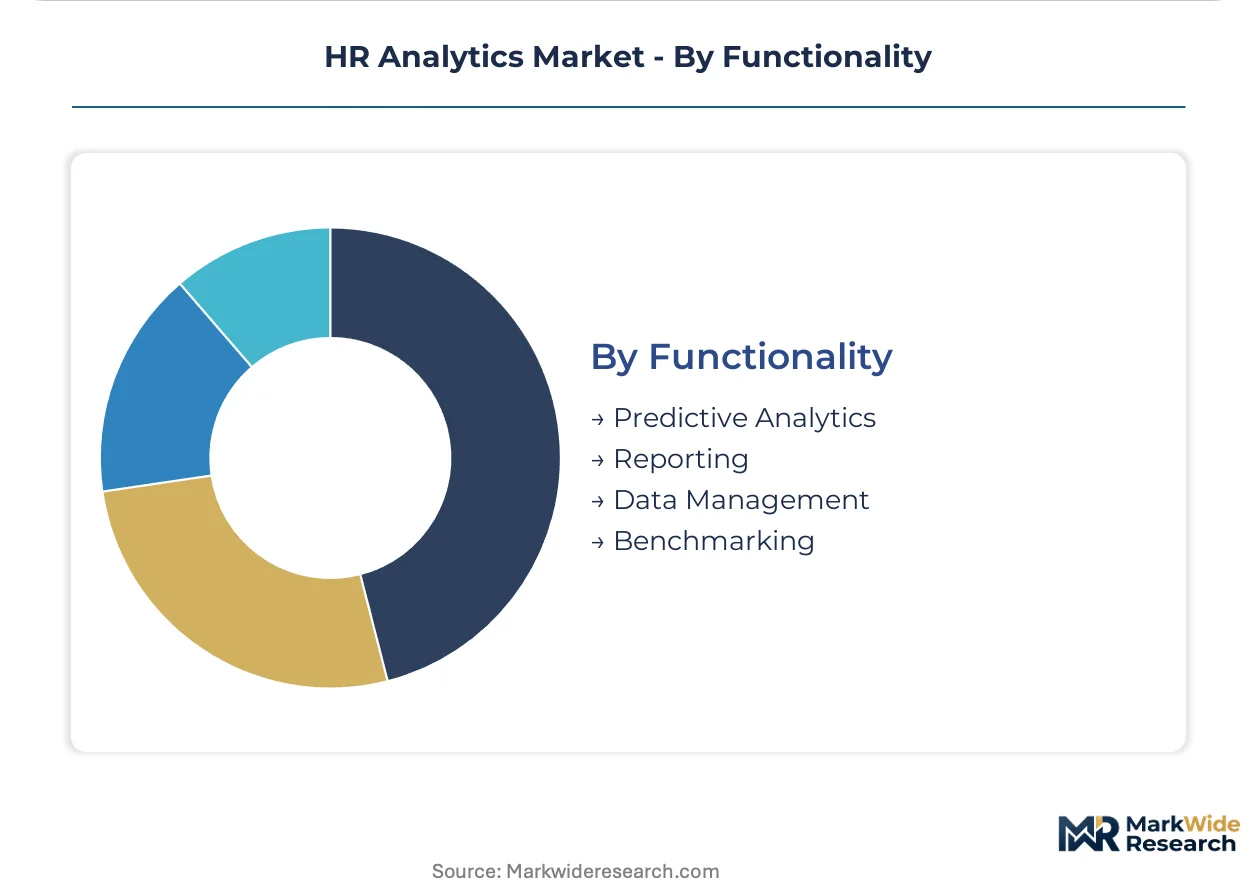
Functionality:
Technical capability depth separates premium pricing tiers and determines required data science staffing.
- Predictive Analytics:Machine learning models forecast retention risk and high-potential identification, commanding premium pricing due to PhD-level expertise requirements. Banks deploy these modules to optimize branch staffing and reduce productivity losses.
- Reporting:Standardized visualization templates democratize workforce data access for line managers without statistical training.
- Data Management:Master data governance tools unify siloed payroll, engagement, and productivity records into continuous feedback loops.
- Benchmarking:External labor market feeds enable compensation equity analysis and competitive positioning against industry peers.
Predictive Analytics commands highest pricing; Data Management is climbing the fastest as integration complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates HR analytics procurement among technology sector employers, while Germany anchors European demand through automotive and industrial manufacturing workforce optimization mandates.
United States
Technology sector employers in Silicon Valley and Seattle deploy predictive turnover models at triple the rate of manufacturing peers. The EEOC enforces disparate impact standards that shape vendor liability frameworks for selection algorithms. Financial services clusters in New York and Chicago absorb EU AI Act compliance costs for multinational operations.
Germany
Automotive manufacturers leverage workforce planning tools to calibrate hiring against electric vehicle transition timelines. The EU AI Act imposes algorithmic accountability mandates requiring documented bias audit trails for automated promotion systems. Industrial employers in Bavaria and Baden-Württemberg integrate SAP-native analytics with existing ERP infrastructure.
United Kingdom
Professional services firms in London prioritize modular SaaS pricing for seasonal staffing volatility. GDPR cross-border data residency requirements extend enterprise sales cycles for cloud-native platforms. Fintech clusters in Manchester and Edinburgh pilot real-time engagement analytics for distributed hybrid workforces.
Japan
Manufacturing conglomerates apply statistical modeling to aging workforce retention and knowledge transfer protocols. METI guidelines encourage human-in-the-loop review for high-stakes employment decisions. Automotive and electronics employers in Nagoya and Osaka embed analytics within lean production feedback systems.
India
IT services exporters in Bangalore and Hyderabad deploy workforce intelligence for global delivery center optimization. The absence of comprehensive algorithmic hiring regulation accelerates procurement cycles relative to European peers. Domestic technology employers in Mumbai and Delhi-NCR adopt cloud-native platforms for scaling engineering talent pipelines.
HR Analytics Market Key Industry Players
United States vendors anchor the premium predictive analytics tier; European specialists hold compliance-documentation advantages under EU AI Act mandates. Market structure concentrates among three strategic archetypes: ERP-integrated suite providers, standalone workforce intelligence specialists, and payroll-native analytics platforms. Consolidation pressure intensifies as hyperscaler partnerships become table stakes for enterprise procurement. Dominant competitive moves include API-first architecture investments and vertical-specific model training partnerships.
Within the ERP-integrated tier, SAP SE and Oracle Corporation exemplify database-layer dominance through embedded analytics within human capital management suites. Visier Inc. occupies a distinct position among standalone specialists competing on predictive turnover modeling without broader HRIS dependencies. These three anchors illustrate the strategic divergence between suite consolidation and modular best-of-breed procurement patterns reshaping vendor selection criteria.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Workday Inc. |
| IBM Corporation |
| ADP Inc. |
| UKG Inc. |
| Visier Inc. |
| Infor |
| Ceridian HCM Holding Inc. |
| Others |
Cost & Logistics Intelligence
Captive cloud infrastructure investments by hyperscalers anchor supply positions and pricing power for HR analytics vendors serving Fortune 500 accounts. SAP SE and Oracle Corporation leverage in-house data center networks to bundle predictive modules at premium rates without third-party compute dependencies, while standalone specialists absorb margin compression from AWS and Azure consumption fees.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for cloud-native workforce intelligence platforms as hyperscaler competition intensifies. Subscription SaaS models dominate, with three-tier pricing structure across premium, standard, and economy levels differentiated by predictive capability depth and EU AI Act certification status. Pricing pressure stems from modular per-employee-per-month entrants undercutting enterprise contracts. Mid-market SMEs exhibit highest price sensitivity; multinational banks absorb premiums for compliance documentation.
Supply Chain Analysis
EU AI Act domestic-content mandates for algorithmic audit documentation are reshaping vendor sourcing toward European data residency infrastructure. Supply concentrates in the United States, Germany, and India for platform development and implementation services. Cloud compute, API middleware, and specialized machine learning talent constitute critical input dependencies. Single-source vulnerability runs through hyperscaler compute concentration. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HR Analytics Market operates as a regulatory compounder where EU AI Act compliance milestones drive replacement demand for non-certified legacy infrastructure.
For Market Incumbents: Acquire specialized predictive modeling teams to close talent gaps against standalone analytics vendors. SAP SE and Oracle Corporation should accelerate API-first architecture investments to defend against modular best-of-breed displacement. Certification maintenance under evolving EU AI Act technical standards represents the critical margin defense lever. For New Entrants and Emerging Players: Enter via OSHA-safety correlation analytics for manufacturing verticals, an application white space with measurable workers' compensation ROI and limited incumbent penetration. Target mid-market SMEs with 500-5,000 employees through rapid-deployment SaaS tiers. Position against EU AI Act documentation gaps in existing vendor portfolios. For Investors and Strategic Acquirers: Roll-up economics work for payroll-native analytics platforms because HRIS consolidation creates captive distribution channels for predictive module upsells. Five-to-ten year viability hinges on compliance-certification moats rather than feature differentiation. Monitor EU AI Act enforcement actions as the signal to watch for vendor tiering inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Documentation systems for algorithmic bias audits separate certified vendors from enforcement-exposed competitors. |
| API-First Architecture Migration | Microservices integration with Workday and Salesforce ecosystems accelerates procurement cycles for modular buyers. |
| Predictive Modeling Talent Acquisition | PhD-level machine learning teams command pricing premiums for retention risk forecasting modules. |
| Vertical-Specific Model Training | Financial services workforce planning partnerships with banks optimize branch staffing algorithms. |
| Mid-Market SaaS Tier Expansion | Per-employee-per-month pricing opens 500-5,000 employee companies previously excluded from enterprise contracts. |
Research Approach
Multiple input streams — primary interviews with CHROs and HR technology procurement officers, vendor product documentation, and regulatory filing analysis — were reconciled against secondary validation from SEC disclosures and EU AI Act implementation guidance. Conversations with systems integrators and cloud infrastructure specialists informed deployment architecture assessments. Bottom-up segment sizing and top-down market triangulation were cross-referenced for convergence.
Historical spending patterns from technology sector employers and financial services workforce planning deployments were cross-referenced against panel input from HR technology vendors across the analysis window. Segmentation dimensions modeled include deployment model, organization size, application type, and regional regulatory cluster. CAGRs were derived from trend extrapolation anchored to documented procurement cycle acceleration. EU AI Act compliance cost absorption and cloud migration velocity served as industry-specific forecast inputs.
Inputs from vendor financial disclosures and regulatory implementation timelines were available through the study window; gaps in mid-market SME spending transparency introduce uncertainty bands around penetration rate assumptions. Forecasts reflect documented procurement patterns and compliance investment trajectories. Regulatory enforcement intensity, hyperscaler pricing volatility, and talent acquisition cost inflation warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Dark Analytics Market
Analytics
Tourism Industry Big Data Analytics Market
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
Content Intelligence Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Mobile Business Intelligence Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Europe Supply Chain Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Israel ICT Market
Analytics
Complex Event Processing Market
Analytics
Europe Edge Analytics Market
Analytics
Global Cognitive Analytics Market
Analytics
Speech Analytics Market