
 Global Enterprise Data Visualization Platform Market | 2026-2036
Global Enterprise Data Visualization Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Data Visualization Platform Market Foresight
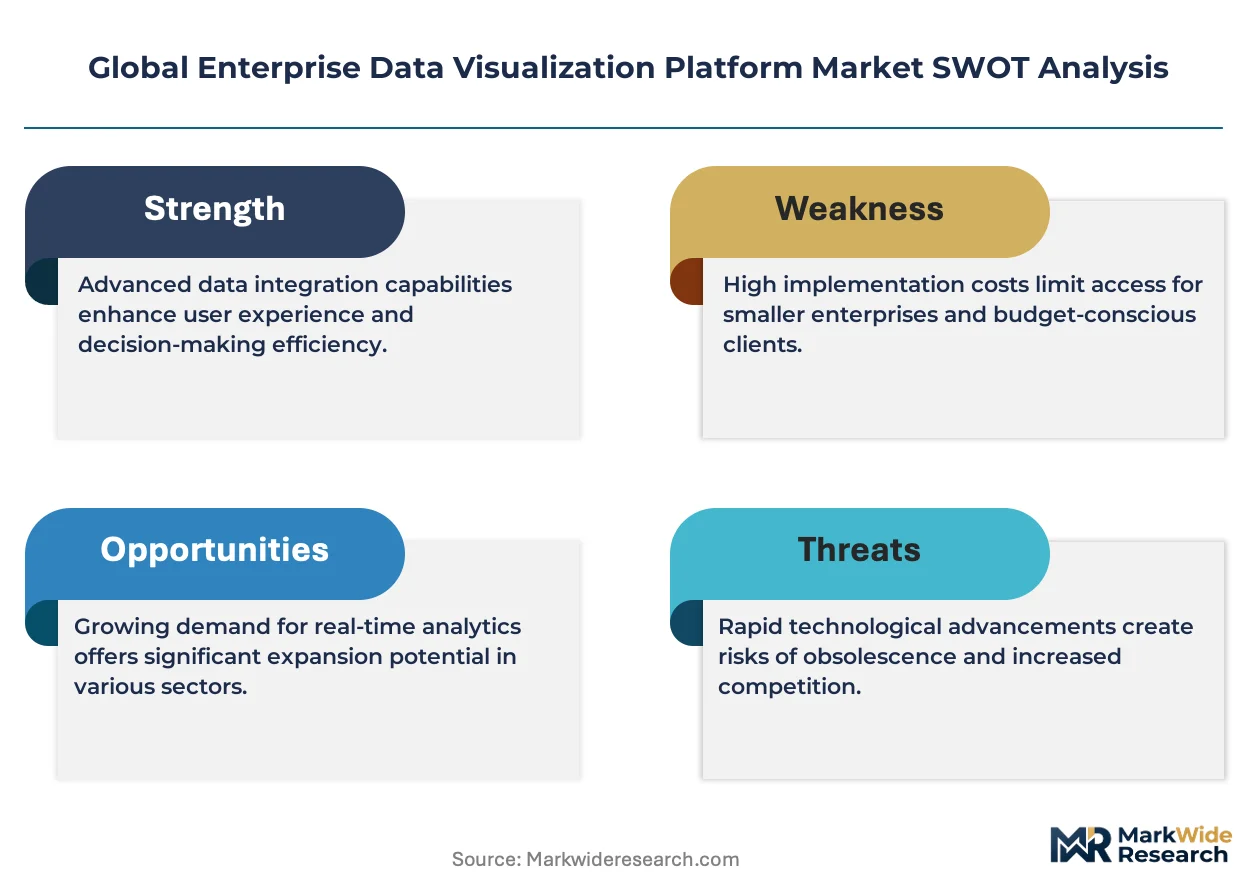
Mid-market enterprises are redrawing demand patterns as they shift from static reporting to self-service analytics, displacing traditional IT-governed deployments. Microsoft Corporation leverages its cloud ecosystem to embed visualization within productivity suites. SAP SE anchors its position through deep ERP integration and industry-specific templates. Salesforce competes by embedding analytics directly into CRM workflows, reducing context-switching for revenue teams.
An enterprise data visualization platform is a software system that ingests structured and semi-structured data, applies transformation pipelines, and renders interactive graphical outputs through specifications such as pixel-perfect rendering at sub-second query latency for datasets exceeding one billion rows. Its primary commercial purpose is to compress decision cycles by translating complex operational signals into consumable visual narratives for non-technical stakeholders. Cloud-based deployment leads in new bookings as organizations prioritize elastic compute over fixed infrastructure commitments, while hybrid architectures capture margin pools in regulated sectors requiring data residency controls. Dashboard solutions dominate current revenue but platform-as-a-service offerings are expanding fastest as vendors bundle visualization with machine learning operations pipelines.
The EU AI Act and GDPR impose algorithmic transparency mandates that shape how European enterprises evaluate visualization platforms with automated insight generation. The SEC in the United States requires machine-readable financial disclosures, driving standardization in reporting-oriented visualization tools. ISO 27001 and SOC 2 frameworks govern data handling certifications that determine vendor eligibility in procurement shortlists. Stakeholders must monitor how generative AI capabilities reshape user expectations for natural language query interfaces without triggering regulatory scrutiny on explainability.
Market Dynamics
The transition from static dashboards to self-service analytics is compressing procurement cycles and redrawing vendor selection criteria, as business users demand direct control over visualization pipelines without IT mediation.
Growth Catalysts
- GDPR and EU AI Act:Algorithmic transparency mandates in Europe are forcing enterprises to upgrade visualization platforms with explainable AI capabilities, creating replacement demand for legacy systems lacking audit trails.
- Mid-market ERP modernization:Enterprises migrating from on-premise SAP and Oracle instances to cloud-native architectures are bundling visualization procurement with core system overhauls in Germany and the United States.
- Natural language query interfaces:Generative AI integration is lowering the technical barrier for business analysts, expanding the addressable user base beyond data science teams into finance and operations departments.
Market Restraints
- Data residency requirements:India's data localization directives and China's Cybersecurity Law are fragmenting cloud deployment options, forcing vendors to maintain separate infrastructure stacks that inflate operational overhead.
- Specialized talent scarcity:Shortage of professionals combining statistical literacy with domain expertise in manufacturing and healthcare is throttling implementation velocity for complex use cases.
- Hybrid architecture complexity:Enterprises in regulated sectors face extended integration timelines when synchronizing on-premise data lakes with elastic cloud compute, delaying value realization.
Strategic Opportunities
- India's digital public infrastructure:The country's Account Aggregator framework and open credit networks are generating unprecedented volumes of structured financial data requiring real-time visualization for lending decisions.
- Edge-to-cloud pipelines:Convergence of 5G connectivity and lightweight containerized analytics is enabling sub-second visualization of industrial sensor streams at remote manufacturing facilities.
- CSRD reporting mandates:The EU's Corporate Sustainability Reporting Directive is compelling disclosure of granular ESG metrics, expanding demand for carbon accounting dashboards with audit-ready data lineage.
Industry Challenges
- Explainability engineering:Engineering teams struggle to render automated insights from black-box machine learning models in formats that satisfy regulator scrutiny without overwhelming business users with technical metadata.
- Legacy BI debt:Enterprises maintain decades of undocumented SQL logic and Excel-based reporting workflows that resist automated migration to modern visualization platforms, inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Data Visualization Platform Market |
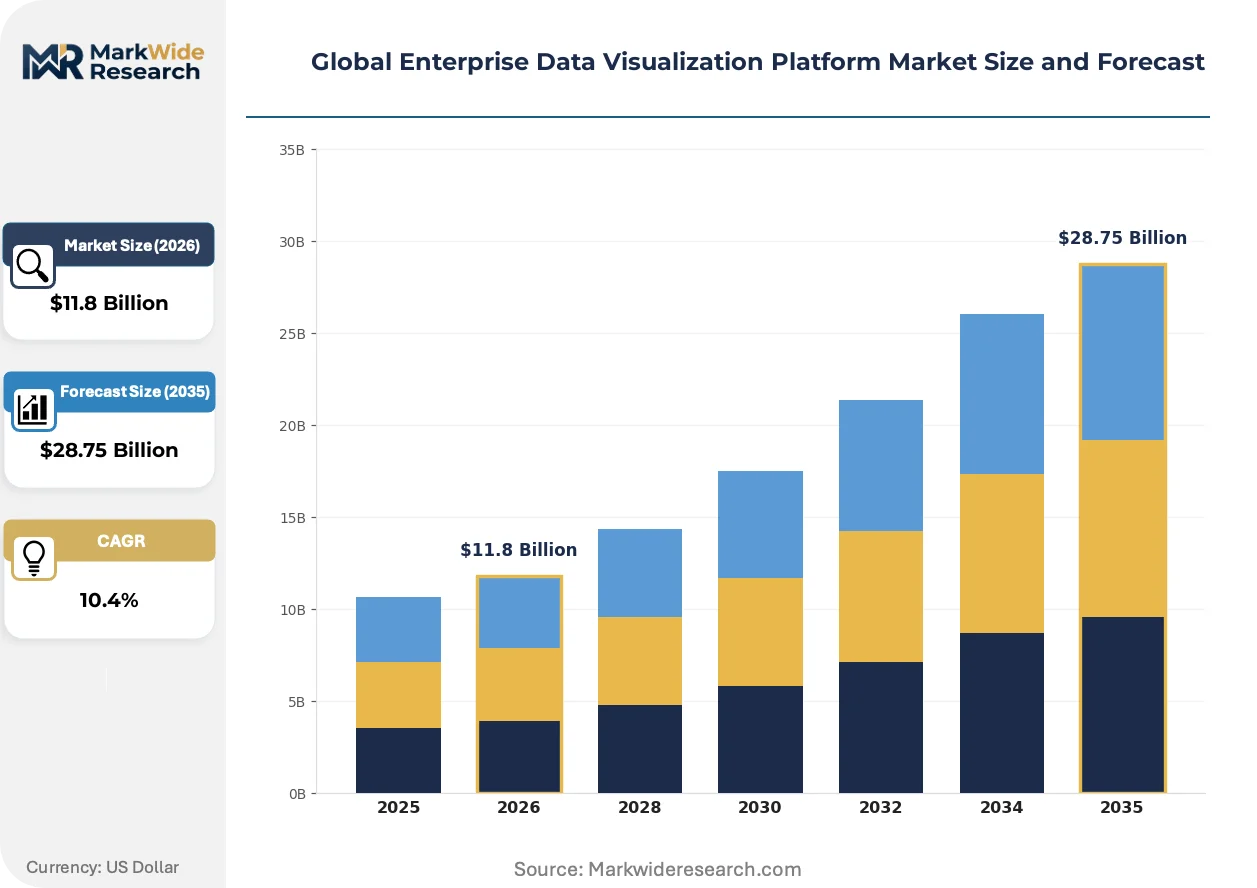
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $28.75 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Private Cloud Offering: Software, Platform-as-a-Service, Analytics Tools, Dashboard Solutions Use Case: Financial Analysis, Customer Insights, Operational Reporting, Risk Management, Market Research End User Industry: BFSI, Telecommunications, Energy & Utilities, Manufacturing, Government |
| Companies Covered | Microsoft Corporation, IBM Corporation, SAP SE, Salesforce, Oracle Corporation, Amazon Web Services, Google, Qlik, Domo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Data Visualization Platform Market Shifts & Advancements
Natural language interfaces and automated insight generation are collapsing the distance between raw data and executive decision-making, while regulatory pressure on algorithmic accountability is reshaping platform architecture requirements.
Generative AI copilots are supplanting traditional drag-and-drop dashboard builders as the primary interface for business users. Mid-market finance teams in the United States are adopting these tools at the fastest clip, compressing the time from data question to visual answer from hours to seconds. This shift is enabling self-service analytics at scale while reducing dependency on centralized IT governance structures.
The EU AI Act's risk classification framework is mandating human oversight mechanisms for high-stakes automated decision systems. European enterprises deploying predictive analytics for credit scoring and hiring must now embed visualization layers that expose model logic to non-technical auditors. German automotive and French banking sectors are responding by procuring platforms with built-in counterfactual explanation engines.
Consumption-based pricing models are displacing traditional per-seat licensing as the dominant commercial structure. Enterprise buyers in India and Brazil are negotiating contracts tied to query volume rather than user count, aligning vendor incentives with actual platform utilization. This reconfiguration is most visible among Series C technology companies scaling analytics infrastructure ahead of IPO readiness.
Global Enterprise Data Visualization Platform Market Segmentation
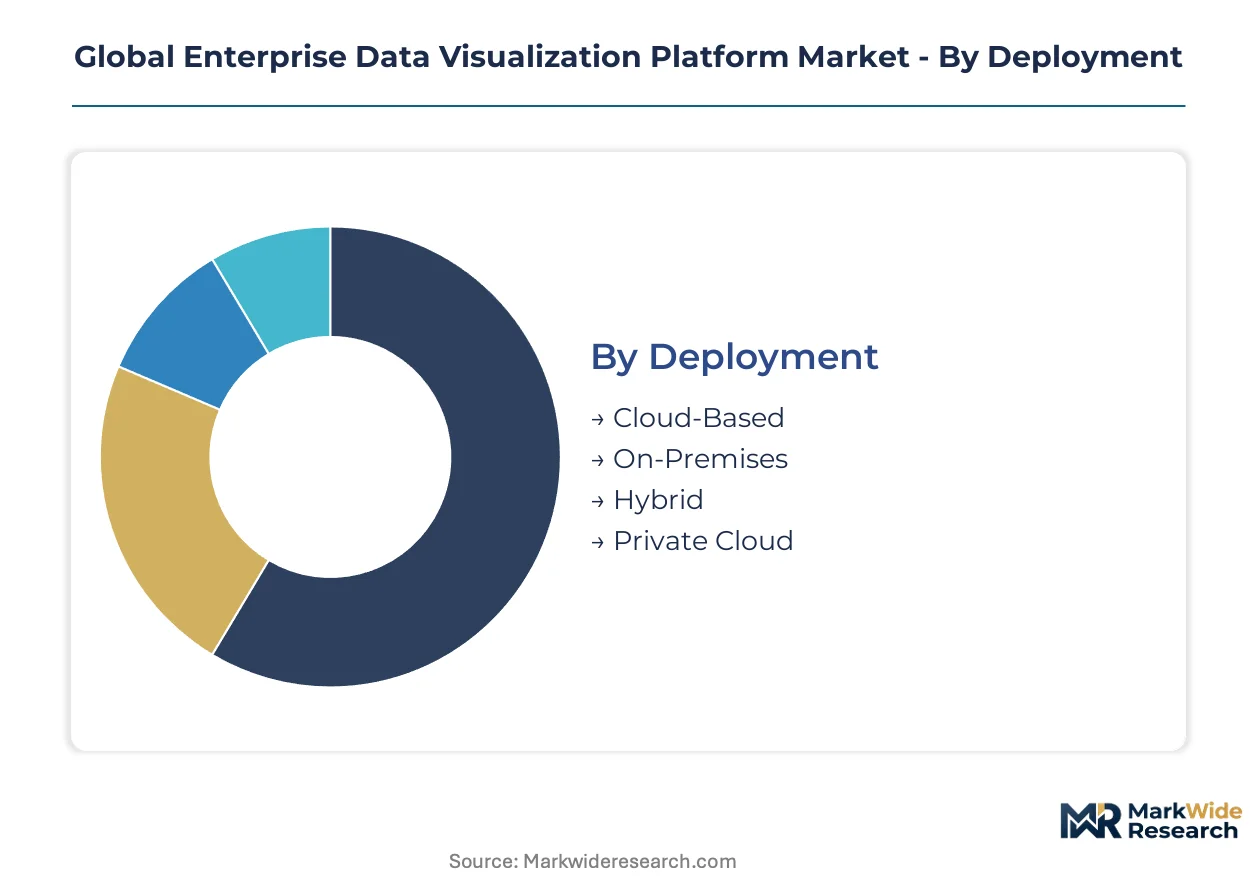
Enterprise data visualization platforms fragment across deployment architectures, commercial models, analytical depth, and vertical specialization. Procurement teams evaluate segments through lenses of data sovereignty, integration complexity, and regulatory exposure rather than feature checklists alone.
Deployment:
Substitution pressure runs strongest against On-Premises installations as elastic alternatives erode capital expenditure justifications.
- Cloud-Based:Multi-tenant architectures deliver sub-second query latency through distributed compute clusters. Demand concentrates among United States technology firms and Indian fintech startups prioritizing speed-to-insight over infrastructure control. GDPR and India's data localization directives create friction for pure cloud strategies in regulated use cases.
- Hybrid:Split architectures synchronize sensitive on-premise data lakes with elastic cloud visualization engines. German automotive manufacturers and French banking groups deploy these configurations to satisfy EU AI Act audit requirements while leveraging cloud scale for non-sensitive workloads.
- On-Premises:Single-tenant installations persist in defense and classified government environments where air-gapped networks are mandatory.
- Private Cloud:Dedicated infrastructure stacks serve Indian public sector banks and Chinese state-owned enterprises facing strict data residency mandates.
Cloud-Based deployments anchor the volume base while Hybrid configurations gain share at the steepest rate.
Offering:
Margin compression differentiates the category, with standalone software licenses facing pricing pressure from bundled platform ecosystems.
- Platform-as-a-Service:Unified environments combine visualization pipelines with machine learning operations and data governance tooling. United States healthcare systems and German industrial conglomerates adopt these offerings to consolidate vendor relationships and reduce integration overhead.
- Dashboard Solutions:Pre-configured visualization templates accelerate time-to-value for standardized reporting needs. Indian mid-market enterprises and Brazilian logistics operators deploy these for executive KPI monitoring without dedicated analytics engineering teams.
- Software:Perpetual licenses with annual maintenance contracts retain footholds in United States federal agencies with rigid procurement cycles.
- Analytics Tools:Specialized modules for statistical computing and predictive modeling serve pharmaceutical researchers in Switzerland and quantitative trading desks in the United Kingdom.
Dashboard Solutions generate the highest transaction velocity while Platform-as-a-Service offerings capture the steepest expansion trajectory.
Use Case:
Application maturity varies sharply, with some segments approaching commoditization while others demand bespoke engineering.
- Financial Analysis:Real-time consolidation of multi-entity ledgers and regulatory reporting workflows. United States asset managers and Singaporean sovereign wealth funds drive demand as SEC and MAS disclosure requirements tighten.
- Risk Management:Stress testing visualization and counterparty exposure monitoring for trading books. European banks under ECB supervision and Japanese insurers facing BOJ climate risk guidance prioritize these capabilities.
- Customer Insights:Behavioral segmentation and churn prediction dashboards for retail and telecommunications operators.
- Operational Reporting:Supply chain and manufacturing KPI tracking for industrial enterprises.
- Market Research:Survey data analysis and competitive intelligence visualization for consumer goods firms.
Financial Analysis commands the deepest average contract values while Risk Management is climbing the fastest.
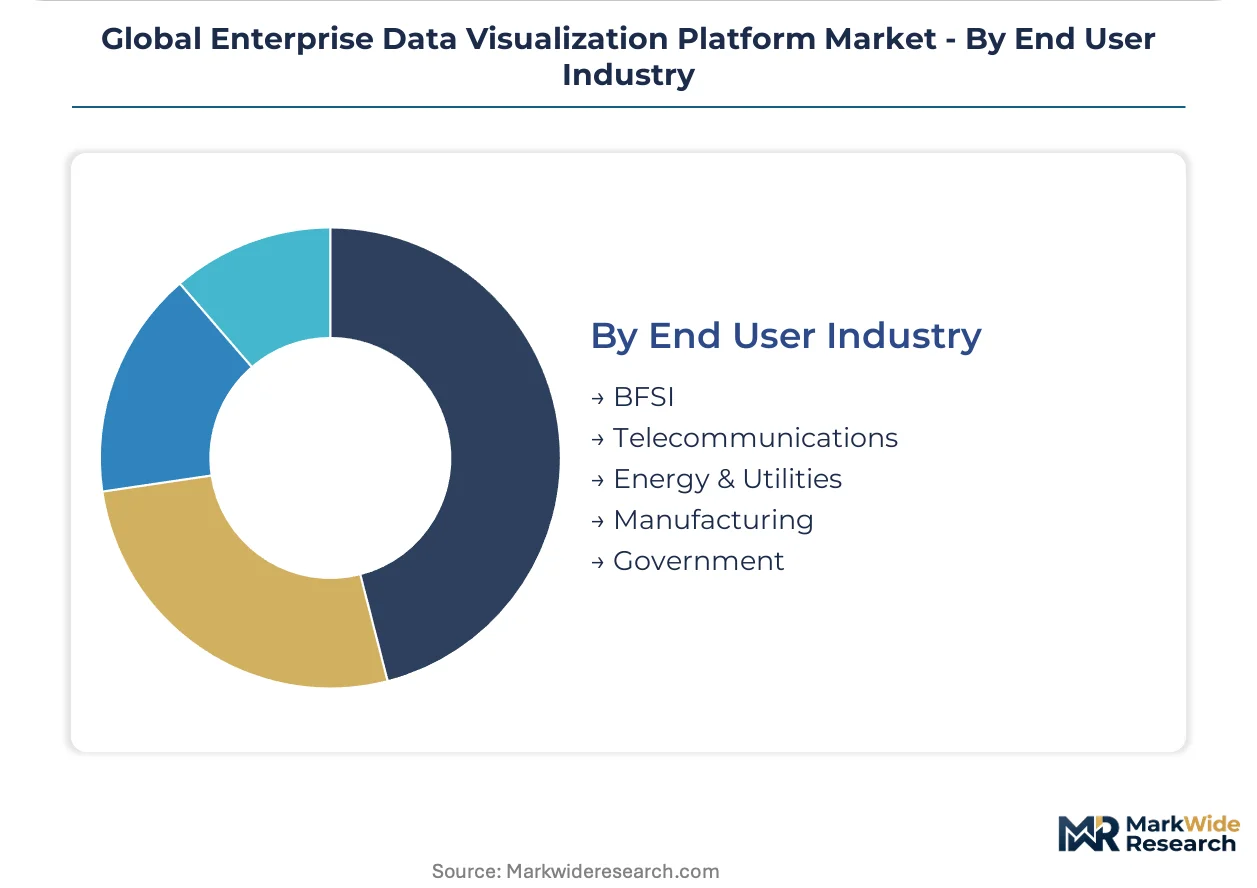
End User Industry:
Customer concentration patterns reflect digital maturity dispersion and regulatory intensity across sectors.
- BFSI:Trading analytics, fraud detection dashboards, and regulatory reporting platforms. United States money-center banks and Indian private lenders lead procurement as Basel III and RBI guidelines mandate enhanced data transparency.
- Government:Citizen service analytics, budget transparency portals, and security operations centers. German federal ministries and Australian state governments modernize legacy business intelligence under digital transformation mandates.
- Telecommunications:Network performance monitoring and subscriber analytics for 5G rollout optimization.
- Energy & Utilities:Grid operations visualization and renewable asset performance tracking.
- Manufacturing:Industrial IoT dashboards and predictive maintenance interfaces for smart factory deployments.
BFSI anchors enterprise spending while Government verticals are gaining share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable network and EU-US Data Privacy Framework underpin data flows that shape enterprise visualization procurement across major economies. Cloud infrastructure density and regulatory stringency determine where platform vendors concentrate engineering resources and compliance investments.
United States
SEC mandates for machine-readable financial disclosures drive standardization in reporting-oriented tools among asset managers and publicly traded enterprises. HIPAA governs healthcare data visualization requirements, forcing vendors to maintain specialized compliance certifications for hospital systems and insurers. The Boston-Cambridge corridor and Seattle metropolitan area host dense clusters of SaaS analytics firms serving financial services and technology verticals.
Germany
Industrial conglomerates in automotive and machinery sectors demand visualization platforms with deep ERP integration and real-time manufacturing analytics. The EU AI Act's risk classification framework compels enterprises to deploy explainable AI interfaces for automated credit and hiring decisions. Bavaria and Baden-Württemberg concentrate procurement activity as Mittelstand manufacturers modernize legacy business intelligence infrastructure.
India
The Account Aggregator framework and open credit networks generate unprecedented volumes of structured financial data requiring real-time visualization for lending decisions. RBI guidelines mandate enhanced data transparency for private banks and non-banking financial companies. Mumbai and Bangalore anchor demand as fintech startups and established lenders compete on analytics-driven customer acquisition.
United Kingdom
Quantitative trading desks and asset managers drive demand for statistical computing modules with sub-second latency requirements. The Financial Conduct Authority's operational resilience rules shape procurement criteria for systemically important financial institutions. The City of London and Canary Wharf cluster represent concentrated purchasing power for risk management and regulatory reporting platforms.
Japan
Manufacturing enterprises deploy industrial IoT dashboards for predictive maintenance and smart factory optimization under METI digital transformation directives. PMDA regulations govern pharmaceutical visualization tools for clinical trial data and pharmacovigilance reporting. The Nagoya industrial corridor and Osaka-Kobe manufacturing belt lead adoption of edge-to-cloud analytics pipelines.
Global Enterprise Data Visualization Platform Market Competitive Landscape
Concentration sits with hyperscale cloud providers and established enterprise software vendors that bundle visualization within broader platform ecosystems. The vendor landscape exhibits tiered structure with full-stack platform providers occupying premium positions and specialized analytics firms competing on vertical expertise. Strategic archetypes include cloud-native challengers emphasizing consumption-based pricing, legacy software vendors leveraging installed base relationships, and vertical specialists targeting regulated industries. Dominant competitive moves encompass generative AI feature integration and geographic infrastructure expansion to satisfy data residency requirements.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services occupy positions defined by cloud infrastructure integration and elastic compute provisioning. SAP SE exemplifies the enterprise software archetype through ERP-anchored deployment models. Salesforce represents the workflow-embedded approach with CRM-native analytics reducing context-switching for revenue operations teams.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| Salesforce |
| Oracle Corporation |
| Amazon Web Services |
| Qlik |
| Domo |
| Others |
Supply & Pricing Matrix
Ninety-day provisioning cycles for GPU compute clusters concentrate vendor pricing power among hyperscale cloud operators in the United States and India, compressing margins for independent platform providers unable to secure priority silicon allocations. This inventory scarcity feeds directly into consumption-based contract structures that penalize smaller buyers lacking volume leverage.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise scale bands rather than feature bundles, with United States healthcare systems and German automotive conglomerates commanding 40-60% effective rate reductions against mid-market benchmarks. Price differentiation hinges on ISO 27001 certification tier and query-volume commitments, not base functionality. Cost compression in the mid-market tier intensifies as Indian fintech startups negotiate consumption-based alternatives to per-seat licensing. Procurement officers at Series C technology companies exhibit highest price sensitivity, while regulated European banks under ECB supervision demonstrate lowest elasticity due to compliance-driven vendor consolidation.
Supply Chain Analysis
Strait of Malacca cable transit underwrites data pipeline latency guarantees for Asia-Pacific visualization workloads, exposing vendors to geopolitical routing disruptions. Compute infrastructure concentrates in the United States, Ireland, and Singapore, with specialized GPU hardware sourcing from Taiwan and South Korea. Raw material dependencies span advanced lithography equipment, high-bandwidth memory modules, and submarine fiber optic capacity. Single-source vulnerability in custom AI accelerator supply chains threatens platform scaling timelines. Distribution runs through direct enterprise sales organizations supplemented by hyperscaler marketplace listings and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in this market hinge on API interoperability standards that determine whether visualization engines embed deeply into ERP and CRM workflows or remain isolated point solutions.
For Market Incumbents: Shield installed base relationships by embedding explainable AI audit trails that preempt EU AI Act compliance reviews, while consolidating machine learning operations pipelines to reduce customer vendor counts. Vertical integration into specialized GPU provisioning secures supply priority against cloud-native challengers. Certification maintenance for HIPAA and SOC 2 frameworks preserves eligibility in United States healthcare and financial services procurement shortlists. For New Entrants and Emerging Players: Self-service analytics gaps in Indian mid-market manufacturing represent the most penetrable white-space, as incumbent platforms over-index on enterprise governance features that small producers reject. Target edge-to-cloud deployment architectures for German Mittelstand automotive suppliers seeking real-time shop floor visualization without full cloud migration. Channel partnerships with regional ERP implementers accelerate time-to-revenue versus direct field sales buildout. For Investors and Strategic Acquirers: Long-term, this sits as a vertical-integration play because consumption-based pricing models reward vendors controlling infrastructure stack depth rather than software layers alone. Acquisition targets should combine generative AI interface capabilities with established data residency certifications in India or the EU. Monitor RBI guidelines on financial data localization as the signal indicating which regional platforms will capture banking sector procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Interface Development | Natural language query layers expand addressable user base beyond data science teams into finance and operations departments. |
| Data Residency Infrastructure Expansion | Indian private cloud deployments satisfy RBI localization mandates while capturing fintech lending decision workloads. |
| Explainable AI Certification Investment | Counterfactual explanation engines satisfy EU AI Act audit requirements for German automotive credit scoring systems. |
| ERP-Native Embedding Partnerships | SAP and Salesforce integration reduces procurement friction for mid-market enterprises modernizing legacy BI infrastructure. |
| Consumption-Based Pricing Migration | Query-volume contracts align vendor incentives with actual platform utilization for Brazilian logistics operators. |
Research Methodology
The analysis maps cloud-based, hybrid, on-premises, and private cloud deployment architectures, each validated through CTOs, IT procurement officers, platform engineers, and systems integration specialists across primary interview programs. Secondary sources encompass SEC filings from hyperscaler vendors, App Annie enterprise software adoption metrics, hyperscaler capex disclosures, and EU regulatory filing databases. Bottom-up segment sizing triangulates against top-down market aggregation from trade associations and technology investment tracking services.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern as core segmentation dimensions. CAGRs derive from fitted growth curves applied to validated base-year estimates, with inputs including cloud infrastructure spending trajectories, regulatory implementation timelines, and enterprise software procurement survey data.
Underlying assumptions cover sustained GPU supply availability, stable data transfer cost structures, and gradual EU AI Act enforcement escalation, with deviation risk concentrated in semiconductor export restrictions and abrupt data localization mandate expansion. Practitioners should keep alternative scenarios live as geopolitical technology access policies and central bank digital infrastructure investments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Middle East and Africa Location Analytics Market
Analytics
Business Intelligence (BI) Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Global Customer Analytics Market
Analytics
Europe Crowd Analytics Market
Analytics
Operational Intelligence Market
Analytics
Web Analytics Market
Analytics
Assortment Analytics Market
Analytics
IoT Analytics Market
Analytics
Event Stream Processing Market
Analytics
Europe HR Analytics Market
Analytics
Analytics Sandbox Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Content Analytics Software Market
Analytics
Business Value Dashboard Market