
 Business Value Dashboard Market | 2026-2036
Business Value Dashboard Market Size, Share, and Industry Trends Forecast 2026-2036
Business Value Dashboard Market Outlook
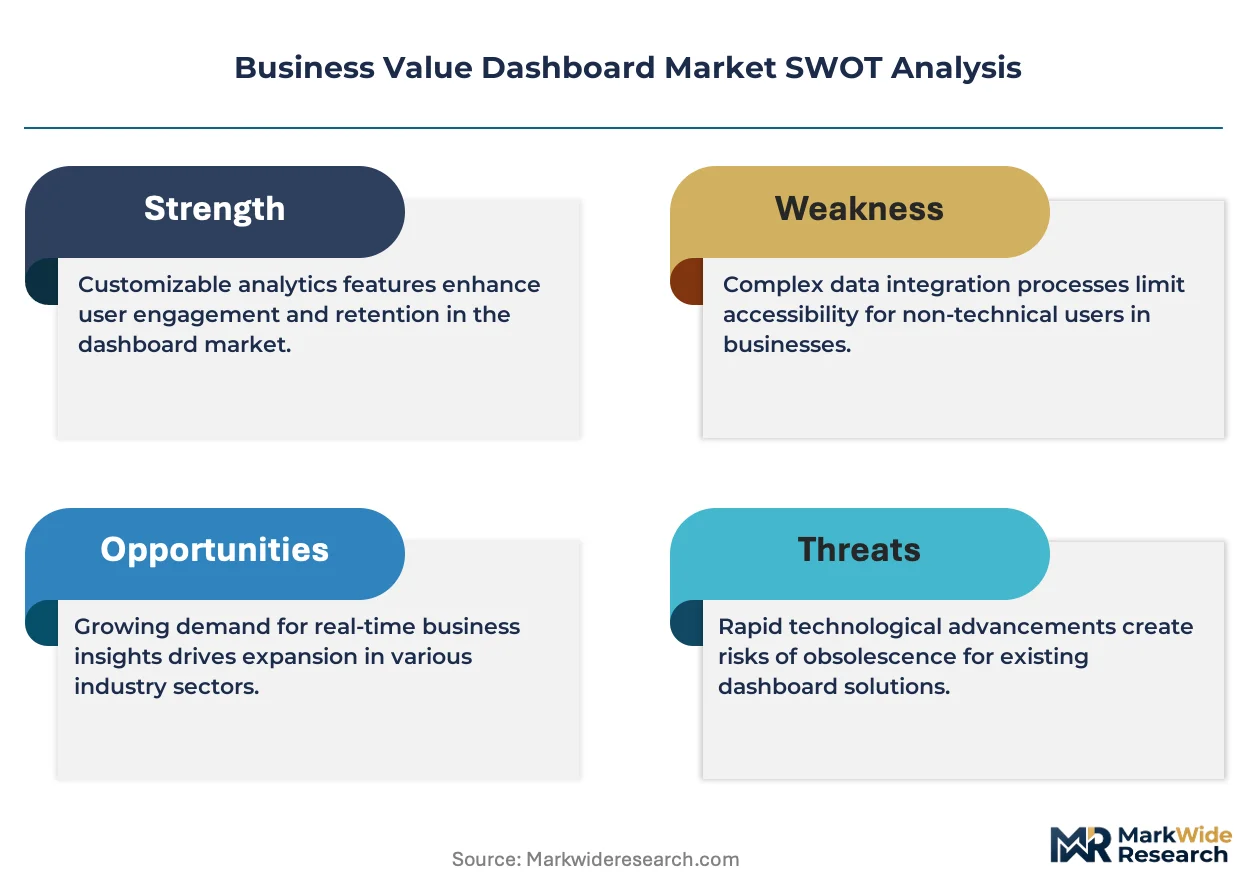
Subscription-based SaaS financing is narrowing the competitive field for capital-intensive on-premise incumbents. IBM Corporation leverages its hybrid cloud infrastructure to sustain enterprise relationships across regulated sectors. Salesforce.com anchors its position through native CRM integration with visual analytics layers. Tableau Software specializes in self-service visualization, competing against broader platform vendors by dominating the business-user segment.
A business value dashboard is a software interface that aggregates key performance indicators, financial metrics, and operational data into real-time visual displays, typically rendering data through interactive charts, scorecards, and drill-down matrices to support executive decision-making. Its primary commercial purpose is to translate disparate enterprise data streams into actionable intelligence for strategic planning and performance management. Cloud-based deployment leads segment growth as organizations prioritize elastic scalability and reduced IT overhead, while on-premise installations retain margin pools in sectors with stringent data residency requirements. Financial analysis functionality commands premium positioning among large enterprises, whereas visual analytics represents the fastest-expanding category as self-service tools proliferate across SMBs.
The EU AI Act, GDPR, and SEC disclosure rules collectively shape product roadmaps by mandating explainable algorithms, audit trails, and standardized ESG reporting interfaces. FDA 21 CFR Part 11 and HIPAA extend these requirements into healthcare deployments, forcing dashboard vendors to embed granular access controls and immutable data logs. Stakeholders must evaluate whether compliance investments will consolidate advantage among full-stack providers or create openings for specialized governance-native platforms.
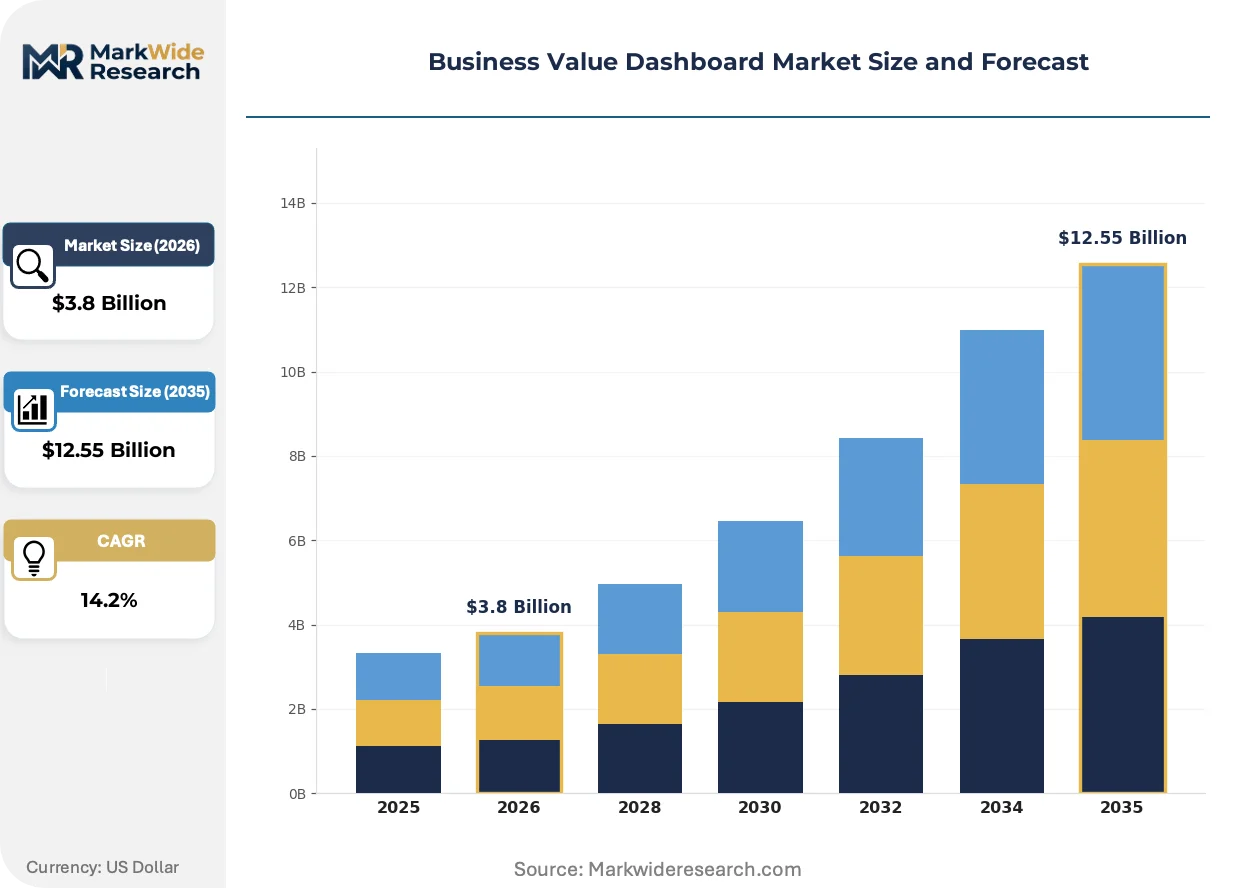
Market Dynamics
Cloud migration mandates under the EU AI Act and analogous data governance frameworks are compressing replacement cycles for legacy ERP reporting architectures, forcing enterprises to prioritize elastic scalability over sunk-cost retention.
Growth Catalysts
- EU AI Act compliance deadlines:Financial services firms across Germany, France, and Italy face mandatory algorithmic audit trails, accelerating procurement of explainable dashboard platforms with embedded governance layers.
- Real-time data streaming infrastructure:Apache Kafka and cloud-native event processing enable sub-second KPI refresh rates, satisfying executive demands for instantaneous operational visibility.
- Fortune 500 ERP modernization:United States-based conglomerates retiring SAP BusinessObjects and Oracle Discoverer installations are consolidating vendor relationships around unified analytics stacks.
Market Restraints
- Specialized talent scarcity:Data engineering and visualization design expertise concentrates in San Francisco, London, and Bangalore, inflating implementation costs for mid-market buyers in secondary metros.
- Input cost volatility:Cloud compute pricing from AWS, Azure, and GCP fluctuates with energy markets, compressing SaaS gross margins for dashboard providers without long-term reserved instance commitments.
- Data residency fragmentation:Divergent national sovereignty laws in Switzerland, Singapore, and Saudi Arabia force redundant infrastructure deployment, raising total cost of ownership.
Strategic Opportunities
- India SME penetration:The country's PLI scheme for IT hardware and RBI-mandated digital lending disclosures create first-mover advantage for localized dashboard vendors serving non-bank financial companies.
- ESG disclosure automation:The EU CSRD and SEC climate rules converge on standardized sustainability reporting, opening premium positioning for dashboards with pre-built emissions calculation modules.
- Natural language query convergence:Large language models integrated with semantic data layers enable conversational analytics, lowering adoption barriers for non-technical business users.
Industry Challenges
- Legacy system integration complexity:Mainframe-era data warehouses in insurance and banking require custom API middleware, extending implementation timelines and eroding project margins.
- Cross-border certification delays:FDA 21 CFR Part 11 validation for healthcare dashboards and HIPAA business associate agreements add six-to-nine month procurement cycles.
- IP licensing entanglement:Embedded third-party visualization libraries trigger patent disputes, forcing costly reengineering or royalty negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Value Dashboard Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMBs, Large Enterprises, Government Agencies, Non-Profits Functionality Type: Financial Analysis, Performance Tracking, Reporting Tools, Visual Analytics Industry Vertical: Finance, Retail, Healthcare, Manufacturing |
| Companies Covered | IBM Corporation, Salesforce.com, Tableau Software, Hewlett Packard Enterprise, SAP SE, Oracle Corporation, ServiceClarity, Interlink Software Services Ltd., PureShare by TeamQuest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Value Dashboard Market Strategic Shifts
Generative AI interfaces and embedded governance automation are compressing the traditional divide between self-service exploration and enterprise-grade compliance, reshaping how business users interact with performance data.
Natural language-to-SQL translation is digitizing query construction for non-technical analysts. Fortune 500 finance departments in the United States and United Kingdom are piloting conversational interfaces that bypass traditional drag-and-drop dashboard builders. This capability is digitizing the middle layer between raw data warehouses and executive consumption, collapsing the need for dedicated BI developer headcount.
The EU AI Act's risk-based classification system mandates human oversight mechanisms for high-stakes algorithmic outputs. Dashboard vendors serving credit underwriting and insurance pricing segments must embed explanation interfaces and override controls. European banking supervisors are requiring model cards and performance drift alerts, forcing product teams to prioritize interpretability over predictive complexity.
Consolidated platform purchasing is displacing best-of-breed point solutions. Procurement functions at North American manufacturers and retailers are bundling dashboard licenses with existing CRM and ERP contracts, squeezing standalone visualization specialists. This concentration favors full-stack providers with native integration capabilities, particularly in mid-market segments where IT procurement authority has centralized.
Business Value Dashboard Market Segmentation
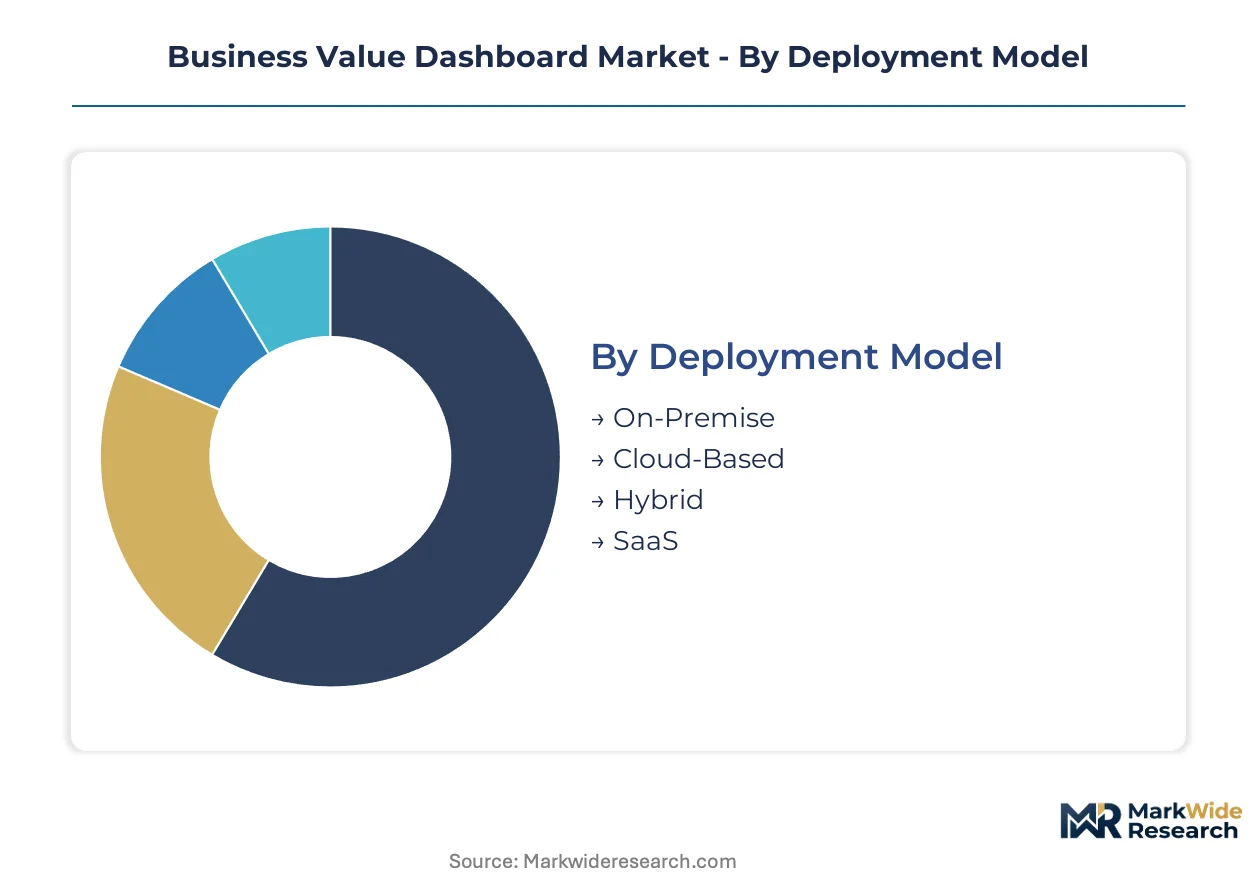
Dashboard procurement patterns diverge sharply across deployment preferences, organizational scale, functional requirements, and sector-specific compliance burdens. Understanding these fault lines enables vendors to align product roadmaps with buyer willingness-to-pay and implementation complexity tolerance.
Deployment Model:
Mature on-premise installations coexist with emerging cloud-native architectures as enterprises navigate data sovereignty mandates and elasticity demands.
- On-Premise:Hardware-resident deployments with dedicated server infrastructure and localized data storage. German automotive manufacturers and Swiss private banks favor these configurations under BfDI and FINMA data localization requirements, accepting higher capital expenditure for audit trail control.
- Cloud-Based:Fully managed public cloud environments with automatic scaling and zero hardware maintenance. United States-based technology startups and mid-market retailers in Austin and Denver prioritize these for rapid deployment without IT headcount expansion.
- Hybrid:Split architectures keeping sensitive workloads on-premise while bursting analytics to cloud. French healthcare networks under CNIL guidelines deploy hybrid models to isolate patient data while enabling population-level trend analysis.
- SaaS:Subscription software delivered through browsers with multi-tenant efficiency. Indian non-bank financial companies leverage SaaS dashboards to meet RBI digital lending disclosure mandates without infrastructure investment.
On-premise retains volume leadership among regulated European institutions; cloud-based holds the steepest expansion curve as United States mid-market buyers consolidate vendor relationships.
End User:
Cost tier stratification separates capital-constrained buyers from procurement functions with centralized IT authority and compliance-driven specification requirements.
- SMBs:Organizations with under 500 employees seeking rapid deployment without dedicated analytics teams. Brazilian agricultural cooperatives and Vietnamese manufacturing exporters adopt self-service visual analytics to replace spreadsheet-based reporting.
- Large Enterprises:Fortune 500 and equivalent conglomerates with complex ERP landscapes and governance committees. These buyers in the United States and United Kingdom mandate embedded audit trails and role-based access matrices for Sarbanes-Oxley and UK Corporate Governance Code compliance.
- Government Agencies:Public sector entities with procurement transparency requirements and legacy system integration challenges. State-level transportation departments and municipal health authorities face extended validation cycles for FedRAMP and equivalent national certification schemes.
- Non-Profits:Mission-driven organizations prioritizing donor reporting and grant compliance over operational analytics. International development NGOs and United States community health centers require pre-built impact measurement templates for foundation reporting.
Large enterprises command the highest average contract values; SMBs are climbing the fastest as verticalized SaaS lowers adoption barriers.
Functionality Type:
Application depth separates point solutions from platform consolidation plays, with buyers trading specialization breadth against integration overhead.
- Financial Analysis:Specialized modules for variance analysis, forecasting, and scenario modeling. United States-based private equity firms and asset managers pay premium licensing for real-time portfolio attribution and risk-adjusted return visualization.
- Performance Tracking:Operational KPI monitoring with alerting and threshold management. German industrial manufacturers embed these capabilities for OEE (Overall Equipment Effectiveness) dashboards tied to shop-floor IoT sensors.
- Reporting Tools:Scheduled distribution and formatted output generation for regulatory submission. Japanese pharmaceutical companies utilize these for PMDA pharmacovigilance reporting with embedded digital signatures.
- Visual Analytics:Self-service exploration with drag-and-drop interfaces and natural language querying. United Kingdom retail chains and Australian professional services firms deploy these to reduce dependency on centralized BI developer queues.
Financial analysis retains margin leadership in enterprise accounts; visual analytics is expanding most quickly as generative AI interfaces collapse technical skill requirements.
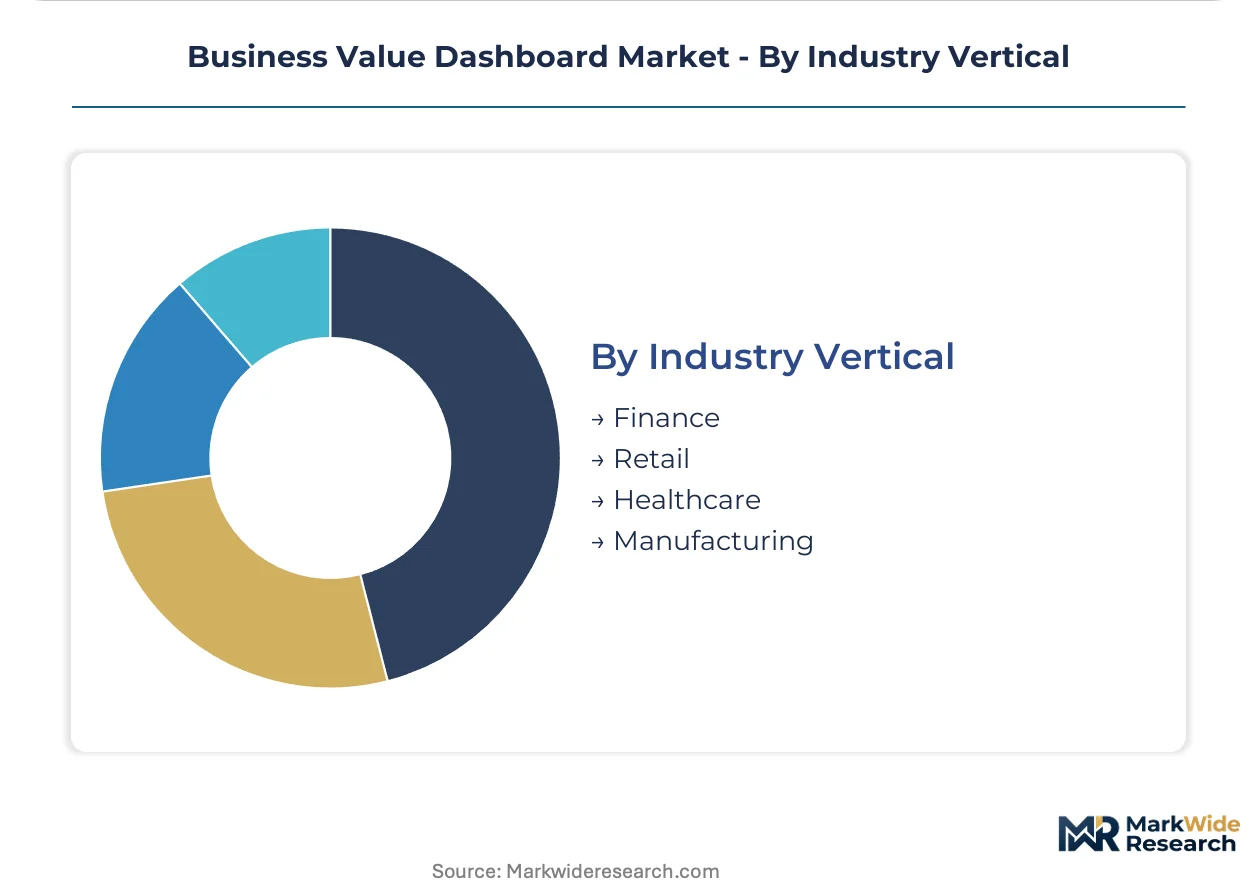
Industry Vertical:
Margin concentration and compliance intensity create divergent vendor profitability profiles across sector-specific procurement patterns.
- Finance:Banking, insurance, and capital markets with stringent model governance and real-time risk visualization requirements. European institutions under ECB supervisory expectations and United States banks facing CCAR stress testing mandates drive demand for explainable algorithmic dashboards.
- Retail:Omnichannel merchants seeking unified customer and inventory visibility. United States-based department stores and United Kingdom grocery chains prioritize demand forecasting dashboards integrating POS, e-commerce, and supply chain signals.
- Healthcare:Providers, payers, and life sciences with HIPAA, FDA 21 CFR Part 11, and equivalent national validation requirements. United States hospital systems and German medical device manufacturers require immutable audit logs and granular access controls for clinical quality dashboards.
- Manufacturing:Discrete and process industries with IoT-enabled predictive maintenance and quality optimization. Japanese automotive suppliers and South Korean semiconductor fabricators deploy real-time SPC (Statistical Process Control) visualizations for yield management.
Finance retains the highest contract values and renewal rates; healthcare is gaining share fastest as post-pandemic operational resilience investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act compliance deadlines and SEC disclosure mandates are compressing procurement cycles across major economies, with data sovereignty requirements fragmenting deployment architectures and cloud migration incentives concentrating vendor selection authority.
United States
Fortune 500 ERP modernization programs are consolidating analytics vendor relationships around unified cloud stacks. SEC climate disclosure rules and Sarbanes-Oxley audit mandates require embedded governance layers with immutable data logs. Chicago-based manufacturers and New York financial services firms are retiring legacy SAP BusinessObjects installations for SaaS-native alternatives.
Germany
BfDI data localization requirements and ECB supervisory expectations for algorithmic explainability are sustaining hybrid deployment demand. German automotive manufacturers in Stuttgart and Munich favor on-premise configurations for shop-floor IoT integration. The EU AI Act's high-risk system classification is forcing credit underwriting dashboards to embed human oversight controls.
United Kingdom
UK Corporate Governance Code disclosure requirements and FCA operational resilience mandates are accelerating replacement of spreadsheet-based reporting. London-based asset managers and retail chains in Manchester are piloting natural language query interfaces to reduce BI developer dependency. Post-Brexit data adequacy negotiations are complicating cross-border cloud architectures.
India
RBI-mandated digital lending disclosures and the PLI scheme for IT hardware are creating first-mover openings for localized SaaS vendors. Mumbai non-bank financial companies and Bangalore technology startups are adopting browser-delivered dashboards without infrastructure investment. Data localization requirements under the Digital Personal Data Protection Act are reshaping cloud provider selection criteria.
Japan
PMDA pharmacovigilance reporting requirements and METI digital transformation subsidies are driving pharmaceutical and manufacturing adoption. Tokyo pharmaceutical companies and Nagoya industrial equipment suppliers require embedded digital signatures and granular access matrices. Aging ERP systems in Osaka-based conglomerates are creating replacement demand for cloud-native visualization platforms.
Business Value Dashboard Market Competitive Environment
On the supply side, the industry is consolidating around full-stack platform providers with native integration capabilities, compressing margins for standalone visualization specialists. Three archetypes dominate: hybrid cloud infrastructure incumbents, CRM-anchored analytics layers, and self-service visualization specialists. Competitive moves center on strategic bundling with ERP contracts and M&A-driven capability expansion into natural language interfaces.
Within the enterprise infrastructure tier, IBM Corporation exemplifies the hybrid cloud archetype sustaining relationships across regulated sectors. Salesforce.com anchors the CRM-integrated positioning through native analytics layering. Tableau Software occupies the self-service specialization vector, competing by dominating business-user segments against broader platform vendors. These three represent divergent responses to the consolidation pressure from unified analytics procurement.
| Leading Market Players |
|---|
| IBM Corporation |
| Salesforce.com |
| Tableau Software |
| Hewlett Packard Enterprise |
| SAP SE |
| Oracle Corporation |
| ServiceClarity |
| Interlink Software Services Ltd. |
| PureShare by TeamQuest |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific submarine cable capacity constraints between Singapore and Los Angeles are elevating latency-sensitive data transfer costs for dashboard vendors, concentrating pricing power among hyperscale cloud providers with private fiber networks while forcing mid-tier SaaS providers toward regional data center partnerships to manage delivery economics.
Pricing Analysis
Certification level (ISO 27001/FDA 21 CFR Part 11/CE-marked) creates the primary spread between premium and standard tiers, with healthcare and financial services buyers absorbing 40-60% uplifts for validated audit trails. Subscription-based SaaS pricing dominates, though annual contract values compress for mid-market buyers lacking dedicated procurement functions. Pricing pressure stems from hyperscaler bundling of analytics modules with core infrastructure contracts, eroding standalone visualization margins. SMB segments exhibit highest price sensitivity, while Fortune 500 compliance officers prioritize governance capabilities over unit cost.
Supply Chain Analysis
Export-control restrictions under US Commerce Department Entity List designations are constraining GPU and advanced semiconductor flows to certain jurisdictions, forcing dashboard vendors toward software-optimized inference architectures. Supply concentration centers on Taiwan for advanced foundry capacity, Ireland for European data center infrastructure, and India for SaaS development operations. Component dependencies span NVIDIA accelerators for AI-enabled querying, Apache Kafka streaming licenses, and embedded visualization libraries. Single-source vulnerability in cloud compute provisioning dominates risk profiles. Distribution runs through direct enterprise sales teams with embedded solution architects, supplemented by hyperscaler marketplace listings for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as compliance-driven procurement splinters demand across governance-native specialists, verticalized SaaS vendors, and full-stack platform consolidators, with EU AI Act implementation timelines creating temporary vendor-switching windows.
For Market Incumbents: Insulate recurring revenue streams through embedded workflow integration that raises switching costs for finance and healthcare buyers facing FDA and ECB validation overhead. Prioritize certification maintenance in ISO 27001 and SOC 2 Type II frameworks as emerging entrants lack audit history depth. Defensive moves should center on API ecosystem expansion and pre-built vertical templates for credit underwriting and clinical quality monitoring. For New Entrants and Emerging Players: Establish a beachhead in Indian non-bank financial companies facing RBI-mandated digital lending disclosures, where localized SaaS deployment outperforms global vendor latency. Target Brazilian agricultural cooperatives and Vietnamese manufacturing exporters with self-service visual analytics replacing spreadsheet workflows. Go-to-market leverage rests on natural language query interfaces that collapse technical skill barriers for non-analyst business users. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core software assets, particularly legacy ERP reporting modules stranded after cloud migration mandates. Long-term viability favors vendors with embedded governance automation and explainable AI interfaces aligned to EU AI Act risk classifications. Watch for inflection signals in SEC climate disclosure enforcement intensity, which would accelerate ESG dashboard procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Language Query Integration | Conversational interfaces reduce BI developer dependency for Fortune 500 finance departments. |
| ESG Disclosure Module Development | Pre-built emissions calculations align with EU CSRD and SEC climate rule convergence. |
| Hybrid Cloud Certification Investment | FDA 21 CFR Part 11 and HIPAA validation opens healthcare procurement pipelines. |
| Vertical SaaS Partnership | Embedded analytics in lending platforms captures RBI-mandated disclosure workflows. |
| API Ecosystem Expansion | Native ERP and CRM connectors defend against full-stack platform bundling pressure. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with CTOs, IT procurement officers, platform engineers, and integration specialists at Fortune 500 enterprises and mid-market SaaS adopters; and secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory texts, and healthcare GPO contract databases. Bottom-up deployment estimates across on-premise, cloud, hybrid, and SaaS configurations were triangulated against top-down market sizing from vendor revenue disclosures and channel partner surveys.
Forecast inputs span deployment model, organization size, functional requirement depth, vertical compliance intensity, and regional adoption pattern across the analysis window. CAGRs were derived from segment-level growth rate reconciliation with macro technology spending indicators. Industry-specific modeling incorporates EU AI Act implementation phase-ins, SEC disclosure rule enforcement trajectories, and RBI digital lending mandate compliance deadlines.
Stress conditions across cloud compute pricing volatility, data sovereignty law fragmentation, and generative AI capability disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enterprise cloud migration velocity. Material shifts in EU AI Act risk classification interpretations or hyperscaler bundling strategy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Condition Monitoring Service Market
Analytics
Italy Geospatial Analytics Market
Analytics
Data Wrangling Market
Analytics
APAC Location Analytics Market
Analytics
Retail Analytics Market
Analytics
Assortment Analytics Market
Analytics
Manufacturing Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Learning Analytics Solution Market
Analytics
Embedded Analytics Market
Analytics
Europe Network and Location Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Global Data Prep Market
Analytics
Personal Analytics Market
Analytics
Global Customer Analytics Market