
 Business Intelligence and Analytics Software Market | 2026-2036
Business Intelligence and Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Business Intelligence and Analytics Software Market Analysis
The capability gap between cloud-native architectures and legacy on-premises stacks is unwinding competitive dynamics across the sector. Microsoft Power BI leverages its Azure integration to anchor enterprise accounts seeking seamless hybrid deployments. SAP Analytics Cloud sustains deep penetration in manufacturing verticals through embedded ERP connectivity. Tableau competes aggressively on visual exploration interfaces, occupying a distinct position among data analyst power users.
Business intelligence and analytics software encompasses platforms that extract, transform, and visualize structured and unstructured data through SQL-based querying, in-memory processing, and machine learning inference layers to support operational and strategic decision-making. Cloud-based deployment is capturing the fastest expansion as organizations retire server farms and adopt elastic compute models for variable workloads. Predictive analytics represents the highest-margin solution type, though dashboarding retains the largest installed base across SMEs and large enterprises. Healthcare and finance verticals are driving specialized demand for real-time streaming analytics and regulatory-compliant data lineage tools.
FDA guidelines on algorithmic transparency in clinical decision support, combined with GDPR data governance requirements in Europe and HIPAA security protocols in the United States, are elevating compliance costs while creating barriers for uncertified entrants. ISO 27001 and SOC 2 Type II certifications have become baseline prerequisites for procurement evaluations across regulated industries. Stakeholders must weigh the trade-off between vertical specialization and platform breadth as buyer consolidation favors vendors offering unified governance across multi-cloud environments.
Market Dynamics
Cloud migration mandates under GDPR and data sovereignty requirements across Asia are forcing enterprises to re-architect their analytics stacks, creating a structural divide between vendors with native multi-cloud governance and legacy on-premises providers.
Growth Catalysts
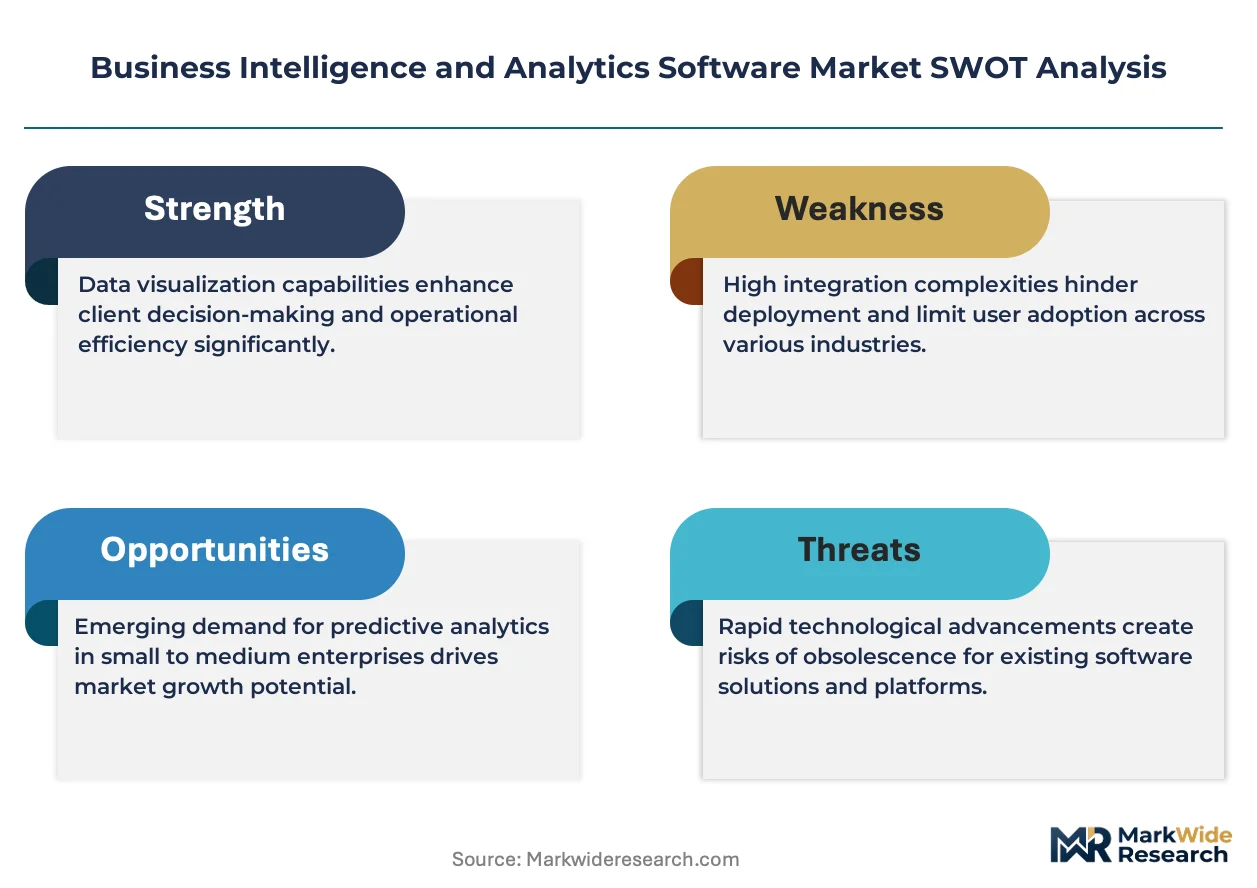
- GDPR cloud migration mandates:European enterprises must relocate analytics workloads to EU-sovereign cloud regions, accelerating procurement of compliant platforms.
- Healthcare predictive analytics:FDA guidelines on algorithmic transparency in clinical decision support are institutionalizing AI-driven diagnostics platforms across US hospital networks.
- Elastic compute models:Variable workload patterns in financial services are driving retirement of server farms in favor of consumption-based analytics infrastructure.
Market Restraints
- ISO 27001 certification costs:Baseline compliance prerequisites in regulated industries impose six-figure audit expenses that barrier uncertified entrants.
- HIPAA security protocol complexity:US healthcare providers face multi-year implementation timelines for encrypted data lineage tools that delay platform rollouts.
- Technical talent scarcity:Shortage of MLOps engineers capable of deploying real-time streaming analytics constrains enterprise adoption velocity.
Strategic Opportunities
- EU AI Act compliance services:Mandatory risk classification for automated decision systems creates white space for governance-layer vendors.
- India BIS data localization:Government cloud-first policies in financial services open procurement channels for hybrid analytics providers.
- Edge-to-cloud convergence:Manufacturing verticals are integrating shop-floor sensors with centralized BI platforms for unified operational visibility.
Industry Challenges
- Legacy ERP integration friction:Embedded connectivity requirements in manufacturing delay SAP Analytics Cloud deployments by 8-14 months.
- SOC 2 Type II audit timelines:Certification backlog at accredited bodies extends vendor qualification cycles beyond buyer procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Intelligence and Analytics Software Market |
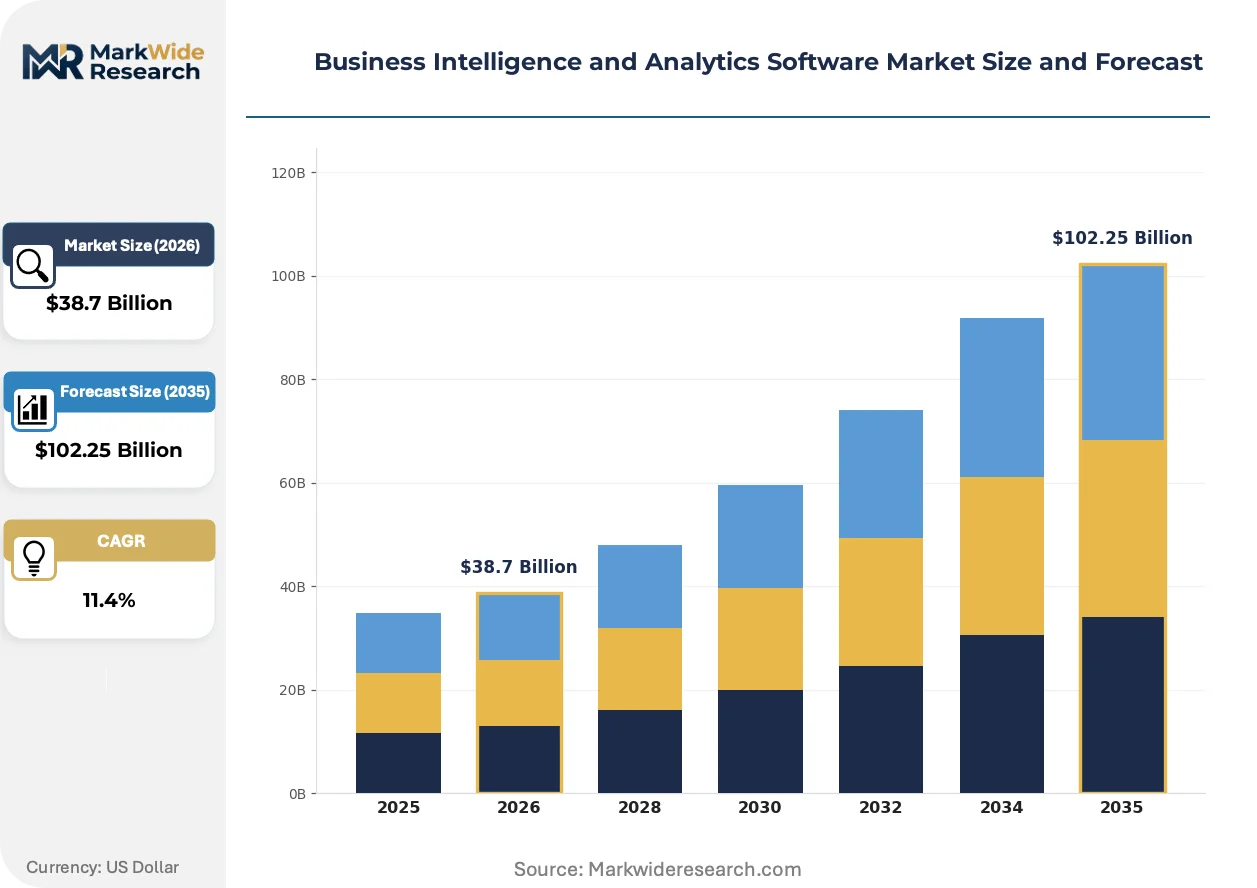
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
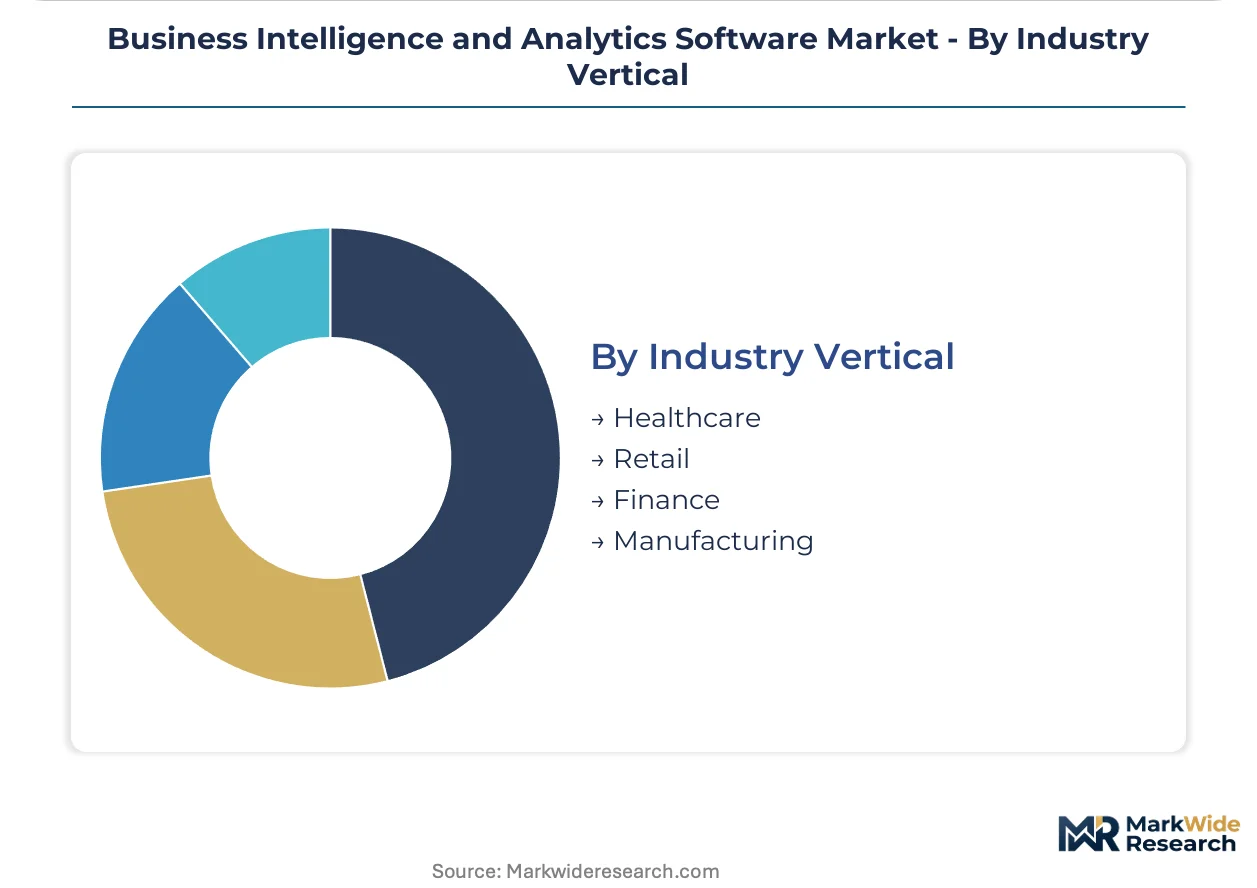
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Solution Type: Reporting Tools, Data Visualization, Dashboarding, Predictive Analytics End User: SMEs, Large Enterprises, Government Agencies, Non-Profit Organizations Industry Vertical: Healthcare, Retail, Finance, Manufacturing |
| Companies Covered | Oracle Analytics Cloud, Looker, Microsoft Power BI, MicroStrategy, IBM Cognos Analytics, Tableau, SAP Analytics Cloud, Sisense, Qlik Sense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Intelligence and Analytics Software Market Emerging Trajectories
Generative AI capabilities are compressing the analytics workflow from data preparation to natural language insight generation, reshaping how business users interact with BI platforms without specialized SQL expertise.
Composable data architectures are decomposing monolithic BI platforms into modular microservices. Large enterprises in the United States are adopting API-first analytics components at accelerated procurement cycles. This modularity is decomposing vendor lock-in and enabling best-of-breed stack assembly across cloud providers.
CSRD sustainability reporting mandates in Europe are forcing disclosure of ESG metrics through auditable data lineage. Manufacturing and energy verticals must deploy carbon accounting modules with immutable audit trails. German automotive suppliers are prioritizing platforms with embedded emissions calculation engines to satisfy regulator deadlines.
Self-service analytics adoption is collapsing the traditional IT-ticket model for dashboard requests. Business units in US Fortune 500 companies are procuring departmental licenses directly, bypassing centralized procurement. Financial services and healthcare show the most pronounced decentralization, with compliance officers now embedded in business lines to govern shadow analytics deployments.
Business Intelligence and Analytics Software Market Segmentation

Deployment architecture, solution sophistication, buyer scale, and vertical specialization each create distinct competitive arenas with diverging margin profiles and vendor qualification requirements. Procurement patterns across these dimensions reveal where substitution pressure from adjacent technologies reshapes competitive boundaries.
Deployment:
Cloud-native architectures face intensifying substitution pressure from containerized analytics microservices that bypass traditional platform licensing entirely.
- Cloud-Based:Elastic compute provisioning through API-first consumption models eliminates upfront infrastructure capitalization. US Fortune 500 financial services firms are retiring server farms for variable-cost analytics infrastructure under SEC data governance guidelines.
- Hybrid:Split workloads between sovereign on-premises data lakes and burst-capable cloud analytics satisfy GDPR residency mandates while preserving legacy ERP connectivity. German automotive suppliers prioritize this architecture to satisfy CSRD audit trail requirements without full cloud migration.
- On-Premises:Remains entrenched in defense contracting and classified government intelligence workflows where air-gapped networks are mandatory.
- Multi-Cloud:Workload portability across AWS, Azure, and GCP regions addresses data sovereignty requirements in Asia-Pacific jurisdictions with BIS-style localization rules.
Cloud-Based deployments anchor the volume base while Multi-Cloud configurations gain share at the steepest rate.
Solution Type:
Margin concentration follows solution complexity, with higher-automation tiers capturing disproportionate value despite smaller installed bases.
- Predictive Analytics:Machine learning inference layers embedded atop data warehouses enable automated forecasting and anomaly detection. Healthcare networks under FDA algorithmic transparency guidelines are institutionalizing these platforms for clinical decision support.
- Data Visualization:Drag-and-drop interfaces for exploratory analysis democratize insight generation beyond SQL-proficient analyst pools. US departmental procurement bypassing centralized IT favors this category for rapid deployment.
- Dashboarding:Static KPI monitoring retains the largest SME installed base through low-code configuration and mobile-optimized rendering.
- Reporting Tools:Scheduled distribution of formatted tabular outputs persists in regulated industries requiring immutable document archives.
Dashboarding retains the broadest footprint while Predictive Analytics expands most quickly as MLOps engineering capacity matures.
End User:
Buyer scale determines procurement centralization, with smaller organizations bypassing enterprise vendor qualification regimes entirely.
- Large Enterprises:Multi-year ELA negotiations with unified governance requirements across cloud environments. SOC 2 Type II certification and ISO 27001 compliance are baseline prerequisites.
- SMEs:Departmental credit-card procurement of self-service analytics tools with minimal IT involvement. Shadow analytics proliferation demands embedded compliance officer oversight.
- Government Agencies:FedRAMP authorization and FedRAMP-equivalent sovereign certifications gate vendor participation in federal analytics modernization.
- Non-Profit Organizations:Grant-funded analytics adoption constrained by restricted indirect cost recovery and donor reporting transparency mandates.
Large Enterprises dominate current spending while SME procurement climbs fastest through verticalized SaaS analytics bundles.
Industry Vertical:
Vertical specialization creates vendor lock-in through embedded workflow integration and sector-specific regulatory compliance modules.
- Healthcare:Real-time streaming analytics for patient monitoring combined with HIPAA-encrypted data lineage. FDA clinical decision support guidelines institutionalize algorithmic transparency requirements.
- Finance:Variable workload patterns in trading analytics and risk modeling drive elastic infrastructure adoption. SEC cybersecurity disclosure rules elevate governance-layer procurement priority.
- Manufacturing:Shop-floor sensor integration with centralized BI platforms enables unified operational visibility. CSRD carbon accounting modules with immutable audit trails satisfy automotive supplier deadlines.
- Retail:Customer journey analytics across omnichannel touchpoints with demand forecasting for inventory optimization.
Finance anchors analytics spending intensity while Healthcare demonstrates the steepest adoption acceleration under diagnostic AI reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European procurement cycles elongate under compliance mandates. German automotive suppliers and French healthcare networks absorb premium licensing costs for sovereign cloud architectures. Asian buyers in India and Japan prioritize localized deployment options over standardized global bundles.
United States
Federal agencies and Fortune 500 companies drive modernization of legacy reporting infrastructure at scale. SEC cybersecurity disclosure rules elevate governance-layer procurement priority for financial services firms. Silicon Valley clusters anchor cloud-native analytics development while New York Metro financial institutions dominate variable-workload adoption.
Germany
Automotive suppliers prioritize platforms with embedded emissions calculation engines to satisfy CSRD regulator deadlines. GDPR cloud migration mandates force re-architecture of analytics stacks toward EU-sovereign cloud regions. Bavaria-based manufacturing clusters integrate shop-floor sensors with centralized BI platforms for unified operational visibility.
India
Government cloud-first policies in financial services open procurement channels for hybrid analytics providers under BIS data localization requirements. MLOps engineering talent scarcity constrains enterprise adoption velocity despite strong demand signals. Bangalore and Hyderabad technology corridors concentrate SaaS analytics development for domestic and export markets.
Japan
Manufacturing verticals demand edge-to-cloud convergence for shop-floor sensor integration with centralized platforms. METI industrial digitization programs accelerate retirement of legacy server farms in favor of elastic compute models. Osaka-Kobe industrial clusters lead predictive maintenance analytics deployment for automotive and electronics production lines.
United Kingdom
Financial services firms in London navigate SEC-equivalent disclosure requirements while maintaining GDPR compliance for EU data flows. Self-service analytics adoption collapses traditional IT-ticket models across departmental procurement. The Square Mile concentration of trading analytics drives demand for real-time streaming infrastructure with sub-millisecond latency requirements.
Business Intelligence and Analytics Software Market Vendor Landscape
Concentration sits with cloud-native platform providers possessing multi-cloud governance capabilities. Microsoft Power BI leverages Azure integration to anchor enterprise accounts seeking seamless hybrid deployments. SAP Analytics Cloud sustains deep penetration in manufacturing verticals through embedded ERP connectivity. Strategic moves center on M&A for vertical specialization and API-first portfolio diversification to capture composable architecture demand.
Within the cloud-native tier, Microsoft Power BI and Oracle Analytics Cloud represent platform breadth strategies, while Tableau exemplifies visual exploration specialization for data analyst power users. SAP Analytics Cloud occupies a distinct position among ERP-embedded providers. IBM Cognos Analytics and MicroStrategy anchor legacy enterprise accounts navigating multi-year modernization timelines. Looker, Sisense, and Qlik Sense sit within the API-first and embedded analytics segments targeting SaaS-native buyers.
| Leading Market Players |
|---|
| Oracle Analytics Cloud |
| Looker |
| Microsoft Power BI |
| MicroStrategy |
| IBM Cognos Analytics |
| Tableau |
| SAP Analytics Cloud |
| Sisense |
| Qlik Sense |
| Others |
Supply Flow & Price Mechanics
Consumption-based capacity reservation contracts anchor enterprise procurement cycles, locking in multi-year pricing visibility for cloud-native analytics platforms while constraining vendor flexibility to adjust rates amid infrastructure cost volatility. These arrangements concentrate pricing power with hyperscale cloud providers in the United States and Germany, where GDPR-mandated EU-sovereign regions command premium licensing differentials.
Pricing Analysis
The customization-premium spread separates standard SaaS-tiered subscriptions from configured-to-order deployments with embedded compliance modules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 27001 and SOC 2 Type II tiers absorbing six-figure audit pass-through costs. Cost compression in the economy tier intensifies as containerized microservices bypass traditional platform licensing entirely. SMEs exhibit highest price sensitivity through departmental credit-card procurement, while Fortune 500 enterprises absorb premium tiers for unified governance across multi-cloud environments.
Supply Chain Analysis
The United States and Ireland anchor hyperscale cloud infrastructure provisioning for analytics workloads, while India and Poland concentrate MLOps engineering talent pools for platform development. Compute capacity draws from specialized GPU clusters and high-memory instance families, with API-first microservices architectures reducing dependency on monolithic vendor stacks. Single-source vulnerability concentrates in NVIDIA-dominated AI accelerator supply, constraining real-time inference deployment timelines. Distribution runs through direct enterprise sales organizations and hyperscaler marketplace channels, with system integrators handling complex ERP-embedded implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI-native analytics tools threaten incumbent dashboarding and visualization platforms by collapsing technical skill barriers for insight generation, forcing established vendors to defend substitution risk through workflow embedding and governance-layer differentiation.
For Market Incumbents: Consolidate platform breadth through API-first portfolio expansion targeting composable architecture demand in US Fortune 500 accounts. Deepen vertical integration into healthcare compliance modules to counter specialized AI-native entrants exploiting FDA algorithmic transparency requirements. Prioritize multi-cloud governance certification to maintain procurement relevance under GDPR and BIS data localization mandates. For New Entrants and Emerging Players: EU AI Act compliance services represent a service-layer gap where incumbents under-serve automated decision-system risk classification demand. Target German automotive suppliers facing CSRD carbon accounting deadlines with embedded emissions calculation engines. Pursue channel partnerships with system integrators handling SAP Analytics Cloud deployment friction to bypass direct enterprise sales barriers. For Investors and Strategic Acquirers: Vertical SaaS analytics bundles with embedded compliance officer tooling offer acquisition target archetypes positioned for SME procurement decentralization. Long-term viability hinges on MLOps engineering capacity scalability and sovereign cloud certification velocity. Watch for inflection signals in India BIS localization enforcement accelerating hybrid deployment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-anchored hybrid deployments capture US federal modernization contracts under FedRAMP authorization. |
| Acquisition of Specialist Firm | Healthcare AI transparency modules address FDA clinical decision support institutionalization timelines. |
| Strategic Partnership | System integrator alliances resolve SAP Analytics Cloud ERP-embedded deployment friction in manufacturing. |
| Geographic Expansion | EU-sovereign cloud regions satisfy GDPR residency mandates for German automotive supplier procurement. |
| Product Launch | Generative AI natural language interfaces compress analytics workflows for SQL-novice business users. |
Methodological Framework
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility data, and GPO contracts anchors the qualitative findings. Bottom-up triangulation across deployment architecture, solution sophistication, buyer scale, and vertical specialization dimensions integrates with top-down macroeconomic drivers. Conversations with healthcare network informatics directors and financial services risk analytics heads informed regulatory compliance cost modeling.
Sensitivity analysis around elastic compute adoption curves and MLOps engineering supply constraints shapes the analytical framework across the projection horizon. Deployment model, organization size, vertical, integration complexity, and regional adoption pattern segmentation dimensions drive value allocation. CAGRs derive from variable workload pattern elasticity and sovereign cloud procurement acceleration. Real-time streaming analytics infrastructure buildouts and CSRD sustainability reporting mandate compliance timelines constitute primary forecast inputs.
Underlying assumptions cover cloud migration velocity, regulatory enforcement intensity, and talent pool expansion, with deviation risk concentrated in HIPAA implementation timeline delays and ISO 27001 certification backlog at accredited bodies. Forecasts reflect documented conditions with revision triggers tied to EU AI Act enforcement commencement and India BIS localization rule expansion. Recalibration cycles align with material shifts in hyperscaler pricing architecture and generative AI capability commoditization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Japan Geospatial Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
Cyprus ICT Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Weather Data Services Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Europe HR Analytics Market
Analytics
Mobile Analytics Market
Analytics
Data Wrangling Market
Analytics
Statistical Analytics Market
Analytics
Service Analytics Market
Analytics
North America HR Analytics Market
Analytics
Brazil Big Data Analytics Market
Analytics
App Analytics Market