
 Lithium Starters Market | 2026-2036
Lithium Starters Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Starters Market Insights
Chinese cylindrical cell producers is recalibrating capacity allocation toward starter-specific lithium iron phosphate formats. Clarios leverages its North American recycling infrastructure to secure cathode material feedstock. GS Yuasa anchors Japanese OEM supply agreements through proprietary thermal management designs.
Lithium starters are rechargeable electrochemical storage devices engineered with lithium iron phosphate or lithium manganese oxide cathodes, delivering cold cranking amperage above 800A at sub-zero temperatures for internal combustion engine ignition. The automotive end user segment dominates unit volume, while marine applications command premium pricing due to salt corrosion resistance requirements. Lithium ion product types are displacing lead acid in electric vehicle starter motor configurations where weight reduction directly extends driving range.
China's NMPA enforces GB/T cycling endurance standards that determine market access for starter battery imports. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in battery manufacturing processes, altering electrolyte formulation pathways. Stakeholders must monitor how EPA domestic content rules under the IRA reshape North American supply qualification criteria.
Market Dynamics
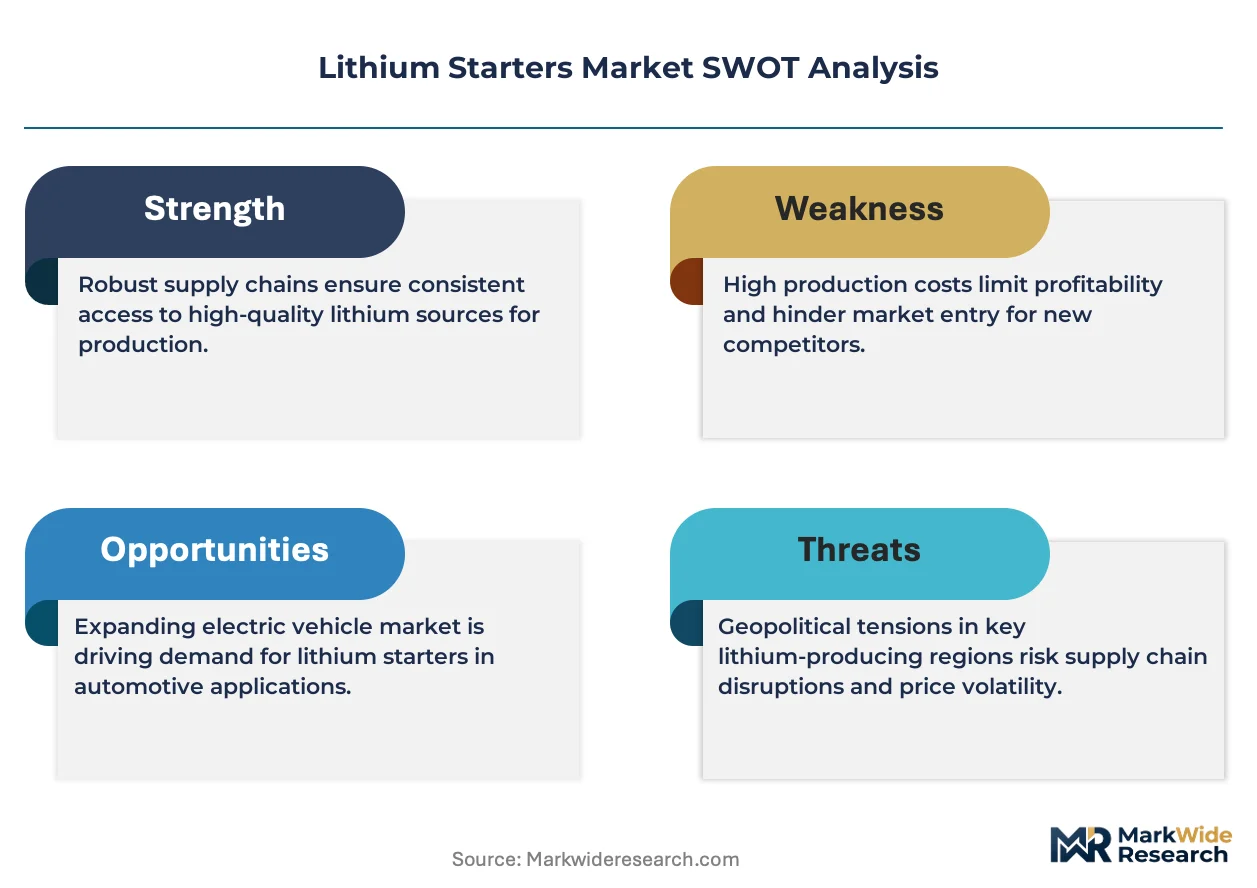
The lithium starters market is undergoing fundamental reconfiguration as automotive OEMs migrate from lead-acid to lithium-ion cranking systems, driven by weight-reduction mandates and cold-climate performance requirements. This chemistry transition is compressing incumbent supply chains while opening cathode material sourcing contests.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated gas restrictions on battery manufacturing processes are accelerating electrolyte formulation innovation, creating first-mover advantages for compliant chemistry suppliers.
- Commercial vehicle electrification:Fleet operators across long-haul trucking segments are specifying lithium starters to reduce idle fuel consumption through auxiliary power unit downsizing.
- Jiangsu manufacturing corridor:China's concentration of cylindrical cell production capacity is enabling just-in-time cathode material flows to starter assembly plants.
Market Restraints
- Cathode material cost volatility:Lithium iron phosphate and lithium manganese oxide input prices fluctuate with mining output constraints in South American salt flats.
- Single-region supply concentration:China's dominance of refined lithium processing creates geopolitical exposure for non-domestic battery assemblers.
- GB/T cycling endurance standards:China's NMPA import testing protocols impose 18-24 month certification timelines that delay market entry.
Strategic Opportunities
- Marine salt-corrosion applications:Premium pricing in offshore vessel cranking systems rewards manufacturers with conformal coating IP.
- EPA domestic content rules:IRA qualification criteria for North American assembly are reshaping cathode precursor sourcing toward US recycling infrastructure.
- Thermal management convergence:Integration of phase-change materials with battery management systems enables sub-zero cranking performance without external heating.
Industry Challenges
- Electrolyte formulation expertise:Shortage of chemists experienced in low-temperature ionic conductivity optimization constrains R&D throughput.
- Cell-to-pack certification timelines:UN 38.3 transportation testing and UL 2580 automotive safety validation extend product launch cycles.
- Legacy starter motor compatibility:Voltage curve mismatches between lithium and lead-acid chemistries require alternator control software recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Starters Market |
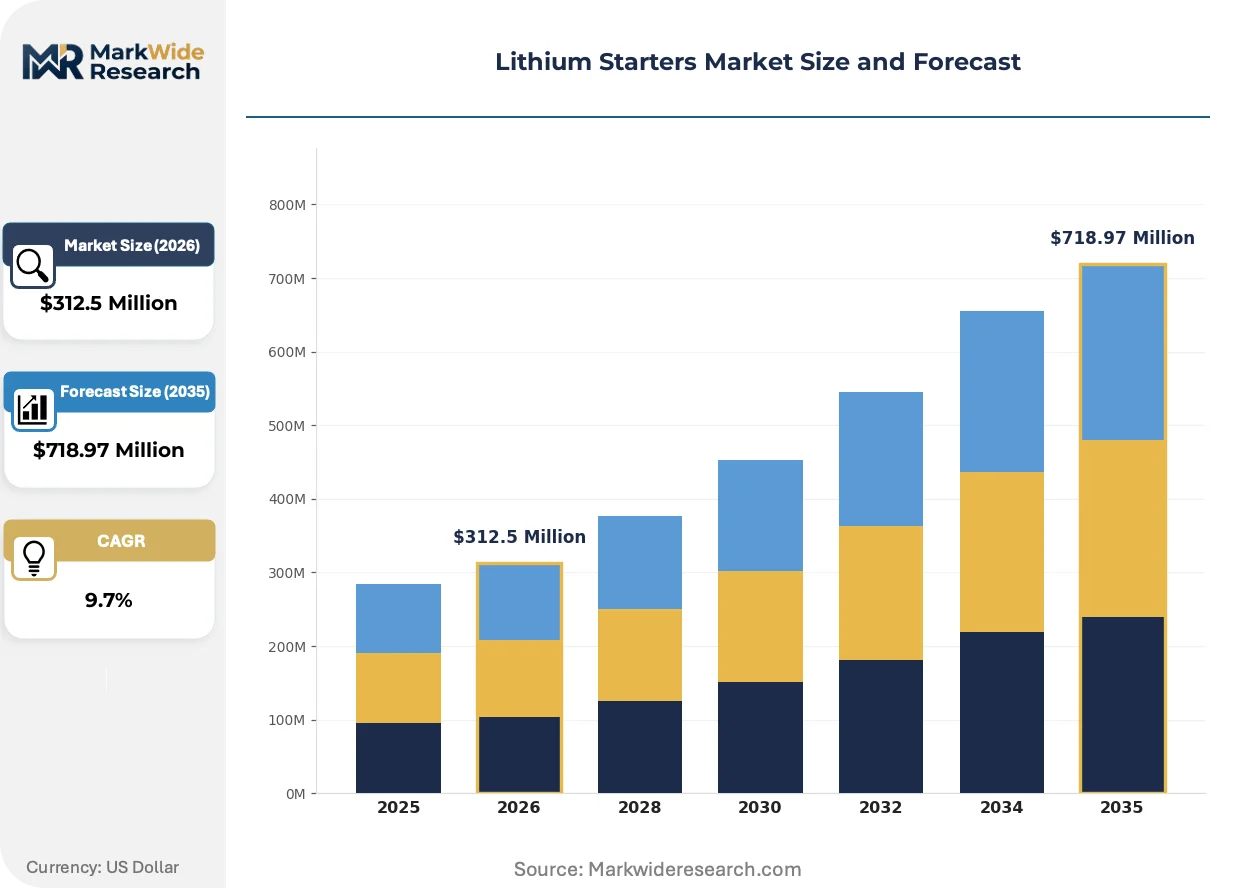
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $718.97 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium Ion, Nickel Metal Hydride, Supercapacitor End User: Automotive, Marine, Industrial, Renewable Energy Technology: AGM, Gel, Flooded, Lithium Polymer Application: Starter Motor, Backup Power, Electric Vehicle, UPS |
| Companies Covered | Clarios, GS Yuasa, Camel Group, Fengfan, COSMX, CATL, A123 Systems, BYD, EnerSys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Starters Market Trends and Innovations
Cell format standardization and thermal management integration are rewriting competitive boundaries in lithium starter design. Manufacturers are racing to lock in cathode material supply agreements while differentiating through cold-start performance validation.
Lithium iron phosphate cylindrical formats are rewriting the economics of commercial vehicle cranking systems. Fleet procurement departments are specifying 26650 and 26700 cell configurations for their superior cycle life in start-stop applications. This format consolidation is compressing development budgets for prismatic alternatives while concentrating tooling investments among Jiangsu and Guangdong producers.
China's NMPA enforcement of GB/T 31484 cycling endurance standards is altering import qualification pathways. Foreign manufacturers must demonstrate 500+ deep discharge cycles at minus 18 degrees Celsius to secure market access. European and Japanese suppliers are responding by establishing in-country testing partnerships rather than relying on third-party laboratory certifications.
Marine distributors are unbundling installation services from hardware procurement to capture margin from yacht and commercial vessel operators. This channel restructuring displaces traditional automotive parts wholesalers in salt-water cranking applications. The shift is most visible in Mediterranean and Southeast Asian ports where corrosion-resistant lithium starters command three-tier pricing stratification based on conformal coating grade.
Lithium Starters Market Segmentation
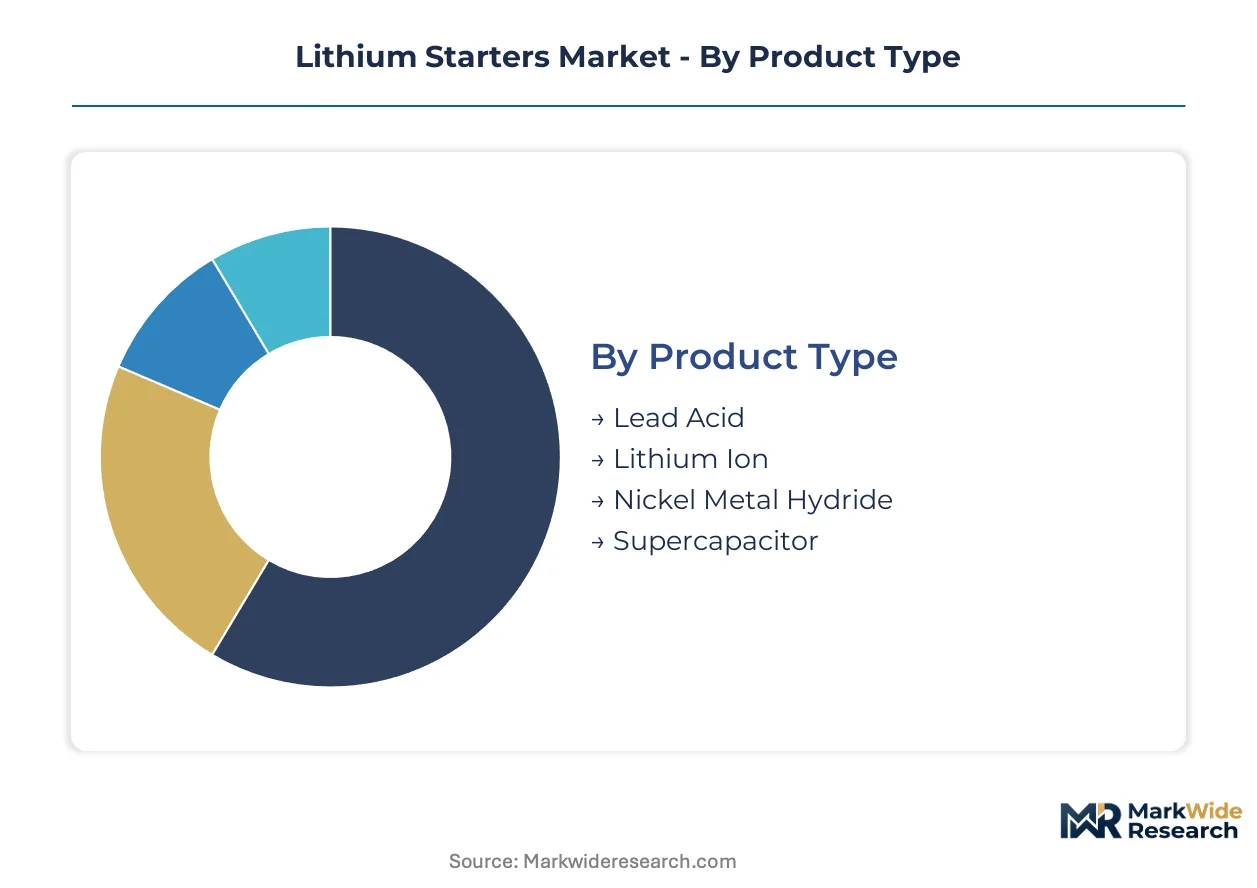
Lithium starter procurement patterns diverge sharply between high-volume automotive platforms and premium marine specifications. Understanding these splits enables suppliers to align cathode material sourcing with margin expectations and certification requirements.
Product Type:
Volume concentration sits with legacy chemistries, while premium capture belongs to advanced lithium formats.
- Lithium Ion:Engineered with lithium iron phosphate or lithium manganese oxide cathodes, these cells deliver cold cranking amperage above 800A at sub-zero temperatures. Automotive OEMs in Germany and Japan are specifying lithium ion for electric vehicle starter motor configurations where weight reduction directly extends driving range.
- Lead Acid:Flooded and AGM variants dominate aftermarket replacement cycles due to established recycling infrastructure and alternator compatibility. Fleet operators across North American long-haul corridors continue procuring lead acid for legacy truck platforms where lithium voltage curves require software recalibration.
- Nickel Metal Hydride:Hybrid vehicle auxiliary systems in Japanese domestic market models specify NiMH for temperature stability in engine bay mounting positions.
- Supercapacitor:Rapid discharge characteristics suit start-stop systems in European urban delivery vehicles with high cycle frequency demands.
Today's leader: Lead Acid. Tomorrow's challenger: Lithium Ion.
End User:
Customer procurement authority separates fleet-scale automotive contracts from specification-driven marine orders.
- Automotive:Passenger vehicle OEMs and commercial fleet operators drive unit volume through platform-standardized cranking systems. China's Jiangsu manufacturing corridor supplies cylindrical cell formats to domestic automotive assembly plants under GB/T cycling endurance compliance.
- Marine:Yacht builders and commercial vessel operators command premium pricing for salt corrosion resistance. Mediterranean and Southeast Asian ports see three-tier pricing stratification based on conformal coating IP and installation service bundling.
- Industrial:Construction equipment and material handling fleets in Germany specify lithium starters for idle fuel reduction through auxiliary power unit downsizing.
- Renewable Energy:Solar and wind farm operators in Texas and California deploy lithium starters for backup generator cranking in grid-tied storage installations.
Automotive commands volume. Marine captures margin. Industrial is climbing fastest.
Technology:
Electrolyte formulation maturity separates proven flooded designs from emerging lithium polymer architectures.
- AGM:Absorbed glass mat construction delivers vibration resistance for commercial vehicle applications. European OEMs specify AGM for start-stop systems under EU F-Gas Regulation compliance pathways.
- Lithium Polymer:Pouch cell formats enable custom form factors for electric vehicle auxiliary battery compartments. South Korean producers are scaling lithium polymer capacity for premium automotive platforms.
- Gel:Immobilized electrolyte suits deep-cycle marine applications in Nordic fishing fleets with extreme temperature exposure.
- Flooded:Lowest cost per ampere-hour sustains aftermarket dominance in emerging market vehicle parcs.
AGM holds installed base. Lithium Polymer shows steepest expansion trajectory.
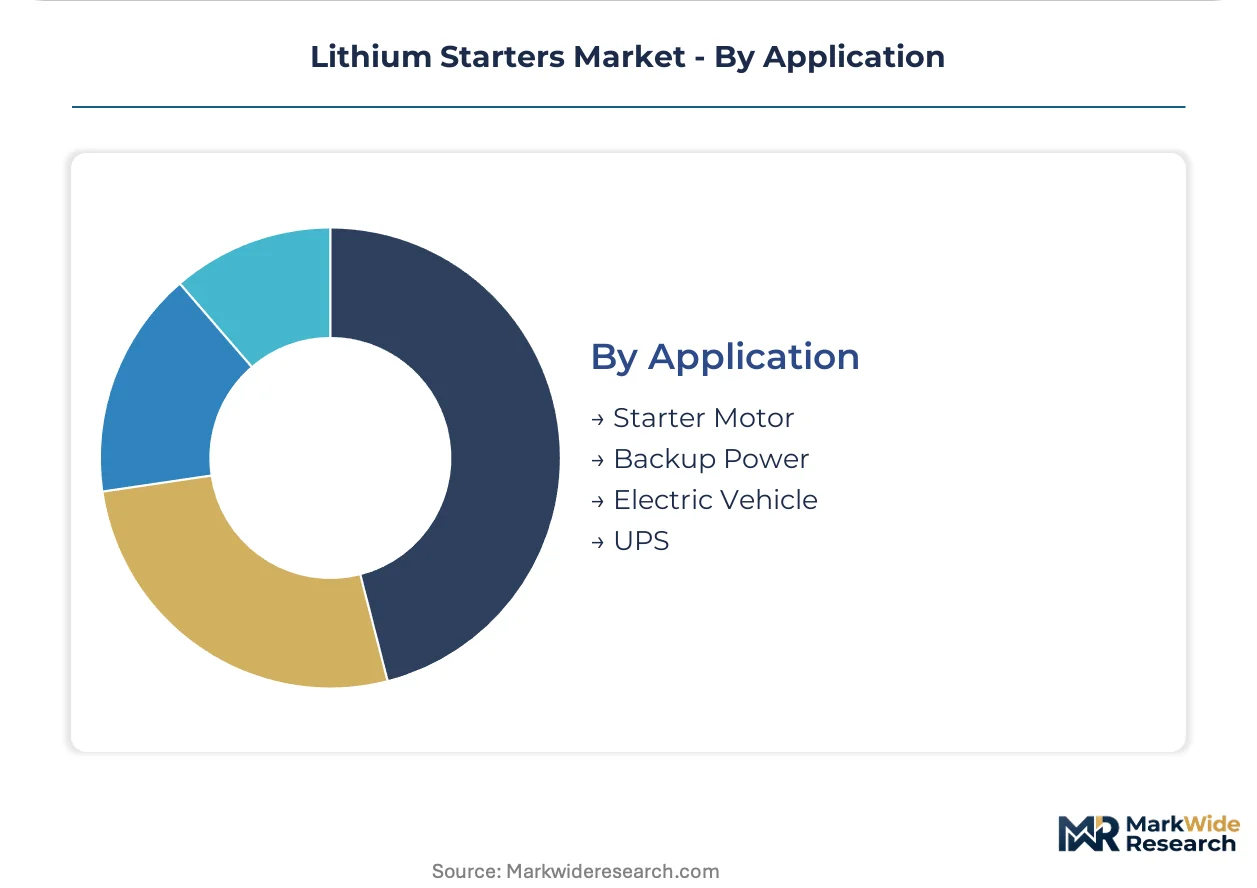
Application:
Functional requirements split between immediate cranking duty and sustained backup power delivery.
- Starter Motor:Internal combustion engine ignition demands high burst current with minimal voltage sag. Chinese cylindrical cell producers are recalibrating capacity allocation toward starter-specific lithium iron phosphate formats.
- Electric Vehicle:Auxiliary 12V systems require low self-discharge for extended parking periods. Japanese OEM supply agreements specify proprietary thermal management designs for EV cranking reliability.
- Backup Power:Telecommunications and data center operators specify lithium starters for generator auto-start sequences in India and Southeast Asia.
- UPS:Uninterruptible power supply integration favors lithium manganese oxide for high-rate discharge in financial services infrastructure.
Starter Motor anchors revenue. Electric Vehicle is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing lithium starter production maps as manufacturers chase cost-of-compliance gaps between China's streamlined GB/T certification and the EU's F-Gas electrolyte restrictions. Assembly capacity is migrating toward jurisdictions with faster market-access timelines.
China
Automotive OEM procurement and commercial fleet electrification drive domestic absorption of cylindrical lithium iron phosphate cells. NMPA enforces GB/T 31484 cycling endurance standards that compress import windows for foreign suppliers. Jiangsu and Guangdong manufacturing corridors concentrate cathode material refining and cell assembly under unified provincial industrial policies.
Germany
Long-haul trucking fleets specify lithium starters for auxiliary power unit downsizing and idle fuel reduction mandates. KBA vehicle-type approval integrates EU F-Gas Regulation compliance into battery system homologation. Bavaria and Baden-Württemberg host OEM engineering centers that validate cold-cranking performance for Arctic logistics contracts.
United States
Electric vehicle platform launches and renewable energy backup generator deployments expand addressable demand. EPA domestic content rules under the IRA reshape cathode precursor sourcing toward North American recycling infrastructure. Michigan and Texas manufacturing zones attract cell-to-pack assembly investments seeking IRA qualification.
Japan
Hybrid vehicle auxiliary battery replacement cycles and marine yacht specifications sustain premium pricing tiers. METI industrial standards govern lithium starter safety validation for domestic OEM supply agreements. Kansai and Chubu industrial belts concentrate thermal management design expertise for sub-zero cranking applications.
South Korea
Electric vehicle platform auxiliary systems and telecommunications backup power contracts diversify end-use exposure. MFDS battery safety notifications align with UN 38.3 transportation testing for export-oriented production. Seoul Capital Area and Busan-Ulsan corridors host pouch cell capacity scaling for custom form-factor automotive programs.
Lithium Starters Market Competitive Landscape
Chinese producers anchor one tier through cylindrical cell volume and integrated cathode supply; Japanese and Korean specialists hold premium positions through thermal management IP and OEM validation relationships. The structure concentrates around three strategic archetypes: diversified battery conglomerates with recycling infrastructure, pure-play lithium starter engineers with conformal coating patents, and automotive-tier suppliers with alternator control software integration. Capacity expansion and backward integration into cathode precursor production dominate competitive moves.
Within the diversified conglomerate tier, Clarios and CATL exemplify scale-driven positioning through captive material flows and multi-region assembly footprints. GS Yuasa occupies a specialist position anchoring Japanese OEM supply relationships through proprietary validation protocols. These three entities represent the dominant competitive anchors shaping procurement authority and certification pathway investments across automotive and marine end-use segments.
| Leading Market Players |
|---|
| Clarios |
| GS Yuasa |
| Camel Group |
| Fengfan |
| COSMX |
| CATL |
| A123 Systems |
| BYD |
| EnerSys |
| Others |
Pricing and Supply Chain Analysis
Captive cathode material production in Jiangsu and Guangdong manufacturing corridors anchors both supply security and pricing power for Chinese cylindrical cell producers serving automotive OEM procurement. This integration pattern compresses third-party supplier margins while enabling just-in-time cost pass-through to fleet operators specifying lithium iron phosphate formats.
Pricing Analysis
Distributor margin capture in marine salt-corrosion applications commands three-tier pricing stratification based on conformal coating grade and installation service bundling. Price differentiation separates premium yacht specifications with proprietary thermal management from standard commercial vessel configurations and economy aftermarket replacements. Cost compression in automotive lithium ion starter tiers is intensifying because fleet procurement departments are consolidating volume under long-term offtake agreements. Commercial vehicle operators demonstrate highest price sensitivity due to total-cost-of-ownership calculations, while marine yacht builders remain least sensitive given specification-driven procurement authority.
Supply Chain Analysis
Battery recycling flows through Clarios North American infrastructure are reshaping cathode precursor sourcing toward domestic qualification under EPA domestic content rules. Geographic supply concentration centers on China for refined lithium processing, South Korea for pouch cell capacity, and Japan for thermal management component fabrication. Raw material dependencies draw from South American salt flats for lithium carbonate, Australian spodumene concentrates, and Chinese graphite anode production. Single-region processing vulnerability creates geopolitical exposure for non-domestic assemblers. Distribution runs through automotive Tier 1 suppliers for OEM platforms and marine distributors for salt-water cranking applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by fleet procurement departments specifying 26650 and 26700 cell configurations for superior cycle life in start-stop applications.
For Market Incumbents: Deploy backward integration into cathode precursor production to defend margin position against South Korean pouch cell expansion. Lock in GB/T 31484 cycling endurance certification partnerships in China to compress 18-24 month import timelines for foreign competitors. Anchor Japanese OEM supply relationships through proprietary thermal management validation protocols that emerging entrants cannot replicate. For New Entrants and Emerging Players: Capture marine salt-corrosion specification white-space in Mediterranean and Southeast Asian ports where conformal coating IP concentrates margin capture. Target industrial construction equipment fleets in Germany specifying lithium starters for idle fuel reduction through auxiliary power unit downsizing. Lead with installation service bundling to displace traditional automotive parts wholesalers in corrosion-resistant applications. For Investors and Strategic Acquirers: Roll-up economics work for pure-play lithium starter engineers with conformal coating patents because marine three-tier pricing stratification enables margin extraction unavailable in commoditized automotive tiers. Long-term viability centers on thermal management convergence with battery management systems for sub-zero cranking performance. Monitor EPA domestic content rule enforcement intensity as inflection indicator for North American assembly investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Production | Captive lithium carbonate flows from South American salt flats secure Jiangsu manufacturing corridor cost positions. |
| GB/T Cycling Endurance Certification Partnership | In-country testing relationships with Chinese NMPA compress 18-24 month import qualification timelines. |
| Conformal Coating IP Development | Proprietary marine corrosion resistance enables three-tier pricing stratification in Mediterranean yacht specifications. |
| Thermal Management System Convergence | Phase-change material integration with battery management systems unlocks Arctic logistics contract validation. |
| North American Recycling Infrastructure Expansion | Clarios-style cathode material feedstock recovery aligns with EPA domestic content rules under IRA qualification. |
Research Methodology
Direct dialogue with automotive Tier 1 supplier procurement officers, marine distributor operations heads, OEM platform engineers, and aftermarket service directors grounded qualitative findings in operational reality. Secondary validation drew from NMPA GB/T standard filings, EU F-Gas Regulation compliance disclosures, EPA domestic content guidance, vehicle production databases, and customs trade records for lithium carbonate and spodumene concentrate flows. Bottom-up cell format demand modeling and top-down automotive platform electrification projections were triangulated against fleet operator specification surveys.
Segment-level value outputs across the analysis window reflect disaggregated modeling of lithium iron phosphate cylindrical formats, lithium manganese oxide alternatives, and legacy lead-acid displacement curves. CAGRs were derived from regression-weighted platform penetration assumptions for electric vehicle auxiliary systems and commercial vehicle start-stop configurations. Industry-specific forecast inputs incorporated Jiangsu manufacturing corridor capacity utilization rates and METI thermal management design validation timelines.
Underlying measurement precision varies by segment; automotive OEM procurement carries tighter precision than fragmented marine distributor channels. Forecasts reflect assumptions about NMPA enforcement consistency, EU F-Gas electrolyte formulation pathway stability, and South American salt flat mining output constraints. Practitioners should monitor EPA domestic content rule finalization, GB/T 31484 testing partnership establishment rates, and fleet operator lithium starter specification conversion velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Yacht Battery Market
Batteries
Molten Salt Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Smart Battery Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Japan Rechargeable Battery Market
Batteries
United States Household Battery Market
Batteries
Wood-Based Batteries Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Global Marine Battery Market
Batteries
South and Central America Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
Battery Separators Market
Batteries
South Asia Battery Market