
 Power Battery Recycling Market | 2026-2036
Power Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Power Battery Recycling Market Insights
Chinese hydrometallurgical refiners is shifting capacity toward direct lithium recovery from black mass. Umicore leverages integrated smelter-refinery complexes across Belgium and Poland to dominate European cathode material supply. GEM Co., Ltd. anchors its position through captive feedstock agreements with domestic automakers. Redwood Materials specializes in closed-loop nickel and cobalt recovery for US-based cell manufacturers.
Power battery recycling encompasses the collection, disassembly, and material recovery of spent electrochemical cells to extract lithium, cobalt, nickel, and manganese at purities exceeding battery-grade thresholds. Hydrometallurgy now leads technology deployment due to lower energy intensity and higher lithium yields compared with pyrometallurgical routes. Automotive end users drive structural volume as OEMs mandate recycled content quotas across their supply bases. Material recovery commands the dominant margin pool within process type segmentation, while direct recycling remains nascent but attracts R&D capital for its potential to preserve cathode crystalline structure.
EU Battery Regulation and REACH compliance frameworks in Europe mandate minimum recycled content ratios and restrict hazardous substance thresholds, forcing non-compliant material out of market access. EPA hazardous waste rules under RCRA in the United States govern interstate transport and storage protocols for end-of-life lithium-ion cells. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries will determine which recycling technologies achieve commercial scale first.
Market Dynamics
EU Battery Regulation mandates are forcing automakers to secure certified recycled cobalt and lithium supply chains, compressing compliance timelines and concentrating feedstock access among hydrometallurgical refiners with proven purity certification.
Growth Catalysts
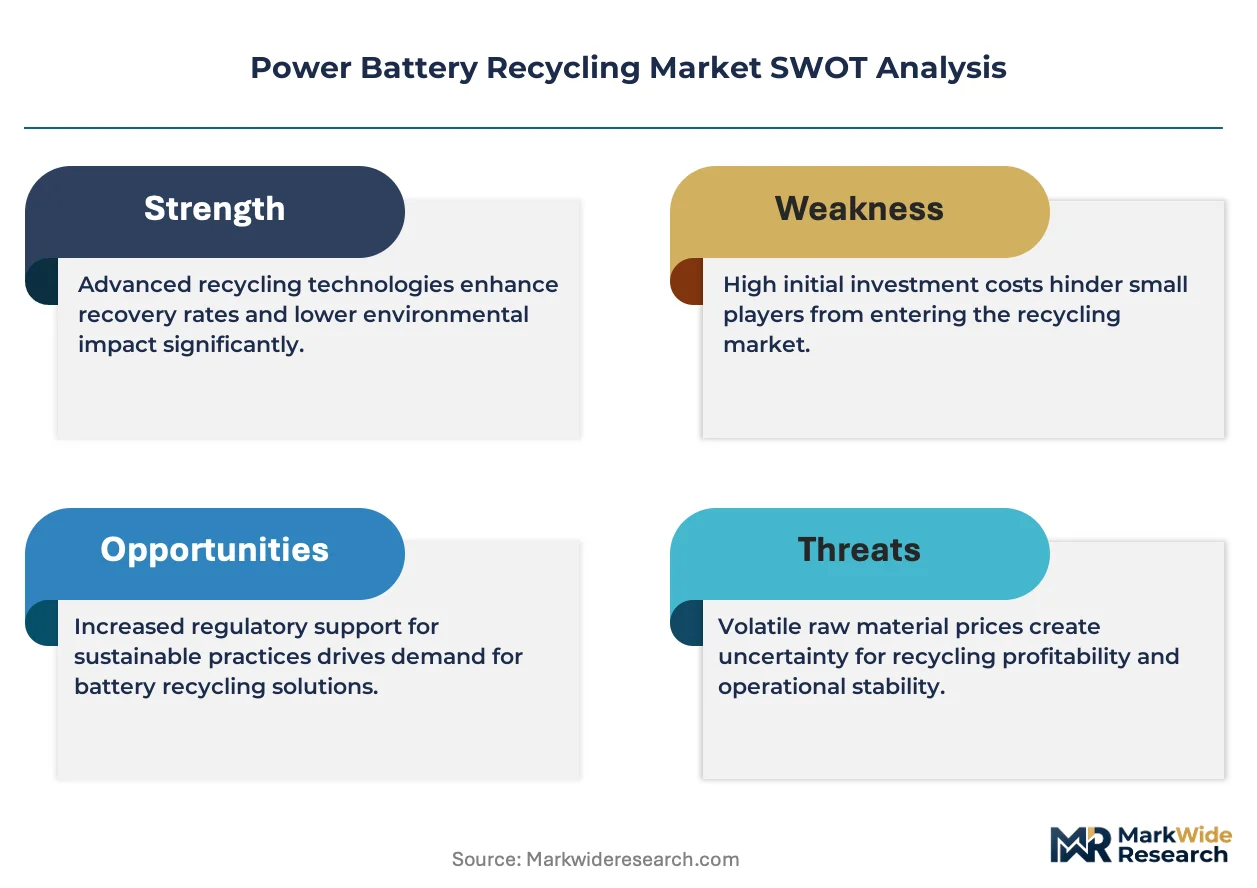
- EU recycled content mandates:Battery Regulation minimum thresholds for recovered lithium, cobalt, and nickel create guaranteed offtake for certified refiners. Automotive OEMs must source from compliant suppliers or face market exclusion.
- Black mass processing economics:Hydrometallurgical routes extract lithium carbonate at battery-grade purity with lower energy intensity than pyrometallurgical alternatives. Refiners capture margin premiums from cathode precursor manufacturers.
- Automotive end-of-life volume:First-generation EV batteries from 2015-2018 production cycles are reaching retirement age. OEMs require closed-loop material return to meet Scope 3 emissions targets and secure supply.
Market Restraints
- Cathode precursor concentration in China:Over 80% of global black mass refining capacity sits with Chinese hydrometallurgical operators. European and North American automakers face feedstock security risks from single-geography dependence.
- Lithium price volatility:Primary lithium carbonate from hard-rock mining and brine extraction fluctuates with EV demand cycles. Secondary lithium recovery economics become marginal when primary prices collapse below $15,000 per ton.
- Transport classification friction:EPA RCRA hazardous waste rules and ADR road transport regulations classify end-of-life lithium-ion cells as dangerous goods. Interstate and cross-border movement requires specialized packaging, documentation, and carrier certification.
Strategic Opportunities
- Direct recycling technology maturation:Startups and research consortia are developing cathode regeneration processes that preserve crystalline structure. Successful commercialization would bypass full dissolution and re-synthesis, cutting processing costs by 30-40%.
- US domestic supply chain construction:IRA production tax credits and the Bipartisan Infrastructure Law fund regional recycling hubs. States with existing automotive manufacturing clusters—Michigan, Tennessee, South Carolina—offer siting advantages for integrated collection-to-refinery operations.
- Stationary energy storage second-life applications:Retired EV batteries retain 70-80% capacity. Repurposing for grid storage extends asset life by 5-10 years before final recycling, creating interim revenue streams and deferred material recovery.
Industry Challenges
- Battery-grade lithium carbonate certification timelines:New entrants require 18-24 months to validate product purity against cathode manufacturer specifications. Automakers will not qualify unproven suppliers for their cell contracts.
- Skilled pyrometallurgist and hydrometallurgist scarcity:The talent pool for high-temperature and solvent-extraction process engineering is concentrated at incumbent mining and primary metals companies. Universities have cut extractive metallurgy programs for two decades.
- Feedstock collection infrastructure fragmentation:Spent batteries accumulate at thousands of independent auto dealers, repair shops, and dismantlers. Reverse logistics networks lack standardized tracking, creating supply uncertainty for refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Battery Recycling Market |
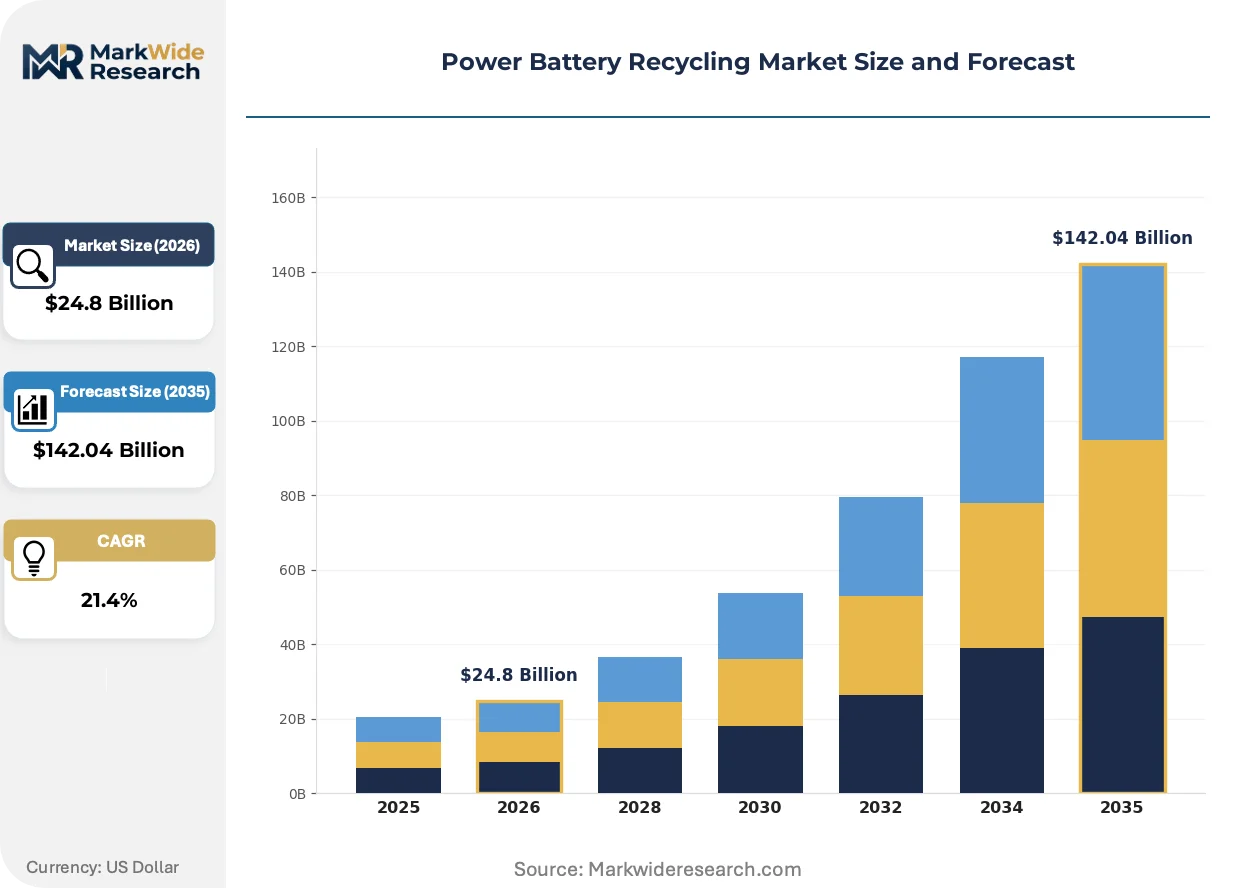
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $142.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pyrometallurgy, Hydrometallurgy, Biotechnological Processes, Direct Recycling End User: Automotive, Consumer Electronics, Industrial Applications, Renewable Energy Systems Material Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Others Process Type: Collection, Disassembly, Material Recovery, Reconditioning |
| Companies Covered | Umicore, GEM Co., Ltd., Li-Cycle Holdings Corp., Glencore, Brunp Recycling Technology, Redwood Materials, Contemporary Amperex Technology Co., Limited., Ecobat, Fortum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Battery Recycling Market Trends and Innovations
Direct cathode recycling and modular hydrometallurgical systems are compressing the distance between collection points and material recovery, reducing transport costs and enabling distributed processing architectures.
Modular hydrometallurgical units are decentralizing battery recycling infrastructure. Containerized direct lithium recovery systems from black mass allow deployment near automotive dismantlers or urban collection hubs. European refiners in Belgium and Poland are piloting these units to reduce feedstock transport distances below 200 kilometers. Distributed processing is compressing the traditional smelter-refinery complex model that concentrated operations in industrial port zones.
REACH authorization requirements for cobalt compounds are tightening material traceability obligations. ECHA mandates force refiners to document conflict-mineral-free and child-labor-free sourcing for recovered cobalt. Cathode precursor manufacturers serving German and French automakers must maintain batch-level chain-of-custody records. Compliance costs are filtering smaller traders from the European supply base.
Automotive OEMs are consolidating recycling contracts under long-term offtake agreements with purity-linked pricing. Cell manufacturers previously sourced recovered materials through spot markets and commodity traders. BMW, Volkswagen, and Mercedes-Benz now require 5-10 year supply commitments with guaranteed battery-grade lithium carbonate and cobalt sulfate specifications. Contract structures are displacing merchant market volumes in Western Europe.
Power Battery Recycling Market Segmentation
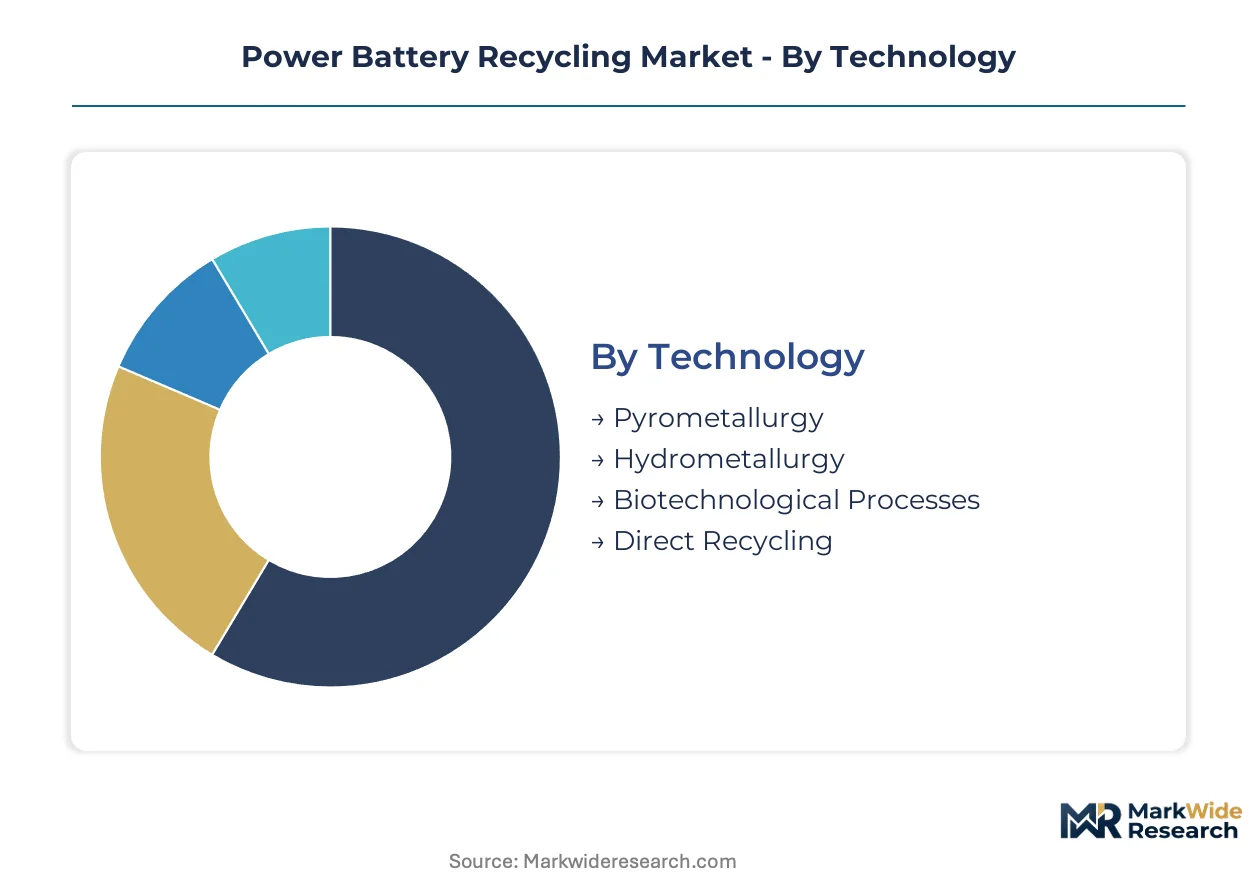
Power battery recycling segmentation reveals how technology choices, end-user requirements, and material chemistry interact to determine recovery economics. Each dimension carries distinct margin profiles and regulatory compliance burdens that shape competitive positioning across the value chain.
Technology:
Upgrade cycles from first-generation EV batteries are forcing refiners to select recovery routes based on lithium yield and energy intensity trade-offs.
- Hydrometallurgy:Solvent extraction and precipitation processes recover lithium carbonate at battery-grade purity with 40-60% lower energy consumption than thermal alternatives. German and Belgian refiners deploy this route to meet EU Battery Regulation recycled content certification timelines.
- Pyrometallurgy:High-temperature smelting concentrates cobalt and nickel into alloy intermediates suitable for stainless steel feedstock, though lithium volatilizes and requires secondary recovery. Chinese integrated smelters leverage scale advantages for black mass preprocessing before hydrometallurgical refining.
- Biotechnological Processes:Bioleaching using acidophilic bacteria selectively dissolves transition metals at ambient temperature and pressure, reducing reagent costs for low-grade feedstock.
- Direct Recycling:Cathode regeneration preserves crystalline structure through relithiation, bypassing full dissolution and re-synthesis for 30-40% cost reduction potential.
Volume placements concentrate in hydrometallurgy; the faster expansion belongs to direct recycling.
End User:
Customer procurement patterns diverge sharply between long-term contract automotive demand and fragmented spot-market electronics recycling.
- Automotive:OEMs mandate closed-loop material return through 5-10 year offtake agreements with purity-linked pricing. BMW, Volkswagen, and Mercedes-Benz require guaranteed battery-grade lithium carbonate and cobalt sulfate specifications.
- Consumer Electronics:Smartphone and laptop batteries generate dispersed, low-volume feedstock collected through retail take-back programs and municipal e-waste streams with inconsistent chemistry documentation.
- Industrial Applications:Forklift and stationary power systems produce predictable retirement schedules with standardized lead-acid and lithium-ion formats suitable for automated disassembly.
- Renewable Energy Systems:Grid-scale battery installations create concentrated decommissioning volumes at utility-owned sites, though second-life repurposing delays final recycling by 5-10 years.
Contract structures favor automotive; the steepest expansion trajectory sits with renewable energy systems as utility-scale deployments mature.
Material Type:
Feedstock chemistry determines recovery pathway selection and purity certification complexity for refiners.
- Lithium-Ion:NMC and LFP cathode formulations dominate EV applications, requiring hydrometallurgical separation of lithium, cobalt, nickel, and manganese with distinct precipitation chemistries for each element.
- Lead-Acid:Mature pyrometallurgical infrastructure achieves 99% lead recovery rates through conventional smelting, with established secondary lead markets in automotive starter battery replacement cycles.
- Nickel-Cadmium:Aerospace and industrial backup power applications generate cadmium-bearing waste classified as hazardous under EPA RCRA and REACH restrictions, requiring specialized thermal treatment.
- Others:Sodium-ion and solid-state chemistries in pilot production lack scaled recycling infrastructure, though their simpler material systems promise lower recovery complexity.
Processing volumes concentrate in lithium-ion; the fastest capacity additions target emerging solid-state formats.
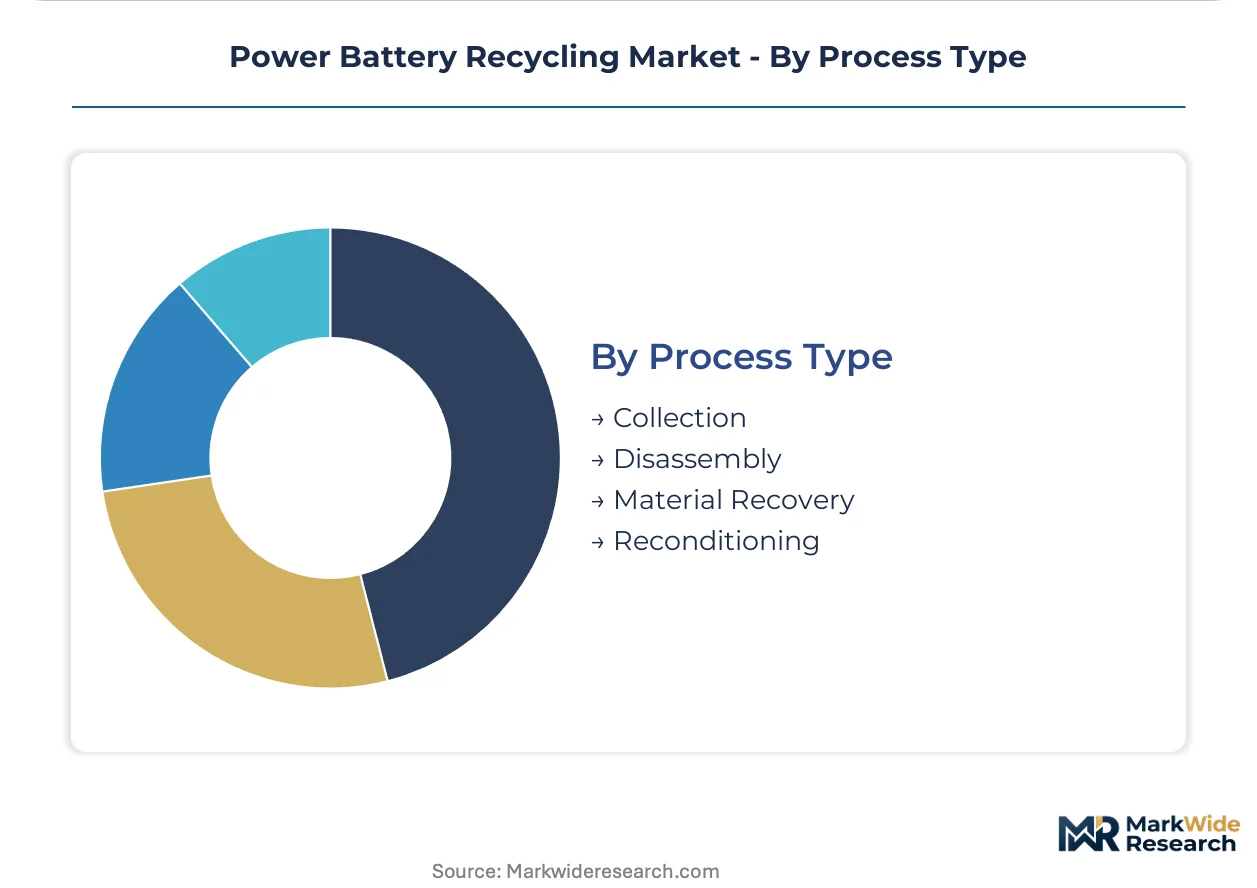
Process Type:
Margin capture shifts downstream from logistics toward high-purity material recovery and cathode precursor synthesis.
- Material Recovery:Hydrometallurgical refiners extract battery-grade lithium carbonate, cobalt sulfate, and nickel sulfate commanding premium pricing from cathode precursor manufacturers under long-term automotive contracts.
- Collection:Reverse logistics networks aggregate spent batteries from thousands of independent auto dealers and dismantlers, with transport costs consuming 15-25% of total recovery economics due to hazardous goods classification.
- Disassembly:Automated cell extraction and electrolyte drainage systems reduce labor costs and fire risks, though pack designs vary widely across OEM platforms requiring flexible tooling.
- Reconditioning:Second-life screening and module reassembly for stationary storage extends asset value before final recycling, creating interim revenue streams.
Value capture concentrates in material recovery; the most rapid scaling occurs in reconditioning as second-life markets formalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Black mass refining capacity concentrates in China's Jiangxi and Hunan provinces, where hydrometallurgical clusters process feedstock from domestic EV retirement waves. Germany, Belgium, and Poland anchor European cathode precursor recovery. The United States builds regional hubs through IRA-funded infrastructure.
China
CATL and BYD retirement volumes from 2015-2018 EV fleets drive feedstock availability. MEE enforces hazardous waste tracking for interstate black mass movement. Ganzhou and Xiangtan refining clusters dominate lithium carbonate purification for battery-grade certification.
Germany
BMW, Volkswagen, and Mercedes-Benz mandate certified recycled cobalt content in cell contracts. EU Battery Regulation thresholds force compliance investments by 2027. North Rhine-Westphalia hosts Umicore's integrated smelter-refinery complex serving European cathode manufacturers.
United States
IRA production tax credits incentivize domestic recycling hub construction. EPA RCRA governs hazardous waste classification for lithium-ion transport. Michigan and Tennessee automotive clusters attract integrated collection-to-refinery operations from emerging processors.
Belgium
Umicore's Hoboken facility anchors European cathode material supply with integrated pyrometallurgical-hydrometallurgical processing. REACH authorization requirements tighten cobalt compound traceability. Antwerp port logistics enable black mass import from dismantlers across France and the Netherlands.
Poland
EU structural funds support battery valley development near LG Energy Solution and SK On cell plants. Battery Regulation recycled content mandates create guaranteed offtake for certified refiners. Lower Silesia hosts pilot modular hydrometallurgical units reducing feedstock transport distances.
Power Battery Recycling Market Competitive Landscape
Global majors compete with regional champions across technology licensing and feedstock access. Market structure shows moderate consolidation with tiered specialization: integrated miners, dedicated recyclers, and OEM-captive operators. Three archetypes dominate: Chinese hydrometallurgical refiners with captive black mass supply, European integrated smelter-refinery complexes, and North American closed-loop specialists serving domestic cell manufacturers. Competitive moves center on long-term offtake agreements with automotive OEMs and modular processing unit deployment near collection hubs.
Within the integrated European tier, Umicore exemplifies the smelter-refinery complex model. Among Chinese operators, GEM Co., Ltd. and Brunp Recycling Technology occupy positions tied to domestic automaker feedstock agreements. Redwood Materials represents the North American closed-loop archetype focusing on nickel and cobalt recovery for US-based cell manufacturing.
| Leading Market Players |
|---|
| Umicore |
| GEM Co., Ltd. |
| Li-Cycle Holdings Corp. |
| Glencore |
| Brunp Recycling Technology |
| Redwood Materials |
| Contemporary Amperex Technology Co., Limited. |
| Ecobat |
| Fortum |
| Others |
Pricing and Supply Chain Analysis
Black mass transport costs from automotive dismantlers to hydrometallurgical refiners cascade through three pricing tiers based on lithium carbonate purity certification and offtake contract duration. Chinese refiners in Ganzhou and Xiangtan capture margin premiums from battery-grade lithium carbonate sold under long-term automotive contracts, while spot-market traders absorb volatility from primary lithium price swings.
Pricing Analysis
Warranty-backed purity certification is unbundled from base material pricing, with automakers paying 15-25% premiums for guaranteed battery-grade lithium carbonate and cobalt sulfate specifications under 5-10 year offtake agreements. Contract-based long-term offtake structures dominate, with price differentiation driven by certification grade against cathode manufacturer specifications and volume scale commitments. Cost compression in spot-market transactions is intensifying because primary lithium carbonate from hard-rock mining collapses below secondary recovery economics. Tier 2 and Tier 3 cathode precursor manufacturers exhibit highest price sensitivity, while German and French automakers prioritize supply security over unit cost.
Supply Chain Analysis
Feedstock supply rests on Chinese hydrometallurgical refiners in Jiangxi and Hunan provinces, Belgian integrated smelter-refinery complexes, and emerging North American processors in Michigan and Tennessee. Lithium-ion black mass, cobalt-bearing alloy intermediates, and battery-grade lithium carbonate constitute the critical input dependencies. Single-source vulnerability concentrates in Chinese black mass refining capacity, where over 80% of global processing sits within one geography. Distribution runs through specialized hazardous waste carriers certified under EPA RCRA and ADR regulations, with reverse logistics networks aggregating from thousands of independent auto dealers and dismantlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrometallurgical lithium recovery is displacing pyrometallurgical routes as the dominant processing technology, rendering high-temperature smelting investments stranded across European and North American legacy infrastructure.
For Market Incumbents: Anchor market position through captive feedstock agreements with domestic automakers facing EU Battery Regulation compliance deadlines. Umicore and GEM Co., Ltd. demonstrate the defensive value of integrated smelter-refinery complexes with proven purity certification timelines. Incumbents must accelerate backward integration into black mass collection networks to offset feedstock security risks from Chinese capacity concentration. For New Entrants and Emerging Players: Modular direct lithium recovery systems from containerized hydrometallurgical units offer the most penetrable wedge into fragmented North American and European markets lacking distributed processing infrastructure. Target second-life reconditioning services for utility-scale battery decommissioning as an interim revenue bridge before final material recovery capabilities mature. Partner with automotive dismantler networks for guaranteed feedstock access rather than competing for spot-market black mass. For Investors and Strategic Acquirers: First-generation EV battery retirement waves from 2015-2018 production cycles are the leading indicator that feedstock volume inflection is imminent across Western markets. Five-to-ten year viability favors processors with demonstrated battery-grade lithium carbonate certification and long-term automotive offtake agreements already in force. Watch for EPA RCRA rulemaking on lithium-ion transport classification as the signal for US domestic supply chain construction acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Agreement | BMW, Volkswagen, and Mercedes-Benz mandate 5-10 year supply commitments with purity-linked pricing structures. |
| Modular Processing Deployment | Containerized hydrometallurgical units reduce feedstock transport distances below 200 kilometers near automotive clusters. |
| Backward Integration into Collection | Reverse logistics networks aggregate spent batteries from thousands of independent auto dealers and dismantlers. |
| Direct Recycling Technology Licensing | Cathode regeneration processes bypass full dissolution for 30-40% cost reduction potential. |
| Second-life Reconditioning Capacity | Grid-scale battery repurposing extends asset life by 5-10 years before final recycling. |
Research Methodology
Document review covered EU Battery Regulation implementation guidance, EPA RCRA hazardous waste classification rulings, and ECHA REACH authorization requirements for cobalt compounds, complemented by interviews with hydrometallurgical refinery operations directors, automotive OEM sustainability procurement leads, cathode precursor manufacturer technical specifications managers, and hazardous waste logistics carriers. Secondary validation drew from customs trade data on black mass movements, SEC filings of listed recycling operators, and national hazardous waste tracking databases. Bottom-up feedstock volume estimates from automotive retirement projections were triangulated against top-down market value assessments.
Historical capacity deployment patterns were cross-referenced against expert panel input on technology adoption timelines across the projection horizon. Segmentation dimensions modeled include technology route, end-user procurement pattern, battery chemistry format, and process type margin capture. CAGRs were derived from volume-weighted growth trajectories within each segment. Forecast inputs incorporated EU Battery Regulation recycled content threshold compliance schedules and IRA production tax credit eligibility for domestic recycling hub construction.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to transport classification rules, breakthrough direct recycling commercialization timelines, and primary lithium carbonate price collapse scenarios. Forecasts reflect documented assumptions on feedstock availability from first-generation EV retirement waves. Regulatory divergence between jurisdictions, technology yield improvements, and second-life market formalization warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Global Primary Battery Recycling Market