
 Lithium-Fluorinated Graphite Batteries Market | 2026-2036
Lithium-Fluorinated Graphite Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Fluorinated Graphite Batteries Market Insights
UN 38.3 lithium battery transport certification is reorganizing which suppliers qualify for OEM qualification programs. COBRA leverages its automotive channel relationships to sustain aftermarket penetration. Stanley Black & Decker anchors its position through tool-platform battery compatibility requirements. Shenzhen NianLun Electronic competes on cost-optimized cell designs for portable starter applications.
Lithium-fluorinated graphite batteries utilize carbon monofluoride (CFx) cathode chemistry paired with lithium metal anodes, delivering energy densities exceeding conventional lithium-ion systems through a solid-state fluorinated carbon lattice structure. These cells serve primary power roles in military equipment, medical implants, and remote sensing devices where replacement cycles are impractical. The cylindrical form factor dominates current procurement volumes due to established winding equipment and thermal management predictability. Electric vehicle applications represent the fastest-expanding end-user segment as OEMs evaluate CFx cells for auxiliary power modules. Anode materials capture the deepest margin pools because fluorinated graphite synthesis requires controlled atmosphere processing at specialized facilities.
FAA hazardous materials regulations govern air transport eligibility for cells above lithium content thresholds, while EPA waste classification rules affect end-of-life handling costs for industrial users. China's GB standards and Japan's JIS certification frameworks create parallel compliance tracks that fragment supplier qualification investments. Stakeholders must monitor evolving UN Manual of Tests and Criteria revisions that could redefine packaging and shipping requirements for high-specific-energy primary cells.
Market Dynamics
Defense procurement programs in the United States are accelerating qualification timelines for high-energy-density primary cells, compressing supplier certification cycles and reshaping manufacturing capacity allocation across fluorinated graphite synthesis facilities.
Growth Catalysts
- UN 38.3 Transport Certification:The revised lithium battery testing protocol is expanding OEM qualification pools by standardizing safety validation requirements across air, sea, and ground logistics networks.
- Medical Implant Power Requirements:Cardiac device manufacturers are specifying CFx chemistry for extended-life pacemakers, creating dedicated demand corridors with decade-long procurement horizons.
- South Korea Electrode Clusters:Concentrated fluorinated carbon processing capacity in Gyeonggi-do province is reducing cathode material lead times for cylindrical cell assemblers.
Market Restraints
- Fluorine Gas Supply Concentration:Controlled atmosphere synthesis depends on semiconductor-grade fluorine sourced from three regional chemical conglomerates, exposing cell manufacturers to input volatility.
- Primary Cell Disposal Classification:EPA hazardous waste rules impose end-of-life handling premiums that industrial users must internalize or pass through pricing.
- Lithium-Thionyl Chloride Substitution:Mature alternative chemistry retains cost advantages in low-temperature telemetry applications, limiting CFx penetration in remote sensing.
Strategic Opportunities
- Electric Vehicle Auxiliary Modules:OEM evaluation programs for 12V backup systems represent a volume pathway beyond established military and medical niches.
- Japan METI Subsidies:Next-generation storage incentive frameworks are covering fluorinated graphite R&D amortization for qualified domestic suppliers.
- Direct-to-Defense Procurement:Bypassing traditional distributor channels for classified program deliveries captures margin currently absorbed by intermediaries.
Industry Challenges
- Fluoropolymer Handling Expertise:Specialized technician training for controlled atmosphere synthesis extends facility commissioning timelines and inflates operational labor costs.
- Dual Certification Burden:Parallel UN 38.3 and FAA hazardous materials compliance tracks force redundant testing expenditures for cells above lithium content thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Fluorinated Graphite Batteries Market |
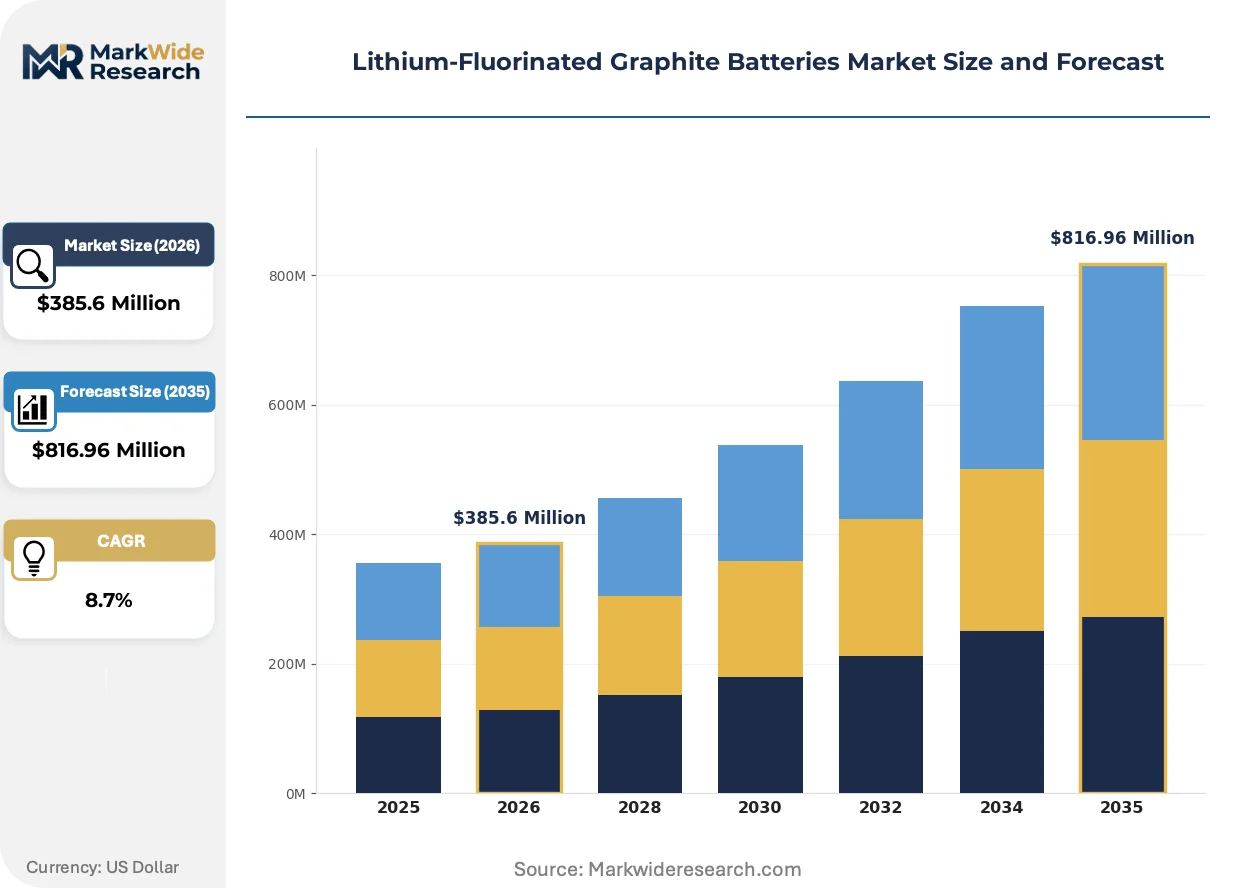
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Anode Materials, Electrolytes, Conductive Additives, Binders End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Applications Form Factor: Prismatic, Cylindrical, Pouch, Coin Application: Portable Devices, Automotive Powertrain, Grid Storage, Renewable Energy |
| Companies Covered | COBRA, Stanley Black & Decker, Clore Automotive, Anker, BOLTPOWER, CARKU, China AGA, Newsmy, Shenzhen NianLun Electronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Fluorinated Graphite Batteries Market Trends and Innovations
Fluorinated graphite cell architecture is undergoing material restructuring as manufacturers balance energy density gains against thermal stability requirements in cylindrical form factors.
Solid-state electrolyte interfaces are decomposing the traditional liquid electrolyte dependency in primary lithium systems. Medical device OEMs are piloting these architectures for implantable neurostimulators requiring decade-long operational lifespans. The shift is decomposing established separator supply relationships and compressing qualification timelines for inorganic electrolyte deposition equipment.
China's NMPA battery safety standards are mandating enhanced thermal runaway propagation testing for cells entering medical device supply chains. The regulation forces fluorinated graphite manufacturers to redesign cylindrical cell venting mechanisms and documentation protocols. Domestic Chinese suppliers are responding by integrating GB standard compliance into initial design phases rather than retrofitting for export markets.
Defense procurement officers are consolidating vendor lists around platform-compatible battery specifications, reducing qualified supplier pools for specialized primary cells. Tool-platform ecosystems in industrial power tools are extending this consolidation pattern into commercial segments. The United States military's battery standardization initiatives represent the most visible geography for this buyer-concentration effect.
Lithium-Fluorinated Graphite Batteries Market Segmentation
CFx battery procurement channels diverge sharply by end-use criticality. Military programs route through defense contractors with multi-year qualification cycles. Medical OEMs demand lot-traceable supply chains with FDA master file documentation. Industrial distributors handle fragmented replacement demand across remote telemetry installations.
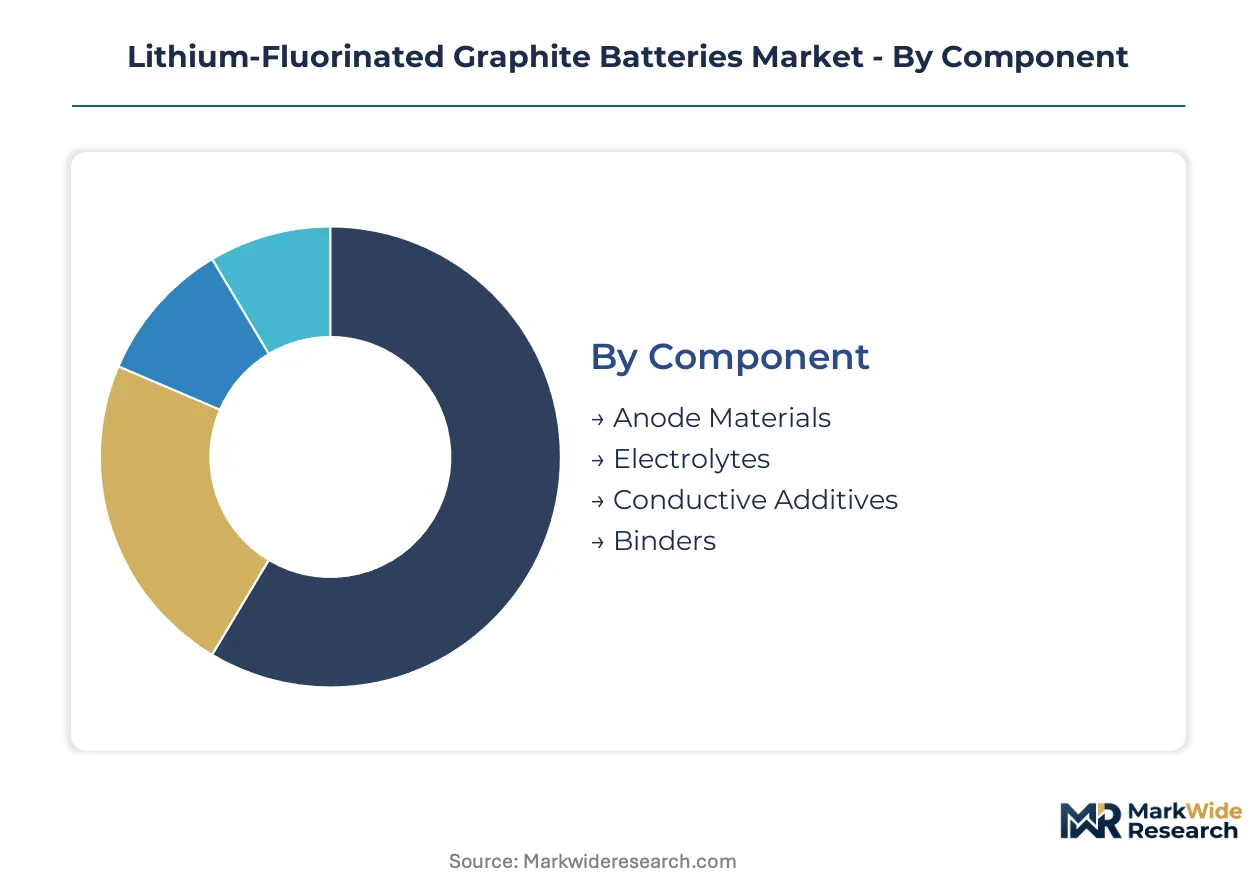
Component:
Anode materials and electrolytes flow through distinct channel structures. Fluorinated graphite synthesis outputs move direct to cell manufacturers under tolling arrangements. Electrolyte salts and conductive additives route through chemical distributors serving multiple battery chemistries.
- Anode Materials:Carbon monofluoride cathodes require controlled atmosphere fluorination at specialized facilities. Demand concentrates in South Korea's Gyeonggi-do electrode clusters where cathode material lead times have compressed for cylindrical cell assemblers. Fluorine gas supply concentration among three regional chemical conglomerates exposes manufacturers to input volatility.
- Electrolytes:Lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide formulations dominate primary cell architectures. Solid-state electrolyte interfaces are displacing traditional liquid systems in medical implant applications, decomposing established separator supply relationships.
- Conductive Additives:Carbon black and graphite powders enhance electron transport in high-rate discharge scenarios.
- Binders:Polyvinylidene fluoride and styrene-butadiene rubber secure active material adhesion during electrode calendering.
By volume, anode materials lead component procurement. By growth pace, electrolyte innovation is climbing the fastest amid solid-state transition programs.
End User:
Customer type determines pricing tolerance and contract structure. Defense buyers accept cost premiums for domestic sourcing compliance. Automotive OEMs impose automotive-grade PPAP documentation burdens. Medical device manufacturers require decade-long supply assurance with regulatory file maintenance.
- Electric Vehicles:OEM evaluation programs for 12V auxiliary power modules represent a volume pathway beyond established military and medical niches. CFx cells are displacing lead-acid in backup systems where weight reduction justifies primary cell replacement costs. Thermal runaway propagation testing under China's NMPA standards is reshaping cell venting designs for this segment.
- Consumer Electronics:Portable power tools and outdoor equipment specify CFx chemistry for cold-weather reliability. Stanley Black & Decker anchors platform compatibility requirements that lock aftermarket replacement demand. Shenzhen NianLun Electronic competes on cost-optimized cell designs for portable starter applications.
- Energy Storage Systems:Grid-scale installations evaluate primary lithium for backup duty in remote renewable installations.
- Industrial Applications:Downhole drilling tools and pipeline inspection gauges specify CFx for temperature extremes where rechargeable chemistries fail.
Defense procurement currently dominates revenue contribution. Automotive auxiliary modules are gaining share fastest as OEM qualification timelines accelerate.
Form Factor:
Manufacturing equipment inheritance shapes form factor adoption curves. Cylindrical winding lines from consumer lithium-ion production adapt readily to CFx electrode stacks. Prismatic formats require greenfield tooling investments that deter mid-scale entrants.
- Cylindrical:Established winding equipment and thermal management predictability dominate current procurement volumes. The 18650 and 26650 formats serve military radio and medical pump applications with standardized interconnect footprints. Defense procurement officers are consolidating vendor lists around platform-compatible cylindrical specifications.
- Prismatic:Laminated electrode structures maximize volumetric energy density for space-constrained automotive auxiliary modules. Japan's METI subsidy frameworks cover fluorinated graphite R&D amortization for qualified domestic suppliers developing prismatic formats.
- Pouch:Flexible aluminum-laminate enclosures suit wearable medical devices requiring conformal battery profiles.
- Coin:Compact diameters serve implantable neurostimulators and RFID tracking tags with microampere discharge profiles.
Cylindrical formats command the installed base. Prismatic architectures are expanding most quickly as automotive qualification programs mature.
Application:
Use-case criticality determines cell specification stringency. Life-sustaining medical applications mandate zero-defect quality systems. Grid storage tolerates higher failure rates given redundant module architectures.
- Portable Devices:Military radios, diving computers, and avalanche transceivers specify CFx for shelf-life stability exceeding ten years. UN 38.3 transport certification is reorganizing which suppliers qualify for OEM qualification programs serving this application cluster.
- Automotive Powertrain:Primary cells serve backup power for critical control systems in electric vehicles where main battery isolation is required. FAA hazardous materials regulations govern air transport eligibility for cells above lithium content thresholds in automotive logistics networks.
- Grid Storage:Utility-scale frequency regulation pilots evaluate CFx against lithium-thionyl chloride for discharge predictability.
- Renewable Energy:Off-grid solar installations in remote geographies specify primary lithium where maintenance access is impractical.
Portable devices anchor current shipment volumes. Automotive powertrain integration is gaining momentum fastest as 12V system electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement officers and medical device OEMs cluster demand in three distinct geographies, each imposing unique qualification frameworks on fluorinated graphite cell suppliers.
United States
Department of Defense battery standardization initiatives compress supplier certification timelines for high-energy-density primary cells. FAA hazardous materials regulations govern air transport eligibility for cells above lithium content thresholds in military logistics networks. Domestic fluorinated graphite synthesis capacity concentrates in specialized chemical processing corridors serving classified program deliveries.
China
NMPA battery safety standards mandate enhanced thermal runaway propagation testing for cells entering medical device supply chains. GB standard compliance is shifting from retrofitting for export markets to integrated initial design phases among domestic suppliers. Electrode material hubs in Jiangsu and Guangdong provinces are expanding fluorinated carbon processing capacity for cylindrical cell assemblers.
Japan
METI subsidy frameworks for next-generation storage cover fluorinated graphite R&D amortization for qualified domestic suppliers. JIS certification requirements create parallel compliance tracks that fragment supplier qualification investments. Precision chemical processing corridors in the Chubu region anchor cathode material synthesis for implantable neurostimulator applications.
South Korea
Gyeonggi-do province electrode clusters are reducing cathode material lead times for cylindrical cell assemblers serving portable power tool OEMs. The national industrial regulator enforces semiconductor-grade fluorine handling protocols for controlled atmosphere synthesis facilities. Busan-Ulsan chemical complexes supply electrolyte salts to regional battery manufacturers under tolling arrangements.
Germany
Automotive OEM evaluation programs for 12V auxiliary power modules represent a volume pathway beyond established military niches. REACH and RoHS compliance frameworks impose substance restriction documentation burdens on cell importers. Industrial machinery manufacturers in Baden-Württemberg specify CFx chemistry for downhole drilling tools requiring temperature extreme tolerance.
Lithium-Fluorinated Graphite Batteries Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with established battery platform ecosystems, supplemented by specialized automotive aftermarket suppliers and cost-optimized Chinese electronics fabricators. Market structure exhibits tiered consolidation around defense contractor qualification lists, tool-platform compatibility requirements, and medical OEM lot-traceability standards. Three archetypes dominate: diversified power tool conglomerates anchoring platform ecosystems, automotive aftermarket specialists leveraging channel relationships, and cost-driven portable electronics assemblers. Competitive moves center on backward integration into fluorinated graphite synthesis capacity and direct-to-defense procurement channel development bypassing traditional distributors.
Within the diversified industrial tier, Stanley Black & Decker anchors platform compatibility requirements that lock aftermarket replacement demand through tool-ecosystem lock-in. COBRA occupies a position representing automotive channel relationship leverage for aftermarket penetration. Shenzhen NianLun Electronic exemplifies the cost-optimized fabrication archetype competing on cell design efficiency for portable starter applications. These three entities collectively illustrate how qualification depth, channel control, and manufacturing cost position segment competitive opportunity in primary lithium battery supply.
| Leading Market Players |
|---|
| COBRA |
| Stanley Black & Decker |
| Clore Automotive |
| Anker |
| BOLTPOWER |
| CARKU |
| China AGA |
| Newsmy |
| Shenzhen NianLun Electronic |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day cathode material lead times in South Korea's Gyeonggi-do electrode clusters concentrate pricing power among fluorinated graphite synthesis facilities with semiconductor-grade fluorine handling capabilities, compressing margins for cylindrical cell assemblers lacking tolling arrangements with controlled atmosphere processors.
Pricing Analysis
Cost-plus contracts with fluorine gas indexation dominate procurement between cathode material suppliers and cell manufacturers. Price differentiation rests on UN 38.3 certification tier and domestic sourcing compliance for defense buyers. Cost compression in the industrial telemetry tier is intensifying because lithium-thionyl chloride substitutes retain cold-temperature cost advantages. Defense procurement officers show the least price sensitivity, while portable power tool OEMs demand volume-scaled economy pricing.
Supply Chain Analysis
Inventory buffers at South Korean electrode hubs have compressed to three weeks for fluorinated graphite cathodes, exposing cylindrical cell assemblers to fluorine gas supply disruptions. Manufacturing draws from South Korea, Japan, and China's Jiangsu province. Raw material inputs hinge on semiconductor-grade fluorine, lithium metal ingots, and carbon monofluoride precursors. Single-source vulnerability concentrates in fluorine gas supply among three regional chemical conglomerates. Distribution runs through defense contractor qualification lists, medical OEM direct procurement, and industrial distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough in defense procurement deferrals, with United States battery standardization initiatives now compressing supplier certification timelines and reallocating manufacturing capacity toward primary cell qualification programs.
For Market Incumbents: Secure backward integration into fluorinated graphite synthesis capacity before semiconductor-grade fluorine supply tightens further. Lock in decade-long tolling arrangements with South Korean electrode clusters to defend against emerging Chinese suppliers integrating GB standard compliance into initial design phases. Channel control through direct-to-defense procurement bypasses margin-absorbing intermediaries for classified program deliveries. For New Entrants and Emerging Players: Aftermarket service gaps for medical implant battery replacement represent the most penetrable white-space target, as incumbents under-serve decade-long supply assurance requirements with lot-traceable documentation. Target automotive auxiliary module qualification programs where OEMs evaluate CFx cells for 12V backup systems. Lead with solid-state electrolyte interface expertise to differentiate from established liquid electrolyte architectures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core battery platform ecosystems seeking to monetize defense contractor qualification positions. Long-term viability rests on fluorinated graphite synthesis capability rather than cell assembly scale. Watch Japan METI subsidy framework revisions as the inflection signal for qualified domestic supplier R&D amortization coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Graphite Synthesis | Captures deepest margin pools in anode materials through controlled atmosphere processing ownership. |
| UN 38.3 Transport Certification Investment | Expands OEM qualification pools across air, sea, and ground logistics networks for military procurement. |
| Direct-to-Defense Procurement Channel Development | Bypasses traditional distributor margins for classified program deliveries with platform-compatible specifications. |
| Solid-State Electrolyte Interface R&D | Displaces liquid electrolyte dependency for medical implant applications requiring decade-long operational lifespans. |
| Japan METI Subsidy Qualification | Covers fluorinated graphite R&D amortization for domestic suppliers developing prismatic automotive formats. |
Research Methodology
Cross-validation between primary interviews with defense procurement officers, medical device OEM supply chain managers, and fluorinated graphite synthesis facility technical directors anchors the qualitative findings, while secondary validation draws from FAA hazardous materials regulatory filings, China's NMPA battery safety standards, Japan's METI subsidy framework documentation, and SEC 10-K disclosures from diversified industrial conglomerates with battery platform ecosystems. Bottom-up cell shipment estimates triangulate against top-down defense procurement budget allocations and medical device power component spend.
Sensitivity analysis around fluorine gas supply disruption scenarios and lithium-thionyl chloride substitution elasticity shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include component tier, end-user criticality, form factor manufacturing equipment inheritance, and application use-case stringency. CAGRs derive from fluorinated graphite synthesis capacity expansion schedules and OEM qualification timeline compression observed in United States battery standardization initiatives.
Underlying assumptions cover sustained defense procurement acceleration and medical implant power requirement stability, with deviation risk concentrated in fluorine gas supply concentration among three regional chemical conglomerates and evolving UN Manual of Tests and Criteria revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Printable Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Primary Lithium Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
Leisure Battery Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
India Lead-Acid Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
India SLI Battery Market
Batteries
Atomic Battery Market
Batteries
48 Volt Battery System Market
Batteries
VRLA Batteries Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Forklift Battery Charger Market
Batteries
Sodium-Ion Battery Electrolyte Market