
 North America Lead-Acid Battery Separator for SLI Applications Market | 2026-2036
North America Lead-Acid Battery Separator for SLI Applications Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lead-Acid Battery Separator for SLI Applications Market Insights
Capital-intensity divergence between integrated resin producers and downstream converters is unwinding traditional supply arrangements in the separator value chain. Hollingsworth & Vose leverages its in-house fiber processing capabilities to control raw material quality from pulp to finished separator sheet. Entek competes through vertical integration into polyethylene membrane extrusion, reducing resin cost volatility. EnerSys anchors its position via captive demand from its own battery manufacturing network across North American industrial sites.
Lead-acid battery separator for SLI applications refers to the microporous barrier interleaved between positive and negative plates in starting, lighting, and ignition batteries, typically manufactured from polyethylene-silica composites with controlled pore sizes of 0.1 to 1.0 microns to enable ionic transport while preventing dendritic short circuits. Its primary purpose is to maintain electrolyte saturation, compress plate growth during cycling, and extend battery service life in high-cranking-demand automotive environments. Plastic and polyethylene product types dominate volume shipments due to cost efficiency in mass-market passenger vehicle batteries, while absorbent glass mat technology commands premium positioning in start-stop and micro-hybrid applications where enhanced cycle stability justifies higher separator expense. Glass separators retain niche presence in heavy-duty commercial fleets requiring superior thermal tolerance.
EPA lead exposure standards and California Proposition 65 labeling requirements compel separator manufacturers to reduce soluble lead content in finished products and document supply chain transparency for aftermarket distribution. NHTSA vehicle safety regulations and corporate average fuel economy standards indirectly shape SLI battery specifications, cascading into separator performance requirements for vibration resistance and cold-cranking reliability. Stakeholders must monitor how US Inflation Reduction Act domestic content incentives for battery supply chains reshape sourcing decisions for separator resin and manufacturing equipment.
Market Dynamics
The EPA's tightened lead exposure standards and California Proposition 65 labeling mandates are compressing formulation flexibility for separator manufacturers, forcing material substitutions and supply chain documentation upgrades across the value chain.
Growth Catalysts
- Aftermarket channel expansion:Rising average vehicle age across the United States is extending battery replacement cycles and concentrating separator demand through independent automotive service networks.
- Start-stop system proliferation:NHTSA corporate average fuel economy standards are accelerating OEM fitment of micro-hybrid architectures that require enhanced cycle-stable separator materials.
- Great Lakes manufacturing cluster:Proximity between separator production facilities and battery assembly plants in Michigan, Ohio, and Ontario reduces logistics friction and supports just-in-time supply arrangements.
Market Restraints
- Polyethylene resin cost volatility:Feedstock price swings tied to crude oil fluctuations compress margin predictability for membrane extrusion operations.
- Supply concentration in silica processing:Limited domestic sources of battery-grade precipitated silica create geographic vulnerability in the raw material base.
- Technical ceiling in pore size control:Existing polyethylene-silica composites face physical limits in achieving sub-0.1-micron pore distributions needed for next-generation thin-plate designs.
Strategic Opportunities
- US Inflation Reduction Act domestic content incentives:Battery supply chain localization credits create procurement preference for North American-manufactured separator materials.
- Absorbent glass mat conversion:Premium positioning in start-stop applications offers margin expansion as AGM technology penetrates mid-range passenger vehicle segments.
- Heavy-duty fleet thermal tolerance requirements:Commercial vehicle operators in Texas and California are specifying glass separator variants for extreme climate reliability.
Industry Challenges
- Electrolyte saturation consistency:Achieving uniform wicking performance across high-speed production lines requires precision calibration that strains quality control systems.
- Proposition 65 compliance documentation:Supply chain transparency mandates impose administrative burden on aftermarket distribution networks serving California.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lead-Acid Battery Separator for SLI Applications Market |
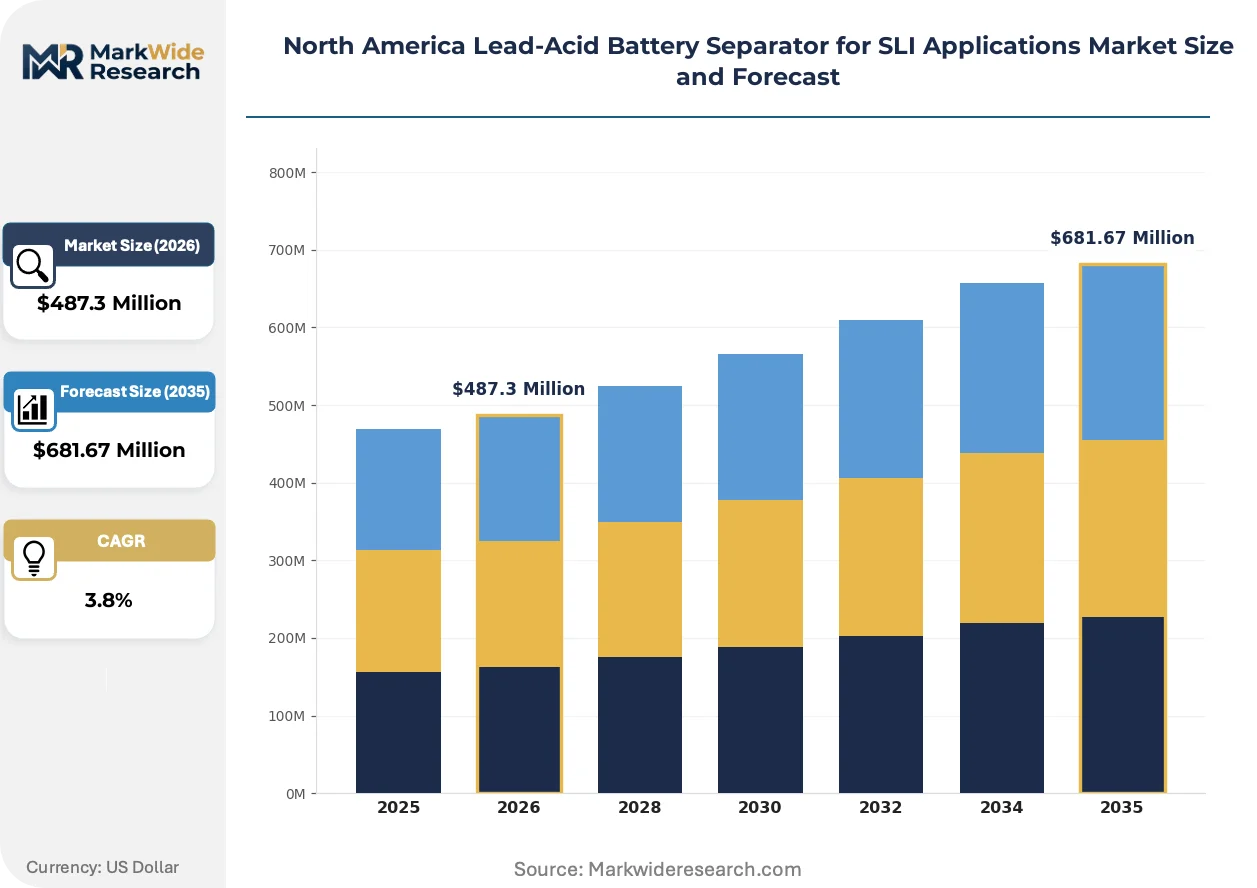
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Polyethylene, Rubber Technology: Absorbent Glass Mat, Thin Plate, Standard Lead-Acid, Gel End User: Automotive, Marine, UPS, Industrial Market Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | Hollingsworth & Vose, Exide Technologies, Daramic, C&D Technologies, EnerSys, Entek, East Penn Manufacturing, Johnson Controls, MICROPOROUS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lead-Acid Battery Separator for SLI Applications Market Trends and Innovations
Material science advances and regulatory compression are converging to reshape separator specifications, with manufacturers racing to balance performance thresholds against environmental compliance burdens.
Backsheet thinning technology is miniaturizing polyethylene-silica composite structures while maintaining mechanical integrity under plate compression. OEM battery engineers are specifying 0.15mm separator gauges for next-generation thin-plate SLI designs. This dimensional reduction is miniaturizing cell pack volumes and enabling higher energy density configurations without sacrificing short-circuit resistance.
California's Proposition 65 enforcement is tightening labeling requirements for lead-containing components entering aftermarket channels. Separator manufacturers must now document supply chain provenance and soluble lead content at the batch level. The compliance burden falls heaviest on converters serving independent distributors, who lack the legal infrastructure of national retail chains.
Fleet operators are consolidating procurement through direct manufacturer relationships, bypassing traditional tiered distribution. Large commercial vehicle lessors in the US Southeast are negotiating volume contracts that specify separator performance metrics and traceability documentation. This channel compression is most visible in the heavy-duty segment, where total cost of ownership calculations dominate supplier selection.
North America Lead-Acid Battery Separator for SLI Applications Market Segmentation
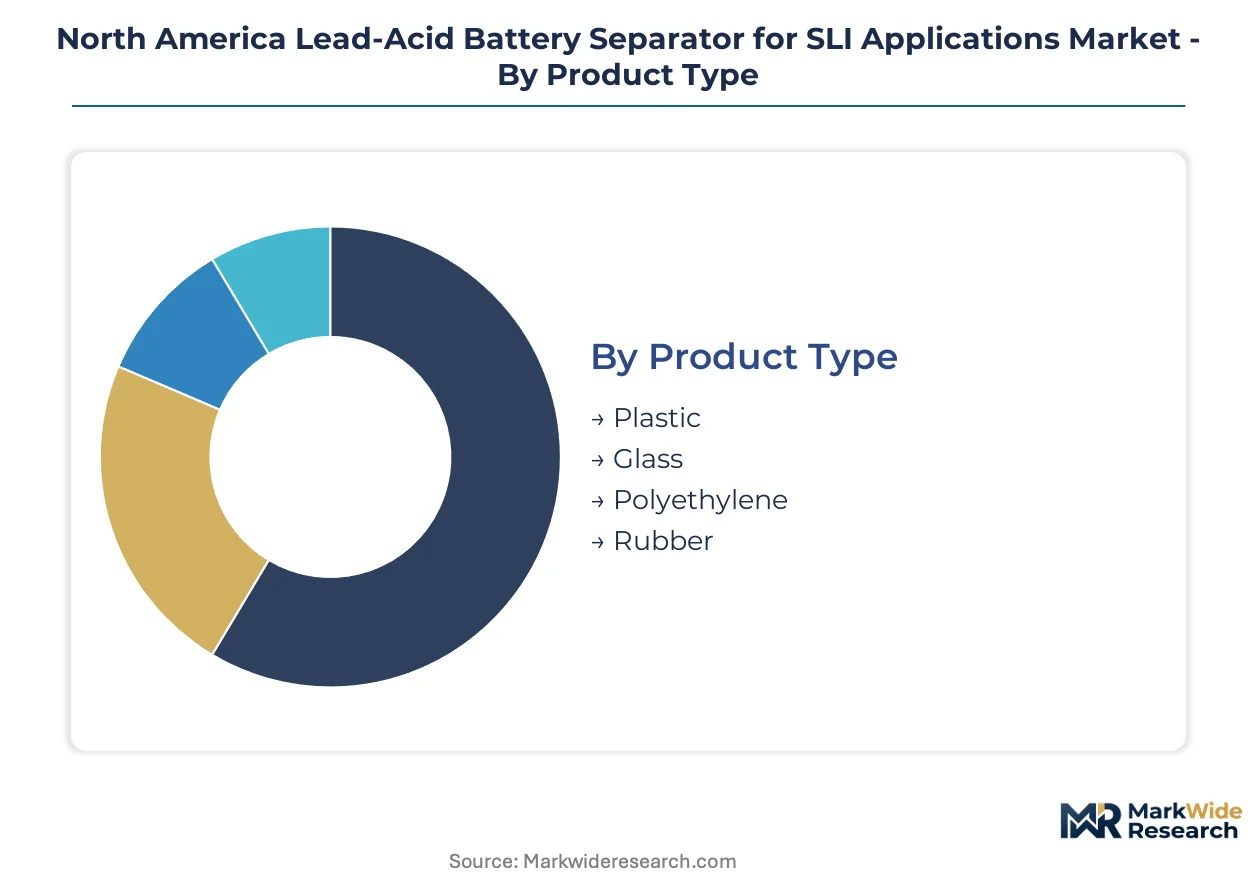
Separator specifications diverge sharply across SLI applications, with material selection and channel strategy determining margin capture. Understanding where value concentrates within each dimension enables targeted positioning against regulatory and performance demands.
Product Type:
Polyethylene-silica composites command the widest margin pools due to scale economies in passenger vehicle supply chains, while glass variants extract premiums in thermal-stress applications.
- Plastic:Polyethylene-silica composites dominate mass-market production with 0.1-1.0 micron pore structures optimized for ionic transport. Michigan and Ohio battery assembly plants source these formulations in high volumes for conventional SLI batteries, though EPA lead exposure standards are compressing formulation flexibility.
- Polyethylene:Membrane extrusion technologies enable sub-0.2mm gauge specifications for thin-plate designs. Start-stop system proliferation across US passenger fleets is accelerating specification upgrades, with OEMs in the Great Lakes corridor driving procurement concentration.
- Glass:Absorbent glass mat separators retain electrolyte without free liquid, serving heavy-duty commercial fleets in Texas and California where thermal tolerance justifies expense.
- Rubber:Legacy formulations persist in niche industrial applications requiring extreme vibration resistance.
The dominant share belongs to Polyethylene, while Glass is closing the gap fastest through AGM conversion in premium automotive segments.
Technology:
Volume-weighted demand clusters around mature lead-acid architectures, though start-stop compliance requirements are redistributing share toward cycle-stable alternatives.
- Standard Lead-Acid:Conventional flooded-cell designs with polyethylene-silica separators retain cost advantages in aftermarket replacement cycles. Rising average vehicle age across the United States sustains demand through independent automotive service networks concentrated in the Southeast and Midwest.
- Absorbent Glass Mat:Electrolyte immobilization within glass microfiber mats enables deep-cycling performance for micro-hybrid architectures. NHTSA corporate average fuel economy standards are accelerating OEM fitment, with California and Texas fleet operators specifying AGM for stop-start reliability.
- Thin Plate:Reduced plate spacing demands sub-0.15mm separator gauges with enhanced mechanical integrity under compression.
- Gel:Immobilized electrolyte systems serve marine and remote industrial installations where spill resistance outweighs cost premiums.
Standard Lead-Acid retains volume leadership, though Absorbent Glass Mat is expanding most quickly as fuel economy regulations tighten.
End User:
Automotive procurement channels offer scale efficiencies, while marine and industrial segments reward performance specifications with pricing power.
- Automotive:Passenger vehicle OEMs and aftermarket networks consume the majority of separator volume, with Great Lakes manufacturing proximity reducing logistics friction. US Inflation Reduction Act domestic content incentives are reshaping sourcing decisions toward North American-manufactured materials.
- Industrial:Forklift and stationary power applications specify thicker separators for extended cycle life, with procurement consolidating through direct manufacturer relationships.
- Marine:Vibration-resistant and spill-proof configurations serve recreational and commercial vessel operators.
- UPS:Uninterruptible power supply systems demand consistent quality for standby applications with infrequent cycling.
Automotive commands the largest share, while Industrial is gaining share fastest through fleet consolidation and direct contracting trends.
Market Channel:
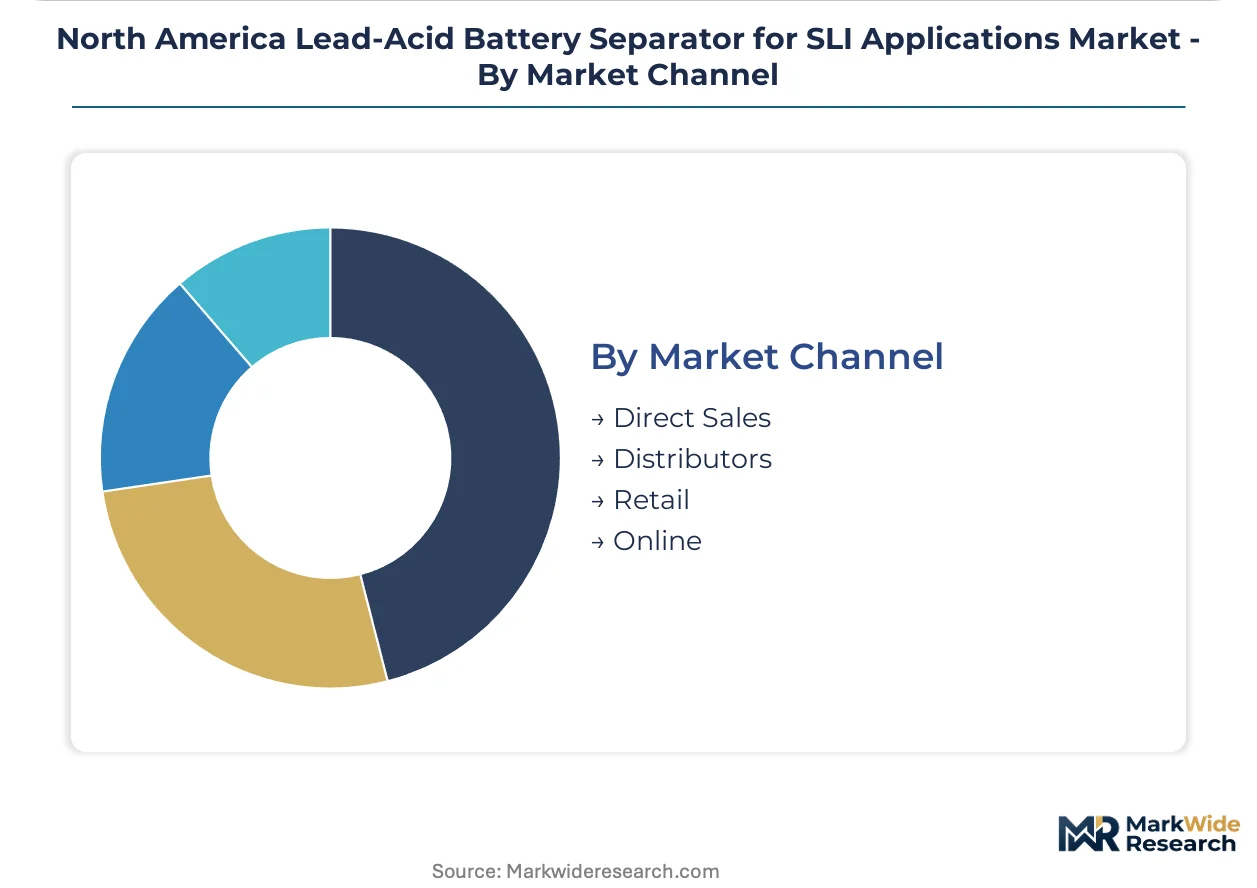
Distribution economics favor national retail chains for standardized products, though direct sales capture value in specification-intensive segments.
- Distributors:Independent automotive service networks rely on tiered distribution for inventory breadth, though California Proposition 65 compliance documentation imposes administrative burden on smaller operators lacking legal infrastructure.
- Direct Sales:Large commercial vehicle lessors in the US Southeast negotiate volume contracts specifying performance metrics and traceability documentation, bypassing traditional tiered distribution.
- Retail:National chains serve consumer replacement demand with standardized product lines.
- Online:Digital procurement channels are emerging for aftermarket segments with clear specification requirements.
Distributors hold the dominant position, while Direct Sales is climbing the fastest as fleet operators consolidate procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes polyethylene-silica separators at scale for conventional SLI batteries, while Canadian and Mexican demand concentrates in cross-border supply chains serving Great Lakes assembly plants. Mexico's aftermarket channels favor cost-optimized plastic formulations distinct from the premium AGM specifications prevalent in Texas and California fleet markets.
United States
The US Southeast sustains aftermarket demand through independent automotive service networks replacing batteries in aging vehicle fleets. EPA lead exposure standards and California Proposition 65 labeling mandates compel separator manufacturers to document supply chain provenance and reduce soluble lead content. Michigan and Ohio anchor production concentration, with battery assembly plants clustering near OEM customer bases in the Great Lakes industrial corridor.
Canada
Ontario's manufacturing base supplies separator materials to cross-border automotive OEMs operating under USMCA trade provisions. Health Canada and Environment Canada coordinate lead exposure guidelines with EPA benchmarks, creating regulatory alignment for integrated North American supply chains. The Windsor-Toronto corridor hosts converter operations serving Detroit-area battery plants through just-in-time logistics arrangements.
Mexico
Nuevo León and the Bajío Region concentrate maquiladora battery assembly operations exporting finished SLI units to US aftermarket distributors. Mexican environmental regulators enforce progressively stricter lead handling protocols under SEMARNAT oversight, pressuring separator suppliers to upgrade documentation systems. Querétaro's industrial parks attract separator converters seeking proximity to expanding OEM battery plants serving the US Southwest.
North America Lead-Acid Battery Separator for SLI Applications Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American separator supply. Hollingsworth & Vose and Entek occupy positions anchored by captive fiber processing or resin extrusion capabilities, while mid-scale converters compete on formulation flexibility and regional logistics. Three archetypes define competitive positioning: vertically integrated material producers controlling raw material quality, battery manufacturers with captive separator demand, and independent converters serving aftermarket distributors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players seeking to secure resin supply agreements or lock in long-term OEM contracts.
Among US-based integrated producers, Hollingsworth & Vose exemplifies the fiber-control archetype through in-house pulp processing capabilities spanning pulp to finished separator sheet. Entek represents the resin-integration model, with polyethylene membrane extrusion reducing feedstock cost exposure. EnerSys occupies a position within the captive-demand tier, leveraging internal battery manufacturing networks across North American industrial sites to anchor separator offtake.
| Leading Market Players |
|---|
| Hollingsworth & Vose |
| Exide Technologies |
| Daramic |
| C&D Technologies |
| EnerSys |
| Entek |
| East Penn Manufacturing |
| Johnson Controls |
| MICROPOROUS |
| Others |
Pricing and Supply Chain Analysis
Polyethylene resin substitution for glass microfiber in mid-range SLI applications simultaneously redraws procurement geography toward Gulf Coast petrochemical corridors and compresses separator pricing differentials across the Great Lakes manufacturing cluster. Battery assemblers in Michigan and Ohio now source membrane-grade polyethylene from Texas and Louisiana producers, while California Proposition 65 compliance costs push aftermarket distributors toward documented supply chains with premium transparency.
Pricing Analysis
Long-term offtake contracts dominate procurement between Great Lakes separator converters and battery assembly plants, insulating volume purchasers from polyethylene resin spot volatility while independent aftermarket distributors absorb spot-market exposure. Three-tier pricing structure across AGM premium, polyethylene-silica standard, and legacy plastic economy levels reflects performance certification tiers and California compliance documentation depth. Cost compression in standard polyethylene-silica formulations is intensifying because resin feedstock volatility and EPA documentation requirements squeeze converter margins. Fleet operators negotiating direct manufacturer contracts exhibit lowest price sensitivity, while independent automotive service networks in the US Southeast face acute margin pressure.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Great Lakes battery assembly plants, with separator converters maintaining 48-hour delivery windows to Michigan and Ohio OEM facilities rather than strategic stockpiles. Supply concentrates in the United States for polyethylene resin extrusion and membrane finishing, with limited domestic precipitated silica processing creating dependency on Mexican and Canadian specialty chemical imports. Raw material dependencies center on battery-grade polyethylene, precipitated silica, and proprietary binder formulations. Single-source vulnerability in silica processing creates geographic concentration risk. Distribution runs through tiered aftermarket networks serving independent automotive service channels alongside direct sales to fleet operators and OEM battery plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation across Texas and California is shifting buyer power toward large commercial vehicle lessers, fragmenting traditional tiered distribution economics and forcing separator manufacturers toward direct contracting relationships.
For Market Incumbents: Compound defensive positioning through backward integration into polyethylene resin supply agreements and captive silica processing capabilities to offset feedstock volatility. Secure long-term OEM contracts with Great Lakes battery assemblers before US Inflation Reduction Act domestic content incentives reshape qualification requirements. Invest in batch-level Proposition 65 documentation systems to defend aftermarket channel access against compliance-weak competitors. For New Entrants and Emerging Players: Aftermarket documentation service gaps where incumbent converters under-serve independent distributors lacking California compliance infrastructure present immediate white-space opportunity. Target specialty glass separator supply to Texas heavy-duty fleet operators specifying thermal tolerance for extreme climate reliability. Pursue direct sales relationships with commercial vehicle lessers bypassing traditional distribution tiers, leveraging traceability documentation as primary go-to-market wedge. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated material processors with in-house fiber or resin capabilities over pure-play converters. Long-term viability across the analysis window hinges on securing stranded domestic silica processing assets and qualifying for federal domestic content incentives. Acquisition target archetype: mid-scale converters with EPA-compliant documentation systems and existing Great Lakes logistics infrastructure. The signal to watch is NHTSA fuel economy standard tightening accelerating AGM specification penetration into mid-range passenger segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene sourcing insulates margin from crude-linked feedstock volatility in Gulf Coast corridors. |
| AGM Capacity Expansion | Micro-hybrid architecture proliferation under NHTSA standards drives specification upgrade demand from Michigan OEMs. |
| Proposition 65 Documentation Systems | Batch-level traceability compliance secures California aftermarket channel access against regulatory enforcement. |
| Direct Fleet Contracting | Bypassing tiered distribution captures value from Texas and California commercial vehicle lessers consolidating procurement. |
| Great Lakes Logistics Optimization | Proximity to Michigan and Ohio battery assembly plants reduces delivery friction for just-in-time OEM supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and industry association disclosures to establish separator demand baselines. Primary interviews engaged separator manufacturing executives, battery plant procurement managers, aftermarket distribution channel heads, and EPA compliance officers across the United States and Ontario. Secondary validation drew from EPA enforcement databases, USMCA trade statistics, NHTSA fuel economy rulemakings, and California Office of Environmental Health Hazard Assessment Proposition 65 guidance documents. Bottom-up triangulation against top-down resin consumption models ensures volume consistency.
Segmentation dimensions modeled include product material type, battery technology architecture, end-use application, and procurement channel structure across the projection horizon. Analytical framework incorporates vehicle fleet age demographics, OEM platform electrification roadmaps, and regulatory compliance cost curves to derive growth trajectories. CAGRs reflect reconciled outputs from demand-side battery production forecasts and supply-side resin capacity expansion schedules. Industry-specific inputs encompass start-stop system penetration rates in US passenger fleets and heavy-duty fleet thermal specification trends in Texas and California.
Forecasts assume regulatory continuity in EPA lead exposure standards and California Proposition 65 enforcement regimes; material policy shifts would require re-modeling separator formulation economics and aftermarket channel qualification requirements. Revision becomes warranted when NHTSA fuel economy standard stringency or US Inflation Reduction Act domestic content thresholds cross implementation thresholds that reshape OEM sourcing decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Europe SLI Battery Market
Batteries
DMC for Battery Market
Batteries
Global Bio Compatible Battery Market
Batteries
3D-Printed Battery Market
Batteries
Thin Film and Printed Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
East Europe Battery Market
Batteries
HIT Battery Market
Batteries
Inverter Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Asia-Pacific Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Portable Battery Powered Products Market
Batteries
Portable Battery Market
Batteries
N-Type Battery Market