

Solid-State Battery Mechanical and Safety Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-State Battery Mechanical and Safety Test Equipment Market Insights
Multi-sourced equipment procurement is rebalancing toward captive validation centers as solid-state chemistry complexity rises. Keysight Technologies leverages its precision instrumentation heritage to anchor high-throughput electrical-mechanical coupling tests. Chroma Systems Solutions competes through integrated battery cycler-safety chamber platforms. TÜV Rheinland sustains third-party certification authority across European automotive supply chains.
Solid-state battery mechanical and safety test equipment encompasses instrumentation that subjects ceramic or sulfide electrolyte cells to compressive loading, thermal cycling, nail penetration, and vibration profiles up to 2000 Hz to detect dendrite-induced short-circuit precursors before commercial deployment. Compression testers dominate capital allocation as stack pressure requirements for oxide electrolytes exceed 10 MPa, while X-ray imaging grows fastest for non-destructive interface defect mapping. Optical microscopy retains relevance for academic and research institute workflows despite slower throughput.
FDA, EPA, and NHTSA frameworks in the United States mandate abuse-test documentation for traction batteries entering vehicle platforms, directly shaping equipment specification sheets. The EU Green Deal and F-Gas Regulation constrain thermal shock chamber refrigerant selections, pushing manufacturers toward cascade CO2 systems. Stakeholders must monitor how China's SAMR evolves GB standards for solid-state cells as domestic production scales, since export-bound equipment will require dual compliance architecture.
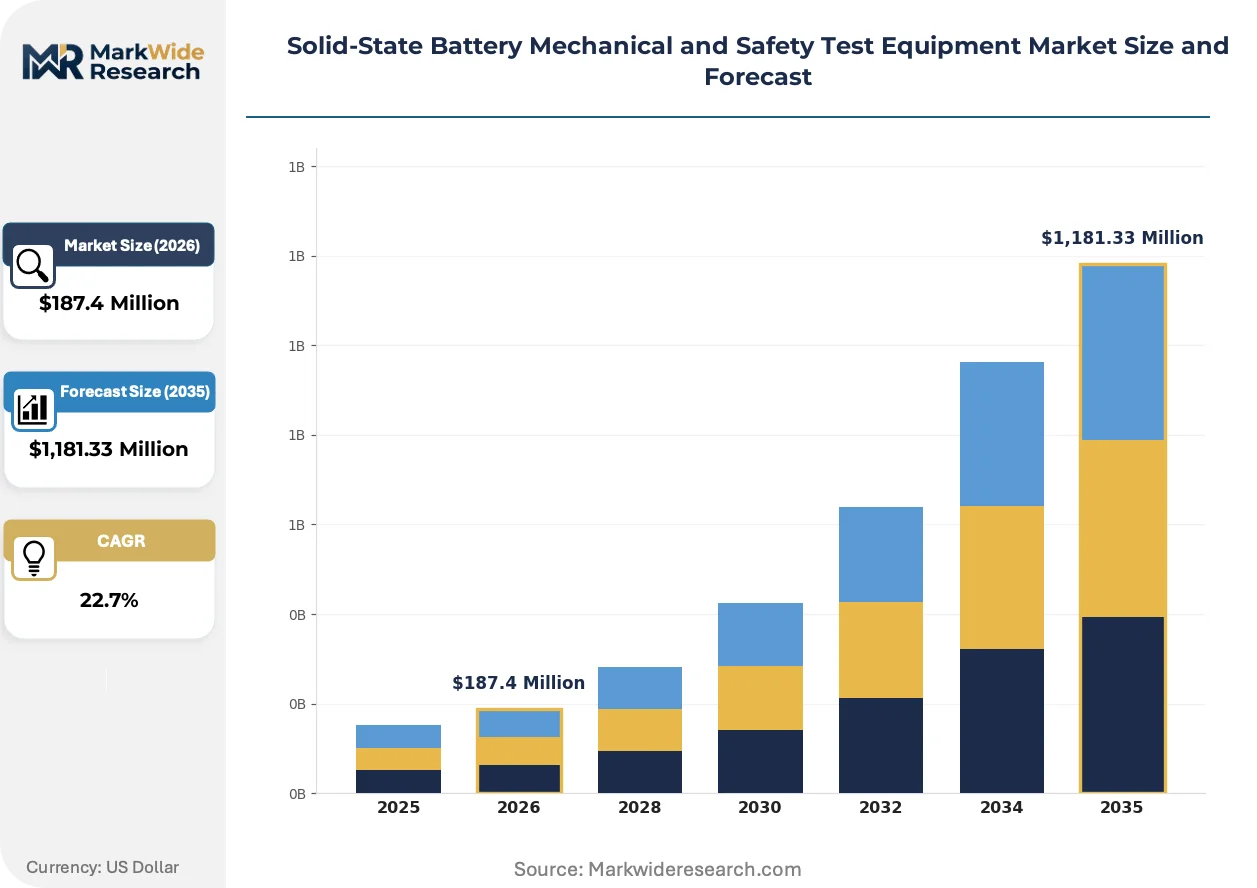
Market Dynamics
Stack pressure requirements for oxide-based solid-state electrolytes exceed 10 MPa, forcing automotive OEMs to abandon outsourced validation in favor of captive mechanical testing centers with integrated thermal-abuse capabilities.
Growth Catalysts
- GB Standards Evolution:China's SAMR is tightening safety verification protocols for sulfide and oxide electrolyte cells, mandating nail penetration and thermal runaway documentation before commercial deployment.
- Automotive OEM Validation Programs:Battery makers for electric vehicle platforms require 2000 Hz vibration profiling and dendrite detection protocols that exceed legacy lithium-ion testing specifications.
- Dual Carbon Policy Alignment:Beijing's carbon neutrality targets are accelerating domestic production of next-generation energy storage, creating demand for export-compliant test equipment architectures.
Market Restraints
- Refrigerant Constraint:The EU F-Gas Regulation is banning conventional thermal shock chamber coolants, forcing cascade CO2 system retrofits that extend equipment lead times.
- Ceramic Electrolyte Brittleness:Oxide electrolyte cells fracture under compressive cycling above 15 MPa, limiting throughput in high-volume production validation lines.
- Supply Concentration:Precision load frame manufacturing concentrates in Germany's Stuttgart-Munich corridor, exposing procurement to single-source dependency risks.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting test equipment vendors to establish localized calibration and service operations.
- X-Ray Interface Mapping:Non-destructive defect detection for ceramic-solid electrolyte boundaries represents an underdeveloped capability with premium pricing potential.
- Integrated Cycler-Chamber Platforms:Convergence of electrical cycling and safety abuse testing into single-workflow systems addresses bottlenecks in high-throughput automotive validation.
Industry Challenges
- Solid-State Electrochemistry Expertise:The shortage of technicians trained in sulfide electrolyte handling and dendrite characterization is extending commissioning timelines for new validation centers.
- Dual Compliance Architecture:Equipment manufacturers must engineer simultaneous adherence to China's GB standards and EU CE marking for automotive export markets, multiplying certification documentation burdens.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-State Battery Mechanical and Safety Test Equipment Market Trends and Innovations
Test instrumentation is converging around electrical-mechanical coupling and real-time defect detection, compressing validation cycles from months to weeks while raising equipment specification complexity.
Artificial vision systems paired with acoustic emission sensors are automating dendrite-induced short-circuit precursor identification during compressive loading cycles. Automotive battery engineering teams at German and Korean OEMs are adopting these platforms for prototype-stage screening. The technology is automating pass-fail decisions that previously required manual microscopy review, reducing validation headcount requirements by half.
The EU Green Deal's F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants in thermal shock chambers from 2027, compelling equipment manufacturers to redesign cascade cooling architectures around CO2 and propane blends. Test chamber OEMs with European automotive supply chain exposure are absorbing R&D costs to maintain CE marking eligibility. Sulfide electrolyte developers face the steepest compliance burden, as their moisture-sensitive chemistry demands precise thermal cycling control.
Validation service contracts are unbundling from equipment sales, with automotive OEMs preferring per-test pricing over capital ownership. Tier-1 battery suppliers in Stuttgart and Munich are driving this shift, treating mechanical safety testing as a variable cost tied to cell development milestones. The model is most advanced in Germany, where captive validation centers compete directly with third-party TÜV-certified facilities for automotive program work.
Solid-State Battery Mechanical and Safety Test Equipment Market Segmentation
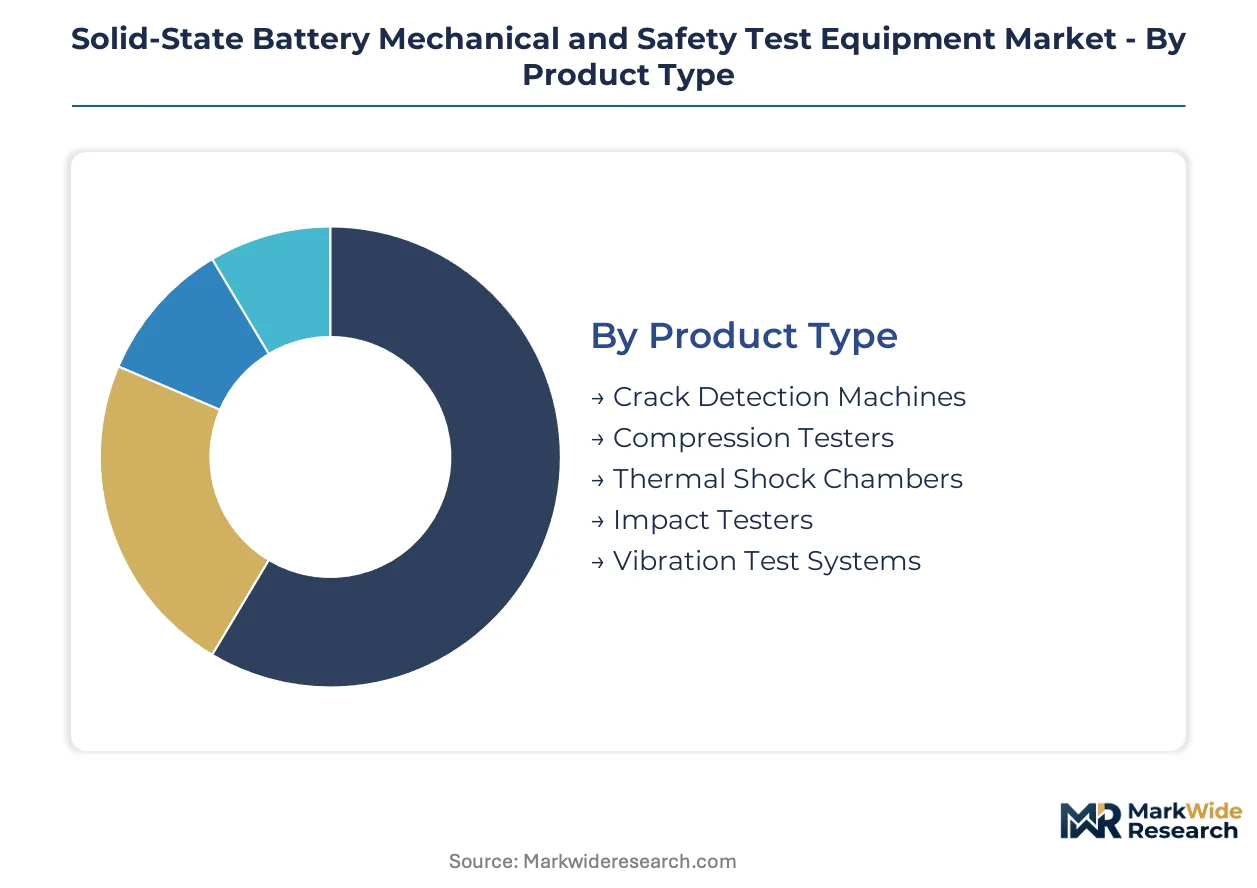
Solid-state battery validation demands equipment matched to electrolyte chemistry brittleness and stack pressure tolerances. Segmentation reveals where capital deployment concentrates across mechanical loading, thermal abuse, and non-destructive inspection workflows.
Product Type:
Compression testers absorb the heaviest capital outlays due to precision load frame requirements exceeding 10 MPa for oxide electrolyte validation.
- Compression Testers:These systems apply controlled stack pressure to ceramic electrolyte cells while monitoring fracture thresholds. Automotive OEMs in Germany's Stuttgart corridor are installing captive units to replace outsourced validation. Capital intensity peaks here from servo-hydraulic actuator specifications.
- Thermal Shock Chambers:Equipment subjects cells to rapid temperature cycling between extreme setpoints to trigger dendrite formation. EU F-Gas Regulation compliance is forcing cascade CO2 refrigerant retrofits, extending lead times for sulfide electrolyte developers.
- Vibration Test Systems:Platforms generate 2000 Hz profiles mimicking vehicle chassis dynamics.
- Crack Detection Machines:Automated systems identify ceramic electrolyte microfractures under cyclic loading.
- Impact Testers:Drop and projectile rigs simulate abuse scenarios for safety documentation.
Most installed capacity flows through compression testers. Expansion is steepest in thermal shock chambers.
Technology:
Non-destructive methods command premium pricing as manufacturers eliminate destructive sampling from production lines.
- X-Ray Imaging:Computed tomography systems map solid-electrolyte interface defects without cell destruction. Battery manufacturers are prioritizing this capability for sulfide-oxide boundary characterization. Throughput limitations persist for high-volume automotive validation.
- Acoustic Emission:Sensors detect microcrack propagation signatures during compressive cycling. Korean and German OEMs are pairing these with artificial vision for automated pass-fail decisions, halving microscopy headcount requirements.
- Laser Scanning:Surface profilometry captures electrolyte layer thickness variation.
- Ultrasonic Testing:Pulse-echo methods identify internal delamination in stacked cells.
- Optical Microscopy:Manual inspection retains relevance for academic and research institute workflows despite throughput constraints.
X-Ray imaging claims the highest equipment margins. Acoustic emission is climbing the fastest as automation converges with mechanical testing.
Application:
Regulatory documentation requirements are reshaping demand across validation stages.
- Safety Compliance:Abuse testing protocols including nail penetration and thermal runaway documentation are mandatory under China's GB standards and US NHTSA frameworks. Test volumes are surging as solid-state platforms approach commercial deployment.
- Quality Control:In-line inspection for ceramic electrolyte uniformity dominates production-scale equipment procurement. Battery manufacturers are integrating compressive loading stations directly into pilot lines.
- Reliability Testing:Accelerated life testing under combined electrical-mechanical stress.
- Performance Evaluation:Electrochemical characterization under mechanical constraint.
- Durability Assessment:Long-cycle testing for warranty validation.
Safety compliance absorbs the largest share of third-party service contracts. Quality control is expanding most quickly with captive center buildouts.
End User:
Procurement authority is shifting from equipment ownership to per-test pricing models.
- Automotive OEMs:Volkswagen, BMW, and Hyundai engineering teams are establishing captive validation centers in Germany and Korea. These facilities integrate electrical cycling with mechanical abuse testing to compress development timelines from months to weeks.
- Battery Manufacturers:Cell producers are unbundling validation service contracts from capital purchases, treating mechanical safety testing as variable cost tied to development milestones.
- Research Institutes:Academic workflows prioritize optical microscopy and lower-throughput methods.
- Aerospace Developers:Satellite and aviation battery programs demand extended thermal cycling protocols.
- Electronics Producers:Consumer device cell validation requires compact equipment footprints.
Automotive OEMs command the largest equipment orders. Battery manufacturers are gaining share fastest through service contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart-Munich automotive testing corridor anchors equipment demand as solid-state validation programs accelerate. Capital deployment concentrates in captive centers serving OEM development timelines. Regulatory divergence across major economies is reshaping equipment specification requirements.
China
Domestic solid-state cell production is scaling under Beijing's dual carbon policy framework. SAMR's evolving GB standards mandate nail penetration and thermal runaway documentation before commercial deployment. Equipment vendors are engineering dual compliance architectures in Shanghai and Shenzhen to serve export-bound battery manufacturers.
Germany
Volkswagen and BMW engineering teams are establishing captive validation centers with integrated electrical-mechanical coupling capabilities. The EU F-Gas Regulation is forcing cascade CO2 retrofits in thermal shock chambers across Baden-Württemberg. Stuttgart-based precision load frame manufacturers face capacity constraints from concentrated automotive procurement.
United States
NHTSA abuse-test documentation requirements directly shape equipment specification sheets for traction battery platforms. The Inflation Reduction Act is accelerating domestic battery manufacturing investment in Michigan and Ohio. Detroit-area validation centers are expanding compression testing capacity for oxide electrolyte programs.
South Korea
Hyundai and Samsung SDI are deploying 2000 Hz vibration profiling systems for dendrite detection protocols. MFDS battery safety frameworks align with automotive OEM validation standards. Gyeonggi-do testing corridors are integrating acoustic emission sensors with artificial vision for automated pass-fail decisions.
India
Production-linked incentive schemes for advanced chemistry cell manufacturing are attracting calibration and service operations to Gujarat and Tamil Nadu. BIS safety standards are converging with international automotive protocols. Domestic battery developers in Telangana are commissioning pilot-line validation equipment for sulfide electrolyte characterization.
Solid-State Battery Mechanical and Safety Test Equipment Market Competitive Landscape
Global majors compete with regional champions across precision instrumentation and third-party certification services. Market structure tilts toward consolidated equipment supply with fragmented validation service provision. Three archetypes dominate: precision measurement heritage players, integrated platform specialists, and third-party certification authorities. Capacity expansion in captive validation centers and strategic partnerships for refrigerant-compliant thermal systems represent the dominant competitive moves.
Within the precision instrumentation tier, Keysight Technologies and Hioki occupy positions anchored by electrical measurement heritage. Chroma Systems Solutions exemplifies the integrated platform archetype through battery cycler-safety chamber convergence. TÜV Rheinland anchors third-party certification authority across European automotive supply chains. These named entities represent strategic positioning patterns rather than specific market share claims.
| Leading Market Players |
|---|
| Arbin Instruments |
| Chroma Systems Solutions |
| Keysight Technologies |
| Hioki |
| Neware Technology |
| Midtronics |
| TÜV Rheinland |
| UL Solutions |
| Intertek Group |
| Others |
Pricing and Supply Chain Analysis
Precision load frame technicians concentrated in Germany's Stuttgart-Munich corridor command wage premiums that compress margins on economy-tier equipment while widening spreads to premium certified systems. Labor-cost differentials between captive European validation centers and outsourced Asian calibration facilities feed directly into three-tier pricing stratification across the equipment base.
Pricing Analysis
Input-cost pass-through from servo-hydraulic actuator components and cascade CO2 refrigeration systems anchors pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified integrated platforms from basic compression testers. Pricing pressure stems from EU F-Gas Regulation compliance costs forcing thermal chamber redesigns. Battery manufacturers exhibit highest price sensitivity through per-test service contracts, while automotive OEMs absorb premium tiers for captive center buildouts.
Supply Chain Analysis
Single-source vulnerability sits with precision load frame manufacturing concentrated in Germany's Stuttgart-Munich corridor. Component sourcing draws from Japan for high-frequency vibration actuators, Germany for servo-hydraulic systems, and South Korea for acoustic emission sensors. Supply chain risk centers on regulatory restriction exposure from dual compliance architectures for GB standards and CE marking. Distribution runs through direct OEM procurement for captive centers and third-party certification houses for validation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery mechanical and safety test equipment has entered a late-cycle quality phase where specification premiums widen as automotive OEMs prioritize dendrite detection accuracy over capital cost minimization. The demand shift toward integrated electrical-mechanical coupling platforms rewards vendors with certified precision heritage.
For Market Incumbents: Anchor defensive positioning through backward integration into precision load frame manufacturing and captive calibration service networks in Germany's automotive testing corridor. Certification investment for simultaneous GB standards and CE marking compliance addresses the regulatory documentation burden multiplying across export-bound equipment architectures. Threat from integrated platform specialists like Chroma Systems Solutions demands response through electrical cycling heritage leverage. For New Entrants and Emerging Players: Mid-tier battery manufacturers in India's Gujarat and Tamil Nadu production clusters represent the most penetrable buyer archetype underserved by established German and Korean vendors. Localized calibration operations and sulfide electrolyte handling expertise address technician shortage constraints extending commissioning timelines. Go-to-market execution through PLI scheme-aligned partnerships with domestic cell developers bypasses incumbent channel control. For Investors and Strategic Acquirers: Valuations sit cheapest among acoustic emission and artificial vision automation specialists lacking integrated platform scale but commanding premium positioning. Long-term viability across the five-to-ten year window rests on convergence technology capture rather than single-modality equipment supply. The inflection signal to watch is unbundling velocity of validation service contracts from capital sales as automotive OEMs shift to per-test pricing models.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Retrofit | Cascade CO2 thermal chamber redesign preserves CE marking eligibility under EU F-Gas Regulation constraints. |
| Dual Compliance Certification | Simultaneous GB standards and CE marking engineering opens China's export-bound battery manufacturer procurement. |
| Acoustic Emission Integration | Automated dendrite detection pairing with artificial vision halves validation headcount requirements for Korean OEMs. |
| Captive Validation Center Buildout | Integrated electrical-mechanical testing compresses automotive OEM development timelines from months to weeks. |
| Localized Service Operations | India PLI scheme-aligned calibration hubs address sulfide electrolyte technician scarcity in domestic production clusters. |
Research Methodology
Bottom-up automotive OEM and battery manufacturer demand modeling reconciled against top-down precision instrumentation supply tracking forms the analytical core. Primary interviews with validation center engineering directors, thermal chamber procurement leads, certification body technical managers, and sulfide electrolyte R&D heads combined with secondary validation from SAMR GB standards documentation, EU F-Gas Regulation compliance filings, and NHTSA abuse-test protocol specifications. Trade data from German mechanical engineering associations and Korean battery industry disclosures provided cross-reference anchors for triangulation.
Input-output matrix framing connects compression tester and thermal shock chamber unit deployments to solid-state cell pilot line investments across the projection horizon. Segmentation dimensions modeled include electrolyte chemistry type, equipment technology modality, validation application stage, and end-user procurement authority. CAGRs derived from equipment replacement cycles and automotive platform development timelines incorporate stack pressure specification evolution and refrigerant compliance transition costs as industry-specific forecast inputs.
Underlying measurement precision varies by segment; compression tester capacity figures carry tighter precision than emerging X-ray imaging penetration estimates. Forecasts reflect assumptions about SAMR regulatory timeline acceleration and automotive OEM captive center buildout velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.