
 Echelon Utilization of Power Battery Market | 2026-2036
Echelon Utilization of Power Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Echelon Utilization of Power Battery Market Insights
Automotive-grade cell certification is bifurcating the competitive landscape into suppliers capable of validating retired packs for secondary use versus commodity recyclers. CATL leverages its cell-to-pack architecture to sustain traceability across first and second life cycles. BYD Co. Ltd. anchors vertical integration from vehicle manufacturing through echelon deployment in grid storage. Panasonic Corporation differentiates through thermal management expertise that extends viable service intervals for reused modules.
Echelon utilization of power batteries denotes the cascading redeployment of cells with degraded yet functional capacity from automotive traction applications into stationary energy storage, requiring residual state-of-health above seventy percent and impedance stability within OEM-specified bands. The process encompasses cell grading, reconfiguration from series-parallel vehicle architectures to stationary rack systems, and integration with battery management systems recalibrated for lower C-rate operation. Lithium-ion chemistries dominate current echelon supply pools owing to their prevalence in electric vehicle production and superior cycle life relative to lead acid alternatives. Grid storage applications lead value capture for retired packs due to tolerant duty cycles that accommodate gradual capacity fade. Fast charging technology segments face structural constraints in echelon contexts where reduced current tolerance limits deployment flexibility.
China's SAMR enforces GB/T standards for battery grading that determine echelon eligibility based on residual capacity and safety test outcomes. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that shape market access for second-life products entering European utility procurement channels. The EPA oversees hazardous material classifications affecting interstate transport of retired lithium-ion assemblies in the United States. Stakeholders must monitor evolving certification requirements that increasingly link echelon qualification to original manufacturing traceability data rather than post-retirement testing alone.
Market Dynamics
Automotive OEMs are driving residual value recovery from retired electric vehicle packs into grid storage, creating a parallel supply chain that competes with virgin cell production for utility procurement contracts.
Growth Catalysts
- EU Battery Regulation carbon mandates:Recycled content thresholds and carbon footprint declarations are creating preferential procurement channels for second-life batteries in European utility-scale installations.
- Utility-scale storage procurement:German, Chinese, and US grid operators are specifying residual capacity thresholds above seventy percent in tender documents, directly pulling retired automotive packs into stationary applications.
- Cell-to-pack traceability architectures:Manufacturing data continuity from first through second life cycles is reducing recertification costs and accelerating deployment timelines for echelon suppliers.
Market Restraints
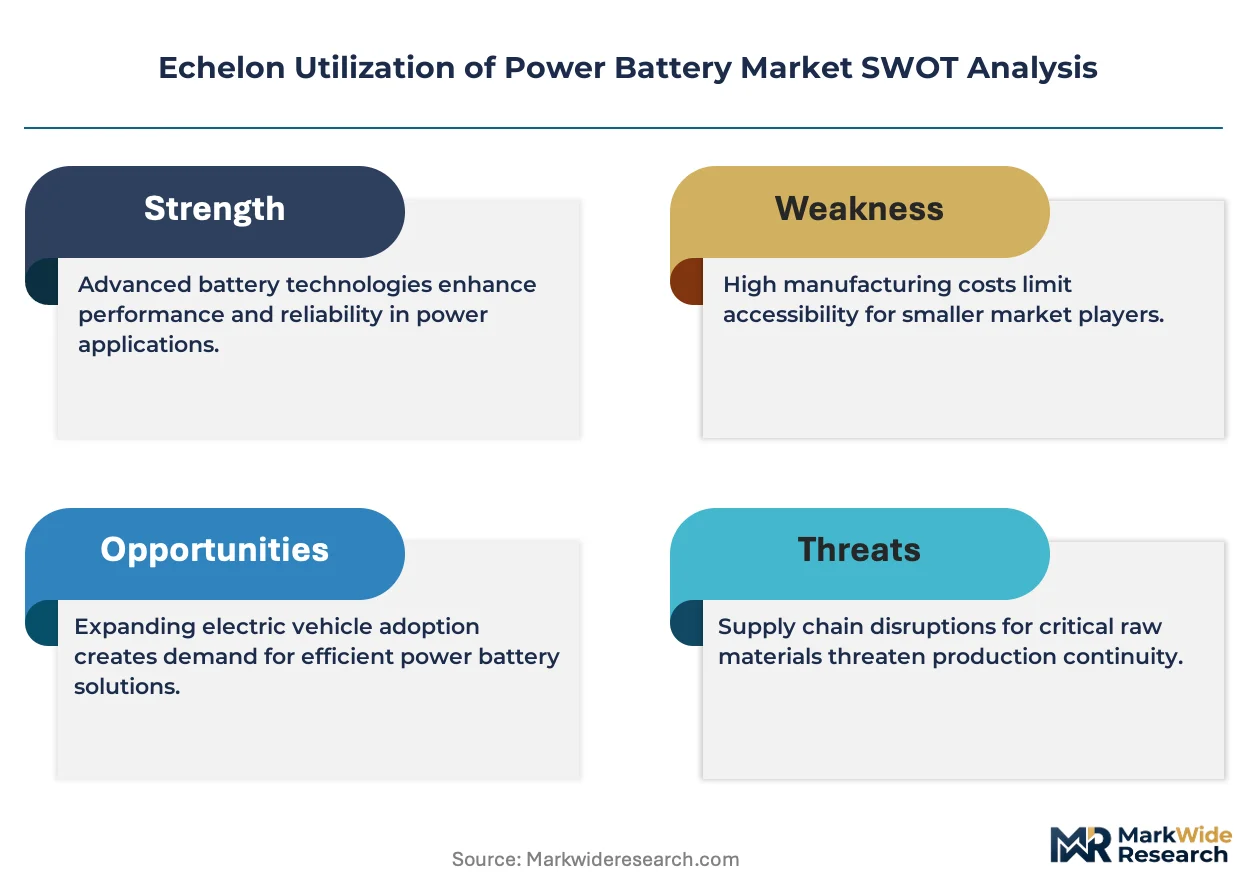
- Impedance instability in aged cells:Thermal runaway risks in modules with degraded electrolyte chemistry limit reconfiguration flexibility and require costly re-engineering of battery management systems.
- Transport classification barriers:EPA hazardous material designations for interstate movement of retired lithium-ion assemblies impose specialized packaging and documentation burdens that erode margin structures.
- Lead acid price floors:Mature recycling infrastructure for conventional batteries sustains price competition in residential storage segments where echelon lithium-ion cannot achieve cost parity.
Strategic Opportunities
- Commercial and industrial behind-the-meter storage:Manufacturing facilities in Texas and California are piloting containerized second-life systems for peak shaving applications with tolerant duty cycles.
- China's dual carbon policy framework:National emissions targets are accelerating SAMR enforcement of GB/T grading standards that favor domestic OEMs with integrated vehicle-to-grid value chains.
- Hybrid renewable pairing:Solar-plus-storage developers in Australia are specifying retired automotive packs for DC-coupled installations where reduced C-rate requirements match degraded cell capabilities.
Industry Challenges
- Battery management system recalibration:OEM-specific communication protocols and safety firmware require specialized engineering talent that concentrates among former automotive electronics suppliers.
- Residual state-of-health verification:Destructive testing requirements for safety certification consume sample cells from already limited echelon supply pools, raising effective procurement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Echelon Utilization of Power Battery Market |
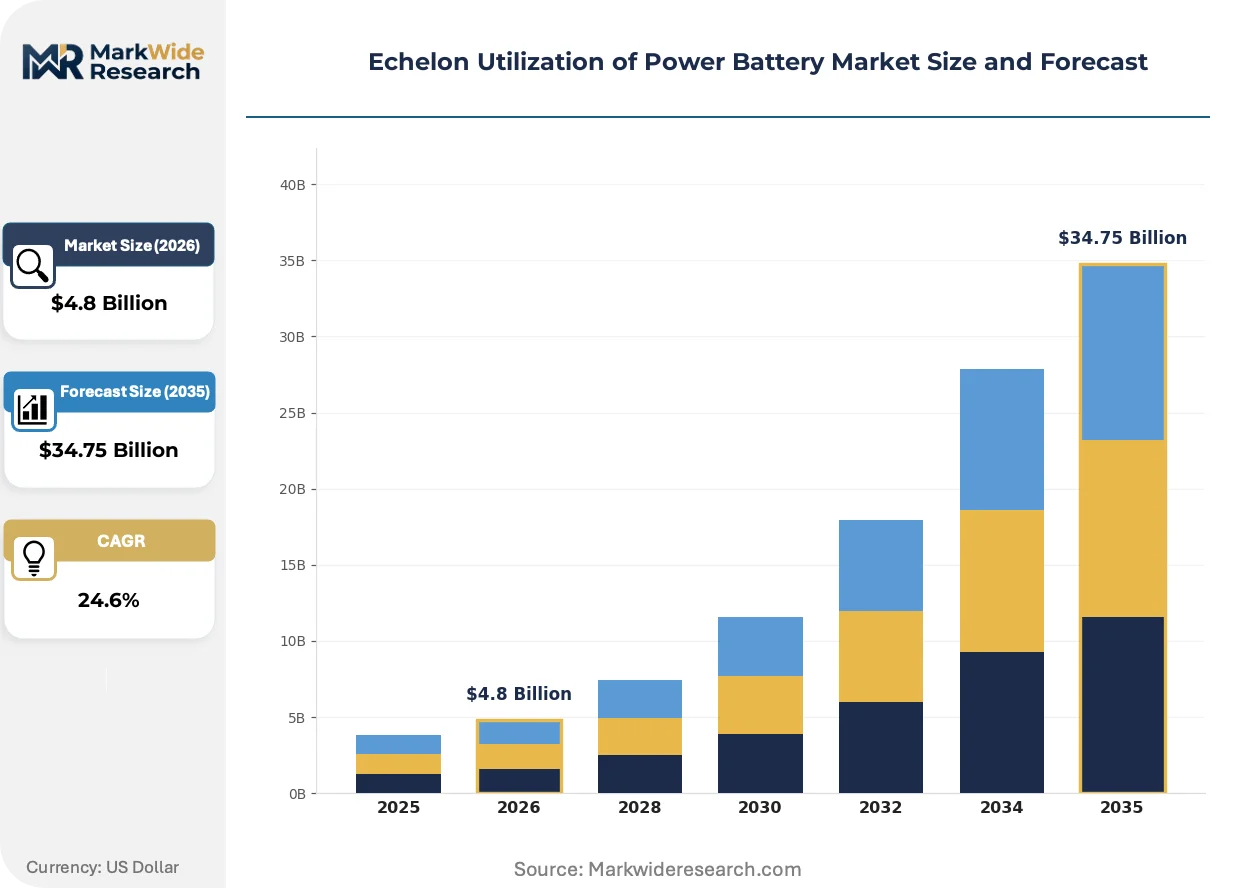
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead Acid, Nickel-Cadmium, Flow Batteries Application: Grid Storage, Electric Vehicles, Renewable Energy Integration, Backup Power End User: Utilities, Automotive, Industrial, Residential Technology: Energy Density, Fast Charging, Recycling, Thermal Management |
| Companies Covered | LG Chem, BYD Co. Ltd., Contemporary Amperex Technology Co. Limited (CATL), Panasonic Corporation, Samsung SDI, Envision AESC, GEM, 4R Energy, SungEel HiTech Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Echelon Utilization of Power Battery Market Trends and Innovations
Digital battery passports and blockchain traceability systems are redefining how residual value is authenticated and transferred across ownership chains in second-life applications.
Direct current fast charging infrastructure is displacing alternating current residential charging as the dominant end-of-life determinant for automotive packs, compressing first-life service intervals and expanding echelon supply pools. Fleet operators with high-utilization duty cycles are retiring cells earlier, creating larger volumes of moderately degraded modules suitable for stationary redeployment. This supply expansion is displacing virgin cell demand in price-sensitive grid storage tenders.
China's SAMR has finalized GB/T 34014-2023 grading protocols that mandate residual capacity testing and thermal abuse validation before echelon eligibility certification. The standard creates a two-tier market where traceable OEM packs command procurement premiums over aftermarket-sourced modules. European utilities are incorporating these testing benchmarks into supplier qualification frameworks despite lacking formal regulatory harmonization.
Utility procurement teams are unbundling engineering-procurement-construction contracts to separate battery supply from integration services, enabling direct sourcing of certified second-life modules. This disintermediation compresses margin capture for traditional system integrators while rewarding suppliers with validated grading capabilities. German transmission system operators have pioneered this model in grid-scale frequency regulation tenders.
Echelon Utilization of Power Battery Market Segmentation
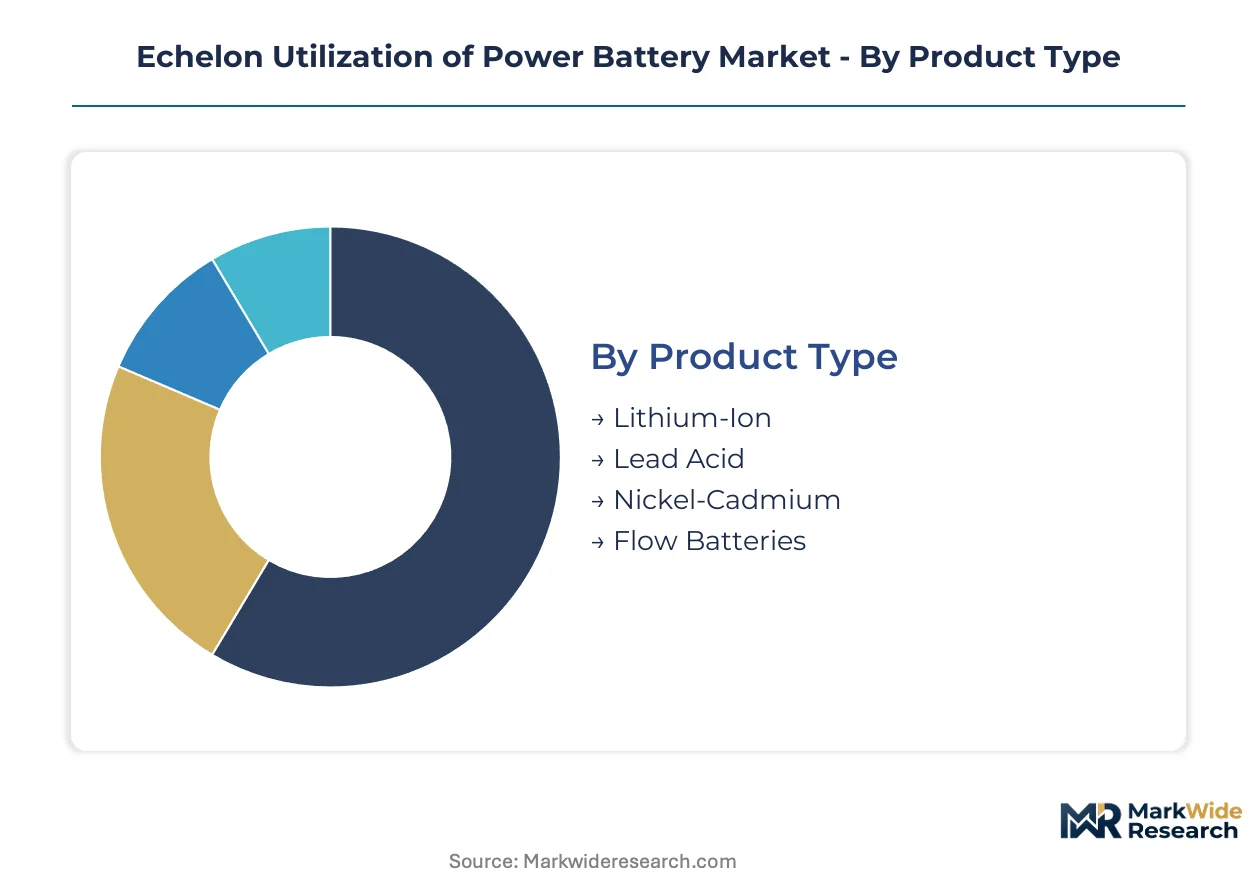
Echelon utilization pathways diverge sharply across cell chemistry and residual performance profiles, with regulatory certification requirements determining which degraded packs qualify for secondary deployment. Grading protocols from China's SAMR and the EU Battery Regulation create tiered eligibility that segments supply pools into traceable OEM-certified streams versus aftermarket commodity flows.
Product Type:
Regulatory differentiation favors chemistries with established traceability infrastructure and standardized degradation assessment protocols.
- Lithium-Ion:Dominant echelon feedstock due to superior cycle life and prevalence in automotive traction applications. Residual capacity thresholds above seventy percent qualify retired packs for grid storage redeployment in Germany, China, and the United States, with impedance stability testing mandated under GB/T protocols.
- Lead Acid:Mature recycling infrastructure sustains cost competition in residential storage segments where echelon lithium-ion cannot achieve price parity. Limited echelon viability due to shorter cycle life and absence of automotive-grade traceability systems required for utility procurement.
- Nickel-Cadmium:Niche industrial backup applications retain limited demand for echelon redeployment. Toxicity concerns and restricted transport classifications under EPA hazardous material designations constrain supply chain flexibility.
- Flow Batteries:Emerging chemistries with inherent decoupled power-energy scaling that reduces echelon relevance. Vanadium and zinc-bromine systems see pilot deployment in Chinese utility-scale projects with tolerant duty cycles.
Established volume favors Lithium-Ion; emerging adoption favors Flow Batteries.
Application:
Cost tier segmentation separates high-volume utility procurement from specialized industrial deployments with distinct duty cycle tolerances.
- Grid Storage:Utility-scale stationary installations across German transmission networks and Chinese provincial grids absorb the majority of echelon supply. Frequency regulation and peak shaving applications tolerate gradual capacity fade that would disqualify packs from automotive reuse.
- Electric Vehicles:Structural constraints limit direct echelon redeployment due to stringent power density and safety requirements. Retired packs cascade downward from this segment rather than entering it.
- Renewable Energy Integration:Solar-plus-storage developers in Australia specify retired automotive packs for DC-coupled installations where reduced C-rate requirements match degraded cell capabilities. Hybrid wind-storage configurations in Texas manufacturing facilities pilot containerized second-life systems.
- Backup Power:Residential and commercial uninterruptible power supply applications compete with lead acid on cost. SAMR grading standards and EU carbon footprint declarations create procurement barriers for uncertified modules.
Grid Storage captures the steepest expansion trajectory; Backup Power faces margin compression from incumbent chemistries.
End User:
Customer type determines certification burden and integration complexity, with utilities imposing the most stringent residual state-of-health verification requirements.
- Utilities:German transmission system operators pioneered unbundled engineering-procurement-construction contracts enabling direct sourcing of certified second-life modules. Tender documents specify residual capacity thresholds and thermal abuse validation per GB/T 34014-2023 benchmarks.
- Automotive:OEMs drive residual value recovery strategies that create parallel supply chains competing with virgin cell production. CATL and BYD anchor integrated vehicle-to-grid value chains with cell-to-pack traceability architectures.
- Industrial:Manufacturing facilities in California and Texas deploy behind-the-meter peak shaving systems with tolerant duty cycles. Containerized second-life configurations reduce capital expenditure versus virgin lithium-ion procurement.
- Residential:Price-sensitive demand competes against lead acid recycling infrastructure. Carbon footprint declarations under EU Battery Regulation create preferential channels for certified echelon products in European markets.
Utilities command premium certification standards; Industrial segments offer fastest deployment timelines for graded modules.
Technology:
Maturity gradients separate proven thermal management systems from emerging fast charging adaptations with limited echelon compatibility.
- Energy Density:First-life automotive specifications prioritize gravimetric and volumetric performance that degrades predictably into stationary applications. Residual energy density above OEM-specified floors determines grid storage eligibility.
- Fast Charging:Structural constraints in echelon contexts where reduced current tolerance limits deployment flexibility. High-utilization fleet duty cycles accelerate first-life retirement, expanding supply pools for stationary redeployment.
- Recycling:Hydrometallurgical and pyrometallurgical recovery pathways compete with direct echelon redeployment for degraded pack volumes. EU recycled content thresholds shape whether modules enter second-life or materials recovery streams.
- Thermal Management:Panasonic Corporation differentiates through expertise extending viable service intervals for reused modules. Active and passive cooling system recalibration represents critical battery management system adaptation for lower C-rate echelon operation.
Thermal Management underwrites service interval extension; Fast Charging faces inherent constraints in degraded cell contexts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in Germany tolerate premium pricing for certified second-life modules, while industrial offtakers in Texas prioritize capital expenditure minimization above traceability documentation.
China
Provincial grid operators in Jiangsu and Guangdong absorb the majority of domestic echelon supply for frequency regulation services. SAMR enforces GB/T 34014-2023 grading protocols that mandate residual capacity testing before certification eligibility. The Yangtze River Delta hosts integrated vehicle-to-grid clusters where CATL and BYD anchor captive second-life value chains from manufacturing through stationary deployment.
Germany
Transmission system operators pioneered unbundled engineering-procurement-construction contracts enabling direct sourcing of retired automotive packs. The EU Battery Regulation's carbon footprint declarations and recycled content thresholds shape procurement specifications for utility-scale tenders. Industrial facilities in Bavaria deploy behind-the-meter peak shaving systems with containerized second-life configurations.
United States
ERCOT grid operators in Texas specify residual capacity thresholds above seventy percent in frequency regulation procurement documents. EPA hazardous material classifications impose specialized packaging burdens for interstate transport of retired lithium-ion assemblies. Manufacturing clusters in California pilot solar-plus-storage installations pairing degraded automotive cells with DC-coupled photovoltaic arrays.
Japan
Automotive OEMs drive residual value recovery strategies through METI-supported vehicle-to-grid demonstration projects. JIS standards for battery safety testing create certification pathways for echelon eligibility distinct from Chinese GB/T protocols. The Kanto region around Tokyo concentrates grid storage deployments utilizing retired packs from high-utilization fleet duty cycles.
Australia
Solar-plus-storage developers specify retired automotive packs for utility-scale installations where reduced C-rate requirements match degraded cell capabilities. The country's national energy regulator oversees grid connection standards that accommodate second-life battery integration with modified safety margins. Queensland and New South Wales host hybrid renewable pairing projects that displace virgin cell demand in price-sensitive tenders.
Echelon Utilization of Power Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated cell manufacturers commanding traceability premiums while specialized graders compete on processing throughput. The market structure concentrates around three strategic tiers: automotive OEMs with captive supply chains, independent battery management system recalibration specialists, and commodity recyclers pivoting toward echelon qualification. Consolidation pressure intensifies as utility procurement teams disintermediate traditional system integrators. Dominant competitive moves include backward integration into vehicle retirement streams and technology licensing agreements for proprietary grading protocols.
Among Asian integrated manufacturers, BYD Co. Ltd. and Contemporary Amperex Technology Co. Limited occupy positions exemplifying cell-to-pack traceability architectures that sustain data continuity across first and second life cycles. Panasonic Corporation represents the thermal management specialization archetype, with expertise extending viable service intervals for reused modules. These three anchors illustrate how manufacturing origin and technical focus differentiate competitive positioning in procurement channels where residual state-of-health verification determines market access.
| Leading Market Players |
|---|
| LG Chem |
| BYD Co. Ltd. |
| Contemporary Amperex Technology Co. Limited (CATL) |
| Panasonic Corporation |
| Samsung SDI |
| Envision AESC |
| GEM |
| 4R Energy |
| SungEel HiTech Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Cell-to-pack traceability architectures in the Yangtze River Delta generate scale economies that compress grading costs for certified modules while sustaining price premiums over aftermarket-sourced alternatives. GB/T 34014-2023 compliance burdens concentrate processing capacity among integrated OEMs, creating bifurcated supply pools where traceable automotive packs command procurement premiums in German and Chinese utility tenders.
Pricing Analysis
EU Battery Regulation carbon footprint declarations dictate the pricing tier structure across European utility procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified modules with full traceability from aftermarket-graded cells and commodity recyclate streams. Price differentiation rests on GB/T grading compliance and residual capacity verification above seventy percent thresholds. Cost compression in standard-tier supply is intensifying because destructive safety testing consumes sample cells from limited echelon pools. Residential backup power segments exhibit highest price sensitivity, while German transmission system operators tolerate premium pricing for certified modules with validated thermal abuse documentation.
Supply Chain Analysis
Inventory lead times for retired automotive packs stretch twelve to eighteen months from vehicle retirement through grading certification and stationary redeployment. Geographic supply concentration centers on China, Germany, and the United States, with Jiangsu and Guangdong provincial grids absorbing majority domestic Chinese volume. Raw material dependencies draw from lithium carbonate feedstocks, electrolyte chemistry stability, and thermal management component availability. Single-source vulnerability concentrates in OEM-specific battery management system firmware and communication protocols. Distribution runs through unbundled engineering-procurement-construction contracts that disintermediate traditional system integrators and enable direct utility sourcing of certified modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility procurement consolidation into direct sourcing models has shifted buyer power toward transmission system operators, fragmenting margin capture for traditional battery integrators and rewarding suppliers with validated grading capabilities.
For Market Incumbents: Shield core revenue streams by securing captive retirement agreements with high-utilization fleet operators, ensuring priority feedstock access before cells enter aftermarket channels. Invest in backward integration into vehicle end-of-life streams to control grading cost structures. Prioritize SAMR certification investment to defend position against emerging commodity recyclers pivoting toward echelon qualification. For New Entrants and Emerging Players: Lead with specialized battery management system recalibration services targeting the commercial and industrial behind-the-meter segment in Texas and California manufacturing clusters. Containerized peak shaving configurations offer fastest deployment timelines with tolerant duty cycles that accommodate moderately degraded modules. Partner with solar-plus-storage developers in Australia for DC-coupled installations where reduced C-rate requirements match degraded cell capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent grading specialists with proprietary thermal abuse validation protocols and utility qualification frameworks. Long-term viability over a five-to-ten year horizon rests on regulatory harmonization between Chinese GB/T standards and EU Battery Regulation requirements. Target acquisition archetypes include former automotive electronics suppliers with OEM-specific firmware expertise. Watch for inflection in utility procurement unbundling rates as signal of margin compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fleet Retirement Streams | CATL and BYD secure captive feedstock access before aftermarket competition. |
| GB/T 34014-2023 Certification Investment | SAMR compliance creates procurement barriers for uncertified commodity recyclers. |
| Direct Utility Sourcing Partnerships | German transmission operators pioneer unbundled contracts disintermediating integrators. |
| Thermal Management System Licensing | Panasonic extends service intervals for reused modules through proprietary cooling recalibration. |
| Blockchain Traceability Platform Deployment | Digital battery passports authenticate residual value across ownership chains in second-life applications. |
Research Methodology
The analysis maps echelon utilization pathways across lithium-ion, lead acid, nickel-cadmium, and flow battery chemistries, each validated through utility procurement officers, automotive OEM sustainability directors, battery management system engineers, and grid-scale EPC contractors. Primary interviews with these stakeholders combined with secondary validation from SAMR regulatory filings, EU Battery Regulation implementation guidance, EPA hazardous material classifications, and FERC grid interconnection standards. Bottom-up cell grading capacity estimates triangulated against top-down utility storage procurement pipelines.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include cell chemistry, application type, end user category, and residual state-of-health tier. CAGRs derived from utility-scale storage deployment trajectories, automotive EV retirement curves, and regulatory compliance timeline assumptions. Key forecast inputs encompass GB/T grading protocol adoption rates and carbon footprint declaration penetration in European procurement channels.
Underlying assumptions cover residual capacity threshold stability, SAMR enforcement consistency, and utility direct-sourcing model persistence, with deviation risk concentrated in impedance instability detection accuracy and interstate transport classification changes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
Home Inverter Battery Market
Batteries
Battery Plate Market
Batteries
Battery Swapping Market
Batteries
Power Tool Batteries Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Proton Battery Market
Batteries
Sweden Rechargeable Battery Market
Batteries
South America Rechargeable Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Europe Battery Market