
 Spain Rechargeable Battery Market | 2026-2036
Spain Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Rechargeable Battery Market Insights
Solid-state electrolyte research is narrowing the performance gap between laboratory prototypes and production-ready cells for automotive applications. Iberdrola leverages its utility-scale project pipeline to anchor long-term offtake agreements for grid storage systems. Basquevolt competes through dedicated R&D on lithium-metal anodes designed for regional EV platforms. Endurance Motive specializes in battery pack integration for industrial forklifts and warehouse automation equipment.
Spain rechargeable batteries are electrochemical energy storage devices designed for repeated charge-discharge cycling, typically employing lithium-ion chemistries with nickel-manganese-cobalt or lithium-iron-phosphate cathodes and graphite or silicon-blend anodes, achieving energy densities of 150-300 Wh/kg for applications requiring sustained power delivery over hundreds to thousands of cycles. Their primary industrial purpose centers on decarbonizing mobility and grid infrastructure by replacing fossil fuel dependence with stored renewable electricity. Lithium-ion chemistry dominates product type dynamics due to its superior energy density and declining cost curve, while lead-acid retains position in stationary backup power where capital constraints override performance requirements. Automotive application segments absorb the largest share of cell output as Spanish OEMs electrify production lines, yet renewable energy storage represents the fastest-expanding margin pool driven by solar and wind intermittency management needs.
Spain's Ministry for the Ecological Transition enforces battery sustainability regulations aligned with EU Battery Directive requirements, mandating recycled content thresholds and carbon footprint declarations that reshape supplier qualification criteria. The Spanish Agency for Food Safety and Nutrition and the Spanish Institute for Energy Diversification and Saving coordinate standards affecting industrial battery deployment in food processing and energy-intensive manufacturing facilities. Stakeholders must monitor how EU Critical Raw Materials Act sourcing rules interact with Spain's domestic lithium exploration permits in Extremadura and Castilla y León.
Market Dynamics
Spain's National Integrated Energy and Climate Plan mandates storage deployment alongside renewable generation capacity, creating binding procurement obligations for grid operators and project developers.
Growth Catalysts
- EU Battery Directive compliance:Spain's Ministry for the Ecological Transition enforces recycled content thresholds and carbon footprint declarations that reshape supplier qualification criteria across automotive and stationary applications.
- Basque Country manufacturing clusters:Cell production facilities and automotive supplier networks overlap in this region, concentrating technical talent and reducing logistics costs for pack assembly.
- Lithium-ion chemistry maturation:Nickel-manganese-cobalt and lithium-iron-phosphate cathodes achieve energy densities of 150-300 Wh/kg, enabling sustained power delivery over thousands of cycles for mobility and grid applications.
Market Restraints
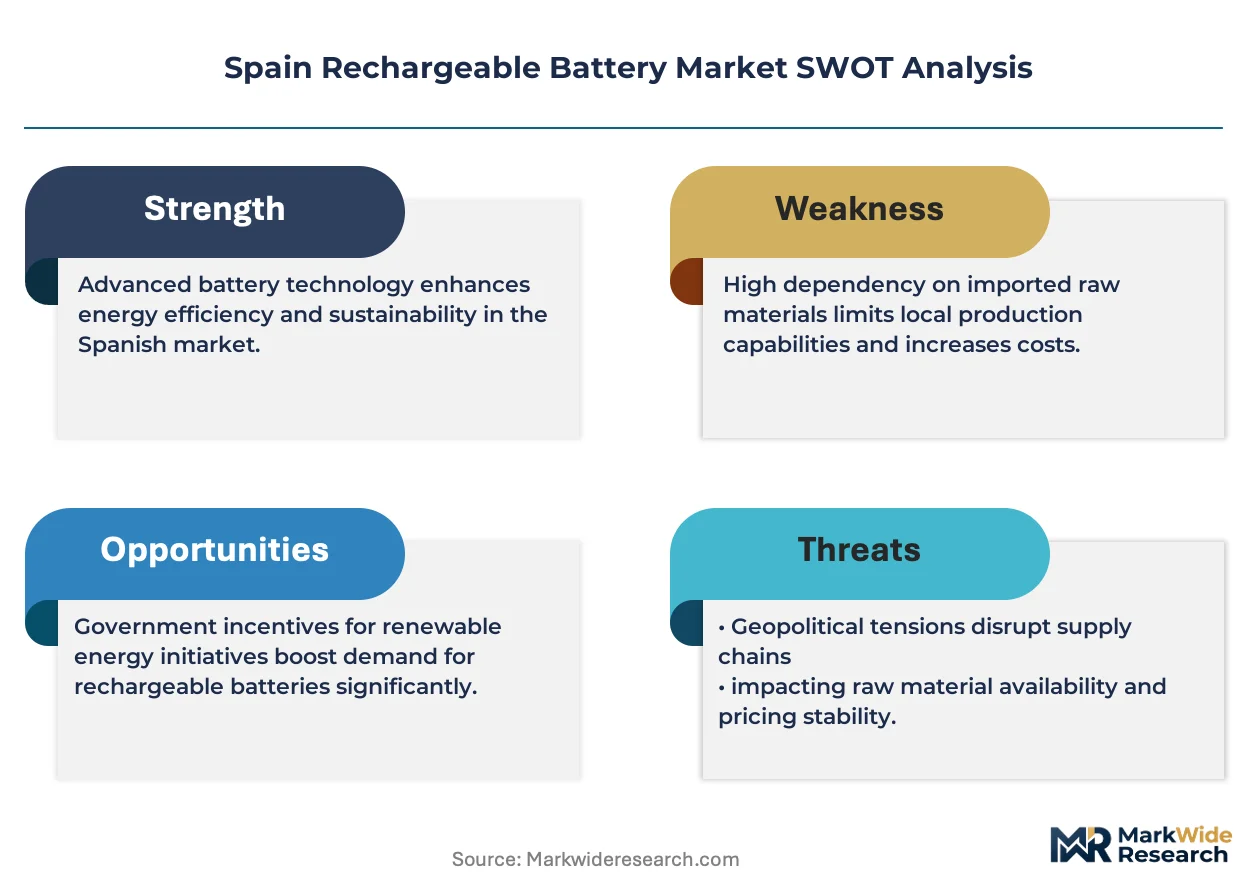
- Raw material supply concentration:Cathode precursor processing concentrates in Asian supply chains, exposing Spanish cell assemblers to input cost volatility and logistics disruption.
- EU Critical Raw Materials Act sourcing rules:Domestic lithium exploration permits in Extremadura and Castilla y León face extended environmental review timelines, delaying captive supply development.
- Lead-acid substitution resistance:Capital-constrained stationary backup applications retain incumbent chemistry where performance requirements are secondary to upfront cost minimization.
Strategic Opportunities
- Industrial forklift electrification:Warehouse automation equipment and material handling fleets present underpenetrated demand for lithium-ion pack integration beyond automotive volumes.
- Grid storage offtake anchoring:Utility-scale project pipelines create long-term contract structures that reduce financing costs and de-risk manufacturing capacity investments.
- Solid-state electrolyte convergence:Laboratory prototypes advancing toward production-ready cells for automotive platforms promise energy density step-changes and thermal stability improvements.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and pack thermal management expertise concentrates in established automotive suppliers, constraining new entrant scale-up velocity.
- Certification timeline compression:UN 38.3 transport testing and IEC 62619 industrial safety validation create multi-month approval gates that mismatch fast-moving project procurement cycles.
- Legacy system integration friction:Grid-connected storage must synchronize with existing inverter architectures and distribution network protection schemes, adding engineering complexity to deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Rechargeable Battery Market |
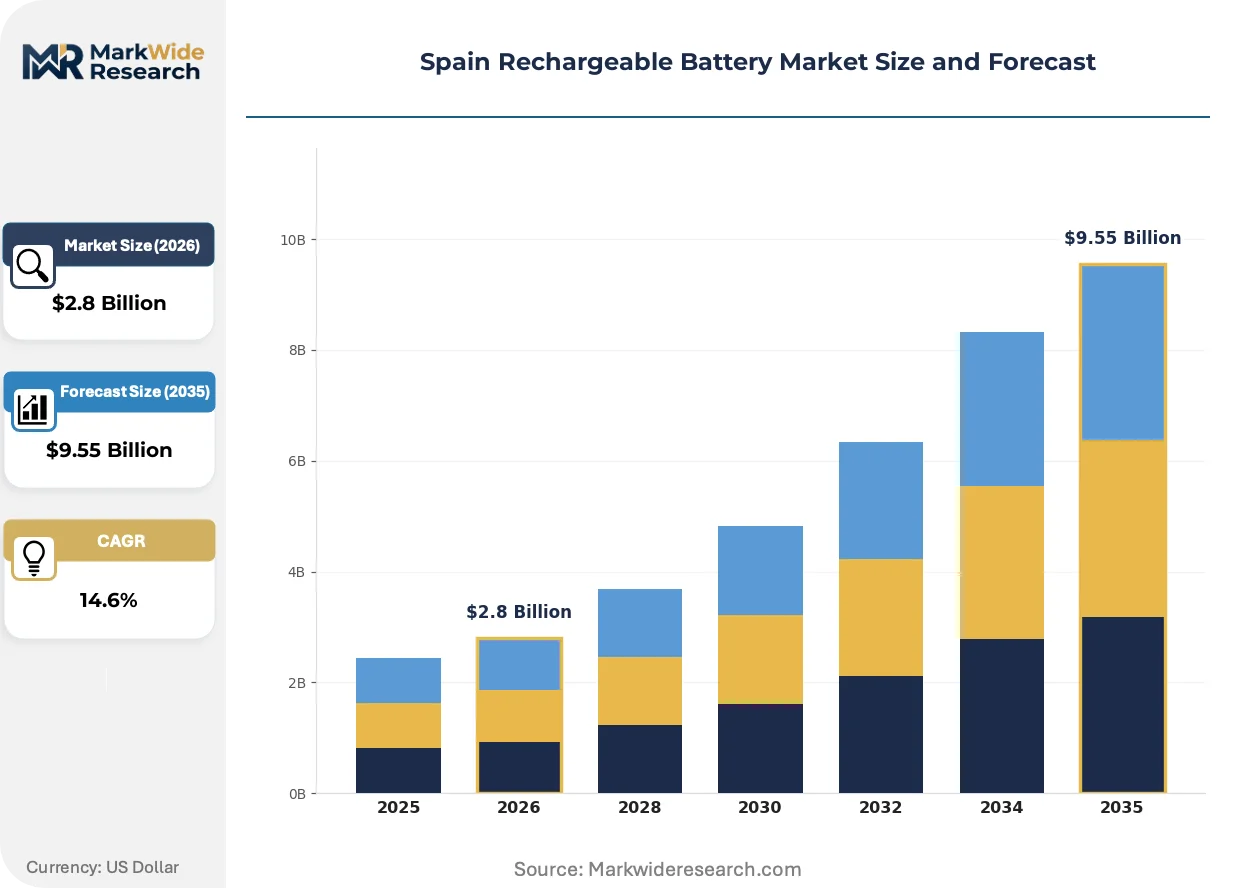
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Cadmium, Nickel-Metal Hydride, Lead-Acid Application: Consumer Electronics, Automotive, Industrial Equipment, Renewable Energy Storage Technology: Charging Technology, Energy Density, Cycle Life, Temperature Tolerance End User: Households, Businesses, Manufacturers, Government Agencies |
| Companies Covered | Iberdrola, Grenergy Renovables, Matrix Renewables, Tesla, Panasonic Corporation, LG Chem, BYD, Endurance Motive, Basquevolt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Rechargeable Battery Market Trends and Innovations
Solid-state research programs and procurement model evolution are compressing development cycles and reshaping how battery systems reach end-users across Spanish mobility and grid applications.
Lithium-metal anode technology is hybridizing with conventional cell architectures as Basquevolt and regional research consortia prototype designs for electric vehicle platforms. Automotive OEMs in Spain evaluate these configurations for next-generation pack integration. The structural consequence is a narrowing performance gap between laboratory demonstrations and production-ready cells, compressing the timeline for energy density breakthroughs.
Spain's alignment with EU Battery Directive requirements mandates recycled content thresholds and carbon footprint declarations that reshape supplier qualification criteria. Industrial buyers now require documentation traceability from cathode precursor through pack assembly. Grid storage and automotive segments face the most stringent compliance burdens, driving qualification investments among cell suppliers seeking long-term offtake agreements.
Logistics providers and ride-sharing platforms are consolidating fleet procurement into multi-year supply agreements with cell manufacturers. Direct contracting displaces spot-market purchasing for electric vehicle fleets, concentrating buyer power among platform operators. This pattern is most visible in urban mobility deployments across Madrid and Barcelona, where fleet electrification targets compress procurement decision timelines.
Spain Rechargeable Battery Market Segmentation
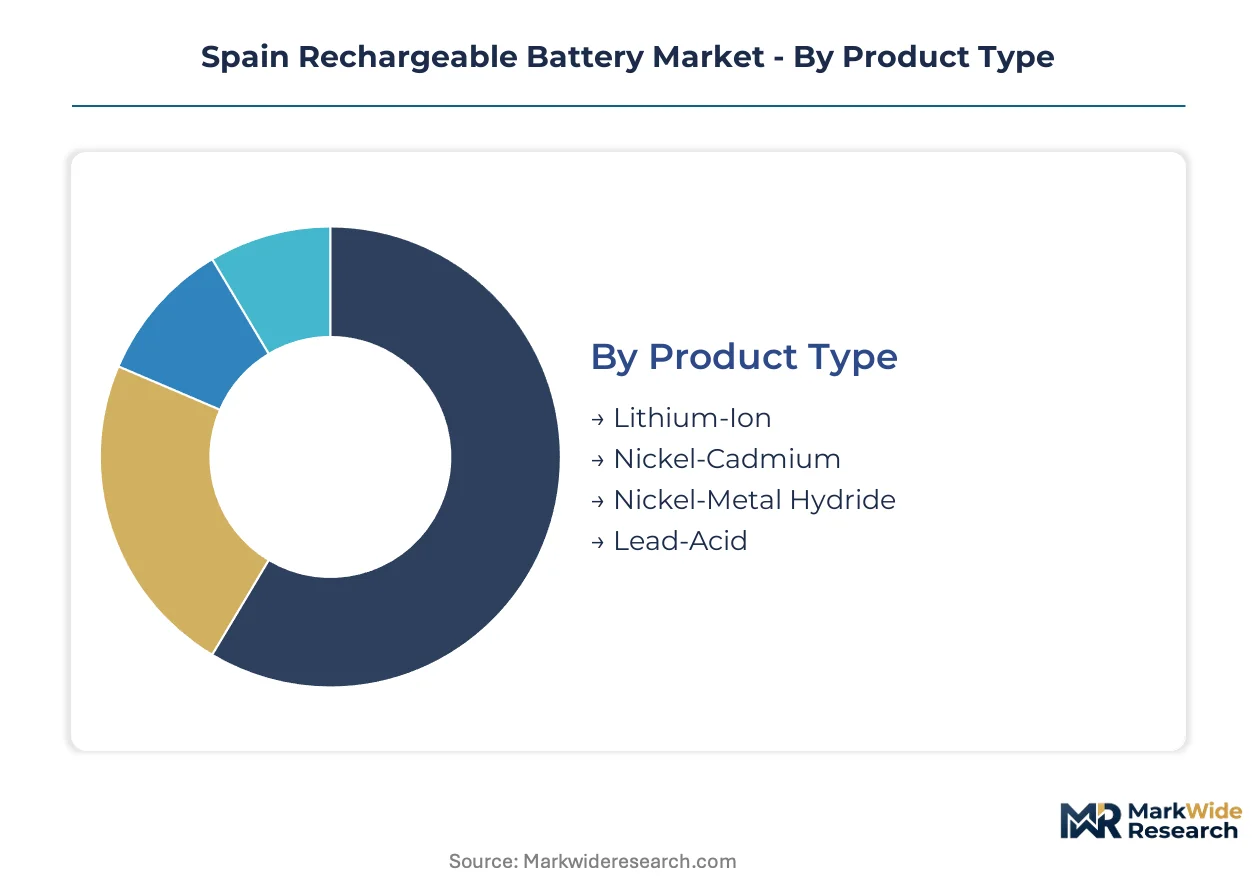
Segmentation reveals how chemistry choices, application requirements, and procurement authority distribute value across Spain's rechargeable battery landscape. Understanding these divides exposes where margin concentrates and where new entrants face structural barriers.
Product Type:
Cost tier differentiation separates chemistries by energy density, cycle durability, and upfront capital requirements.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathodes deliver 150-300 Wh/kg energy density. Automotive OEMs in the Basque Country and grid storage developers under Spain's National Integrated Energy and Climate Plan anchor procurement volumes for this chemistry.
- Lead-Acid:Mature flooded and valve-regulated designs dominate stationary backup power where capital constraints override performance specifications. Industrial facilities in Extremadura and Castilla y León retain incumbent installations for non-critical backup duty cycles.
- Nickel-Cadmium:Rugged construction tolerates extreme temperature swings for railway signaling and emergency lighting applications.
- Nickel-Metal Hydride:Moderate energy density serves hybrid electric vehicle auxiliary systems and consumer appliance niches.
Lithium-Ion holds installed capacity. Lead-Acid is rotating up the share rankings in price-sensitive stationary segments.
Application:
Application scope determines pack integration complexity, certification burden, and contract duration with end-users.
- Automotive:Full electric and plug-in hybrid platforms require thermal management systems, battery management electronics, and UN 38.3 transport certification. Spanish OEM electrification roadmaps and logistics fleet procurement by ride-sharing platforms concentrate demand in this segment.
- Renewable Energy Storage:Utility-scale lithium-ion installations synchronize with solar and wind generation to manage intermittency. Iberdrola's project pipeline and grid operator procurement obligations under Spain's National Integrated Energy and Climate Plan drive deployment velocity.
- Consumer Electronics:Cylindrical and prismatic cells power smartphones, laptops, and portable tools with standardized form factors.
- Industrial Equipment:Forklift electrification and warehouse automation systems present underpenetrated lithium-ion substitution opportunities against incumbent lead-acid fleets.
Automotive commands manufacturing scale. Renewable Energy Storage is climbing the fastest as grid modernization accelerates.
Technology:
Technical performance vectors separate premium pack suppliers from commodity assemblers in qualification-driven procurement.
- Energy Density:Gravimetric and volumetric metrics determine vehicle range and pack footprint. Solid-state electrolyte research programs at Basquevolt and regional consortia target step-change improvements for next-generation automotive platforms.
- Cycle Life:Calendar and cycle durability specifications govern warranty economics and total cost of ownership calculations for grid storage investors.
- Charging Technology:Fast-charge protocols and thermal management integration differentiate premium automotive pack designs.
- Temperature Tolerance:Operating range specifications constrain chemistry selection for industrial deployments in unconditioned environments.
Energy Density holds technical priority. Cycle Life is gaining share fastest as warranty terms extend in utility contracting.
End User:
Customer type dictates procurement sophistication, contract structure, and compliance documentation requirements.
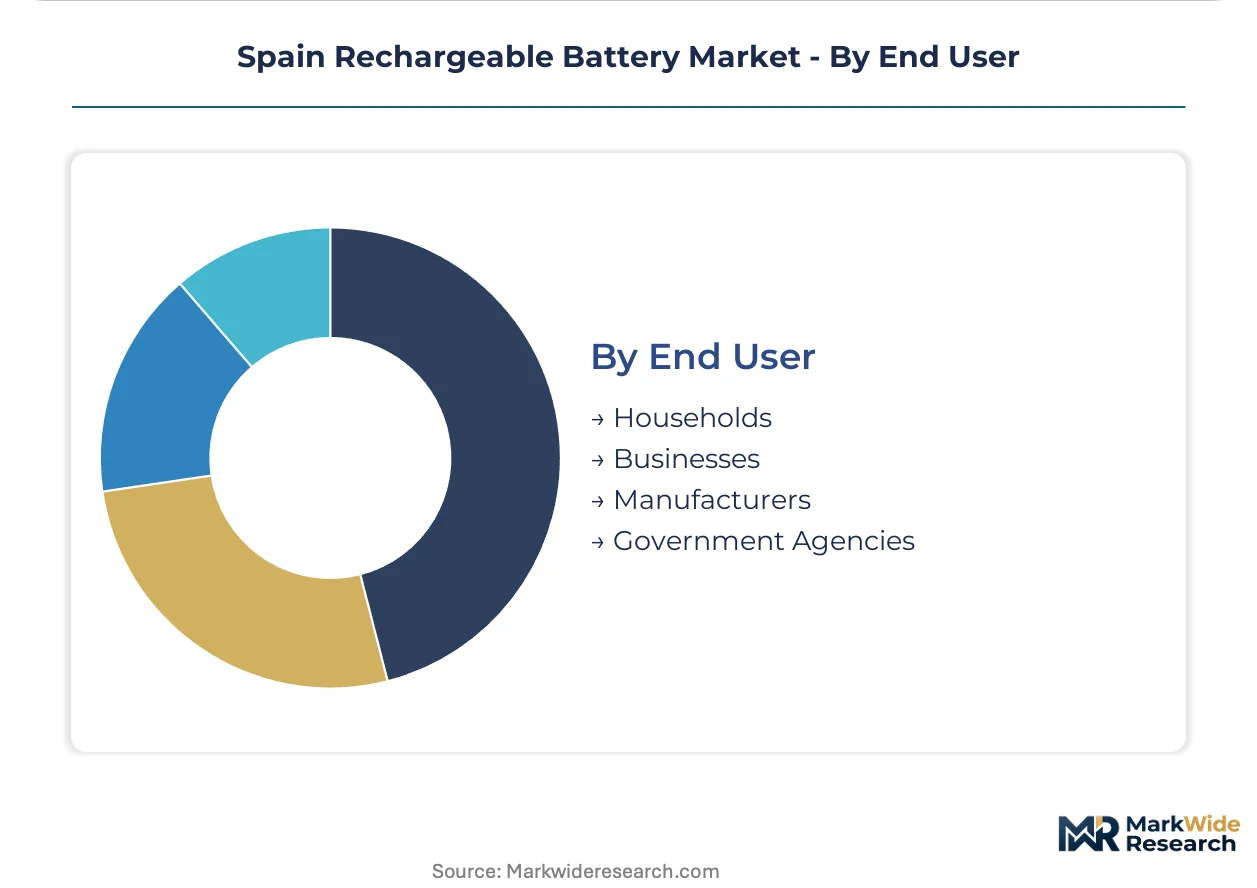
- Manufacturers:Automotive OEMs and industrial equipment builders negotiate multi-year offtake agreements with recycled content and carbon footprint traceability mandated by Spain's Ministry for the Ecological Transition alignment with EU Battery Directive requirements.
- Government Agencies:Public transit electrification and defense procurement specify domestic content thresholds and extended technical validation protocols.
- Businesses:Commercial and industrial facility operators evaluate total cost of ownership for forklift fleets and backup power systems.
- Households:Residential solar-plus-storage adopters respond to net metering policies and regional incentive structures.
Manufacturers concentrate contract value. Government Agencies are rotating up the share rankings as public fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cell exports supply Spanish pack assemblers through Rotterdam-Antwerp logistics corridors, while Basque Country manufacturing clusters absorb French cathode precursor shipments via Bay of Biscay ports. This trade geometry positions Spain as a downstream integration node within European battery value chains.
Madrid
Logistics fleet electrification by ride-sharing platforms concentrates procurement decisions in the capital region. Spain's Ministry for the Ecological Transition enforces EU Battery Directive recycled content thresholds that reshape supplier qualification for urban mobility operators. The Madrid metropolitan area hosts headquarters coordination for national grid storage offtake negotiations.
Catalonia
Industrial forklift electrification demand from warehouse automation clusters in Barcelona's logistics corridor drives lithium-ion pack integration. The Spanish Institute for Energy Diversification and Saving coordinates standards affecting battery deployment in energy-intensive manufacturing facilities. Automotive supplier networks in the region overlap with chemical processing infrastructure for electrolyte formulation.
Basque Country
Cell manufacturing facilities and automotive OEM electrification roadmaps concentrate technical talent and reduce logistics costs for pack assembly. Spain's National Integrated Energy and Climate Plan mandates storage deployment obligations that anchor procurement for grid-connected installations. Bilbao and Vitoria-Gasteiz host overlapping R&D consortia on solid-state electrolyte research programs.
Andalusia
Solar-plus-storage project development for utility-scale intermittency management attracts grid operator procurement under renewable generation mandates. The country's national energy regulator oversees distribution network protection scheme synchronization requirements for battery installations. Seville and Málaga concentrate engineering services for inverter architecture integration.
Valencia
Port infrastructure handles cathode active material imports from Asian supply chains for redistribution to interior cell plants. Extended environmental review timelines for domestic lithium exploration permits delay captive supply development in neighboring regions. The metropolitan area functions as a customs and warehousing node for precursor chemical flows.
Spain Rechargeable Battery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers in Spain's rechargeable battery market. Utility-scale developers and automotive OEMs anchor long-term offtake agreements that concentrate buyer power, while industrial equipment integrators and residential solar installers fragment demand across smaller contract values. Three strategic archetypes dominate: vertically integrated energy companies leveraging project pipelines, dedicated cell technology developers pursuing chemistry breakthroughs, and industrial pack integrators serving niche equipment categories. Competitive moves center on strategic partnerships for raw material security and capacity expansion announcements timed to public procurement cycles.
Among utility-scale developers, Iberdrola exemplifies the channel-controlling archetype through project pipeline anchoring. Basquevolt occupies a position within the dedicated cell technology tier, representing lithium-metal anode research concentration in the Basque Country. Endurance Motive sits within the industrial pack integration segment, exemplifying specialization for warehouse automation equipment. These three company types illustrate how competitive positioning distributes across procurement authority levels rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Iberdrola |
| Grenergy Renovables |
| Matrix Renewables |
| Tesla |
| Panasonic Corporation |
| LG Chem |
| BYD |
| Endurance Motive |
| Basquevolt |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Asian cathode precursor processing exposes Spanish pack assemblers to input cost volatility that compresses tier spreads between premium automotive cells and economy stationary systems while simultaneously reshaping logistics networks toward Rotterdam-Antwerp corridor consolidation.
Pricing Analysis
Next-generation solid-state electrolyte prototypes command substantial premiums over incumbent lithium-ion configurations, while prior-generation lead-acid systems face accelerated price erosion in warehouse automation substitution. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with UN 38.3 transport-validated automotive packs extracting maximum value. Cost compression in economy stationary tiers intensifies because lead-acid incumbents defend share through upfront capital minimization. Logistics fleet operators demonstrate lowest price sensitivity due to total cost of ownership framing, while residential solar-plus-storage adopters exhibit highest elasticity to net metering policy adjustments.
Supply Chain Analysis
Upstream feedstock concentration in Chile, Australia, and China for lithium carbonate and spodumene concentrates anchors Spanish cell assemblers to seaborne bulk cargo schedules and Rotterdam port discharge bottlenecks. Cathode active materials—nickel-manganese-cobalt precursors and lithium-iron-phosphate powders—draw from South Korean and Japanese chemical processing facilities with limited European redundancy. Single-source vulnerability in high-purity electrolyte salt production creates qualification timeline risk for new supplier onboarding. Distribution runs through Valencia customs warehousing nodes for precursor redistribution to Basque Country cell plants and Madrid pack integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among utility-scale developers and national logistics platforms, fragmenting procurement authority away from distributed industrial operators and compressing contract negotiation leverage for mid-tier pack assemblers.
For Market Incumbents: Build captive supply moats through backward integration into domestic lithium exploration permits in Extremadura and Castilla y León, securing feedstock autonomy against EU Critical Raw Materials Act sourcing enforcement. Anchor long-term offtake agreements with Iberdrola's grid storage pipeline to lock in manufacturing capacity utilization. Invest in solid-state electrolyte R&D consortium participation to preempt technology substitution threats from Basquevolt lithium-metal configurations. For New Entrants and Emerging Players: Mid-market industrial forklift electrification in Catalonia's Barcelona logistics corridor represents the most penetrable entry point, with lead-acid fleet replacement cycles accelerating under warehouse automation CAPEX expansion. Basque Country automotive supplier networks offer partnership pathways for pack integration subcontracts without cell manufacturing scale requirements. Target government agency procurement through domestic content threshold compliance and extended technical validation protocol navigation. For Investors and Strategic Acquirers: Dedicated cell technology developers with lithium-metal anode specialization and regional OEM qualification relationships present the highest strategic value capture potential within a five-to-ten year technology transition window. Monitor solid-state electrolyte prototype-to-production timeline compression as the critical inflection indicator for chemistry disruption velocity. Cross-checking against EU Battery Directive recycled content threshold enforcement schedules is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Iberdrola's project pipeline anchoring reduces financing costs for grid storage manufacturing capacity. |
| Backward Integration | Domestic lithium exploration permits in Extremadura mitigate EU Critical Raw Materials Act sourcing exposure. |
| Technology Licensing | Solid-state electrolyte research programs at Basquevolt narrow laboratory-to-production performance gaps. |
| Joint Venture | Basque Country R&D consortia concentrate electrochemical engineering talent for automotive platform integration. |
| Green Certification Program | EU Battery Directive carbon footprint declarations reshape supplier qualification criteria across procurement tiers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and project development databases through structured interviews with utility planning officers, automotive OEM procurement leads, grid operators, and industrial equipment maintenance directors. Spain's Ministry for the Ecological Transition enforcement documentation and Iberdrola capacity announcement disclosures provided secondary validation anchors. Bottom-up cell production capacity modeling triangulated against top-down renewable energy storage deployment obligations under the National Integrated Energy and Climate Plan.
Forecast inputs span lithium-ion chemistry maturation curves, lead-acid substitution elasticity in material handling equipment, and grid storage procurement velocity tied to solar-plus-storage project development timelines. Segmentation dimensions include product type chemistry tiers, automotive versus stationary application splits, and end-user procurement sophistication levels. CAGRs derive from installed capacity build-out trajectories and manufacturing capacity announcement pipelines across the projection horizon. Solid-state electrolyte research commercialization timelines and EU Battery Directive compliance cost pass-through assumptions inform scenario boundaries.
Practitioners should monitor domestic lithium exploration permit approval velocity, cathode precursor processing capacity expansion in European chemical hubs, and logistics fleet electrification procurement consolidation for early signals of supply constraint or demand acceleration. Forecasts embed assumptions regarding EU Critical Raw Materials Act enforcement intensity and UN 38.3 transport testing timeline standardization. Cross-checking against IEA grid storage deployment tracking and European Battery Alliance capacity databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Curved Lipo Battery Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
EV Batteries Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market